
 Food Testing Kits Market | 2026-2036
Food Testing Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Food Testing Kits Market Intelligence
The capability gap between high-throughput automated systems and low-cost rapid assays is rotating competitive dynamics in the food testing sector. Large, diversified companies like Thermo Fisher Scientific Inc. leverage extensive R&D to lead in high-sensitivity PCR and chromatography technologies. In contrast, specialists such as Charm Sciences, Inc. focus on rapid, on-site tests for specific contaminants. Meanwhile, bioMérieux SA sustains its market position through deep expertise in microbiological and pathogen detection solutions.
Food testing kits are pre-packaged analytical tools designed to detect specific targets like pathogens, allergens, chemical residues, or genetic markers in food and beverage samples. These kits often utilize immunoassays with specific antibodies or molecular techniques involving DNA primers for high-specificity detection. Their primary purpose is to enable rapid, reliable, and often on-site quality control and safety verification for food producers and regulators. While Contaminant Detection and Foodborne Pathogen Surveillance constitute the largest applications, the demand for Allergen Detection Kits is accelerating due to stricter labeling mandates.
Regulatory frameworks are the primary determinant of testing frequency and methodology. The US FDA's Food Safety Modernization Act (FSMA) and the European Union's EFSA regulations impose strict limits on contaminants and pathogens, compelling producers to implement routine testing. Similarly, standards from China's SAMR and Japan's Ministry of Health, Labour and Welfare shape market access and product requirements. The critical decision for kit manufacturers is balancing investments between developing highly sensitive, lab-based PCR technologies and expanding portfolios of cost-effective, field-deployable lateral flow assays.
Market Dynamics
The proliferation of stringent, non-harmonized food safety regulations, led by frameworks like the US FSMA and standards from China's SAMR, is the central force shaping the market. This regulatory pressure mandates higher testing frequencies and pushes for specific technology adoption.
Growth Catalysts
- Stringent Regulatory Mandates:The US Food Safety Modernization Act (FSMA) compels preventative controls, requiring food processors to conduct routine pathogen testing, which directly drives kit volume.
- Expanding Food Processing Industry:Rapid industrialization in China's food sector, coupled with heightened oversight by the SAMR, creates sustained demand for a wide range of testing kits.
- Consumer Health Awareness:Increased focus on food allergens accelerates demand for specific detection kits to comply with stricter labeling laws in Europe and North America.
Market Restraints
- High R&D Costs:Significant investment to develop and validate high-sensitivity technologies like PCR and chromatography limits market entry and pressures innovator margins.
- Technical Performance Trade-offs:End-users face a compromise between the low cost and speed of lateral flow assays and the superior accuracy of laboratory-based methods.
- Complex Supply Chains:Production depends on a limited supply of high-affinity monoclonal antibodies and specific DNA primers, creating potential bottlenecks and price volatility.
Strategic Opportunities
- Emerging Market Penetration:Food safety modernization in Southeast Asian and Latin American countries presents growth opportunities as local regulations align with international standards.
- Novel Food Categories:The expansion of plant-based alternatives creates a new requirement for testing kits tailored to detect unique allergens, proteins, and potential contaminants.
- Digital Integration:Developing rapid tests that connect to cloud-based platforms offers an opportunity to provide customers with automated data logging, trend analysis, and traceability.
Industry Challenges
- Lack of Global Standardization:Disparate testing protocols between regions like the EU, US, and Asia complicate kit design and validation for manufacturers targeting a global audience.
- Data System Integration:Food producers struggle to integrate data from new on-site rapid tests into established Laboratory Information Management Systems (LIMS), creating data silos.
- Specialized Skill Gaps:Operating advanced high-throughput systems requires specialized technicians, a talent pool that remains scarce in many food processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Testing Kits Market |
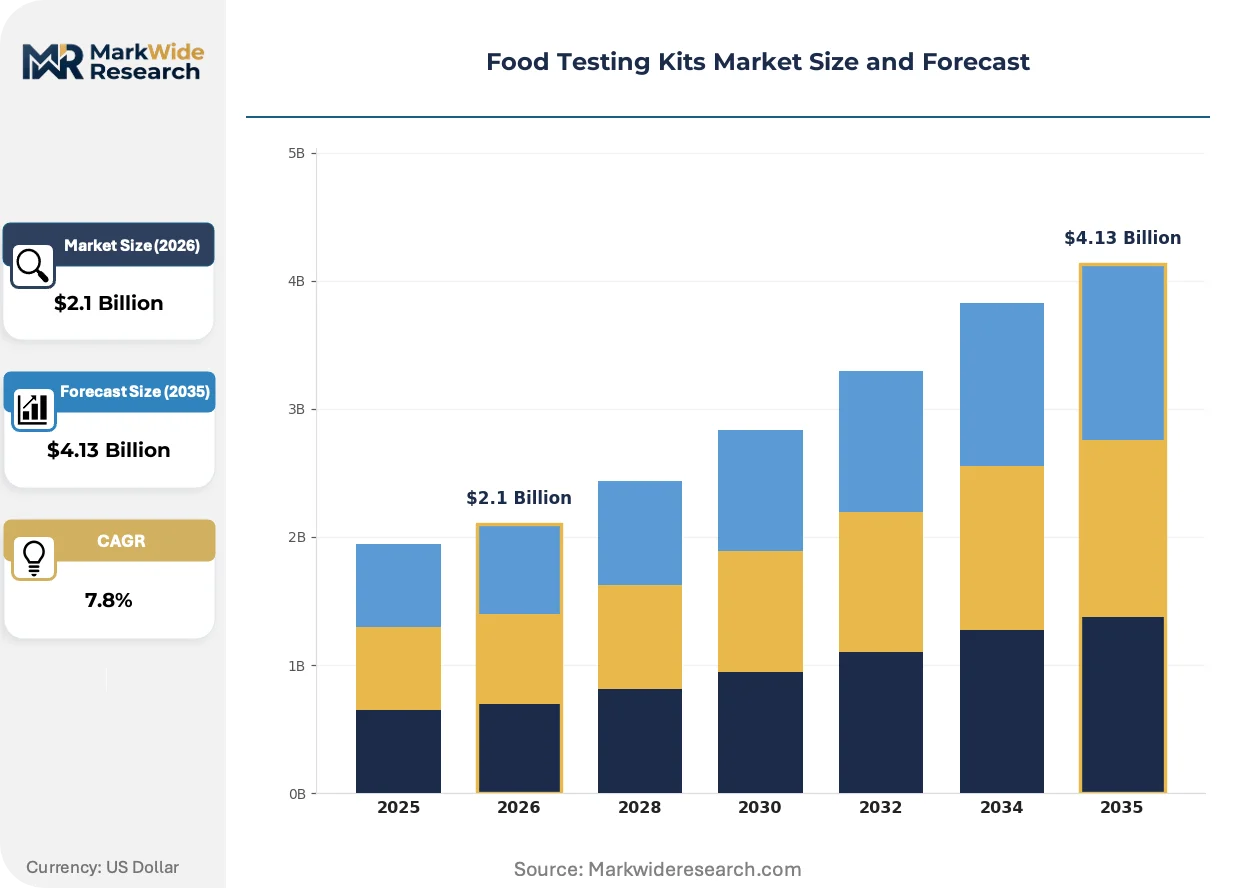
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbiological Kits, Chemical Residue Kits, Allergen Detection Kits, Genetically Modified Organism (GMO) Kits Technology: Polymerase Chain Reaction (PCR), Enzyme-Linked Immunosorbent Assay (ELISA), Lateral Flow Immunoassay, Chromatography Application: Contaminant Detection, Foodborne Pathogen Surveillance, Nutrient Analysis, Authenticity Testing End User: Food Processing Plants, Quality Control Laboratories, Research Institutes, Regulatory Authorities |
| Companies Covered | Neogen Corporation, bioMérieux SA, 3M Company, QIAGEN N.V., Merck KGaA, Thermo Fisher Scientific Inc., Agilent Technologies, Inc., Charm Sciences, Inc., Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Testing Kits Market Strategic Shifts & Innovations
Technological advancements are pushing testing from centralized labs toward the point of need on the production floor. This shift prioritizes speed and connectivity, altering how food producers manage safety and quality control.
Lab-on-a-chip platforms use microfluidics to perform complex molecular or immunoassay analyses. Food processing facilities adopt these for real-time quality assurance checks directly on production lines. This technology is miniaturizing entire laboratory workflows into handheld devices, reducing dependency on external testing services.
Stricter maximum residue limits (MRLs) for pesticides set by the European Food Safety Authority (EFSA) are influencing testing protocols globally. This forces exporters to the EU market to implement more rigorous screening methods. The grain and wine industries are most affected, driving investment in chromatography-based kits for compliance.
A behavioral shift is underway from qualitative pass-fail results toward demand for quantitative data and digital records. This change diminishes the value of basic visual-read test strips, favoring kits integrated with smartphone apps. The trend is most pronounced in the North American seafood and European dairy sectors where supply chain transparency is paramount.
Food Testing Kits Market Segmentation
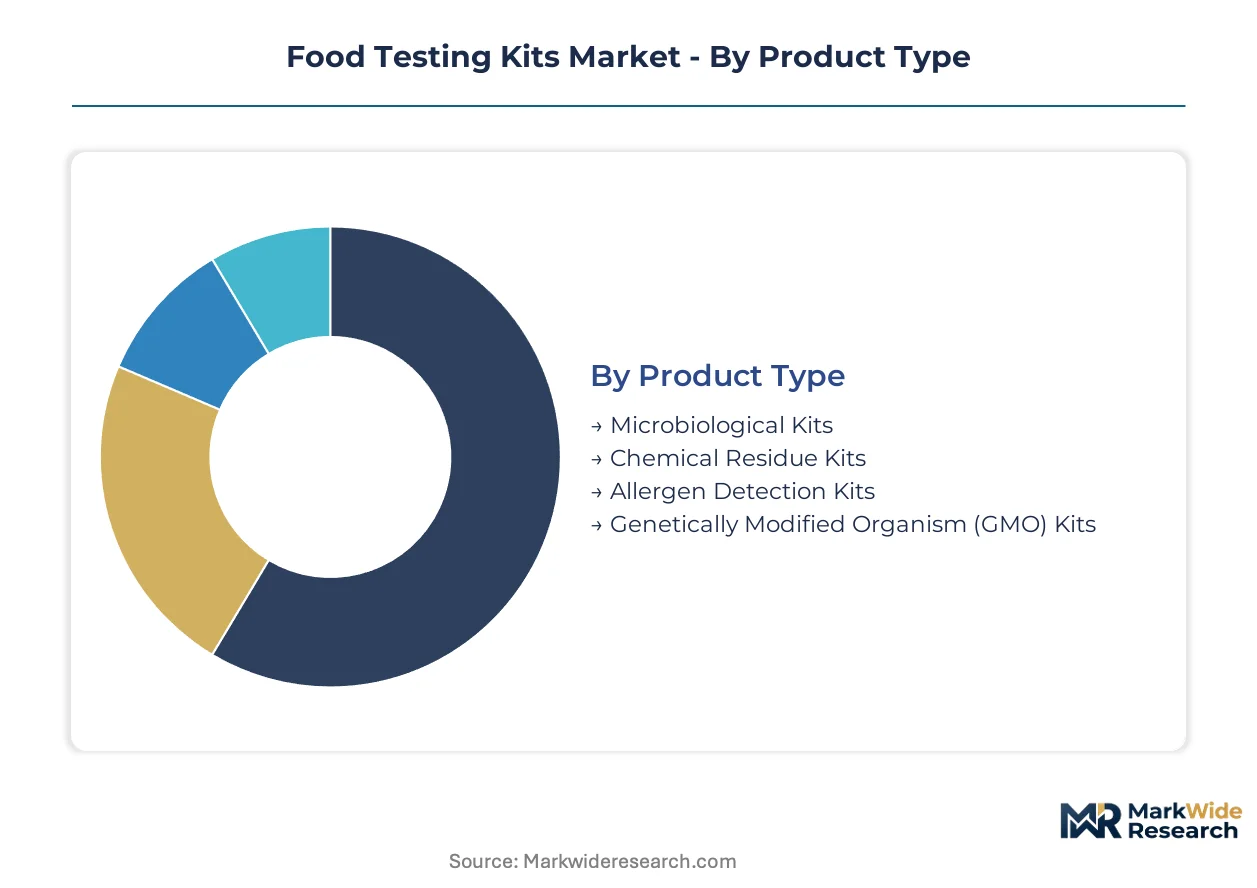
Understanding the distinct segments within the food testing kits market reveals varied compliance requirements and operational priorities. Regulatory frameworks globally drive specific kit adoption, influencing both technology choices and application focus for food safety. This granular analysis provides insights into where investment and innovation are most impactful across the value chain.
Product Type:
Regulatory differentiation for food safety drives distinct product type demands across global markets, influencing the development of specialized detection tools. Different regulatory bodies mandate specific testing parameters for various food categories.
- Microbiological Kits:These kits identify and quantify bacteria, viruses, and fungi in food samples, utilizing culture-based methods or molecular techniques like PCR. Demand for these kits is concentrating in European meat processing and North American dairy sectors due to stringent EFSA and USDA pathogen control mandates.
- Chemical Residue Kits:Designed to detect pesticides, antibiotics, and veterinary drug residues in food, these kits often employ immunoassay or chromatography principles. China's SAMR and Japan's Ministry of Health, Labour and Welfare impose strict maximum residue limits, driving demand for these kits in agricultural exports.
- Allergen Detection Kits:These kits specifically identify common food allergens such as peanuts, gluten, and dairy proteins, often using ELISA technology.
- Genetically Modified Organism (GMO) Kits:These kits detect the presence of genetically modified DNA sequences in crops and food products, primarily through PCR-based methods.
Established volume favors Microbiological Kits; emerging adoption favors Allergen Detection Kits.
Technology:
The complexity of analytical applications dictates the choice of testing technology, balancing speed, sensitivity, and cost-effectiveness. Each technology offers distinct advantages for specific detection challenges in food matrices.
- Polymerase Chain Reaction (PCR):PCR kits amplify specific DNA or RNA sequences to detect pathogens, GMOs, or allergens with high sensitivity and specificity. Demand for PCR technology is strong in European pathogen surveillance and US authenticity testing, driven by the need for definitive genetic identification.
- Enzyme-Linked Immunosorbent Assay (ELISA):ELISA kits use antigen-antibody reactions for quantitative or qualitative detection of proteins, toxins, or allergens. The seafood and dairy sectors in North America and Europe show high demand for ELISA due to its capability for rapid, high-throughput screening.
- Lateral Flow Immunoassay:These rapid, on-site tests provide quick qualitative or semi-quantitative results for contaminants or allergens, ideal for initial screening.
- Chromatography:Chromatography separates complex mixtures to identify and quantify chemical residues like pesticides or mycotoxins, offering high precision for regulatory compliance.
High sensitivity requirements often drive investment into Polymerase Chain Reaction (PCR), while rapid screening needs favor Lateral Flow Immunoassay.
Application:
End-user priorities in food safety and quality control shape the primary applications for testing kits, reflecting diverse needs from pathogen monitoring to nutritional verification. Each application addresses a critical aspect of food integrity.
- Contaminant Detection:This application focuses on identifying unwanted substances such as heavy metals, pesticides, and mycotoxins in food products, crucial for regulatory compliance. Strict MRLs set by EFSA for exports to the EU and SAMR standards in China significantly increase demand for these kits in fruit, vegetable, and grain industries.
- Foodborne Pathogen Surveillance:This involves routine testing for harmful microorganisms like Salmonella, E. coli, and Listeria, critical for public health protection and preventing outbreaks. The US FDA's FSMA mandates preventative controls, ensuring sustained demand for pathogen detection in meat, poultry, and dairy processing.
- Nutrient Analysis:Kits for nutrient analysis determine the nutritional content of food products, including vitamins, minerals, fats, and proteins, supporting accurate labeling.
- Authenticity Testing:This application verifies the origin, species, or composition of food ingredients to prevent fraud and ensure product integrity, particularly in high-value products.
Preventative regulatory mandates disproportionately influence demand for Contaminant Detection and Foodborne Pathogen Surveillance.
End User:
Operational scale and regulatory oversight define the distinct end-user segments, each requiring tailored testing solutions to meet their specific compliance and quality objectives. Different entities have varying needs for throughput and data integration.
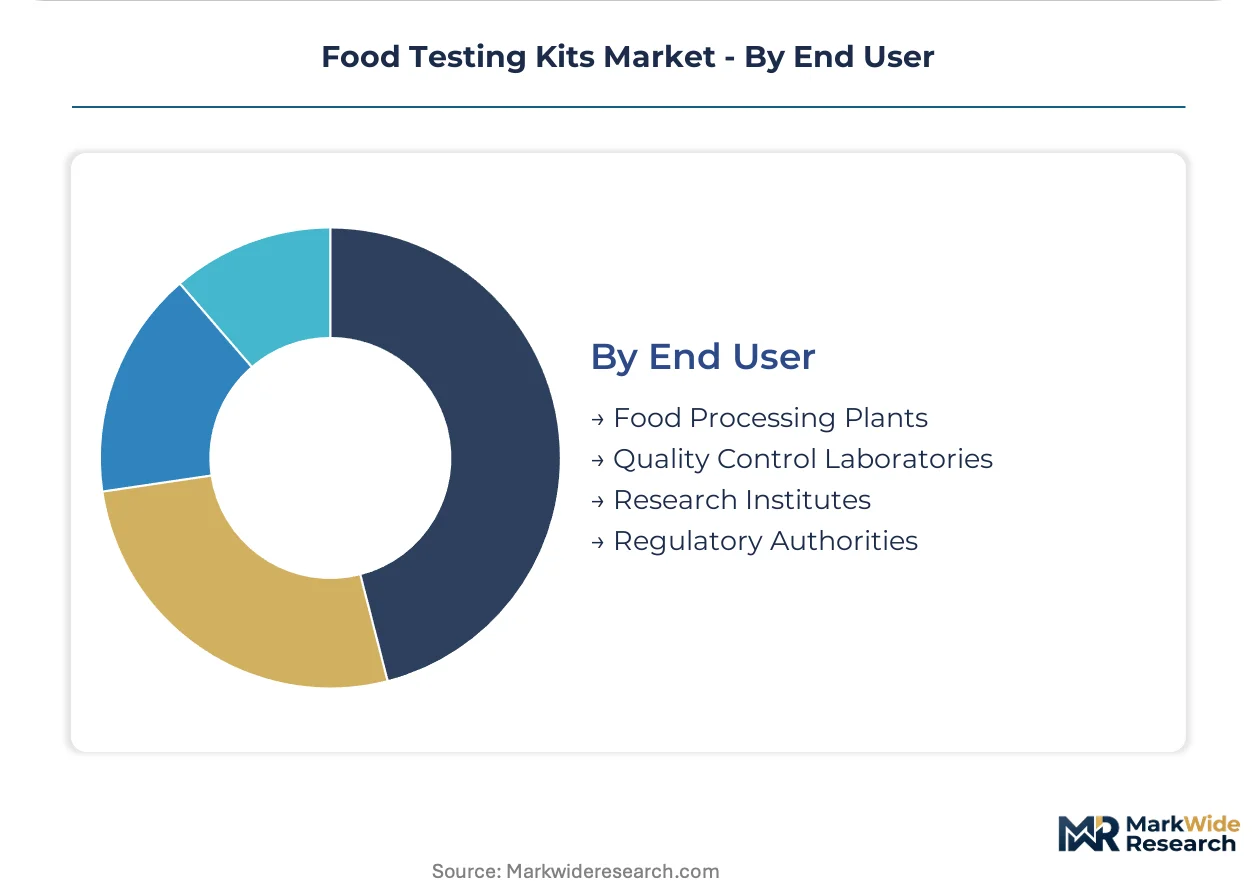
- Food Processing Plants:These facilities conduct in-house testing for raw materials, in-process samples, and finished products to ensure safety and quality throughout production. Stringent regulations like the US FSMA compel food processors to implement routine pathogen and allergen testing, driving high-volume kit purchases.
- Quality Control Laboratories:Independent or corporate laboratories offer specialized analytical services, performing advanced and confirmatory tests for food producers and regulators. These labs frequently handle complex chromatography and PCR analyses for export compliance to markets like the EU and Japan.
- Research Institutes:Academic and private research entities utilize food testing kits for method development, scientific studies, and understanding food safety challenges.
- Regulatory Authorities:Government agencies employ testing kits for market surveillance, verifying compliance with food safety standards, and investigating foodborne incidents.
Volume requirements are highest among Food Processing Plants, while advanced analytical capabilities are concentrated within Quality Control Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across global food testing kit markets, with some regions exhibiting high price sensitivity for routine screening while others prioritize advanced, higher-cost analytical solutions. Regulatory stringency consistently correlates with higher demand for precise and validated testing methodologies. Local food safety cultures and export market requirements also dictate the adoption rates of different kit technologies.
United States
The US market for food testing kits is driven by strict federal oversight and a large, diversified food processing industry. The US FDA's Food Safety Modernization Act (FSMA) mandates comprehensive preventative controls, requiring extensive pathogen and allergen testing. Major food production hubs in states like California and Iowa demonstrate sustained demand for high-throughput PCR and ELISA kits.
China
China presents a rapidly expanding market, fueled by heightened consumer awareness and aggressive government initiatives to bolster food safety. The State Administration for Market Regulation (SAMR) enforces stringent standards, particularly for chemical residues and foodborne pathogens. Provinces such as Guangdong and Shandong, with their vast food manufacturing bases, concentrate demand for diverse testing solutions.
Germany
Germany's food testing kit market benefits from robust export-oriented food production and the rigorous standards of the European Food Safety Authority (EFSA). Compliance with maximum residue limits (MRLs) and pathogen controls drives demand for sophisticated chromatography and PCR technologies. Bavaria and North Rhine-Westphalia, key agricultural and processing regions, lead in adopting advanced analytical methods.
Japan
Japan's market is characterized by a strong emphasis on food quality, safety, and authenticity, influenced by the Ministry of Health, Labour and Welfare's strict regulations. Demand concentrates on kits for allergen detection, chemical residues, and precise authenticity testing for high-value products. The Kanto region, including Tokyo, serves as a central hub for advanced food safety laboratories and research.
Brazil
Brazil's food testing market is growing due to its significant agricultural exports and increasing domestic food safety regulations. The country's national agricultural and food safety authorities are implementing stricter controls on contaminants and pathogens. Major food processing centers in São Paulo and Minas Gerais drive the need for cost-effective rapid tests and reliable laboratory-based solutions.
Food Testing Kits Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a tiered market structure. These large entities offer comprehensive portfolios, while numerous niche players focus on specific technologies or applications. Three strategic archetypes define the competitive landscape: diversified solution providers, specialized technology innovators, and regional rapid test manufacturers. Competitive moves frequently involve strategic partnerships to expand geographic reach and technology licensing to integrate novel detection methods.
Diversified solution providers like Thermo Fisher Scientific Inc. leverage extensive R&D capabilities to offer a wide array of high-sensitivity PCR and chromatography instruments. bioMérieux SA sustains its market position through deep expertise in microbiological and pathogen detection solutions, catering to high-volume laboratory needs. Meanwhile, Charm Sciences, Inc. exemplifies specialized technology innovators, focusing on rapid, on-site tests for specific contaminants and allergens, serving immediate quality control requirements at the processing floor.
| Leading Market Players |
|---|
| Neogen Corporation |
| bioMérieux SA |
| 3M Company |
| QIAGEN N.V. |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies, Inc. |
| Charm Sciences, Inc. |
| Bio-Rad Laboratories, Inc. |
| Others |
Cost & Logistics Intelligence
The 90-day inventory cycle for high-affinity monoclonal antibodies directly influences the supply chain's resilience and kit manufacturers' pricing power. This dynamic creates a tension where specialized component availability can dictate production schedules and impact final kit costs for food producers.
Pricing Analysis
The recurring revenue from instrument calibration and service contracts drives long-term value for high-throughput system providers. Pricing for food testing kits often follows a hybrid model, combining per-unit transactional sales for consumables with service contracts for analytical instruments. Certification level, such as FDA or EFSA validation, and volume scale are primary drivers of price differentiation. Pricing pressure stems from the increasing competition from low-cost rapid assays. Food processing plants are the most price-sensitive buyers for routine tests, while Quality Control Laboratories prioritize advanced analytical capabilities over cost for confirmatory tests.
Supply Chain Analysis
China and the United States anchor the production of key reagents like DNA primers and specialized antibodies for food testing kits. The supply chain for these kits draws from a limited global pool of high-affinity monoclonal antibodies and specific DNA primers. Single-source vulnerability for these specialized reagents represents a structural supply chain risk. Distribution runs through direct sales channels for large food processors and comprehensive distributor networks serving smaller laboratories and regulatory bodies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food testing kits market experiences a buyer-power shift as the food processing industry consolidates, creating larger procurement entities. This consolidation demands more integrated solutions and better data management from kit providers.
For Market Incumbents:
Fortify core market positions by investing in next-generation PCR and chromatography platforms to maintain technological leadership. Pursue strategic acquisitions of niche technology firms specializing in novel detection methods to counter emerging low-cost rapid assay providers. Prioritize certification investment for new methods to meet evolving regulatory standards from the US FDA and European EFSA. Enhance channel control through direct sales teams focused on large food processing accounts.
For New Entrants and Emerging Players:
The service-layer gap in integrating rapid on-site test data with existing Laboratory Information Management Systems (LIMS) presents an opportunity. Target small to mid-sized food processing plants in Southeast Asian countries where food safety modernization is accelerating. Develop cloud-based data analytics platforms bundling rapid tests to offer automated logging and trend analysis. Focus on specific allergen detection kits to capitalize on stricter labeling mandates in Europe.
For Investors and Strategic Acquirers:
Carve-out targets emerge from large diversified life sciences conglomerates seeking to divest non-core food safety divisions. The long-term viability of this market is strong, driven by global regulatory harmonization and consumer health awareness. Seek out vertically integrated specialists in specific detection technologies, such as advanced allergen or pathogen detection. Increased M&A activity among mid-sized technology innovators specializing in digital integration represents a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Cloud-Integrated Rapid Tests | Provides automated data logging and trend analysis for food producers, enhancing traceability. |
| Acquire Niche Allergen Detection Specialist | Expands product portfolio to meet rising demand from stricter labeling mandates in Europe. |
| Invest in Microfluidics R&D | Miniaturizes laboratory workflows into handheld devices for real-time quality assurance on production lines. |
| Expand Distribution in Southeast Asia | Captures growth from food safety modernization and aligning local regulations with international standards. |
| Secure Long-Term Reagent Supply Contracts | Mitigates supply chain risks and price volatility for critical components like monoclonal antibodies. |
Research Approach
A standing panel of food safety officers, quality assurance managers, regulatory compliance specialists, and kit manufacturers' R&D leads provided ongoing calibration for primary insights. This included combining primary interviews with industry stakeholders and secondary validation from official reports. Bottom-up and top-down triangulation ensured data accuracy across the analysis. Secondary data sources included EFSA reports, USDA food safety data, company annual reports, and scientific journals.
Output consistency checks against historical market sizing and macroeconomic indicators validated the forecast framework. The analytical framework employed demand-side modeling and supply-side capacity analysis across the modeling period. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory stringency. Compound annual growth rates were derived from projected volume and value trajectories, using food production volumes and regulatory enforcement budgets as key forecast inputs.
Forecasts assume regulatory continuity in US FDA and European EFSA regimes; material policy shifts would require re-modeling. The analysis reflects documented assumptions regarding technological advancements and market dynamics. Unforeseen technological breakthroughs or global trade disruptions represent specific risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
High-Throughput Food Allergen Screening Test Instruments Market
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Mercury Testing Service Market