
 Catering Food Warmers Market | 2026-2036
Catering Food Warmers Market Size, Share, and Industry Trends Forecast 2026-2036
Catering Food Warmers Market Analysis
Market Dynamics
Premium hot-holding equipment is decoupling from commodity buffet warmers on the basis of precision temperature control, IoT connectivity, and stainless steel gauge specifications. Hatco leverages its vertical integration into heating element manufacturing to sustain margin advantages in countertop warmers. Alto-Shaam anchors the premium tier through its Halo Heat low-temperature holding technology, while Vollrath competes aggressively on modularity and NSF-certified construction for institutional buyers.
Product Architecture
Catering food warmers are electrically or gas-powered thermal retention appliances designed to maintain prepared food within HACCP-compliant temperature zones, typically between 140°F and 165°F, using convected, conducted, or radiant heat transfer. Heated display cases command the highest unit margins due to glass construction and merchandising functionality, while electric power sources dominate volume shipments across restaurants and catering services. Buffet servers represent the most mature segment with replacement-driven demand, whereas hybrid power configurations are gaining traction among food truck operators seeking generator flexibility.
Regulatory Environment
NSF International and UL standards govern material safety and electrical compliance for commercial food warmers in the United States, while the EU Green Deal and Ecodesign regulations are tightening energy efficiency thresholds for electric holding cabinets in Europe. These frameworks elevate capital costs for non-compliant manufacturers while creating specification advantages for certified suppliers. Stakeholders must monitor evolving state-level energy rebates and commercial kitchen electrification mandates that will reshape equipment replacement timelines and power source preferences.
Market Dynamics
NSF International certification requirements and energy efficiency mandates are bifurcating procurement between premium certified equipment and commodity alternatives, concentrating specification power with institutional buyers and hospitality renovation contractors.
Growth Catalysts
- Commercial kitchen electrification mandates:State-level building codes in California, New York, and Washington are phasing out gas-powered holding equipment in new construction, redirecting capital toward electric warming cabinets and heated display cases.
- Food trucks and mobile catering expansion:Hybrid power configurations combining battery storage with generator flexibility are attracting fleet operators seeking operational versatility across urban and remote service locations.
- HACCP compliance automation:Precision temperature logging and IoT-enabled monitoring systems are becoming standard requirements for institutional catering contracts, particularly in healthcare and correctional facilities.
Market Restraints
- Stainless steel input volatility:Gauge-grade 304 and 316 stainless steel pricing fluctuations compress margins for manufacturers of NSF-certified construction, forcing absorption or pass-through tradeoffs.
- Heating element supply concentration:Ceramic and calrod element production clusters in East Asia create single-source dependencies for North American and European equipment assemblers.
- UL electrical compliance timelines:Extended certification cycles for novel power configurations delay product launches and freeze R&D amortization schedules.
Strategic Opportunities
- Cloud kitchen infrastructure buildout:Ghost kitchen operators in dense metropolitan zones require compact, high-density warming arrays with rapid recovery cycles and minimal footprint.
- EU Ecodesign regulatory tailwind:Tightening efficiency thresholds for electric holding cabinets create first-mover advantages for manufacturers with standby power optimization and insulated cavity designs.
- Remote temperature monitoring convergence:Integration of Bluetooth Low Energy and cellular telemetry enables predictive maintenance subscriptions and compliance documentation automation for multi-location operators.
Industry Challenges
- Field service technician scarcity:Specialized expertise in dual-fuel systems and IoT diagnostics is concentrating with OEM captive service networks, raising aftermarket support costs.
- Legacy control system integration:Proprietary temperature management protocols from incumbent manufacturers create interoperability friction for third-party monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catering Food Warmers Market |
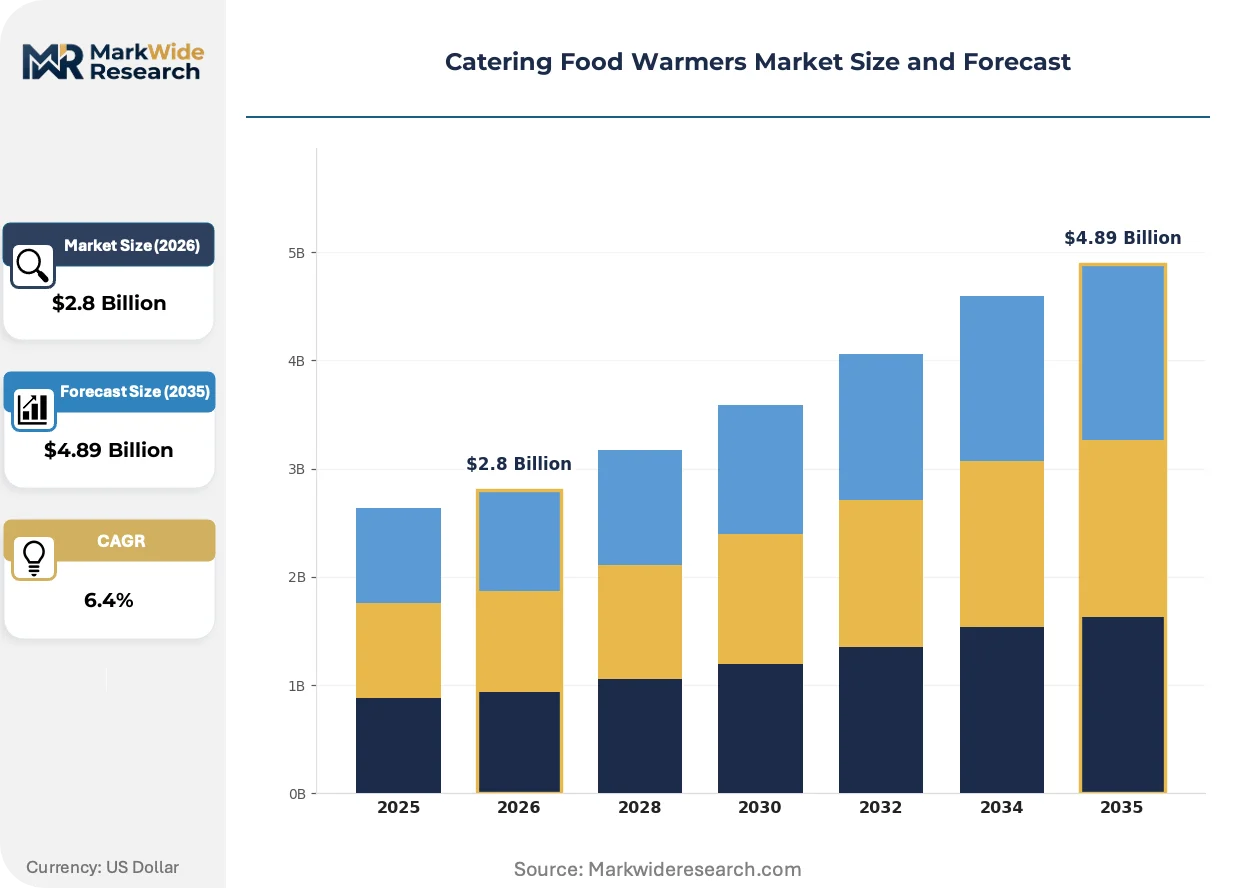
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Warmers, Buffet Servers, Heated Display Cases, Bain Maries End User: Restaurants, Catering Services, Hotels, Food Trucks Power Source: Electric, Gas, Hybrid, Solar Size: Small, Medium, Large, Extra Large |
| Companies Covered | Hatco, Alto-Shaam, Vollrath, Winco, Cambro Manufacturing, The Middleby Corporation, True Manufacturing, Turbo Air, Cres Cor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catering Food Warmers Market Emerging Trajectories
Active reshaping in catering food warmers centers on connected equipment architectures, regulatory-driven efficiency upgrades, and procurement model compression toward specification bundling.
Induction warming technology is consolidating position in high-throughput buffet and banquet applications. Casino resorts and convention centers in Las Vegas and Orlando are replacing radiant heat lamps with induction drop-in wells to reduce ambient kitchen temperatures and energy draw. The technology is consolidating supplier relationships around firms with in-house coil manufacturing and control firmware development.
EU Green Deal implementation timelines are accelerating equipment replacement cycles across continental hospitality. Ecodesign regulations mandating maximum standby power consumption for heated cabinets are disqualifying legacy inventory from new procurement tenders. Full-service restaurant chains in Germany, France, and the Netherlands are front-loading capital expenditure to secure compliant inventory before 2027 enforcement windows.
Specification bundling is compressing buyer decision cycles and consolidating vendor relationships. Institutional catering directors are consolidating hot-holding, refrigeration, and serving equipment under single-source contracts with unified IoT dashboards. This pattern is most visible in United States healthcare systems and university dining services, where procurement committees prioritize interoperable fleet management over best-of-breed component selection.
Catering Food Warmers Market Segmentation
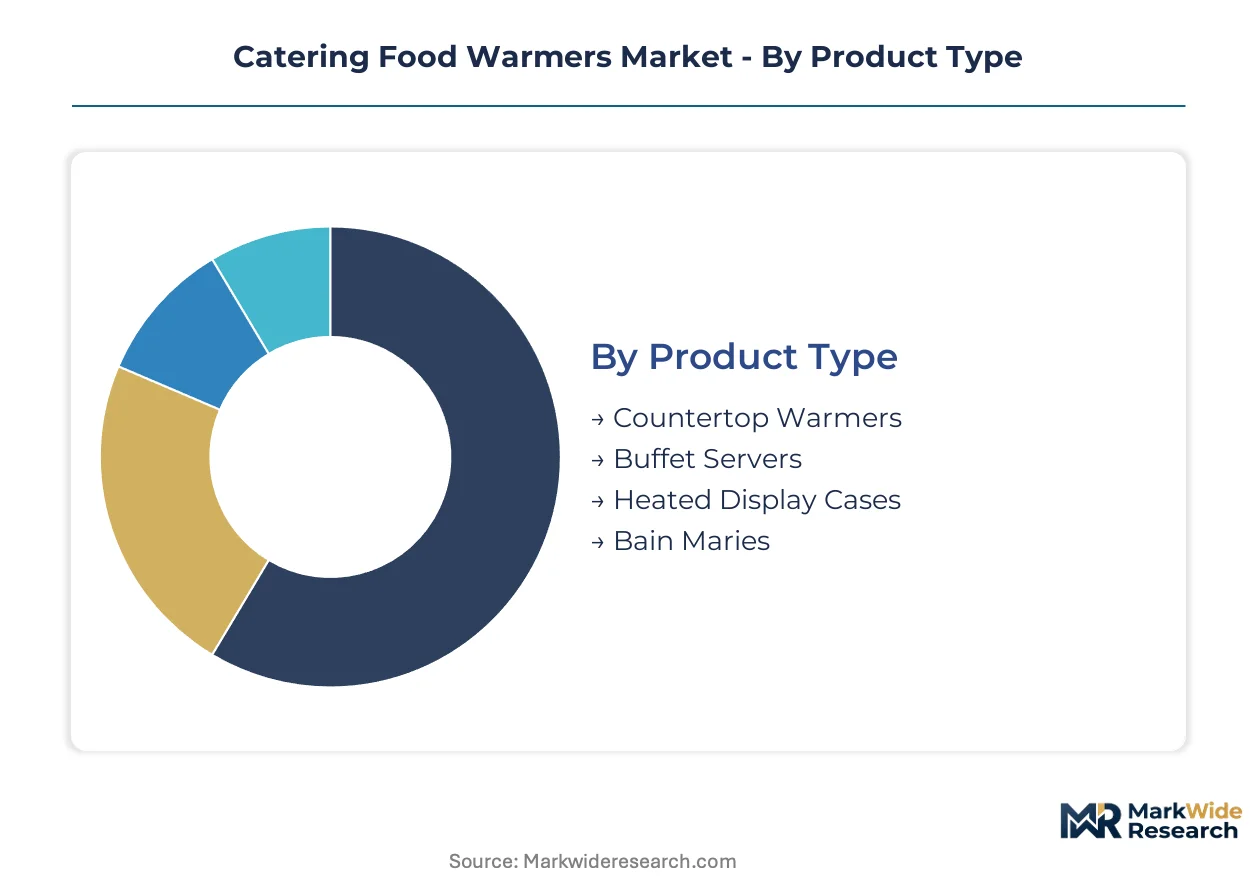
Segmentation in catering food warmers reveals how procurement specifications diverge across operational environments. Equipment selection hinges on power infrastructure, service format, and compliance requirements rather than unit economics alone.
Product Type:
Supply concentration in glass fabrication and precision heating elements concentrates margin capture among manufacturers with captive coil production or vertical integration into display case assembly.
- Countertop Warmers:Compact electrically heated units with convected or conducted heat transfer, typically 1-4 pan capacity. Demand concentrates in United States independent restaurants and ghost kitchen operators where space constraints and rapid recovery cycles dominate specification. California electrification mandates are redirecting procurement toward UL-certified electric models with NSF construction.
- Heated Display Cases:Glass-enclosed merchandising units with radiant or convected heating, commanding premium positioning through visual presentation functionality. United States casino resorts and convention centers in Las Vegas and Orlando are consolidating supplier relationships around firms with in-house coil manufacturing as induction warming displaces radiant heat lamps.
- Buffet Servers:Mature chafing dish and steam table configurations for self-service applications.
- Bain Maries:Water bath warming systems for sauce and liquid holding in institutional settings.
Today's leader: Heated Display Cases. Tomorrow's challenger: Countertop Warmers.
End User:
Customer type determines specification intensity, with institutional buyers enforcing NSF certification and IoT connectivity requirements that commodity purchasers ignore.
- Restaurants:Full-service and limited-service operators with varying throughput requirements. United States renovation cycles and state-level electrification mandates in California, New York, and Washington are accelerating replacement timelines for gas-powered holding equipment.
- Hotels:Banquet and catering departments with high-volume, intermittent service patterns. Demand clusters in United States urban markets where hospitality construction and property renovation remain active.
- Catering Services:Mobile and fixed-location operators serving institutional and private events.
- Food Trucks:Mobile operators requiring generator flexibility and compact footprints, driving hybrid power configuration adoption.
Procurement gravity rests with Hotels. Fleet operators in Food Trucks are climbing the fastest.
Power Source:
Regulatory momentum is compressing the viable power source set, with electrification mandates and EU Ecodesign thresholds disqualifying legacy configurations from new tenders.
- Electric:Dominant volume configuration using resistive or induction heating elements. United States state-level building codes and EU Ecodesign standby power regulations are elevating specification requirements for insulated cavity designs and precision temperature control.
- Hybrid:Battery storage combined with generator or grid connectivity. Food truck fleet operators across United States metropolitan zones are adopting these configurations for operational versatility across urban and remote service locations.
- Gas:Propane or natural gas configurations facing phase-out in new construction.
- Solar:Photovoltaic-assisted warming with limited commercial penetration.
Electric commands current procurement. Hybrid configurations are gaining share fastest.
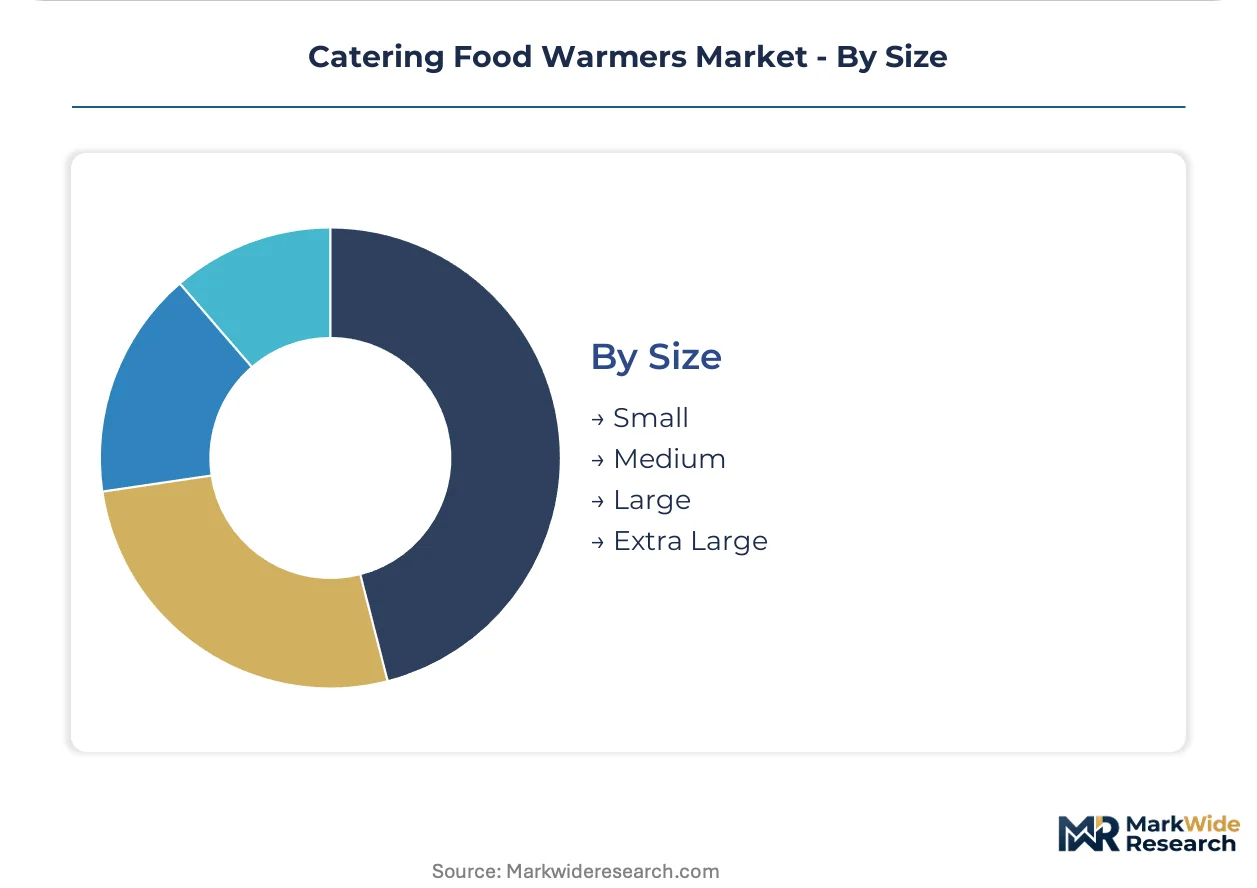
Size:
Footprint requirements correlate with real estate costs and service format density, driving divergence between compact urban installations and high-volume banquet infrastructure.
- Small:Single-pan or limited-capacity units for space-constrained operations. Ghost kitchen operators in dense United States metropolitan zones specify these for minimal footprint and rapid recovery cycles.
- Large:Multi-pan high-capacity systems for banquet and institutional service. United States healthcare systems and university dining services are consolidating procurement under single-source contracts with unified fleet management.
- Medium:Mid-capacity units bridging countertop and built-in applications.
- Extra Large:Custom-configured warming arrays for convention centers and stadium catering.
Large formats anchor institutional procurement. Small units are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technicians in commercial kitchen equipment installation and IoT diagnostics concentrate in United States metropolitan corridors, Germany's industrial heartland, and China's manufacturing zones, anchoring regional service capabilities and procurement specification authority.
United States
Institutional catering contracts and hospitality renovation cycles drive specification intensity for NSF-certified equipment with precision temperature logging. California's building electrification mandates under Title 24 phase out gas-powered holding equipment in new commercial kitchen construction. Las Vegas casino resorts and Orlando convention centers are consolidating supplier relationships around induction warming systems to reduce ambient temperatures and energy draw.
Germany
Full-service restaurant chains front-load capital expenditure to secure Ecodesign-compliant inventory ahead of enforcement windows. The EU Green Deal and Ecodesign regulations mandate maximum standby power consumption thresholds for electric holding cabinets, disqualifying legacy equipment from procurement tenders. Industrial clusters in North Rhine-Westphalia and Bavaria host equipment assemblers integrating standby power optimization and insulated cavity designs.
China
Domestic hospitality construction and export manufacturing capacity expansion sustain demand for gauge-grade stainless steel construction. The country's national commercial equipment regulator enforces GB standards for electrical safety and material specifications in food service appliances. Manufacturing concentrations in Guangdong and Zhejiang provinces supply ceramic and calrod heating elements to North American and European equipment assemblers.
Japan
Precision manufacturing traditions translate into specification requirements for temperature control accuracy in banquet and institutional applications. METI energy efficiency guidelines and JIS standards govern commercial kitchen equipment performance thresholds. The Kanto region around Tokyo anchors demand from hotel chains and contract catering operators renovating aging hot-holding infrastructure.
United Kingdom
Healthcare system procurement committees prioritize interoperable fleet management for multi-location catering operations. NHS estate modernization programs specify HACCP-compliant warming equipment with unified IoT dashboards for temperature monitoring. London and Southeast England concentrate demand from university dining services and private hospital chains consolidating vendor relationships under single-source contracts.
Catering Food Warmers Market Vendor Landscape
Capital-heavy producers with captive heating element manufacturing compete with asset-light designers outsourcing coil production and final assembly. The vendor base organizes around three strategic archetypes: vertically integrated specialists controlling upstream component supply, modular system assemblers competing on NSF-certified construction flexibility, and premium technology developers anchoring specification power through proprietary low-temperature holding protocols. Dominant competitive moves include backward integration into heating element production to defend margin position, and strategic partnerships with IoT platform providers to bundle remote monitoring subscriptions with equipment sales.
Within the vertically integrated tier, Hatco Corporation and Alto-Shaam exemplify contrasting approaches to sustaining specification authority—Hatco through in-house production of heating elements for countertop warmers, Alto-Shaam through proprietary Halo Heat technology anchoring premium-tier positioning. Vollrath Company occupies a position between these archetypes, competing aggressively on modularity and NSF-certified construction for institutional buyers requiring flexible configuration options. These three players collectively represent the competitive spectrum from component-level control to system-level integration.
| Leading Market Players |
|---|
| Hatco |
| Alto-Shaam |
| Vollrath |
| Winco |
| Cambro Manufacturing |
| The Middleby Corporation |
| True Manufacturing |
| Turbo Air |
| Cres Cor |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign standby power mandates and California Title 24 electrification codes gate qualified supply access and premium-tier pricing power for NSF-certified manufacturers serving institutional buyers and hospitality renovation contractors.
Pricing Analysis
The bundled-vs-unbundled service split separates equipment-only transactions from IoT monitoring subscription packages. Three-tier pricing structure across premium, standard, and economy levels stratifies by NSF certification grade and precision temperature control capability. Pricing pressure stems from stainless steel input volatility compressing margins on gauge-grade 304 construction. Institutional catering directors exhibit lowest price sensitivity due to compliance documentation requirements, while independent restaurants and food truck operators prioritize unit economics.
Supply Chain Analysis
Domestic-content mandates in US federal procurement and EU public tender rules are reshaping sourcing toward regional stainless steel fabrication and captive heating element production. Gauge-grade 304 and 316 stainless steel draws from China, India, and US domestic mills, while ceramic and calrod heating elements concentrate in Guangdong and Zhejiang provinces. Single-source vulnerability in East Asian element production creates procurement risk for North American assemblers. Distribution runs through hospitality equipment dealers and foodservice supply houses serving institutional and commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Ecodesign enforcement windows and US state-level electrification mandates continuously refresh replacement demand across hospitality and institutional sectors.
For Market Incumbents: Deploy captive heating element manufacturing to defend margin position against commodity assemblers sourcing from East Asian single-source suppliers. Accelerate IoT platform partnerships to bundle predictive maintenance subscriptions with equipment sales, creating switching costs against modular competitors. California Title 24 phase-out timelines for gas-powered equipment threaten legacy product lines without rapid electric portfolio expansion. For New Entrants and Emerging Players: Direct-to-food-truck digital channels offer lowest competitive density against established dealer networks serving hotels and hospitals. Target hybrid power configuration demand from mobile catering fleets seeking generator flexibility across urban and remote locations. White-space exists in compact warming arrays for ghost kitchen operators prioritizing minimal footprint and rapid recovery cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional foodservice equipment distributors with captive service networks because field technician scarcity concentrates aftermarket support pricing power with OEM-affiliated channels. Long-term viability hinges on electrification compliance capabilities across state and federal regulatory frameworks. Watch for induction warming technology adoption inflection in casino resort and convention center refurbishment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Captive coil production defends margins against East Asian supply concentration and tariff exposure. |
| IoT Platform Partnership | Bluetooth Low Energy telemetry enables predictive maintenance subscriptions for multi-location operators. |
| NSF Certification Investment | UL and NSF compliance opens institutional procurement channels closed to commodity alternatives. |
| Hybrid Power Configuration Launch | Battery-generator flexibility captures food truck fleet demand across urban and remote service locations. |
| EU Ecodesign Compliance Program | Standby power optimization and insulated cavity designs secure first-mover advantage in continental hospitality tenders. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice equipment procurement directors, commercial kitchen design consultants, NSF certification specialists, and aftermarket service technicians with secondary validation against UL certification databases, state energy commission rebate filings, and hospitality construction permit records. Bottom-up equipment shipment analysis triangulated against top-down hospitality renovation expenditure tracking.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product architecture, power source configuration, end-use environment, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and electrification mandate compliance timelines incorporated HACCP automation requirements and EU Ecodesign standby power thresholds as demand drivers.
The model assumes a particular technology adoption path; alternative pathways for induction warming displacement of radiant heat systems would alter the outlook for heating element supply chains and manufacturer margin structures. Forecasts reflect assumptions regarding state-level electrification enforcement consistency and stainless steel pricing stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Brazil Foodservice Market
Food Service
Europe Food Service Market
Food Service
Restaurants and Mobile Food Services Market
Food Service
Africa Foodservice Market
Food Service
Tabletop Pizza Oven Market
Food Service
Cutting Boards Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
Contract Blending Services Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Philippines Quick Service Restaurants Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Commercial Sink Market
Food Service
Gas Fryers Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
South America Free from Food Market
Food Service
Cloud Kitchen Market