
 Food Display Cabinet Market | 2026-2036
Food Display Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Food Display Cabinet Market Analysis
The EU F-Gas Regulation is pivoting European food retail toward hydrocarbon and CO2-based display cabinet systems. Carrier Global Corporation leverages its transnational service network to sustain aftermarket revenue across retrofit cycles. True Manufacturing anchors North American production with domestic stainless-steel fabrication capacity. Hussmann competes on integrated refrigeration architecture for supermarket chains.
Food display cabinets are thermally insulated enclosures with glass panels, engineered to maintain precise temperature zones between -18°C and +65°C depending on application, using forced-air or gravity-coil refrigeration circuits. Their primary commercial purpose is to present perishable or prepared goods to consumers while preserving food safety and extending shelf visibility. Refrigerated display cases dominate unit volume in supermarkets, while heated display cases capture premium margin pools in quick-service environments. Stand-alone units lead installation-type shipments due to flexibility in renovation projects, though integrated units are gaining traction in new-build food halls.
The US EPA SNAP program and the EU Ecodesign Directive impose refrigerant-phaseout timelines and minimum energy performance standards on commercial refrigeration equipment, forcing manufacturers to redesign compressor systems and insulation packages. China's GB standards and Japan's METI Top Runner program add parallel efficiency mandates across East Asian supply chains. Stakeholders must monitor refrigerant-transition compliance costs and regional energy-label divergence when allocating R&D budgets and factory certification investments.
Market Dynamics
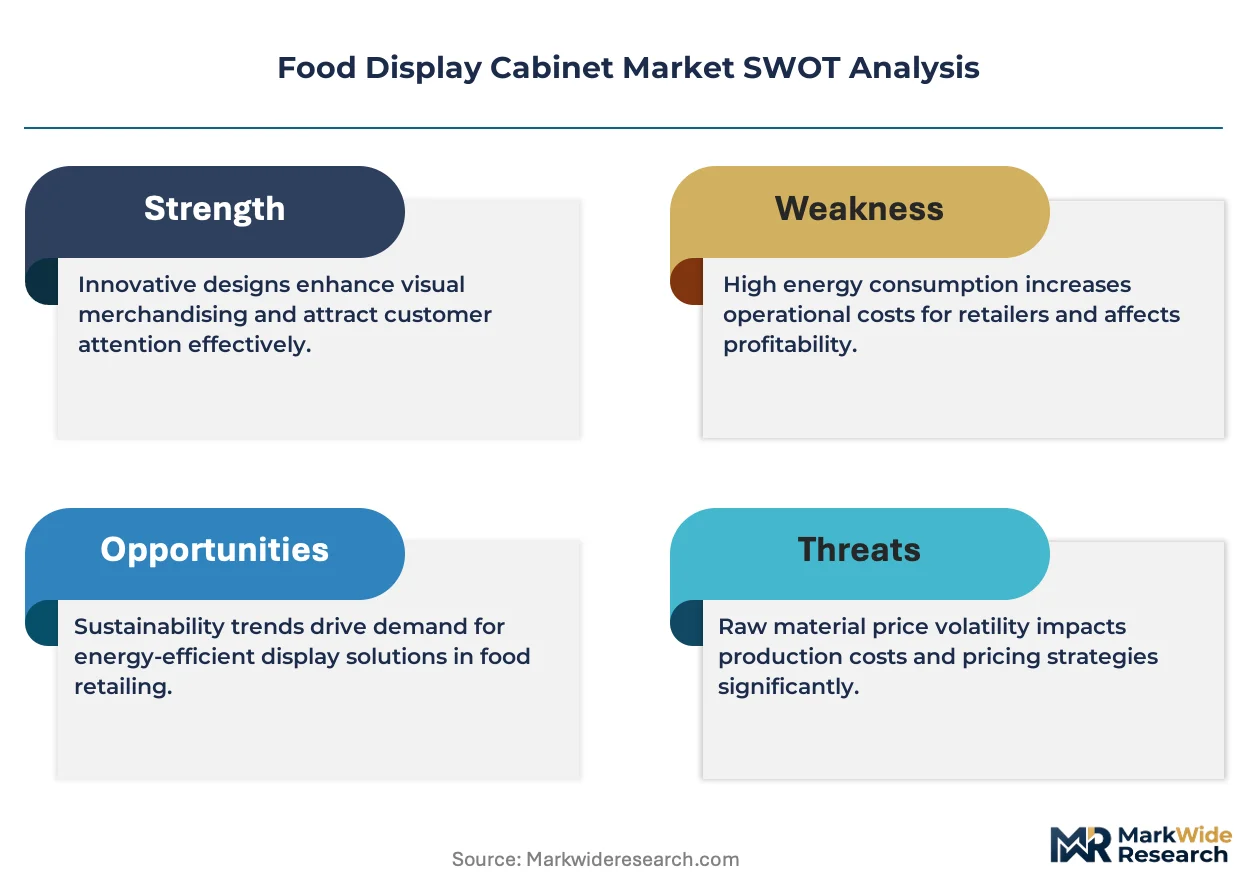
Refrigerant-phaseout mandates under the EU F-Gas Regulation and US EPA SNAP program are forcing simultaneous redesign of compressor architectures, insulation systems, and service protocols across food retail supply chains.
Growth Catalysts
- Natural refrigerant mandates:The EU F-Gas Regulation's HFC quota reductions are accelerating hydrocarbon and CO2 system adoption in supermarket chains, creating replacement demand for legacy R-404A equipment.
- Quick-service expansion:Southeast Asian QSR chains are scaling cold-chain infrastructure for prepared food visibility, driving unit demand for compact refrigerated display cases in high-temperature climates.
- Convenience-store densification:Tier-one Chinese cities are experiencing rapid convenience-store rollout, concentrating demand for grab-and-go display cabinets in Shanghai, Beijing, and Shenzhen.
Market Restraints
- Copper and aluminum volatility:Coil and frame material costs fluctuate with commodity markets, compressing margin predictability for mid-tier cabinet manufacturers.
- Compressor supply concentration:European and Japanese compressor OEMs control critical variable-speed technology, creating bottleneck risk for natural refrigerant system scaling.
- Retrofit capex burden:Existing R-404A infrastructure requires complete system replacement rather than drop-in refrigerant conversion, elongating payback periods for independent grocers.
Strategic Opportunities
- India cold-chain modernization:The country's PLI scheme for food processing infrastructure is subsidizing refrigerated display investments in organized retail formats.
- Refrigerant-as-a-service models:Leasing structures that bundle equipment, maintenance, and compliance monitoring are penetrating UK and German supermarket procurement.
- AI-driven predictive maintenance:Sensor-embedded cabinets with machine-learning fault detection are expanding into Japanese convenience-store networks, reducing unplanned downtime.
Industry Challenges
- Natural refrigerant technician scarcity:Hydrocarbon and CO2 system servicing requires specialized certification that outpaces vocational training program output in most markets.
- Multi-standard certification complexity:Manufacturers must simultaneously pursue UL, CE, and GB mark approvals, fragmenting engineering resources and elongating product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Display Cabinet Market |
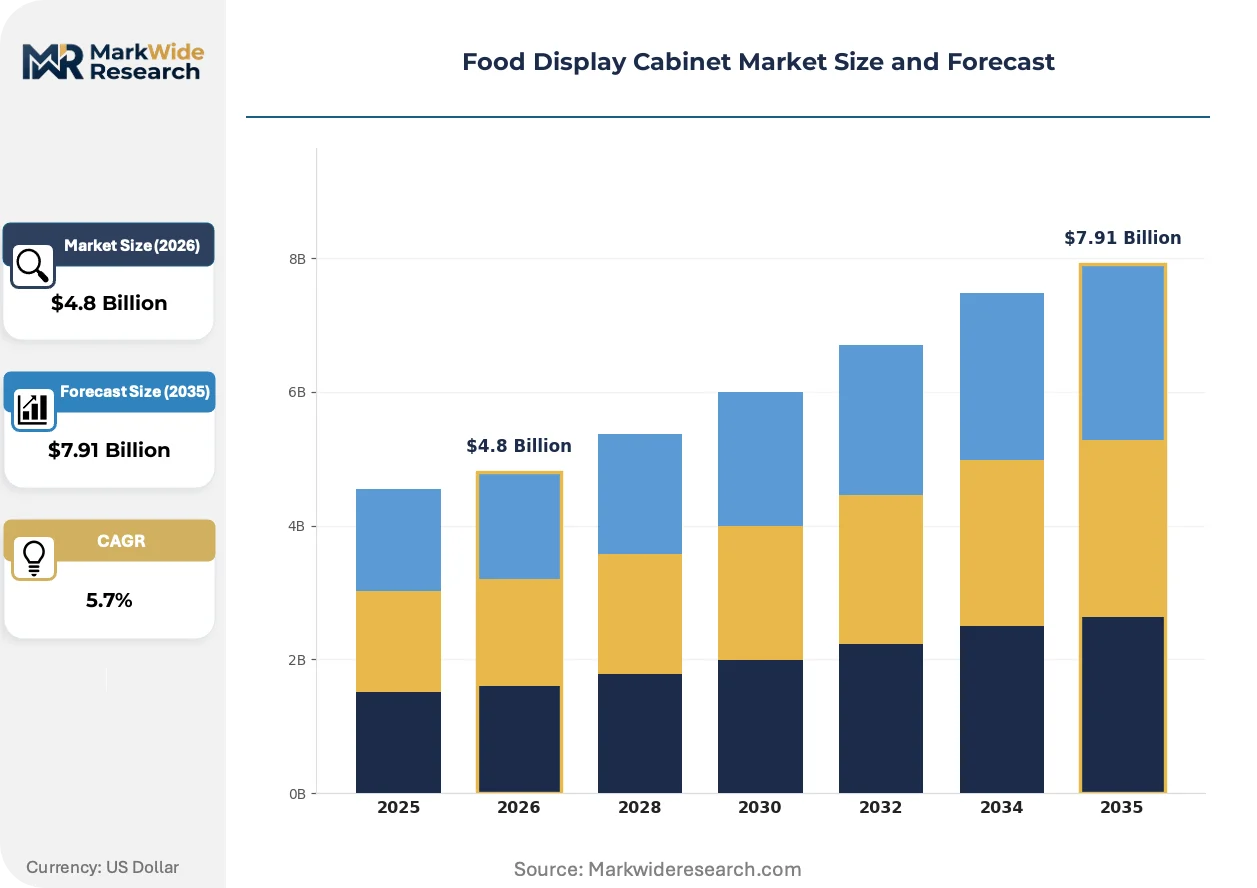
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Display Cases, Heated Display Cases, Bakery Display Cases, Beverage Merchandisers End User: Restaurants, Supermarkets, Convenience Stores, Coffee Shops Installation Type: Stand-Alone Units, Integrated Units, Built-In Units, Countertop Models Distribution Channel: Direct Sales, Online Retail, Distributors, Showrooms |
| Companies Covered | Carrier Global Corporation, Hoshizaki Corp, True Manufacturing, The Vollrath Co. LLC, The Middleby Corp, Hussmann, Hatco Corp, FRIGOGLASS S.A.I.C, Alto-Shaam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Display Cabinet Market Emerging Trajectories
Active redesign of thermal management architectures is compressing energy consumption benchmarks while expanding connectivity integration, reshaping how food retailers specify and operate display infrastructure.
CO2 transcritical booster systems are expanding into warm-climate supermarket applications, delivering subcritical efficiency in ambient temperatures previously requiring HFC cascade architectures. Australian and Southeast Asian retail chains are piloting these configurations in preparation for phased HFC restrictions. The technology is expanding into regions where ambient heat rejection previously blocked natural refrigerant viability.
The EU Ecodesign Directive's 2023 tiered efficiency requirements are mandating LED lighting, fan motor upgrades, and improved glazing specifications for all new refrigerated display case placements. German and French retail engineering teams are now specifying these standards as baseline procurement criteria. Heated display case categories face parallel thermal efficiency mandates under the same framework, compressing legacy resistance-element designs.
Buyers are unbundling after-sales service from equipment procurement, contracting directly with refrigeration service networks rather than accepting OEM-captive maintenance agreements. UK supermarket chains pioneered this shift, and the model is penetrating Nordic and Benelux markets. Independent service aggregators are capturing margin pools that previously accrued to original equipment manufacturers.
Food Display Cabinet Market Segmentation
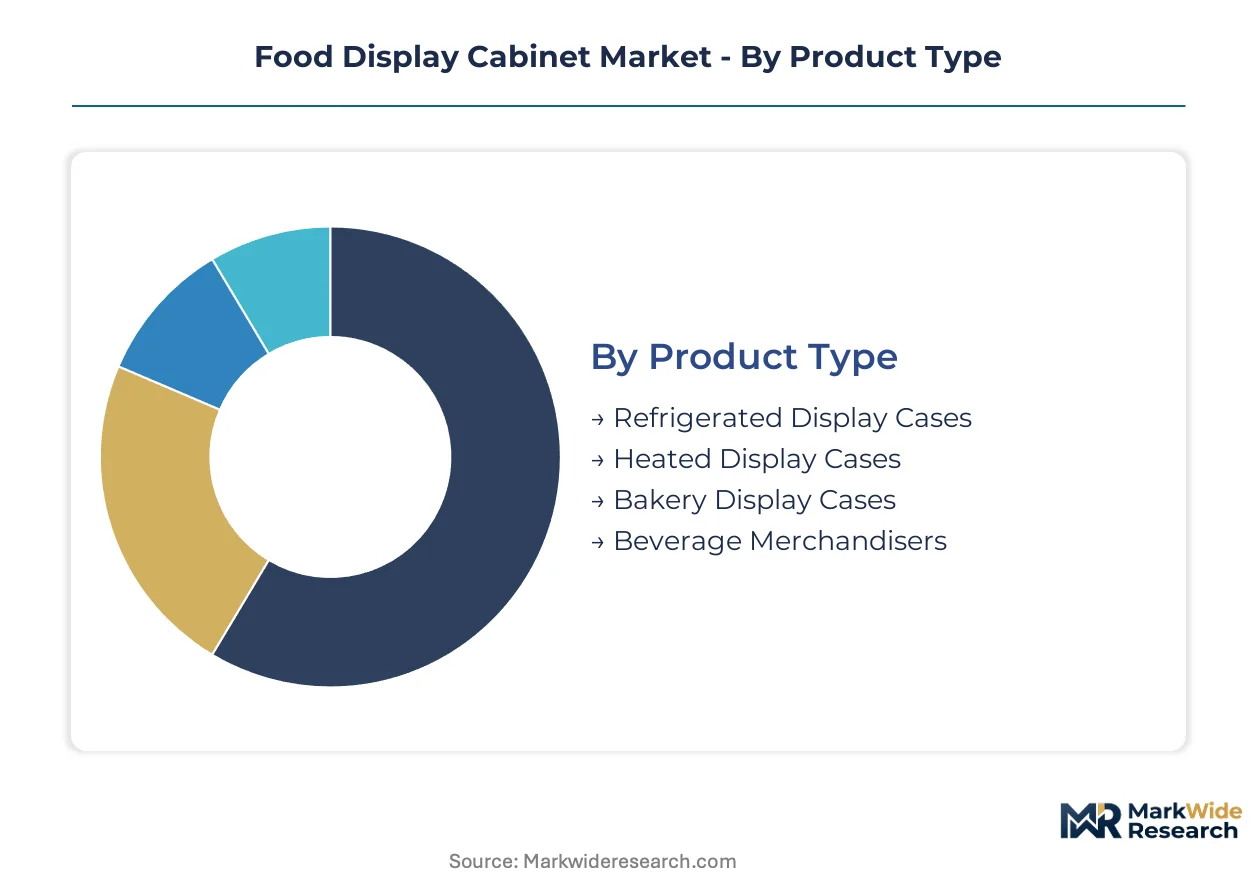
Food display cabinet procurement varies sharply by operational scale and thermal requirements. Specification committees balance energy compliance against renovation flexibility. Channel selection reflects whether buyers prioritize OEM technical support or third-party cost efficiency.
Product Type:
Standardization dominates entry-level refrigerated cases, while heated and bakery formats demand greater customization for menu-specific thermal profiles and aesthetic integration.
- Refrigerated Display Cases:Forced-air or gravity-coil systems maintain -18°C to +4°C zones for dairy, deli, and prepared foods. Supermarket chains in Germany and France are specifying CO2 transcritical architectures to meet EU F-Gas Regulation phaseout timelines.
- Heated Display Cases:Resistance-element or infrared warming systems sustain +65°C holding temperatures for rotisserie and grab-and-go hot items. Quick-service chains across Southeast Asia are scaling compact countertop units for prepared food visibility in high-temperature ambient conditions.
- Bakery Display Cases:Humidity-controlled enclosures with curved glass fronts preserve crust texture and visual appeal for artisan bread and pastry presentation.
- Beverage Merchandisers:Vertical or horizontal glass-door units optimize packout density for bottled and canned drinks in convenience-store formats.
Most installed capacity flows through Refrigerated Display Cases. Expansion is steepest in Heated Display Cases.
End User:
Volume concentrates with large-format retail, though margin pools favor smaller-footprint operators with limited technical staff and higher service dependency.
- Restaurants:Full-service and fast-casual operators deploy mixed-temperature lines for buffet and pass-through applications. China's tier-one cities are driving replacement cycles as local F&B operators upgrade to energy-compliant LED and fan-motor systems.
- Supermarkets:Multi-deck and island cases dominate perimeter departments with remote rack or integral compressor architectures. European chains are unbundling service contracts from equipment procurement, shifting aftermarket revenue to independent refrigeration networks.
- Convenience Stores:Grab-and-go chilled and heated units maximize transaction velocity in constrained floorplates.
- Coffee Shops:Pastry and beverage-forward cases emphasize countertop footprint reduction and front-of-house aesthetic integration.
Supermarkets anchor current installed base. Convenience stores are gaining share fastest.
Installation Type:
Retrofit-driven demand favors flexibility, while new-build food halls and supermarket ground-ups enable integrated architectural coordination.
- Stand-Alone Units:Self-contained plug-in systems with onboard compressors require no remote piping. Independent grocers in India are leveraging PLI-subsidized procurement to replace aging R-404A equipment with hydrocarbon alternatives.
- Integrated Units:Architecturally coordinated lines with shared refrigeration racks reduce energy intensity. Australian retail chains are piloting CO2 transcritical boosters in warm-climate configurations previously blocked by ambient heat rejection limits.
- Built-In Units:Flush-mounted enclosures merge with millwork for premium food hall and hotel buffet presentations.
- Countertop Models:Compact thermal enclosures maximize impulse purchase capture in space-constrained formats.
Stand-Alone Units carry the largest replacement volume. Integrated Units are climbing the fastest.
Distribution Channel:
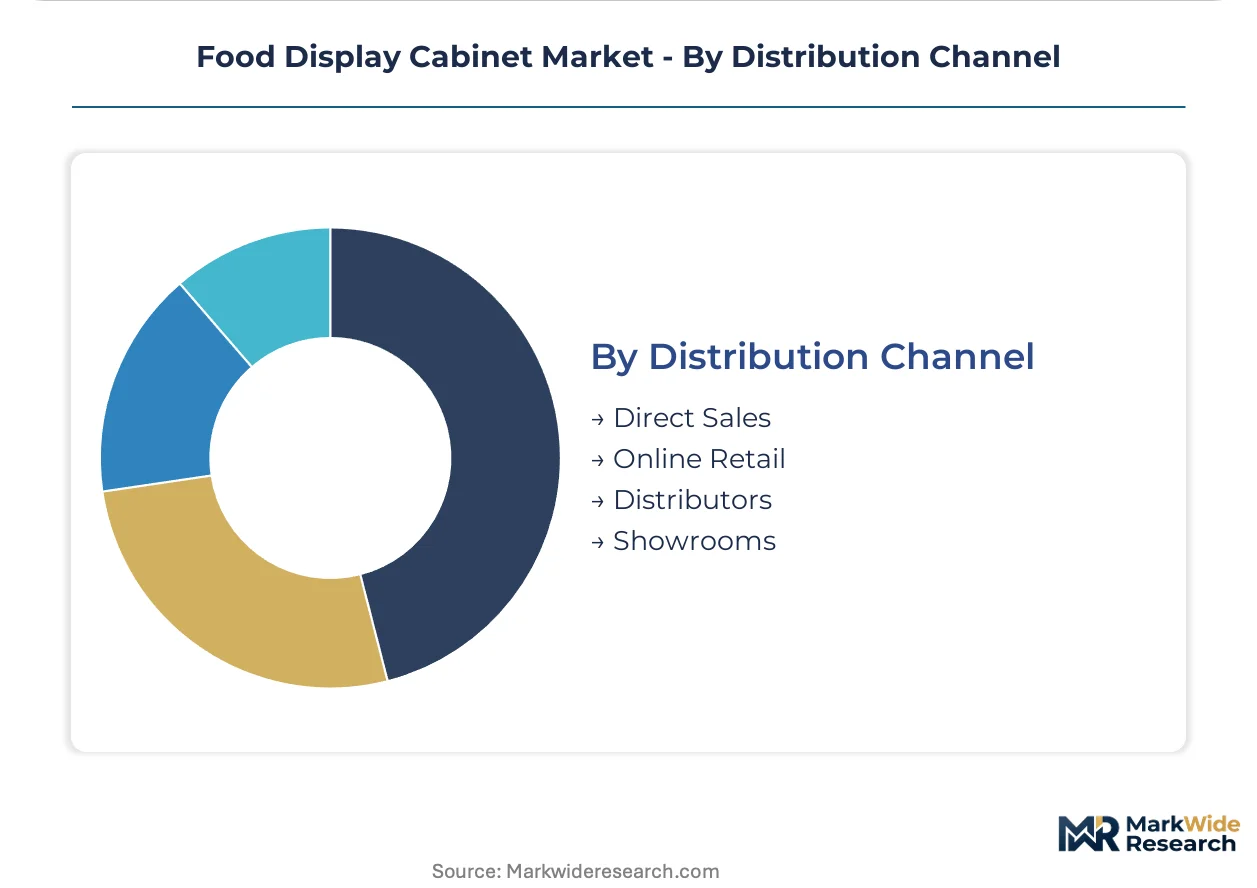
Direct relationships dominate complex multi-site rollouts, while distributors capture fragmented independent operator demand.
- Direct Sales:OEM field engineers coordinate specification, installation, and commissioning for chain accounts. UK supermarket engineering teams now contract directly with refrigeration service aggregators rather than accepting OEM-captive maintenance agreements.
- Distributors:Regional inventory and technical support networks serve mid-tier independent retail and foodservice. Japanese convenience-store operators are sourcing sensor-embedded cabinets with predictive maintenance capabilities through specialized refrigeration distributors.
- Online Retail:E-commerce platforms standardize specifications for smaller operators with limited procurement staff.
- Showrooms:Physical demonstration environments enable hands-on thermal performance and aesthetic evaluation before capital commitment.
Distributors move the highest unit volume. Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food display cabinet manufacturing originated in post-war American commercial kitchen equipment foundries, then migrated to Japanese precision metalworking centers and German refrigeration engineering clusters before proliferating across Asian contract fabrication hubs.
United States
Quick-service restaurant chains and supermarket operators drive replacement cycles for hydrocarbon-compatible equipment. The EPA SNAP program enforces HFC phaseout timelines that compress retrofit windows for independent grocers. Equipment specification concentrates in Chicago-area commercial kitchen manufacturing corridors and California's foodservice distribution clusters.
Germany
Supermarket engineering teams specify CO2 transcritical architectures for new-build and retrofit installations alike. The EU F-Gas Regulation's quota reductions force simultaneous compressor and insulation system redesigns. Industrial concentration sits in Baden-Württemberg's refrigeration component belt and North Rhine-Westphalia's retail fixture manufacturing zones.
China
Tier-one city convenience-store densification accelerates grab-and-go cabinet procurement in Shanghai, Beijing, and Shenzhen. GB standards impose parallel efficiency mandates that compress product launch timelines for domestic manufacturers. Yangtze River Delta fabrication clusters dominate stainless-steel enclosure production for both domestic deployment and export assembly.
Japan
Convenience-store networks deploy sensor-embedded cabinets with predictive maintenance capabilities to minimize unplanned downtime. METI's Top Runner program sets escalating efficiency benchmarks for commercial refrigeration equipment. Kanto region engineering groups coordinate specification standards across Tokyo-Osaka retail corridors.
India
Organized retail expansion and cold-chain modernization subsidized under the PLI scheme for food processing infrastructure stimulate refrigerated display investments. Independent grocers leverage subsidized procurement to replace aging R-404A equipment with hydrocarbon alternatives. Maharashtra and Gujarat host emerging fabrication capacity for domestic market supply.
Food Display Cabinet Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered vendor base where stainless-steel fabrication capacity anchors regional supply security. The market fragments across integrated refrigeration architects, standalone cabinet specialists, and component subsystem suppliers. Three archetypes dominate: full-system integrators commanding supermarket chain accounts, regional fabricators serving independent foodservice operators, and technology licensors extracting royalties from compressor and control module patents. Competitive intensity concentrates on geographic expansion into subsidized emerging markets and portfolio diversification beyond traditional refrigerated cases into heated and hybrid thermal formats.
Among North American equipment manufacturers, Carrier Global Corporation and True Manufacturing occupy positions spanning integrated system architecture and domestic fabrication capacity respectively. Japanese precision engineering is represented by Hoshizaki Corp, which exemplifies the component-to-system vertical specialist archetype. These three entities anchor distinct competitive vectors: transnational service network coverage, captive stainless-steel production, and precision refrigeration component integration.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Hoshizaki Corp |
| True Manufacturing |
| The Vollrath Co. LLC |
| The Middleby Corp |
| Hussmann |
| Hatco Corp |
| FRIGOGLASS S.A.I.C |
| Alto-Shaam |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between UL-marked premium systems and economy-tier domestic units manifests in both procurement premiums and supply chain sourcing patterns. Buyers in Germany and the United States pay substantial markups for EU F-Gas Regulation-compliant CO2 architectures, while Indian independent grocers source hydrocarbon-compatible cabinets through PLI-subsidized channels at compressed price points. This tiered structure concentrates margin capture with full-system integrators who control compressor technology licensing and captive service networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with differentiation driven by refrigerant architecture certification and after-sales service bundling. Premium CO2 transcritical systems command substantial procurement premiums in European supermarket chains, while economy-tier plug-in hydrocarbon units serve price-sensitive independent grocers in India. Pricing pressure stems from copper and aluminum commodity volatility compressing margin predictability for mid-tier fabricators. Convenience-store operators in China's tier-one cities demonstrate highest price sensitivity, whereas German supermarket engineering teams prioritize energy compliance over upfront capital expenditure.
Supply Chain Analysis
Skilled technician scarcity in hydrocarbon and CO2 system servicing constrains manufacturing scale-up in European and North American production corridors. Supply concentrates in China's Yangtze River Delta stainless-steel fabrication clusters, Germany's Baden-Württemberg refrigeration component belt, and emerging capacity in Maharashtra and Gujarat. Critical inputs include variable-speed compressor technology from Japanese and European OEMs, copper coil stock, and specialized glazing systems. Single-source vulnerability in compressor supply creates bottleneck risk for natural refrigerant system scaling. Distribution runs through direct OEM field engineering for chain accounts and regional distributor networks for fragmented independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food display cabinet procurement has shifted toward premium natural refrigerant specifications as EU F-Gas Regulation compliance deadlines compress retrofit windows. This late-cycle quality story favors manufacturers with certified CO2 and hydrocarbon architectures over legacy R-404A dependent suppliers.
For Market Incumbents: Hedge refrigerant-transition exposure by accelerating hydrocarbon and CO2 compressor system certification while maintaining R-404A service capacity for elongated replacement cycles. Carrier Global Corporation and Hussmann demonstrate defensive positioning through transnational service network coverage that captures aftermarket revenue independent of equipment sales. Compressor supply concentration represents the primary threat, warranting strategic partnerships with European and Japanese variable-speed technology licensors. For New Entrants and Emerging Players: Specialized refrigeration distributors in Japanese convenience-store networks offer channel access with lower capital barriers than direct OEM field engineering investment. White-space targets include AI-driven predictive maintenance sensor integration for Southeast Asian QSR chains and PLI-subsidized procurement channels for Indian organized retail expansion. The most penetrable segment comprises independent grocers in India requiring complete R-404A system replacement rather than drop-in conversion. For Investors and Strategic Acquirers: Asymmetric upside sits with component-to-system vertical specialists who control precision refrigeration engineering and captive stainless-steel fabrication capacity. Long-term viability across the analysis window hinges on natural refrigerant certification depth and service network density rather than unit manufacturing scale. Acquisition target archetype: mid-tier fabricators with GB standard approval and Yangtze River Delta production assets. The signal to watch is technician certification program output lagging hydrocarbon system deployment rates.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Certification Investment | EU F-Gas Regulation compliance deadlines force simultaneous compressor and insulation system redesigns across European supply chains. |
| Service Network Unbundling | UK supermarket chains now contract directly with independent refrigeration aggregators, shifting aftermarket margin pools from OEM captivity. |
| Predictive Maintenance Technology Integration | Sensor-embedded cabinets with machine-learning fault detection reduce unplanned downtime in Japanese convenience-store networks. |
| Backward Integration into Compressor Technology | European and Japanese OEM concentration in variable-speed systems creates strategic vulnerability for natural refrigerant scaling. |
| Geographic Manufacturing Footprint Expansion | India's PLI scheme subsidizes domestic fabrication capacity in Maharashtra and Gujarat for cold-chain modernization demand. |
Methodological Framework
Multiple input streams — regulatory filing analysis, trade customs data, and equipment shipment records — were reconciled against primary interviews with supermarket engineering directors, refrigeration service contractors, convenience-store procurement managers, and compressor OEM technical leads. Secondary validation drew from EPA SNAP program documentation, EU Ecodesign Directive implementing measures, China's GB standard publications, and METI Top Runner efficiency benchmarks. Bottom-up unit shipment modeling and top-down market value triangulation were cross-checked against disclosed capex patterns from major retail chains.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers to each product type, installation configuration, and end-user category. Modeled dimensions included refrigerant architecture, thermal application range, geographic regulatory cluster, and channel structure. CAGRs were derived from fitted trend analysis incorporating equipment replacement cycle timing, subsidy program phase-ins, and efficiency mandate compliance deadlines. Industry-specific forecast inputs captured CO2 transcritical system penetration curves and technician certification program expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant-phaseout timeline adjustments, commodity price volatility in copper and aluminum markets, and natural refrigerant technician training program throughput. Forecasts reflect documented assumptions about regulatory enforcement consistency and subsidy program continuity. Material deviation in EU F-Gas Regulation quota allocation or PLI scheme renewal terms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Countertop Ice Dispensers Market