
 South America Botanical Supplements Market | 2026-2036
South America Botanical Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
South America Botanical Supplements Market Analytics
ANVISA's updated botanical registration framework is realigning the cost-of-entry calculus for new supplement entrants in Brazil. Herbalife International of America Inc. leverages its direct-selling infrastructure to sustain market presence across multiple South American countries. Natulab Laboratório S/A anchors its competitive position through specialized manufacturing of standardized herbal extracts for domestic and export markets. GNC Holdings Inc. competes through controlled retail channel access in premium shopping districts of major Brazilian cities.
Botanical supplements comprise plant-derived preparations containing bioactive compounds extracted through solvent, steam distillation, or mechanical processing methods, standardized to specified marker compound concentrations for consistent physiological effect. These products serve commercial purposes spanning immune support, digestive health, cognitive function, and athletic recovery applications across consumer wellness and clinical nutrition contexts. Herbal extracts command the dominant value share due to higher per-unit pricing and established clinical validation pipelines, while essential oils capture expanding demand from aromatherapy crossover segments. Capsules and tablets together occupy the core form factor preference among health enthusiasts seeking precise dosing convenience, though liquid formats gain traction among herbalists favoring sublingual absorption profiles.
ANVISA in Brazil, INVIMA in Colombia, and DIGEMID in Peru collectively enforce GMP compliance, label accuracy verification, and controlled substance screening that determines which botanical species achieve commercial clearance. These regulatory bodies require stability testing data and toxicological assessments that extend product development timelines and favor established manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor pending harmonization initiatives across Mercosur member states that could unify registration standards and reshape competitive access patterns.
Market Dynamics
ANVISA's tightened botanical registration requirements in Brazil are forcing manufacturers to rebuild compliance infrastructure from the ground up, compressing margins for mid-tier players while erecting defensive moats around established operators with dedicated regulatory affairs teams.
Growth Catalysts
- Fitness sector expansion:Brazilian fitness professionals are integrating standardized herbal extracts into recovery protocols, creating sustained demand pull from São Paulo's health-conscious consumer clusters.
- Export market development:Colombian INVIMA's streamlined clearance pathways for Andean botanical species are enabling cross-border commercialization of regionally endemic plant preparations.
- Extraction technology advancement:Supercritical CO2 processing methods are improving marker compound consistency and extending shelf stability for heat-sensitive bioactives.
Market Restraints
- Raw material volatility:Climate-sensitive harvesting cycles for Amazonian Uncaria tomentosa and Paullinia cupana create input cost instability and supply intermittency.
- Regulatory friction:ANVISA's extended toxicological assessment timelines stretch product development cycles to 18-24 months, freezing capital in pre-revenue phases.
- Substitution pressure:Synthetic isolates of caffeine, theobromine, and polyphenols from pharmaceutical suppliers undercut whole-herb positioning on unit economics.
Strategic Opportunities
- Peruvian market penetration:DIGEMID's emerging GMP certification support programs are lowering compliance barriers for manufacturers targeting Lima's underserved wellness retail channels.
- Aromatherapy convergence:Essential oil crossover applications in spa and hospitality sectors are opening adjacent revenue streams beyond traditional supplement formats.
- Direct-to-consumer channels:Subscription-based replenishment models are bypassing pharmacy retail gatekeepers and capturing recurring revenue from chronic-condition users.
Industry Challenges
- Phytochemistry expertise scarcity:Qualified analytical chemists capable of HPLC marker compound validation command premium compensation, constraining quality control scaling.
- Legacy system integration:Batch record digitization for ANVISA traceability mandates requires capital outlays that fragment smaller manufacturers' technology investment priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Botanical Supplements Market |
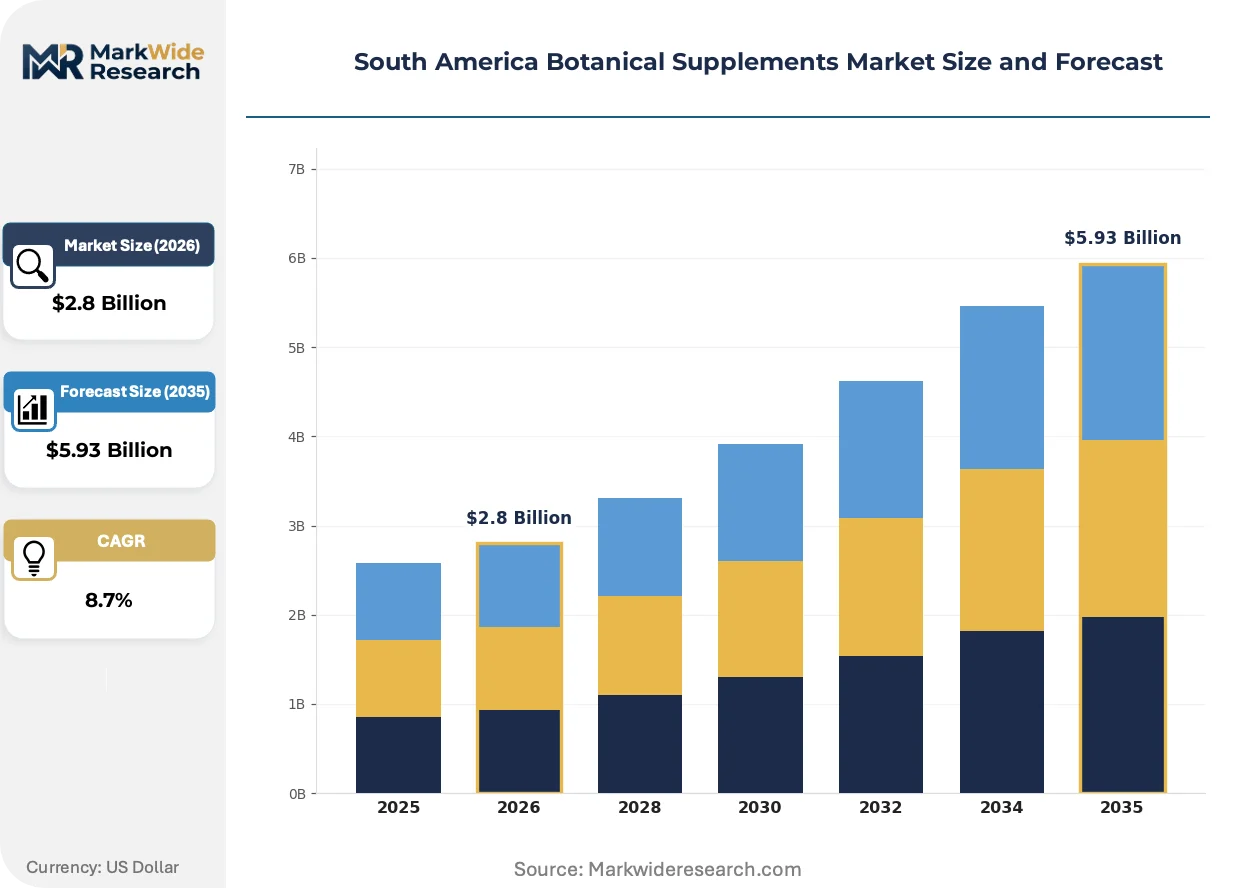
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Powdered Herbs, Tinctures Form: Capsules, Tablets, Liquid, Tea End User: Health Enthusiasts, Fitness Professionals, Herbalists, Retail Consumers Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | Amway International Inc., Herbalife International of America Inc., GNC Holdings Inc., Natulab Laboratório S/A, Now Health Group Inc., Nutraceutical International Corporation, Sanofi SA, The Nature's Bounty Co., The Clorox Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Botanical Supplements Market Evolving Landscape
Digital quality assurance systems and extraction automation are compressing production variance while regulatory data harmonization initiatives across Mercosur members promise to reshape cross-border competitive access.
Near-infrared spectroscopy coupled with machine learning algorithms is automating real-time potency verification during extraction workflows. Mid-sized Brazilian manufacturers are deploying these systems at pilot scale to reduce third-party laboratory testing dependencies. The technology is automating release decisions that previously required 72-hour external validation cycles.
ANVISA's 2023 updated botanical registration framework now mandates stability testing across three climate zones and toxicological screening for novel excipient combinations. The regulation is forcing reformulation investments estimated to absorb 8-15% of annual R&D budgets for domestic manufacturers. Companies with captive analytical laboratories are absorbing these requirements faster than contract manufacturers dependent on external testing queues.
Practitioner-channel purchasing is fragmenting as Brazilian nutritionists and herbalists consolidate buying through specialized B2B platforms offering lot-specific certificates of analysis. Traditional pharmaceutical distributors are losing share to these vertically specialized procurement networks in São Paulo and Rio de Janeiro metropolitan corridors. The shift is most visible among sports nutrition clinics seeking transparent supply chain documentation for liability protection.
South America Botanical Supplements Market Segmentation
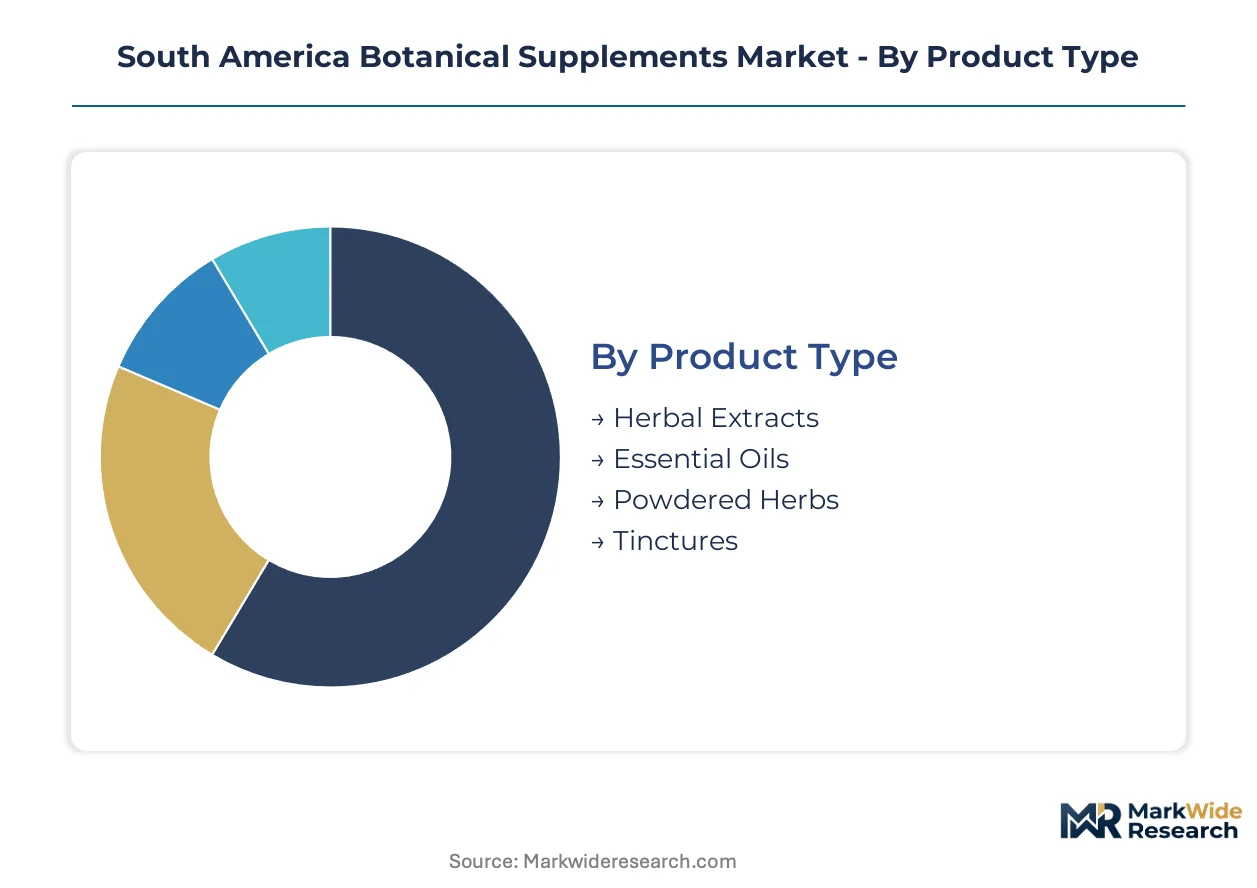
Botanical supplement segmentation in South America reflects divergent regulatory burdens across product formats and distribution pathways. ANVISA's tiered approval requirements create distinct cost-of-entry profiles that reshape competitive positioning by segment.
Product Type:
ANVISA mandates stability testing across three climate zones for herbal extracts and novel excipient combinations, while essential oils face lighter aromatherapy-aligned documentation.
- Herbal Extracts:Concentrated bioactive preparations standardized to specified marker compounds through solvent or supercritical CO2 processing. São Paulo's fitness professionals drive demand for recovery-focused formulations containing Uncaria tomentosa and Paullinia cupana, though climate-sensitive harvesting cycles create input instability.
- Essential Oils:Steam-distilled or cold-pressed volatile compounds capturing aromatic and therapeutic properties. Spa and hospitality sectors in Rio de Janeiro and Lima expand procurement for aromatherapy crossover applications, bypassing stringent supplement registration pathways.
- Powdered Herbs:Mechanically processed dried plant material retaining whole-herb phytochemical matrices.
- Tinctures:Alcohol or glycerin-based liquid extractions favoring sublingual absorption profiles among traditional herbalist communities.
Leading the category by volume: Herbal Extracts. Growing fastest: Essential Oils.
Form:
Manufacturing capital intensity varies sharply—tablet compression and capsule filling require GMP-certified cleanrooms, while liquid bottling accommodates smaller batch producers.
- Capsules:Gelatin or vegetable-based shells enabling precise unit dosing and masking bitter compounds. Brazil's Southeast region concentrates demand among health enthusiasts seeking convenience, with practitioner-channel platforms in São Paulo consolidating procurement through lot-specific certificate offerings.
- Liquid:Tinctures, syrups, and suspensions favoring rapid buccal absorption. Colombian herbalists and Brazilian nutritionists drive preference for transparent supply chain documentation, accelerating shift from pharmaceutical distributors to specialized B2B networks.
- Tablets:Compressed powders with binders and coatings for extended shelf stability.
- Tea:Traditional infusion preparations retaining cultural acceptance across Andean markets.
Capsules dominate current volume. Liquid formats gain share fastest among professional channels.
End User:
Purchasing authority fragmentation distinguishes institutional buyers seeking liability protection from individual consumers prioritizing accessibility.
- Fitness Professionals:Certified trainers and sports nutrition clinics integrating standardized extracts into recovery protocols. São Paulo's health-conscious consumer clusters sustain demand pull, with practitioners requiring batch-specific analytical documentation for professional insurance compliance.
- Herbalists:Traditional medicine practitioners favoring whole-herb preparations and sublingual delivery formats. Peruvian and Colombian markets retain stronger cultural penetration, though formal training scarcity constrains quality control scaling.
- Health Enthusiasts:Self-directed wellness consumers prioritizing convenience and brand trust.
- Retail Consumers:Mass-market purchasers responding to pharmacy and supermarket merchandising.
Fitness Professionals command premium pricing. Herbalists represent the steepest expansion trajectory as practitioner channels formalize.
Distribution Channel:
Channel selection determines regulatory touchpoint density—pharmacies face INVIMA and DIGEMID inspection schedules, while online platforms navigate evolving e-commerce labeling enforcement.
- Online Retail:Direct-to-consumer platforms and subscription replenishment models bypassing traditional gatekeepers. Brazilian manufacturers deploy these channels to capture recurring revenue from chronic-condition users, though ANVISA's traceability mandates complicate batch record digitization for smaller operators.
- Health Stores:Specialized retailers catering to informed consumers seeking practitioner-grade formulations. São Paulo and Rio de Janeiro metropolitan corridors witness fastest consolidation of vertically specialized procurement networks.
- Pharmacies:Regulated dispensaries requiring full registration documentation and pharmacist oversight.
- Supermarkets:Mass-market retail with limited SKU depth and price-competitive positioning.
Health Stores lead by volume. Online Retail climbs fastest as subscription models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives draw extract manufacturers to Amazonas state, concentrating supercritical CO2 processing capacity near raw material sources. This fiscal advantage reshapes where South American botanical supplement production locates.
Brazil
São Paulo's health-conscious consumer clusters sustain demand for standardized Uncaria tomentosa and Paullinia cupana formulations. ANVISA's 2023 stability testing mandates across three climate zones extend product development timelines. Southeast region manufacturers absorb compliance costs faster than contract operators dependent on external laboratory queues.
Colombia
Bogotá sports nutrition clinics drive procurement of Andean botanical preparations for recovery protocols. INVIMA's streamlined clearance pathways for endemic species enable cross-border commercialization of regionally unique plant extracts. Cundinamarca department hosts emerging extraction facilities serving domestic and export markets.
Peru
Lima wellness retail channels present penetration opportunities for GMP-certified manufacturers. DIGEMID's emerging certification support programs lower compliance barriers for new entrants. Coastal metropolitan corridors witness fastest consolidation of practitioner-channel procurement networks.
Argentina
Buenos Aires metropolitan herbalists sustain preference for tincture formats and whole-herb preparations. The country's national pharmaceutical regulator enforces label accuracy verification that matches Mercosur harmonization trajectories. Pampas region agricultural zones supply mechanically processed dried botanical inputs.
Chile
Santiago health enthusiasts concentrate demand for capsule and tablet convenience formats. The country's national pharmaceutical regulator maintains controlled substance screening protocols for psychoactive botanical species. Central Valley distribution infrastructure connects Andean harvesting zones to Pacific export corridors.
South America Botanical Supplements Market Competitive Landscape
Brazilian producers anchor one tier; Colombian and Peruvian specialists hold complementary positions in Andean botanical supply. The market structure favors established operators with captive regulatory affairs capabilities over mid-tier entrants facing margin compression. Three archetypes dominate: direct-selling networks with continental reach, domestic manufacturers with specialized extraction infrastructure, and controlled retail channel operators. Competitive moves concentrate on reformulation investments for compliance and practitioner-channel platform consolidation.
Among direct-selling specialists, Herbalife International of America Inc. and Amway International Inc. occupy positions leveraging continental infrastructure. Natulab Laboratório S/A represents the domestic manufacturing archetype with Brazilian S.A. structure. GNC Holdings Inc. anchors the controlled retail tier with premium shopping district presence. These entities exemplify how regulatory capability and channel access separate sustainable operators from capital-constrained competitors.
| Leading Market Players |
|---|
| Amway International Inc. |
| Herbalife International of America Inc. |
| GNC Holdings Inc. |
| Natulab Laboratório S/A |
| Now Health Group Inc. |
| Nutraceutical International Corporation |
| Sanofi SA |
| The Nature's Bounty Co. |
| The Clorox Company |
| Others |
Value Network & Pricing Analysis
ANVISA's three-climate-zone stability testing mandate gates both qualified supply and premium-tier pricing access, as manufacturers absorbing these compliance costs command pricing power over contract operators stuck in external laboratory queues.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with captive analytical laboratories and penalizes spot-market buyers facing 72-hour external validation cycles. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified domestic producers from mid-tier contract manufacturers and informal channel operators. Price differentiation hinges on certification grade and batch-specific analytical documentation. Pricing pressure stems from synthetic isolate substitution in caffeine and polyphenol segments. Retail consumers show highest price sensitivity; fitness professionals and practitioner channels accept premium positioning for liability protection.
Supply Chain Analysis
Local-content rules under ANVISA's updated framework reshape sourcing toward Brazilian Amazonas state extraction facilities and domestic tableting operations. Geographic supply concentrates in Brazil, Colombia, and Peru, with Manaus Free Trade Zone incentives anchoring supercritical CO2 processing capacity. Raw material dependencies include Uncaria tomentosa, Paullinia cupana, and Andean endemic species. Supply chain risk centers on climate-sensitive harvesting cycles creating input intermittency. Distribution runs through vertically specialized B2B procurement networks consolidating in São Paulo and Rio de Janeiro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where ANVISA's extended toxicological assessment timelines force capital-constrained mid-tier operators toward exit or acquisition.
For Market Incumbents: Deepen regulatory affairs capabilities to maintain defensive moats against emerging contract manufacturers. Invest in captive analytical laboratories to compress release decision cycles below external validation dependencies. Expand practitioner-channel platform control in São Paulo metropolitan corridors before specialized B2B networks consolidate procurement authority. For New Entrants and Emerging Players: Capture DIGEMID certification support program slots in Peru's Lima wellness retail channels before GMP compliance barriers rise. Target Colombian INVIMA streamlined clearance pathways for endemic Andean botanical species. Deploy subscription-based replenishment models to bypass pharmacy retail gatekeepers and secure recurring revenue traction. For Investors and Strategic Acquirers: ANVISA batch record digitization mandates is the leading indicator that technology-fragmented smaller manufacturers face forced exit or distressed sale scenarios. Five-to-ten year viability favors established operators with captive regulatory affairs teams and Amazonas state extraction infrastructure. Acquisition target archetype: mid-sized Brazilian manufacturers with pilot-scale near-infrared spectroscopy deployment and pending reformulation completion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Investment | ANVISA stability testing mandates absorb 8-15% of R&D budgets, favoring captive laboratory operators. |
| Practitioner Channel Consolidation | Lot-specific certificate platforms in São Paulo displace traditional pharmaceutical distributors. |
| Extraction Technology Automation | Near-infrared spectroscopy with machine learning reduces third-party laboratory dependencies. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass pharmacy gatekeepers for chronic-condition user segments. |
| Peruvian Market Certification Program | DIGEMID GMP support lowers compliance barriers for Lima wellness retail penetration. |
Research Methodology
Document review covered regulatory filings with ANVISA, INVIMA, and DIGEMID, complemented by interviews with extraction facility managers, regulatory affairs specialists, sports nutrition clinic procurement directors, and practitioner-channel platform operators. Secondary validation drew from customs trade data, pharmaceutical distributor inventory records, and Mercosur harmonization initiative documentation. Bottom-up demand modeling triangulated against top-down production capacity assessments across Amazonas, Cundinamarca, and coastal Peruvian manufacturing zones.
Value and volume projections across the analysis window applied segment-level growth rate derivation from historical registration clearance timelines and practitioner-channel adoption curves. Segmentation dimensions modeled include product type, form factor, end-user archetype, and distribution channel density. CAGRs emerged from regression analysis against regulatory event timelines and fitness sector expansion indicators. Forecast inputs incorporated supercritical CO2 processing capacity buildout and climate-sensitive harvesting cycle variability.
The model holds under sustained ANVISA enforcement intensity and stable Mercosur regulatory trajectories; deviation in harmonization timeline acceleration or synthetic isolate substitution rates would shift competitive access patterns. Forecasts reflect documented assumptions regarding practitioner-channel formalization speed and extraction technology deployment scale. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Nutraceutical Market
Nutritional Supplements
Flax Protein Powder Market
Nutritional Supplements
Red Ginseng Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Dysphagia Supplements Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Fucoidan Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Testosterone Booster Supplements Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Zinc Supplement Market