
 Nigeria Food Service Market | 2026-2036
Nigeria Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Food Service Market Insights
NAFDAC's mandatory food safety certification is decoupling informal street vendors from formal chain expansion. Eat & Go Limited leverages its centralized supply hub to sustain quality compliance across multiple outlets. Chicken Republic anchors its competitive edge through backward integration into poultry processing. Tantalizers PLC differentiates via localized menu engineering that navigates regional taste variations.
The Nigeria food service industry encompasses commercial preparation and sale of ready-to-eat meals through organized or semi-organized outlets, spanning cooking facilities with minimum 10-seat capacity or equivalent throughput. Its primary commercial purpose is converting agricultural commodities into prepared food experiences for time-constrained consumers outside domestic kitchens. Fast Food service type dominates transaction volume due to affordability and speed, while Delivery channel distribution is capturing the fastest growth as logistics networks densify in Lagos, Abuja, and Port Harcourt. Fine Dining remains a narrow margin pool concentrated in expatriate corridors and corporate entertainment budgets.
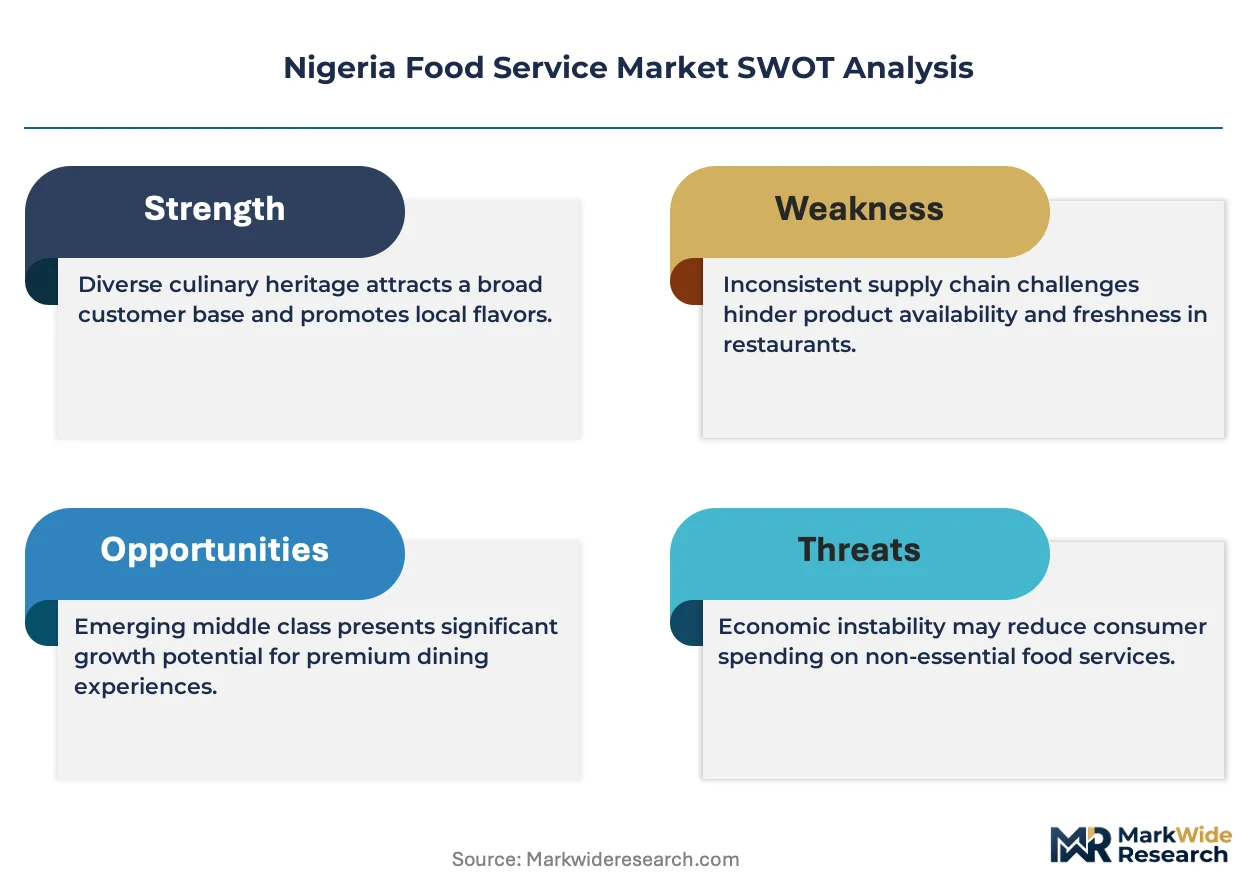
NAFDAC, SON, and state-level environmental health boards collectively shape market access through hygiene grading, packaging standards, and location permits. SON's mandatory product certification for imported kitchen equipment raises capital requirements for new entrants. Stakeholders must monitor how Lagos State's emerging carbonated beverage sugar tax signals broader nutrition-policy drift that could reshape menu engineering priorities.
Market Dynamics
NAFDAC's mandatory food safety certification is forcing a bifurcation between informal street vendors and formal chain operators. Lagos State's emerging sugar tax signals broader nutrition-policy drift that will reshape menu engineering priorities.
Growth Catalysts
- Urban workforce density:Quick-service restaurant adoption accelerates among time-constrained business workers in Lagos, Abuja, and Port Harcourt. Formal employment growth drives demand for standardized meal solutions outside domestic kitchens.
- NAFDAC certification mandate:Hygiene grading requirements elevate operational standards nationwide. Compliance creates competitive moats for organized operators with centralized supply infrastructure.
- Logistics network densification:Third-party delivery platforms expand last-mile coverage in major metropolitan clusters. Dark kitchen models proliferate where real estate costs prohibit dine-in expansion.
Market Restraints
- Imported equipment costs:SON's mandatory product certification for foreign kitchen equipment raises capital thresholds for new entrants. Domestic fabrication capacity remains underdeveloped for specialized appliances.
- Input price volatility:Poultry feed and cooking fuel costs fluctuate with naira exchange rate instability. Margin compression hits operators lacking backward integration into protein supply.
- Informal sector competition:Unlicensed street vendors avoid regulatory compliance costs and taxation. Price-sensitive consumers in peri-urban zones remain anchored to informal channels.
Strategic Opportunities
- Secondary city expansion:Ibadan, Kano, and Enugu exhibit underpenetrated organized food service density. First-mover operators capture nascent middle-class demand before competition intensifies.
- State-level environmental health boards:Emerging location permit standardization creates regulatory clarity for multi-outlet expansion. Operators with compliance infrastructure scale faster across state boundaries.
- Cloud kitchen convergence:Virtual brands and aggregator platform integration reduce real estate dependency. Technology-enabled demand forecasting optimizes production scheduling across distributed kitchens.
Industry Challenges
- Supply chain reconfiguration friction:Cold chain gaps between farmgate and urban processing centers cause protein spoilage. Operators must build captive logistics or accept quality inconsistency.
- Certification timeline compression:NAFDAC food handler permits and facility inspections create operational delays. New outlet openings face bureaucratic bottlenecks that extend cash runway requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Food Service Market |
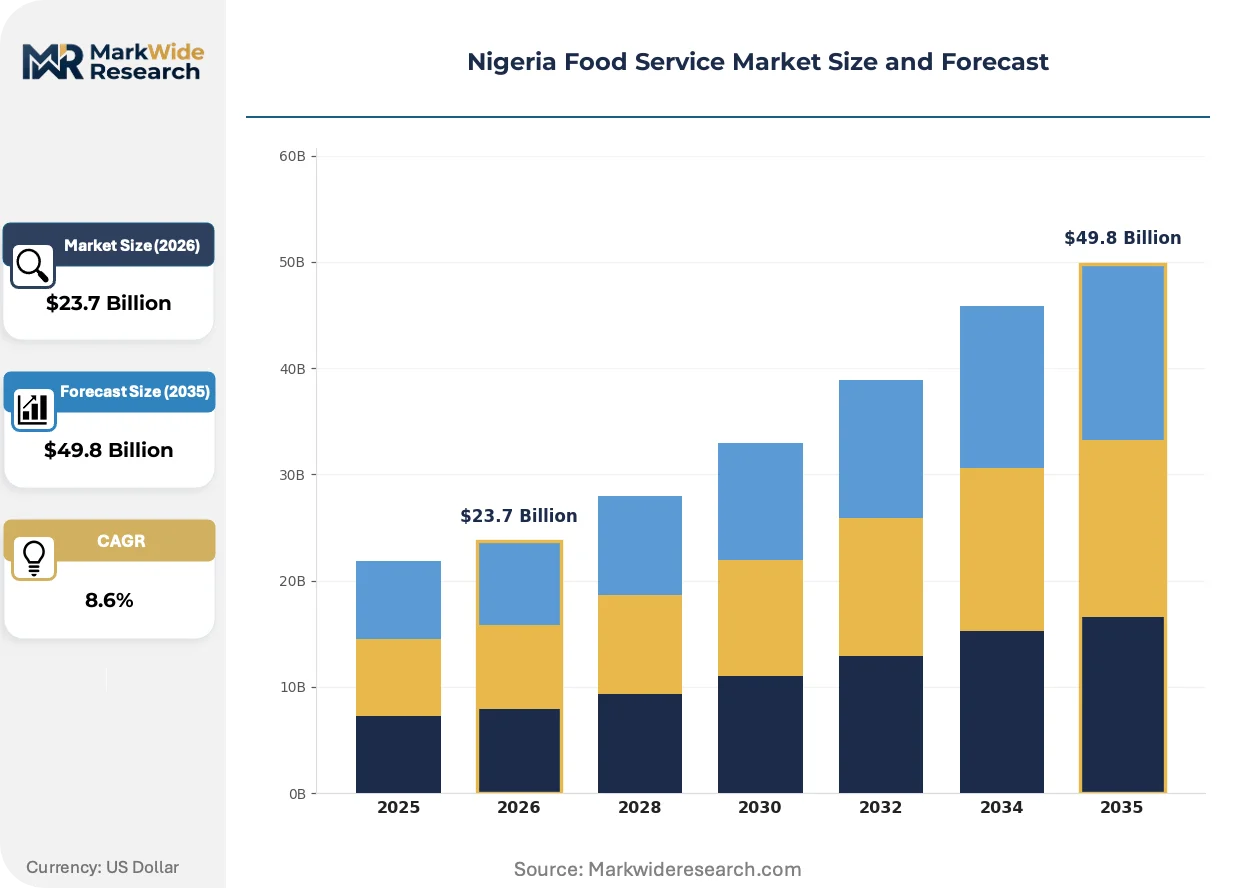
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Food, Casual Dining, Fine Dining, Cafes Customer Type: Families, Business Workers, Tourists, Students Distribution Channel: Dine-in, Takeaway, Delivery, Catering Menu Type: Local Cuisine, International Cuisine, Vegetarian, Fast Casual |
| Companies Covered | Eat & Go Limited, Marathon Restaurant Group, Chicken Republic, Devyani International (Nigeria) Limited, Tantalizers PLC, United Africa Company of Nigeria PLC, Sundry Foods Limited, Burger King Nigeria, Food Concepts PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Food Service Market Trends and Innovations
Digital ordering infrastructure and regulatory compliance technology are reshaping competitive positioning in Nigeria's food service sector. Three developments warrant particular attention from stakeholders.
Cloud-based point-of-sale systems with integrated inventory management are decentralizing operational control from central headquarters to individual outlet managers. Quick-service chains deploy tablet-based ordering interfaces that synchronize real-time stock levels with procurement triggers. This technology is decentralizing decision-making authority while maintaining brand consistency across dispersed locations.
NAFDAC's food safety certification framework is tightening traceability requirements for prepared food ingredients. Operators must document supplier credentials and batch records through digital audit trails. Full-service restaurants with complex supply webs face the steepest compliance burden, driving consolidation toward simplified menu architectures.
Aggregator platform subscriptions are compressing customer acquisition costs for delivery-native brands. Young professionals in Lagos Island and Victoria Island corridors increasingly bypass restaurant websites for consolidated app interfaces. This channel shift concentrates bargaining power with logistics platforms and commoditizes brand discovery.
Nigeria Food Service Market Segmentation
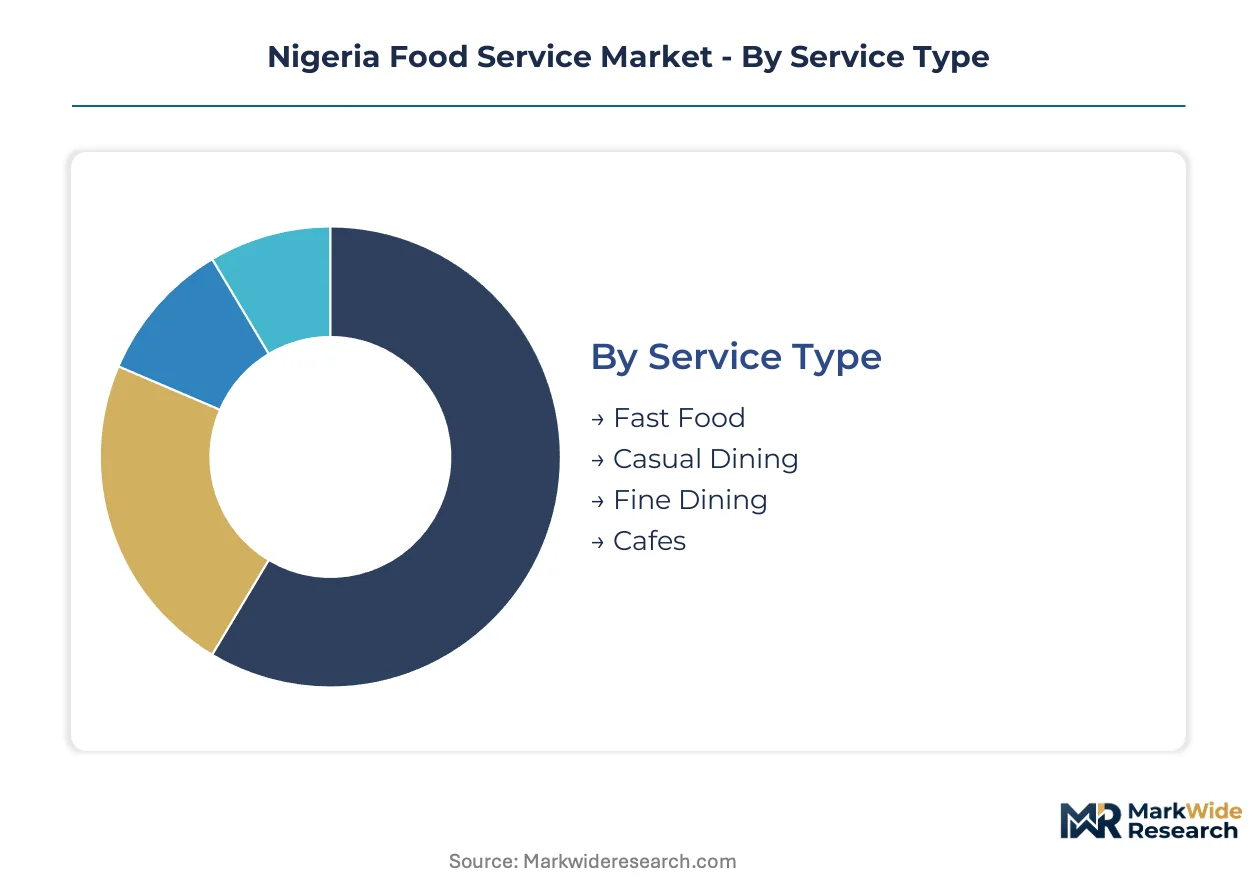
Nigeria's food service segmentation reflects divergent operational economics across service formats and customer cohorts. Service type determines capital intensity and regulatory exposure. Distribution channel selection shapes real estate strategy and technology infrastructure requirements.
Service Type:
Speed-to-serve and price-point positioning define competitive boundaries across formats.
- Fast Food:Standardized menus with sub-5-minute service cycles dominate transaction volume in Lagos and Abuja. NAFDAC compliance costs favor chains with centralized supply hubs over independent operators. Quick-service density concentrates along commercial corridors serving time-constrained business workers.
- Casual Dining:Full-service formats with moderate price elasticity attract family occasions and informal corporate gatherings. Ibadan and Port Harcourt show accelerating casual dining expansion as middle-class disposable income stabilizes. Menu localization requirements elevate operational complexity versus fast food standardization.
- Fine Dining:Premium formats target expatriate clusters and corporate entertainment budgets in Victoria Island and Ikoyi districts. High fixed costs limit viable addressable market to narrow geographic corridors.
- Cafes:Beverage-forward formats with limited hot food menus serve remote workers and informal meetings. Bakery-cafe hybrids gain traction in Abuja's emerging co-working districts.
Mature deployment sits with Fast Food. Newer deployment is concentrated in Casual Dining.
Customer Type:
Meal occasion and payment authority segment demand patterns across urban Nigeria.
- Business Workers:Formal employment clusters in Lagos Island, Victoria Island, and Abuja Central Business District drive weekday lunch demand. Expense account eligibility separates premium formats from self-funded meal decisions.
- Families:Weekend and celebration dining concentrates in casual dining and fast food formats. Multi-generational decision-making favors menu breadth over specialization.
- Tourists:Transient demand concentrates in airport corridors, hotel districts, and heritage sites. Currency volatility affects international visitor volume unpredictability.
- Students:Price-sensitive cohort anchors informal sector competition near university clusters in Ife, Zaria, and Nsukka. Aggregator platform discounts capture this segment disproportionately.
Volume concentration favors Business Workers. Margin expansion potential sits with Families.
Distribution Channel:
Channel selection determines real estate economics and labor model configuration.
- Delivery:Third-party platform integration enables asset-light expansion without dine-in real estate. Dark kitchen models proliferate in Lagos where rent per square meter prohibits traditional storefronts. Aggregator commission structures compress net margins below 15 percent for pure-play delivery brands.
- Dine-in:Experience-driven occasions sustain premium pricing power in Fine Dining and Casual Dining segments. Location permits from state environmental health boards create regulatory moats for established operators.
- Takeaway:Counter-service formats with minimal seating reduce square footage requirements. Packaging compliance with NAFDAC material safety standards adds per-unit cost.
- Catering:B2B contract catering serves corporate campuses and institutional clients. Volume predictability offsets lower per-meal margins.
Delivery represents the fastest-growing trajectory. Dine-in retains the highest revenue per transaction.
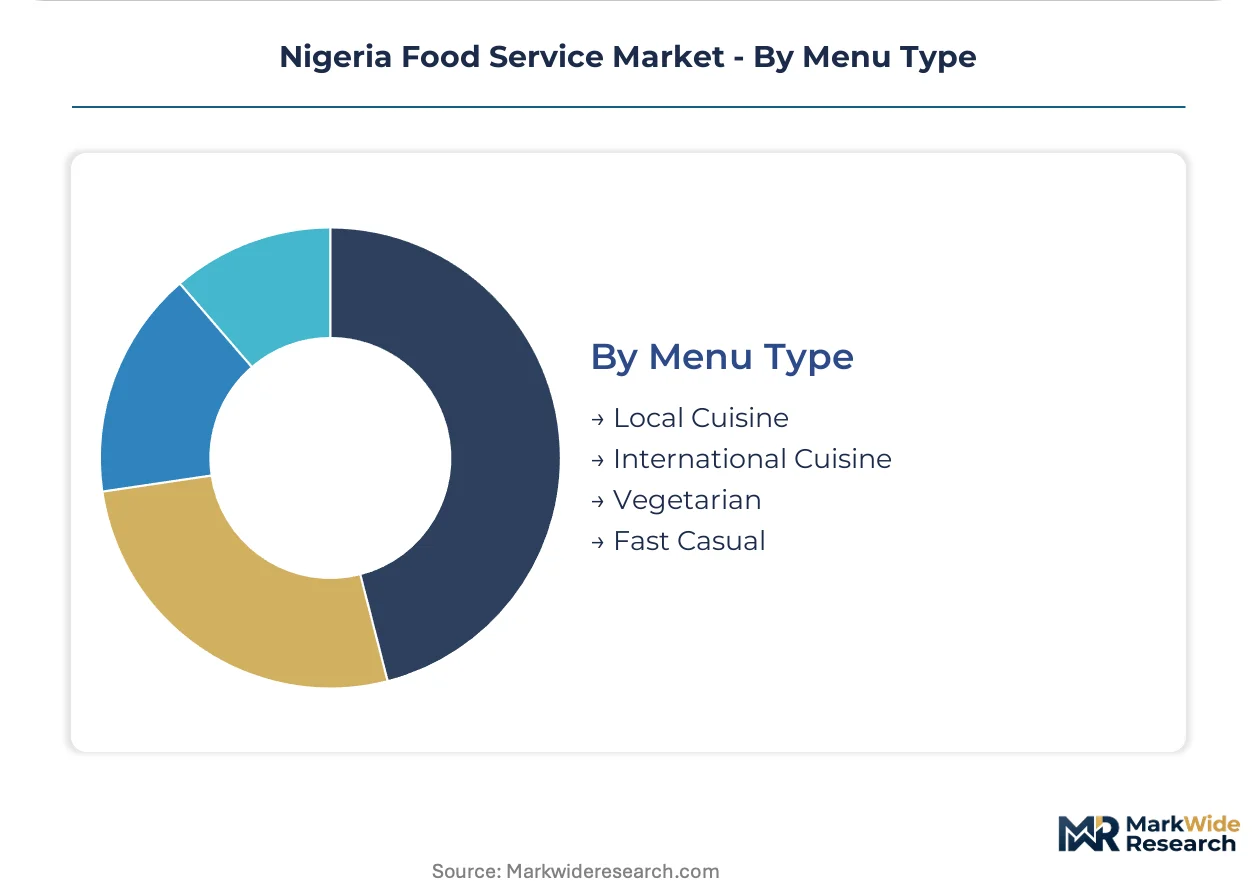
Menu Type:
Ingredient sourcing complexity and kitchen equipment requirements vary sharply across cuisine categories.
- Local Cuisine:Jollof rice, suya, and pepper soup variants dominate volume in all geographic zones. Backward integration into poultry and spice supply chains differentiates quality consistency.
- International Cuisine:Chinese, Lebanese, and Italian formats concentrate in expatriate corridors. Imported ingredient dependency exposes margins to naira exchange rate volatility.
- Vegetarian:Limited standalone demand; predominantly accommodated as menu modifiers. Religious dietary requirements in northern states create localized opportunity clusters.
- Fast Casual:Hybrid formats combining speed with customization attract health-conscious professionals. Build-your-own bowl concepts expand in Lagos fitness-oriented districts.
Local Cuisine commands volume leadership. Fast Casual exhibits the steepest expansion trajectory among emerging formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos State's Lekki Free Trade Zone concentrates quick-service restaurant investment through tax holidays and streamlined NAFDAC pre-certification. This special economic zone structure accelerates formal chain expansion while informal vendors operate outside its perimeter.
Lagos State
Urban workforce density along Lagos Island and Victoria Island corridors drives quick-service restaurant demand among time-constrained financial sector employees. NAFDAC's mandatory food handler permits and facility hygiene grading apply most stringently here, elevating compliance costs for new entrants. The Lekki-Epe axis hosts the densest concentration of cloud kitchen facilities and aggregator platform dark stores.
Federal Capital Territory
Abuja's Central Business District and emerging district centers generate weekday lunch demand from federal civil servants and diplomatic missions. State-level environmental health boards coordinate with NAFDAC on location permit standardization, reducing regulatory friction for multi-outlet operators. The Jabi and Wuse districts show accelerating casual dining expansion as middle-class residential clusters densify.
Rivers State
Port Harcourt's oil and gas sector employment sustains premium-format demand in corporate entertainment segments. SON's mandatory product certification for imported kitchen equipment raises capital thresholds, favoring established operators with existing supply relationships. The Trans Amadi industrial zone supports catering contracts for institutional clients including energy sector campuses.
Oyo State
Ibadan's underpenetrated organized food service density offers first-mover opportunity before competition intensifies. Federal and state tax incentive programs for agricultural processing create upstream advantages for operators integrating into poultry supply chains. The Ring Road and Bodija commercial corridors concentrate emerging fast-casual concepts targeting university-adjacent professionals.
Kano State
Northern Nigeria's commercial hub exhibits localized demand for religious dietary-compliant menu engineering. State environmental health boards apply NAFDAC frameworks with regional adaptation for halal certification requirements. The Sabon Gari district and emerging suburban centers show nascent quick-service adoption among formal trade sector employees.
Nigeria Food Service Market Competitive Landscape
Lagos-based operators anchor the premium tier; Port Harcourt and Abuja specialists hold regional strongholds. Market structure shows moderate consolidation around vertically integrated poultry processors and centralized supply hub operators, with fragmentation persisting among single-location casual dining concepts. Three archetypes dominate: backward-integrated protein suppliers, aggregator-platform-native delivery brands, and compliance-heavy formal chains with multi-state permits. Competitive moves concentrate on secondary city pre-emption and cloud kitchen asset-light expansion.
Within the integrated supply tier, Chicken Republic and Food Concepts PLC exemplify operators with captive poultry processing infrastructure. Eat & Go Limited occupies a position among centralized supply hub operators sustaining quality compliance across dispersed outlets. Tantalizers PLC represents the menu localization archetype, navigating regional taste variations through engineered product portfolios. These three companies illustrate how regulatory compliance infrastructure and supply chain control separate formal chain expansion from informal sector competition.
| Leading Market Players |
|---|
| Eat & Go Limited |
| Marathon Restaurant Group |
| Chicken Republic |
| Devyani International (Nigeria) Limited |
| Tantalizers PLC |
| United Africa Company of Nigeria PLC |
| Sundry Foods Limited |
| Burger King Nigeria |
| Food Concepts PLC |
| Others |
Pricing and Supply Chain Analysis
Backward integration into poultry processing anchors supply position and pricing power for organized chains navigating NAFDAC certification costs. Captive protein supply insulates margin structures from naira volatility while compliance infrastructure creates tiered access barriers.
Pricing Analysis
Short lead-time premiums attach to aggregator platform orders where dark kitchen proximity compresses fulfillment windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and brand recognition. Pricing pressure stems from informal vendor competition in peri-urban zones where regulatory evasion undercuts compliant operators. Students and price-sensitive families anchor economy tier demand; corporate entertainment budgets absorb premium positioning.
Supply Chain Analysis
Returns and spoilage flows from cold chain gaps between farmgate and urban processing centers force inventory write-downs that propagate into spot pricing volatility. Domestic poultry supply concentrates in Oyo and Kaduna agricultural zones. Imported kitchen equipment draws from China, Italy, and Turkey. Single-source vulnerability sits with specialized refrigeration compressors subject to SON certification delays. Distribution runs through centralized supply hubs feeding multi-outlet networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAFDAC food handler certification capacity constraints prop pricing power for compliant operators while bottlenecking informal sector expansion. Cold chain infrastructure scarcity amplifies spoilage costs that selective players capture as margin.
For Market Incumbents: Deepen backward integration into poultry feed and processing to offset exchange rate exposure on imported protein. Expand cloud kitchen footprints in Lagos Lekki-Epe corridor before real estate costs preclude entry. Certification infrastructure investment defends against aggregator platform disintermediation threatening brand discovery. For New Entrants and Emerging Players: Begin with secondary city fast-casual positioning in Ibadan or Enugu where organized density remains thin and location permit standardization is emerging. Cloud-native delivery brands bypass dine-in capital intensity. Partner with third-party logistics platforms for last-mile coverage rather than captive fleet investment. For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated poultry processors with multi-state permit infrastructure. Five-to-ten year viability hinges on regulatory compliance scalability rather than format innovation. Monitor Lagos State sugar tax implementation breadth as signal for nutrition-policy drift reshaping menu engineering returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Poultry Supply | Captive processing insulates margins from naira volatility and feed cost spikes. |
| Cloud Kitchen Network Expansion | Dark kitchen models circumvent Lekki-Victoria Island rent premiums while capturing delivery growth. |
| NAFDAC Certification Infrastructure | Pre-certified facility templates accelerate multi-state rollout timelines. |
| Aggregator Platform Partnership | Consolidated app interfaces concentrate customer acquisition for delivery-native brands. |
| Secondary City Pre-emption | First-mover positioning in Ibadan and Kano captures nascent middle-class demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Nigeria food service analysis. Primary interviews with quick-service chain operations directors, NAFDAC compliance officers, state environmental health inspectors, and aggregator platform logistics managers cross-validated operational assumptions. NAFDAC facility inspection databases, SON product certification registries, and Lagos State revenue service tax filings supplied bottom-up outlet counts. Top-down expenditure estimates triangulated against national accounts household consumption data.
Granularity-level modeling deployed outlet-level capacity assumptions for Lagos, Abuja, and Port Harcourt metropolitan clusters. Service type segmentation by fast food, casual dining, fine dining, and cafe formats combined with distribution channel splits across delivery, dine-in, takeaway, and catering. Menu type variation by local cuisine, international cuisine, vegetarian, and fast casual categories informed ingredient cost projections. CAGRs derived from urban workforce growth trajectories and disposable income elasticity estimates. Poultry feed price indices and naira exchange rate scenarios fed margin compression sensitivity analysis.
Underlying measurement precision varies by segment; fast food transaction volume carries tighter precision than fine dining corporate entertainment estimates. Forecasts reflect assumptions about NAFDAC certification timeline standardization and cold chain infrastructure buildout pace. Practitioners should monitor Lagos State sugar tax enforcement scope and aggregator platform commission structure changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Portion Cups Market
Food Service
Switzerland Food Service Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Air Fryer Meal Kits Market
Food Service
North America Online Food Delivery Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Self-Heating Hot Pot Market
Food Service
Personal Chef Services Market
Food Service
Food Trucks Market
Food Service
United States Cafes & Bars Market
Food Service
Mobile Food Services Market
Food Service
Smart Food Logistics Market
Food Service
Restaurant Griddle Market
Food Service
Street Vendors Market
Food Service
Global Meal Kit Market
Food Service
Food Service Market