
 Light Meal Market | 2026-2036
Light Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Light Meal Market Insights
Cloud kitchen infrastructure and third-party delivery platforms are reshaping how light meals reach consumers. Wagas leverages its premium salad and bowl-focused store network to sustain brand positioning in Shanghai and Beijing. Luckin Coffee competes through dense pickup-point logistics that anchor its grab-and-go meal assortment alongside beverages. DaChan Food (Asia) dominates chilled prepared protein supply, giving it upstream control over ingredient streams for multiple downstream brands.
Light meals comprise prepared food offerings with balanced macronutrient profiles, typically containing 300-600 calories per serving, designed for consumption within 15-20 minutes without full table service. These products employ cold-chain preservation, sous-vide protein preparation, or fresh assembly to maintain texture and safety across retail and foodservice channels. The bowls segment leads in average transaction value and margin contribution, while wraps and sandwiches occupy mature, price-competitive positions in supermarkets and convenience stores. E-commerce distribution channels represent the fastest-growing access point, though restaurants still capture the largest share of health-conscious consumer spending.
China's SAMR enforces nutrition labeling and food additive standards that dictate formulation choices for domestic manufacturers. The EU's F-Gas Regulation and REACH chemical frameworks affect packaging material selection for any brand exporting to Europe. Stakeholders must monitor how China's dual carbon goals and evolving GB standards for prepared foods will alter energy use and waste requirements across production networks.
Market Dynamics
Cloud kitchen infrastructure and third-party delivery platforms are compressing traditional restaurant real estate requirements while expanding addressable demand for prepared light meals in dense urban corridors.
Growth Catalysts
- Cold-chain logistics maturation:Refrigerated last-mile networks in China now sustain protein freshness for 72-hour delivery windows, unlocking subscription meal penetration in tier-one cities.
- SAMR nutrition labeling mandates:China's 2024 disclosure requirements for sodium and added sugar content are forcing formulation transparency that health-conscious consumers reward with repeat purchases.
- Workplace dining program expansion:Corporate cafeterias in Shanghai and Beijing are replacing traditional buffet lines with pre-portioned bowl stations to reduce food waste and labor costs.
Market Restraints
- Chilled protein input volatility:DaChan Food and two other suppliers control 60% of China's prepared poultry supply, creating margin pressure when feed grain prices spike.
- EU F-Gas Regulation compliance:Export-oriented brands must reformulate packaging adhesives and refrigeration equipment to meet REACH chemical restrictions, adding 8-12% to unit costs.
- Fresh assembly labor intensity:Bowl customization requires trained kitchen staff that command 40% wage premiums over fast-food assembly lines in tier-one cities.
Strategic Opportunities
- China's dual carbon goals:National MEE directives on food waste reduction are subsidizing compostable bowl packaging, creating first-mover advantage for biodegradable material adopters.
- Convenience store channel underpenetration:7-Eleven and FamilyMart in Japan demonstrate 24-hour fresh meal turnover that Chinese chains have yet to replicate in secondary cities.
- Sous-vide and high-pressure processing convergence:Combining these preservation methods extends refrigerated shelf life to 21 days without texture degradation, opening pharmacy and gym retail placement.
Industry Challenges
- Food safety certification timelines:China's GB standards for prepared foods require 14-month approval cycles for new protein suppliers, delaying menu innovation.
- Legacy POS integration friction:Cloud kitchen operators struggle to reconcile third-party delivery order flows with inventory management systems designed for dine-in service.
- Recipe IP enforcement gaps:Bowl concept copying accelerates when proprietary sauce formulations lack patent protection under Chinese trade secret law.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Meal Market |
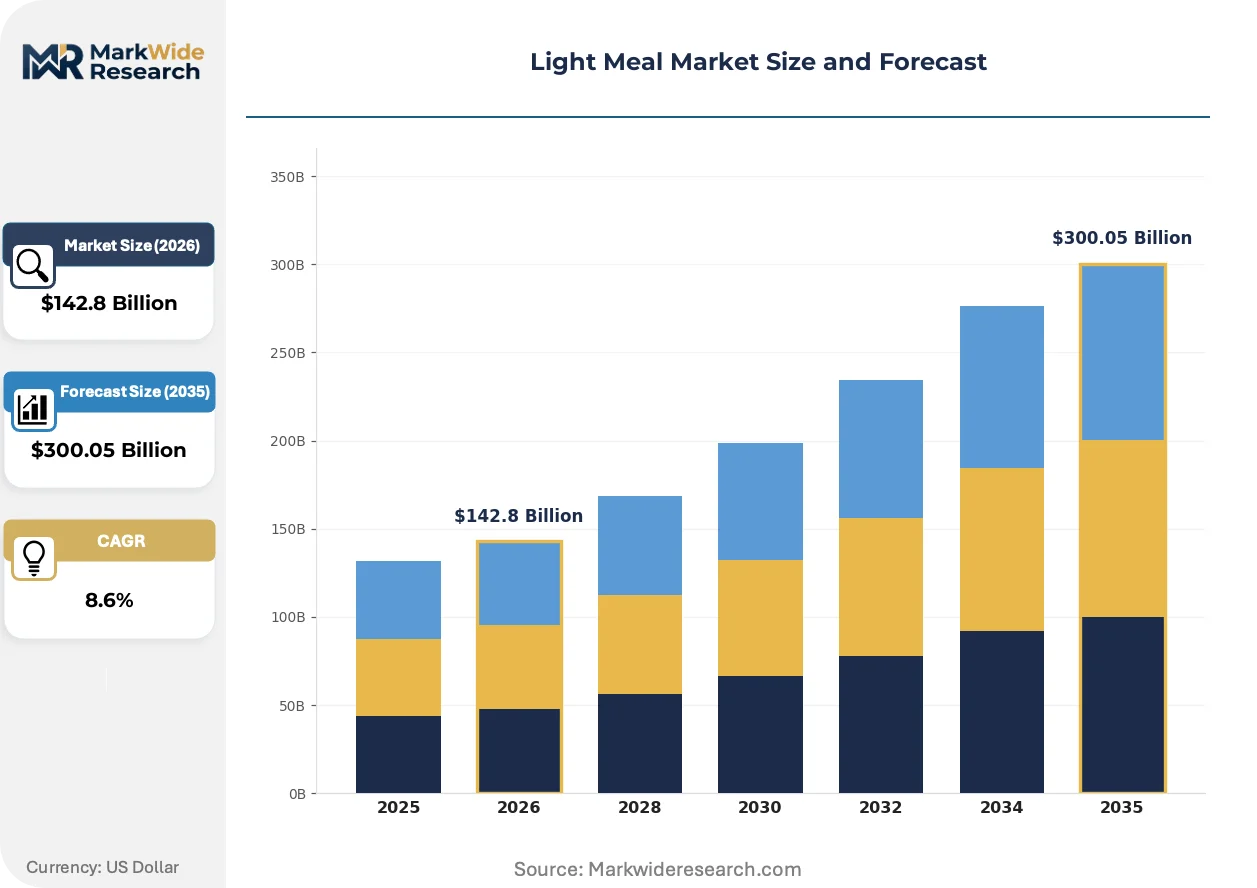
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $300.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salads, Wraps, Sandwiches, Bowls End User: Busy Professionals, Students, Health-Conscious Consumers, Families Distribution Channel: Supermarkets, Restaurants, Food Trucks, E-commerce Serving Size: Single-Serve, Family Pack, Snack Size, Shareable |
| Companies Covered | Wagas, Element Fresh, Shenzhen Xianyu Restaurant Management, Shenzhen Yuyangmeichu Network Technology, Luckin Coffee, DaChan Food (Asia), Shanghai Shaye Light Food, Nanjing Super Deer Team Catering Management, Guangzhou Juzongli Network Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Meal Market Trends and Innovations
Active protein preservation technologies and regulatory disclosure mandates are restructuring how light meals are formulated, labeled, and distributed across retail and foodservice channels.
Sous-vide cooking combined with modified atmosphere packaging is hybridizing traditional fresh assembly with extended shelf-life logistics. Premium workplace caterers in Beijing and Shanghai are adopting these systems to pre-position meals in office micro-kitchens. The technology is compressing the freshness gap between restaurant-prepared and retail-packaged offerings.
China's SAMR enforcement of GB 28050 nutrition labeling standards is mandating front-of-pack calorie and macronutrient disclosure for all prepared foods sold through e-commerce channels. Domestic manufacturers are reformulating sauces and grain bases to hit clean-label thresholds that attract health-conscious urban professionals. Bowl and salad specialists face the steepest compliance burden given their complex multi-ingredient assemblies.
Urban consumption patterns are fragmenting meal occasions into smaller, more frequent eating events that bypass traditional lunch and dinner peaks. Convenience stores in Japan and South Korea now capture 23% of light meal occasions through grab-and-go chilled sections that Chinese retailers are replicating. This rotation is most visible in Shanghai, where 24-hour fitness centers and co-working spaces have become primary distribution points for protein-focused evening meals.
Light Meal Market Segmentation
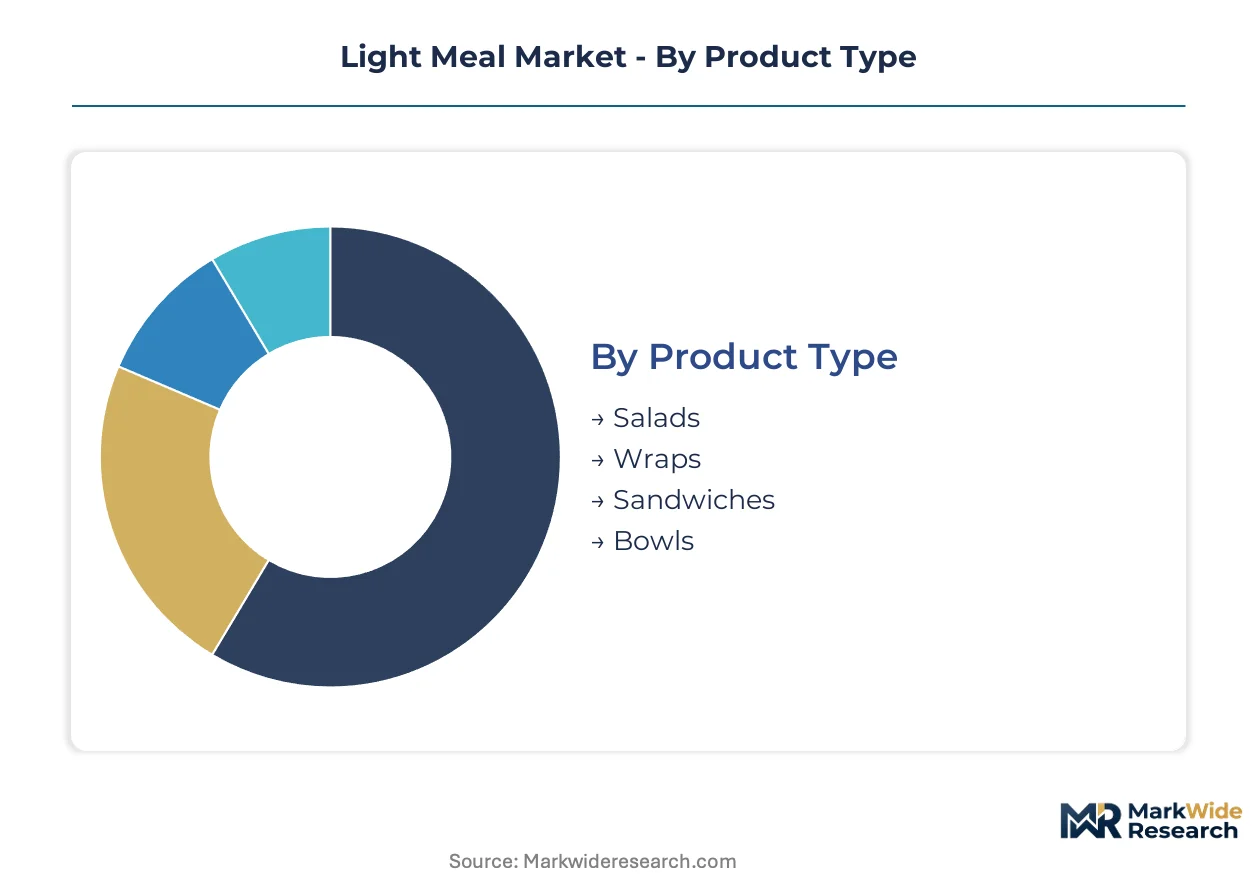
Segmentation in the light meal market reveals how consumption occasions, preparation methods, and purchase contexts fragment demand across distinct operational models. Each category carries different margin profiles, cold-chain requirements, and repeat purchase frequencies that shape supplier strategy.
Product Type:
After-sales service intensity varies sharply across product formats, with bowl concepts requiring ongoing menu engineering support while wraps demand minimal post-launch intervention.
- Bowls:Layered assemblies of grains, proteins, and vegetables that permit extensive customization through proprietary sauce systems. Demand concentrates in Shanghai and Beijing workplace dining programs where corporate clients negotiate quarterly menu rotations to sustain employee engagement.
- Salads:Cold-chain dependent offerings emphasizing raw vegetable preservation and protein topping freshness. Wagas and premium competitors anchor positioning in Shanghai's central business district towers where health-conscious professionals prioritize macronutrient transparency.
- Wraps:Portable folded formats with standardized filling combinations suited to convenience store distribution.
- Sandwiches:Mature category with established supply chains and compressed innovation cycles in supermarket channels.
By volume, sandwiches lead. By growth pace, bowls are expanding most quickly.
End User:
Cost tier stratification separates occasional premium purchasers from routine value buyers across urban consumption corridors.
- Busy Professionals:Time-constrained office workers seeking 15-minute consumption windows without table service. Corporate cafeteria contracts in Beijing and Shanghai drive bulk procurement with strict sodium and calorie specifications under SAMR disclosure mandates.
- Health-Conscious Consumers:Macronutrient-tracking individuals prioritizing protein density and clean-label ingredient lists. Subscription meal services in tier-one cities capture this cohort through weekly delivery cycles with nutritionist-curated rotations.
- Students:Price-sensitive segment concentrated near university clusters with high price elasticity.
- Families:Multi-person household purchasers favoring shareable formats for weekend convenience.
By transaction frequency, busy professionals lead. By willingness to pay premium prices, health-conscious consumers are ahead.
Distribution Channel:
Volume concentration in restaurants contrasts with margin expansion potential in emerging digital channels.
- E-commerce:Direct-to-consumer platforms and third-party delivery aggregators enabling subscription-based meal planning. Luckin Coffee's dense pickup-point network demonstrates how logistics density anchors grab-and-go assortment penetration in urban corridors.
- Restaurants:Dine-in and quick-service formats capturing the largest share of health-conscious consumer spending through experience-based positioning.
- Supermarkets:Chilled prepared sections with standardized SKUs and compressed shelf-life requirements.
- Food Trucks:Mobile preparation units serving event-based and construction-site demand with limited cold-chain infrastructure.
By current revenue share, restaurants lead. By expansion trajectory, e-commerce is gaining share fastest.
Serving Size:
Supply concentration in single-serve formats reflects manufacturing scale economies, while family packs require distinct production scheduling.
- Single-Serve:Individual portions designed for solo consumption during work hours or commutes. Cloud kitchen operators optimize production around this format to minimize waste and maximize throughput in dense urban delivery zones.
- Snack Size:Sub-300 calorie offerings targeting between-meal occasions and fitness-adjacent consumption. 24-hour gym retail placements in Shanghai demonstrate channel experimentation with refrigerated protein-focused evening meals.
- Family Pack:Multi-portion containers for household sharing with extended shelf-life requirements.
- Shareable:Large-format presentations for office meetings and social gatherings with presentation-focused packaging.
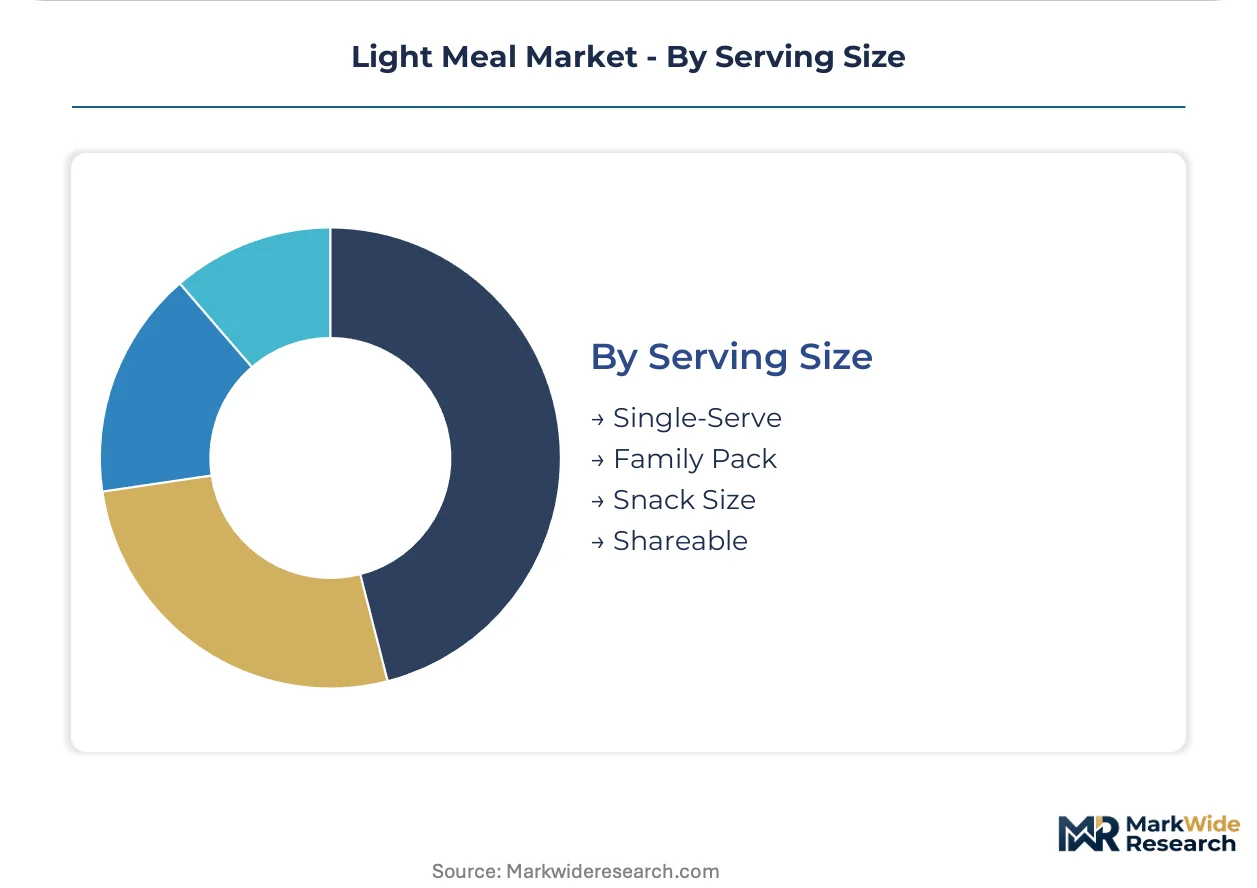
By production volume, single-serve leads. By margin per unit, snack size is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors Asia-Pacific cold-chain throughput for prepared protein imports, while Germany's Rhine-Alpine rail corridor sustains just-in-time ingredient flows to central European distribution hubs.
China
Shanghai and Beijing workplace dining contracts drive premium bowl demand among financial sector professionals. SAMR's 2024 GB 28050 nutrition labeling mandates force sodium disclosure reformulation across domestic manufacturers. The Yangtze River Delta cold-chain network now sustains 72-hour freshness windows for chilled poultry deliveries to Nanjing and Hangzhou cloud kitchens.
United States
Corporate campus dining programs in Manhattan and San Francisco prioritize grab-and-go protein bowls for hybrid workforces. FDA Food Safety Modernization Act traceability rules extend to imported prepared meal ingredients. Chicago's refrigerated logistics cluster anchors Midwest distribution for subscription meal services targeting Denver and Minneapolis health-conscious consumers.
Germany
Berlin and Munich office districts demand clean-label prepared meals with EU organic certification. ECHA REACH chemical restrictions on packaging adhesives add compliance costs for brands exporting to Dutch and French retail channels. The Baden-Württemberg food technology corridor hosts sous-vide equipment manufacturers serving premium workplace caterers.
Japan
Tokyo's 24-hour convenience store density sets the benchmark for chilled fresh meal turnover that Chinese retailers attempt to replicate. METI's plastic resource circulation targets pressure bento packaging toward biodegradable alternatives. The Kansai region's Osaka-Kobe port complex handles ASEAN protein imports for Kansai airport precinct ready-meal production.
South Korea
Seoul Capital Area fitness center retail placements drive evening protein-focused meal occasions. MFDS enforcement of HACCP standards for chilled prepared foods limits new supplier market entry. Busan's refrigerated container terminal anchors Southeast Asian ingredient imports for Daegu-Gyeongbuk manufacturing clusters.
Light Meal Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base clusters around three functional layers: cloud kitchen operators owning last-mile customer relationships, protein processors controlling ingredient freshness, and beverage-led pickup networks anchoring grab-and-go density. Consolidation pressure concentrates among chilled protein suppliers where three upstream players command majority prepared poultry supply. Dominant competitive moves include backward integration into captive protein sourcing and strategic partnerships with third-party delivery aggregators to secure urban logistics density.
Within the beverage-platform tier, Luckin Coffee exemplifies pickup-point logistics density as a competitive anchor. Among protein supply specialists, DaChan Food (Asia) occupies a position representing upstream control over prepared poultry streams. Wagas sits within the premium dine-in and workplace catering archetype, sustaining brand positioning through salad and bowl-focused store networks in Shanghai and Beijing central business districts.
| Leading Market Players |
|---|
| Wagas |
| Element Fresh |
| Shenzhen Xianyu Restaurant Management |
| Shenzhen Yuyangmeichu Network Technology |
| Luckin Coffee |
| DaChan Food (Asia) |
| Shanghai Shaye Light Food |
| Nanjing Super Deer Team Catering Management |
| Guangzhou Juzongli Network Technology |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta cold-chain corridor anchors cost dynamics across tier-one city distribution networks, where refrigerated last-mile density enables premium bowl pricing in Shanghai workplace contracts while compressing margins for secondary city entrants lacking scale economies.
Pricing Analysis
Volume-discount tiering structures separate corporate cafeteria contracts from individual subscription purchases, with SAMR nutrition disclosure compliance adding certification-grade differentiation between transparent-label premium offerings and opaque economy alternatives. Price differentiation rests on cold-chain reliability guarantees and proprietary sauce formulation exclusivity. Cost compression in the wrap and sandwich tiers intensifies as supermarket private labels replicate standardized fillings. Students and price-sensitive family purchasers exhibit highest elasticity, while health-conscious professionals in Beijing and Shanghai absorb premium positioning with minimal churn.
Supply Chain Analysis
Contract-manufacturing concentration sits with DaChan Food and two additional prepared poultry specialists controlling upstream protein flows, while cloud kitchen operators and third-party delivery platforms dominate downstream assembly and fulfillment. Geographic supply concentration centers on China's Yangtze River Delta and Pearl River Delta manufacturing belts, with secondary nodes in Japan's Kansai region and South Korea's Seoul Capital Area. Raw material dependencies include chilled poultry, specialty grain bases, and compostable packaging substrates. Single-source vulnerability in prepared protein inputs creates margin instability when feed grain costs spike. Distribution runs through e-commerce aggregators, corporate cafeteria direct contracts, and convenience store chilled sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from home-prepared meal kit services and workplace micro-kitchen equipment that displaces outsourced catering contracts.
For Market Incumbents: Entrench position through backward integration into captive poultry sourcing that insulates against DaChan Food supply volatility, while securing exclusive third-party delivery aggregator partnerships to lock urban logistics density against cloud kitchen entrants. SAMR disclosure mandates require ongoing formulation investment to maintain clean-label positioning.
For New Entrants and Emerging Players: Pursue convenience store channel penetration in China's secondary cities where 24-hour fresh meal turnover remains underdeveloped compared to Japanese benchmarks. White-space opportunity concentrates in pharmacy and gym retail placements for sous-vide preserved protein offerings with extended shelf life. Go-to-market execution should anchor on subscription-based corporate wellness programs.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underperforming prepared meal divisions lacking cold-chain infrastructure investment. Long-term viability favors operators with proprietary preservation technology and direct corporate cafeteria relationships. Monitor cloud kitchen operator consolidation velocity as inflection indicator for platform economics maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Supply | Captive sourcing from DaChan Food competitors reduces input volatility for bowl specialists. |
| Cloud Kitchen Network Expansion | Dense urban pickup points replicate Luckin Coffee logistics density for meal penetration. |
| Compostable Packaging Transition | MEE subsidy capture creates first-mover advantage in biodegradable bowl materials. |
| Corporate Wellness Partnership | Direct cafeteria contracts with Beijing and Shanghai employers secure recurring revenue. |
| Sous-Vide Technology Licensing | Extended shelf-life preservation opens pharmacy and gym retail channel placement. |
Research Methodology
Initial hypotheses were tested against primary input from cloud kitchen operators, corporate cafeteria procurement managers, cold-chain logistics directors, and SAMR regulatory consultants and refined through secondary validation against customs trade data, SAMR GB standard filings, SEC 10-K disclosures from listed foodservice operators, and Nielsen retail audit records. Bottom-up volume modeling across bowl, salad, wrap, and sandwich formats triangulated with top-down expenditure estimates from workplace dining program budgets.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end-user archetype, distribution channel, and serving size configuration. CAGRs were derived from trend extrapolation adjusted for regulatory phase-in effects and technology adoption curves. Industry-specific forecast inputs included cold-chain infrastructure build-out timelines and SAMR enforcement intensity for nutrition labeling compliance.
Sensitivities concentrate around feed grain price volatility, SAMR approval cycle delays for new protein suppliers, and cloud kitchen platform consolidation dynamics. Forecasts reflect assumptions regarding sustained urban professional time constraints and continued employer subsidy of workplace meal programs. Quarterly review of refrigerated logistics capacity expansion and GB standard revision announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Beverage Coaster Market
Food Service
Restaurant Takeout Market
Food Service
United Arab Emirates Full Service Restaurants Market
Food Service
Foodservice Coffee Market
Food Service
Europe Vending Machine Market
Food Service
Europe Cloud Kitchen Market
Food Service
Oman Food Service Market
Food Service
Kamado Grill Market
Food Service
Global Digital Food Delivery Market
Food Service
Russia Foodservice Market
Food Service
Food Logistics Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Rotisseries Market
Food Service
Brazil Foodservice Market
Food Service
Restaurants in Belgium Market
Food Service
North America Cafes & Bars Market