
 Peer-To-Peer Dining Market | 2026-2036
Peer-To-Peer Dining Market Size, Share, and Industry Trends Forecast 2026-2036
Peer-To-Peer Dining Market Analytics
Experience-seeking travelers is decoupling from traditional restaurant bookings as the dominant demand source in peer-to-peer dining. EatWith leverages host verification protocols and curated event formats to sustain premium positioning across European and North American cities. Traveling Spoon anchors its competitive edge in hyper-local culinary immersion, specializing in cooking classes and market tours led by home cooks rather than professional chefs. Withlocals competes on price-accessible experiences while extending its host network into secondary tourism destinations across Asia.
Peer-to-peer dining denotes a digitally mediated marketplace where individual hosts offer prepared meals, cooking instruction, or food-centric gatherings to guests through platform infrastructure, with transactions typically involving real-time booking, host-guest messaging, and post-experience rating systems. The model functions primarily as an alternative hospitality channel, converting residential kitchens and dining spaces into temporary commercial venues while capturing spend that would otherwise flow to conventional restaurants or tour operators. Culinary experiences within the offering segment command disproportionate margin attention due to higher per-booking values and repeat guest potential, while mobile app platforms dominate customer acquisition through push-notification-driven discovery and frictionless payment integration. Food enthusiasts represent the most engaged customer type, though travelers generate the highest absolute booking volumes during seasonal peaks.
The FDA and state-level health departments in the United States impose varying cottage food and temporary food establishment rules that directly determine host eligibility and operational scope. The EU's GDPR and emerging platform-work directives shape data handling obligations and host classification standards across member states, with France's DGCCRF actively enforcing consumer protection compliance. Stakeholders must monitor how regulatory fragmentation between national food safety regimes and platform liability standards affects cross-border host onboarding and insurance product design.
Market Dynamics
Platform liability frameworks are forcing peer-to-peer dining operators to restructure host onboarding, insurance products, and verification protocols across multiple jurisdictions simultaneously. The collision between national food safety regimes and digital platform accountability standards is compressing operational margins while elevating compliance costs for cross-border expansion.
Growth Catalysts
- GDPR-aligned data portability:The EU's platform-work directives are clarifying host classification standards, reducing legal ambiguity for operators scaling across member states. This regulatory clarity accelerates host recruitment in France, Germany, and Spain.
- Culinary tourism infrastructure:Experience-seeking travelers now prioritize hyper-local immersion over conventional restaurant bookings, creating sustained demand for cooking classes and market tours in destinations with mature digital payment ecosystems.
- Push-notification discovery:Mobile-first customer acquisition is automating real-time booking flows and reducing friction in host-guest matching, particularly among urban millennials in metropolitan clusters.
Market Restraints
- Cottage food regulatory fragmentation:The FDA and fifty state-level health departments impose inconsistent temporary food establishment rules that fragment host eligibility criteria and operational scope across the United States.
- Insurance product gaps:Standard hospitality liability coverage excludes residential kitchen conversions, forcing platforms to develop bespoke host protection products with limited carrier participation.
- Professional chef substitution:Traditional cooking schools and established culinary tour operators retain brand trust advantages in premium experience segments, constraining price realization for amateur-led offerings.
Strategic Opportunities
- Secondary tourism destinations:Host network expansion into underpenetrated Asian markets beyond Tokyo, Kyoto, and Osaka captures emerging experience-seeking traveler flows before incumbent platform saturation.
- EU Green Deal alignment:Carbon-conscious experience marketing and local sourcing certification protocols attract sustainability-motivated European travelers seeking low-impact culinary immersion.
- Real-time translation integration:Converging AI-powered language tools with existing booking infrastructure removes communication barriers between hosts and international guests, unlocking non-English-speaking host populations.
Industry Challenges
- Food handler certification timelines:Host onboarding delays from multi-week safety training requirements compress booking windows and reduce host conversion rates from application to first experience.
- Legacy kitchen retrofit costs:Residential spaces require capital investment in commercial-grade equipment and ventilation to meet temporary food establishment standards, deterring price-sensitive prospective hosts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peer-To-Peer Dining Market |
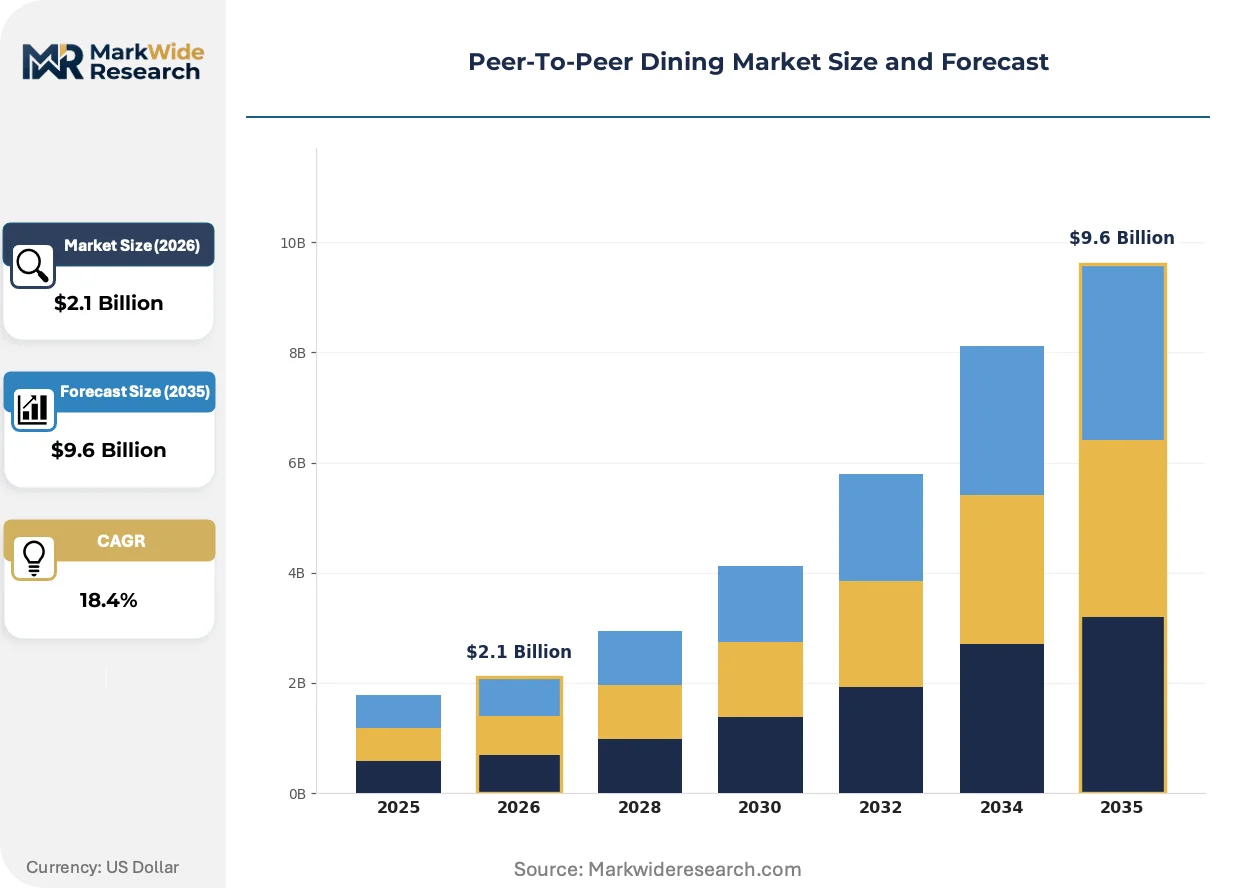
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.6 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Offering: Homemade Meals, Culinary Experiences, Food Events, Dining Tours Customer Type: Food Enthusiasts, Travelers, Locals, Event Hosts Service Type: Meal Delivery, In-Person Dining, Cooking Classes, Food Pairing Platform: Mobile App, Website, Social Media, Community Boards |
| Companies Covered | EatWith, BonAppetour, Traveling Spoon, Withlocals, Feastly, PlateCulture, Bookalokal, Cookly, Supper Club, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peer-To-Peer Dining Market Evolving Landscape
Artificial intelligence and evolving liability standards are restructuring how peer-to-peer dining platforms verify hosts, price experiences, and manage cross-border regulatory exposure. These shifts are compressing operational timelines while expanding addressable host populations.
Machine learning-driven host verification is automating background checks, kitchen safety assessments, and guest matching algorithms at scale. Platform operators in the United States and France are deploying these systems to reduce manual review backlogs and accelerate host time-to-first-booking from weeks to days. This compression is enabling faster geographic expansion without proportional compliance headcount growth.
France's DGCCRF is intensifying consumer protection enforcement against experience platforms, mandating transparent pricing disclosure and host qualification documentation. The industrial consequence is elevated legal review costs for platform operators active in the French market. Experience categories with higher per-booking values face disproportionate scrutiny, prompting operators to pre-emptively standardize disclosure protocols across European deployments.
Experience-seeking travelers are compressing their booking decision cycles, with mobile push notifications now driving majority discovery rather than search-based planning. This behavioral shift is displacing traditional travel agency and concierge channels for culinary experience procurement. The pattern is most visible in United States and Japanese metropolitan markets where same-week booking volumes now exceed advance reservations during seasonal peaks.
Peer-To-Peer Dining Market Segmentation
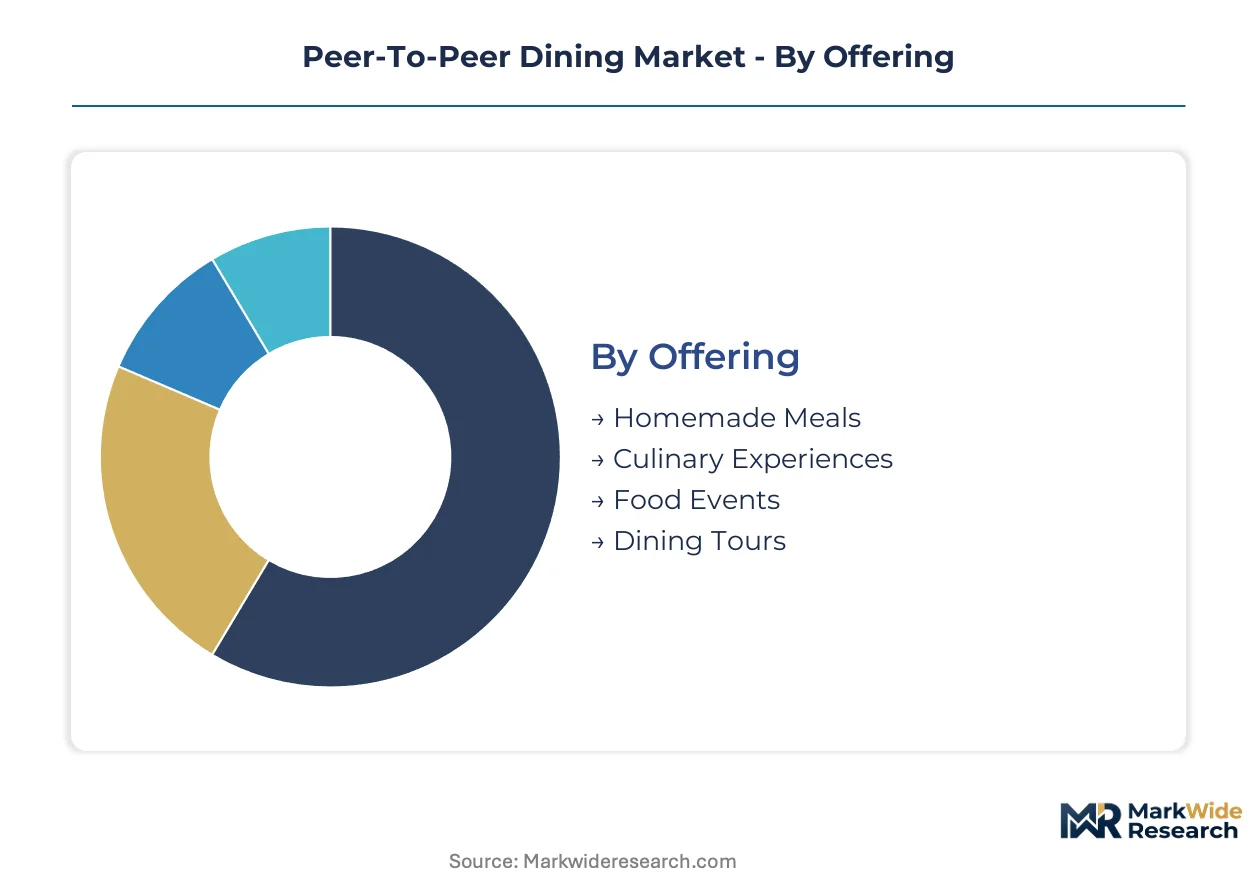
Segmentation in peer-to-peer dining reveals how platform operators allocate engineering resources and marketing spend across fundamentally different engagement models. Each dimension carries distinct margin profiles, regulatory exposure, and host onboarding complexity that shapes competitive strategy.
Offering:
Standalone experiences operate independently of broader travel itineraries, while embedded offerings integrate with multi-day tourism packages or corporate event programming.
- Homemade Meals:Individual hosts prepare and serve dishes in residential settings, typically priced below commercial restaurants. Demand concentrates among urban millennials in United States metropolitan clusters seeking authentic local cuisine without premium restaurant markup.
- Culinary Experiences:Structured activities combining cooking instruction with shared dining, commanding higher per-booking values. French and Japanese markets show strongest concentration where culinary tourism infrastructure and digital payment maturity converge.
- Food Events:Multi-gathering formats such as supper clubs or themed dining nights. These leverage social media discovery in United States and United Kingdom urban centers.
- Dining Tours:Progressive meals across multiple host locations, requiring complex logistics coordination. European cities with compact historic centers support this format most effectively.
Homemade Meals leads volumes today; Culinary Experiences is gaining share fastest.
Customer Type:
Cost tier differentiation separates discretionary leisure spend from business-funded or special-occasion budgets across the customer base.
- Food Enthusiasts:Repeat bookers with high engagement and review participation, generating platform loyalty metrics. This segment shows strongest lifetime value in France and Japan where culinary identity drives sustained platform interaction.
- Travelers:Seasonal demand spikes during peak tourism windows, with booking decisions compressed to same-week timeframes. United States and Japanese metropolitan markets show this pattern most acutely.
- Locals:Residents seeking novel social experiences or neighborhood exploration. Price sensitivity is highest here, favoring platforms with accessible entry points.
- Event Hosts:Corporate or private party organizers booking group experiences. This segment requires bespoke coordination and carries elevated liability exposure.
Travelers generate peak seasonal revenue; Food Enthusiasts deliver the steadiest year-round booking flow.
Service Type:
Margin structure varies dramatically between low-touch digital delivery and high-touch in-person hospitality requiring physical host presence.
- Meal Delivery:Prepared food transported to guest locations, bypassing shared space requirements. Cottage food regulations in United States states create operational fragmentation for this segment.
- In-Person Dining:Traditional host-guest table sharing with highest experiential authenticity. This format faces steepest regulatory compliance costs across European jurisdictions with strict temporary food establishment rules.
- Cooking Classes:Hands-on instruction with ingredient preparation and technique demonstration. Demand clusters in Asian markets where travelers seek hyper-local skill acquisition.
- Food Pairing:Curated combinations of dishes with beverages, requiring specialized host knowledge. Premium positioning supports higher price realization in mature markets.
In-Person Dining dominates absolute transaction volume; Cooking Classes show the steepest expansion trajectory among experience-seeking travelers.
Platform:
Customer acquisition efficiency and host onboarding friction diverge sharply between mobile-native and web-legacy infrastructure.
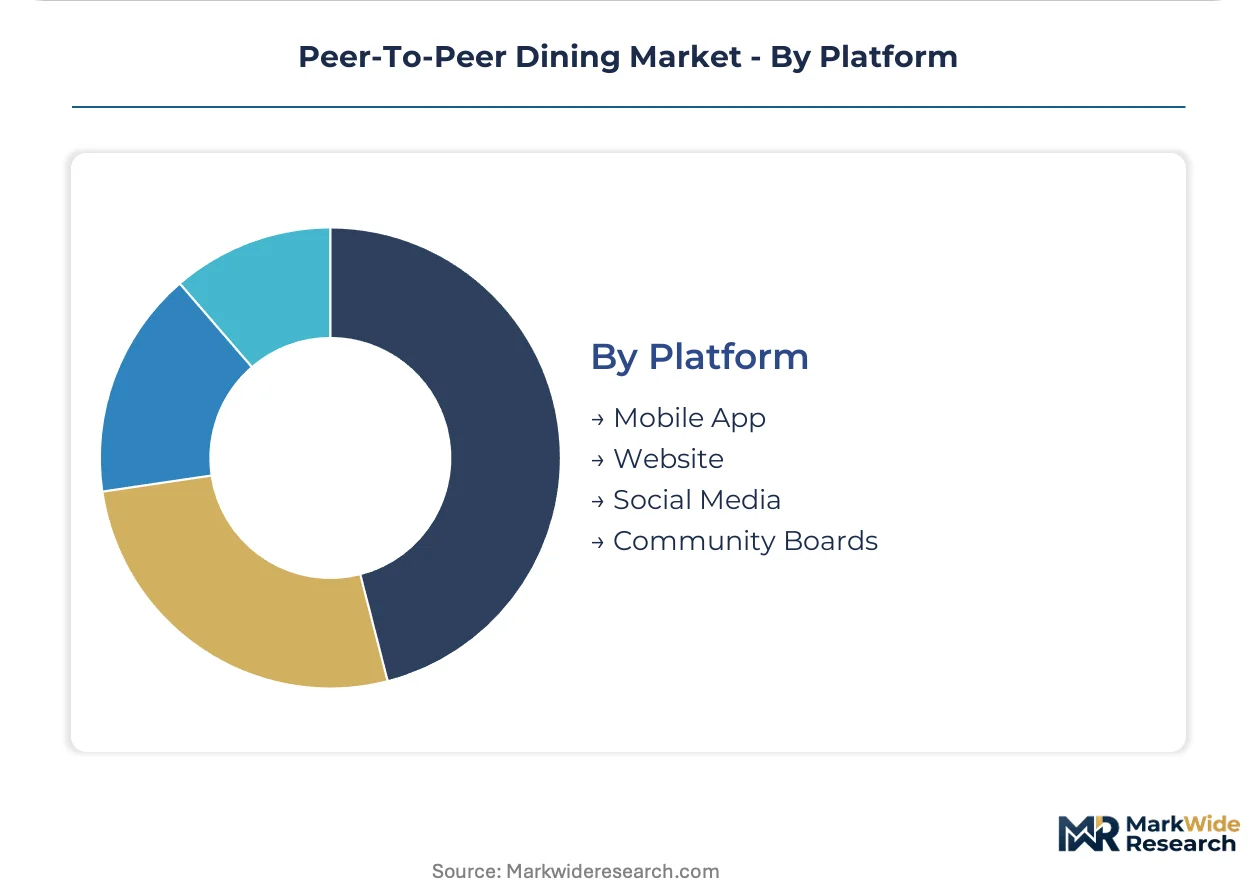
- Mobile App:Push-notification-driven discovery with integrated payment and real-time messaging. United States and Japanese urban millennials show highest conversion rates through this channel.
- Website:Search-oriented booking with richer content presentation, capturing advance planners and corporate bookers. European markets retain stronger web-based booking share.
- Social Media:Discovery through influencer content and peer recommendations, with booking handoff to primary platforms. Visual formats drive culinary experience discovery in France and Italy.
- Community Boards:Hyper-local listings with minimal platform intermediation, common in secondary Asian tourism destinations with limited platform penetration.
Mobile App captures the majority of new customer acquisition; Social Media is climbing the fastest as a discovery-to-booking pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan clusters in the United States, France, and Japan concentrate platform activity where digital payment maturity and culinary tourism infrastructure intersect most densely.
United States
Urban millennials in New York, Los Angeles, and San Francisco drive same-week booking volumes through mobile-first discovery. The FDA and fifty state health departments impose fragmented cottage food rules that complicate host eligibility across jurisdictions. Platform operators concentrate compliance resources in California and Texas where temporary food establishment standards are most stringently enforced.
France
Experience-seeking travelers in Paris, Lyon, and Marseille prioritize hyper-local culinary immersion over conventional restaurant bookings. The DGCCRF mandates transparent pricing disclosure and host qualification documentation under intensifying consumer protection enforcement. Culinary experience providers face elevated legal review costs as disclosure protocols standardize across European deployments.
Japan
Travelers in Tokyo, Kyoto, and Osaka generate peak seasonal demand for cooking classes and market tours led by home cooks. METI guidelines shape platform accountability standards while local health bureaus enforce kitchen safety protocols. Host network expansion targets secondary destinations beyond the Kansai and Kanto corridors to capture emerging tourist flows.
Germany
Food enthusiasts in Berlin, Munich, and Hamburg sustain year-round engagement through repeat bookings and active review participation. GDPR-aligned platform-work directives clarify host classification standards and reduce legal ambiguity for operators scaling across member states. Compliance clarity accelerates host recruitment in metropolitan clusters with mature digital payment ecosystems.
United Kingdom
Social media discovery drives culinary experience procurement among London, Manchester, and Edinburgh residents seeking novel neighborhood exploration. The UK Food Standards Agency coordinates with local authorities to enforce temporary food establishment rules for residential kitchen conversions. Platform operators navigate post-Brexit regulatory divergence from EU host classification standards.
Peer-To-Peer Dining Market Competitive Landscape
Host verification protocol differentiation dominates the current landscape as platforms compete on trust infrastructure rather than price alone. The vendor base fragments between premium-positioned experience curators, price-accessible mass-market operators, and hyper-local specialists. Three strategic archetypes have emerged: verification-heavy premium platforms, network-scale aggregators, and niche culinary immersion specialists. Geographic expansion and strategic partnerships represent the dominant competitive moves as operators seek pre-saturation positioning in secondary Asian destinations.
Within the premium curation tier, EatWith and Traveling Spoon exemplify divergent approaches to host quality assurance and experience design. EatWith anchors its positioning through curated event formats and stringent verification protocols across European and North American cities. Traveling Spoon occupies a specialist position emphasizing cooking classes and market tours led by home cooks rather than professional chefs, with concentration in Asian destinations. Withlocals sits within the price-accessible tier, extending host networks into secondary tourism markets through lower-friction onboarding.
| Leading Market Players |
|---|
| EatWith |
| BonAppetour |
| Traveling Spoon |
| Withlocals |
| Feastly |
| PlateCulture |
| Bookalokal |
| Cookly |
| Supper Club |
| Others |
Value Network & Pricing Analysis
Captive insurance arrangements anchor supply position and pricing power for peer-to-peer dining platforms navigating fragmented food safety regimes. Platforms that underwrite host liability in-house capture margin that otherwise flows to third-party carriers while compressing onboarding timelines in high-friction jurisdictions like California and France.
Pricing Analysis
Input-cost pass-through from host certification and kitchen retrofit requirements shapes pricing stratification across experience tiers. Three-tier pricing structure across premium, standard, and economy levels separates professionally equipped hosts with commercial ventilation from residential kitchen operators and basic meal-sharing participants. Certification level—specifically ServSafe or equivalent food handler credentials—drives price premiums in United States and French markets. Cost compression in the economy tier is intensifying because cottage food regulatory fragmentation forces platforms to subsidize compliance navigation for price-sensitive prospective hosts. Locals show highest price sensitivity, while experience-seeking travelers demonstrate lowest elasticity due to compressed booking decision cycles.
Supply Chain Analysis
Regional distribution centers for host onboarding and verification equipment concentrate in United States, France, and Japan where platform accountability standards are most stringently enforced. The supply chain draws from third-party background check providers, commercial kitchen equipment lessors, and specialized food safety training platforms. Single-source vulnerability in AI-powered translation tools—critical for unlocking non-English-speaking host populations—creates concentration risk as platforms expand into secondary Asian destinations. Distribution runs through mobile app infrastructure with integrated payment rails, reducing friction in host-guest matching while elevating platform dependency on Apple and Google ecosystem policies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage in peer-to-peer dining exploits cost differentials between strict temporary food establishment regimes in California and Massachusetts versus permissive cottage food laws in Texas and Florida. Regulatory compliance spend concentrates in high-barrier jurisdictions while margin capture shifts to low-friction expansion markets.
For Market Incumbents: Hedge against professional chef substitution by embedding host verification protocols as proprietary infrastructure rather than commoditized table stakes. Invest in captive insurance products to defend margin position against third-party carrier withdrawal from residential kitchen coverage. Accelerate host recruitment in Germany and Spain where GDPR-aligned platform-work directives reduce legal ambiguity and compress onboarding timelines. For New Entrants and Emerging Players: Corporate event organizers represent an underserved buyer archetype with elevated per-booking values and limited incumbent platform customization. Secondary tourism destinations in Vietnam, Indonesia, and Thailand offer the most penetrable geography before network saturation by EatWith and Traveling Spoon. A cooking-class-first go-to-market angle bypasses the steepest temporary food establishment compliance costs while capturing experience-seeking traveler demand. For Investors and Strategic Acquirers: Roll-up economics work for verification-heavy regional platforms because host trust infrastructure does not scale across borders and creates local moats. The five-to-ten year viability window favors operators with pre-saturation positioning in Asian markets beyond Tokyo and Osaka. Target acquisition profile: mobile-native platforms with concentrated host networks in single metropolitan clusters and established DGCCRF or FDA compliance protocols. The signal to watch is same-week booking volume share crossing above advance reservation volumes—indicating behavioral shift completion and platform dependency lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Host Verification Automation | Machine learning deployment in France and United States compresses manual review backlogs from weeks to days. |
| Captive Insurance Product Development | In-house liability coverage captures margin otherwise lost to carriers excluding residential kitchen conversions. |
| Secondary Destination Expansion | Host network extension into Vietnam and Indonesia captures tourist flows before incumbent platform saturation. |
| Real-Time Translation Integration | AI-powered language tools unlock non-English-speaking host populations in Asian markets. |
| EU Green Deal Alignment | Carbon-conscious certification protocols attract sustainability-motivated European travelers seeking low-impact culinary immersion. |
Research Methodology
Coverage spans United States, France, Japan, Germany, and United Kingdom, with primary inputs from each market's regulatory environment and platform operator landscape. Primary interviews with peer-to-peer dining platform executives, host community managers, food safety compliance officers, and culinary tourism operators combined with secondary validation from FDA guidance documents, DGCCRF enforcement records, METI platform accountability guidelines, and EU platform-work directive texts. Bottom-up host network sizing and top-down tourism expenditure triangulation anchored market estimates.
Granularity-level modeling addressed offering type, customer segment, service format, and platform channel across the projection horizon. Segment-specific growth patterns were derived from mobile app download trajectories, host application-to-booking conversion rates, and seasonal tourism flow data. CAGRs reflect compounding assumptions around urban millennial adoption curves and experience-seeking traveler behavioral shifts without year-specific anchors.
Inputs from platform operators and regulatory filings were available through the study window; gaps in host income disclosure and unreported cash transactions introduce uncertainty bands around absolute market sizing. Forecasts reflect documented assumptions around mobile adoption rates and food safety regime stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
India Foodservice Market
Food Service
Integrated Stove Market
Food Service
Commercial Griddle Market
Food Service
Plates Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Netherlands Food Service Market
Food Service
US Food Service Market
Food Service
Cambodia Foodservice Market
Food Service
Personal Chef Services Market
Food Service
Food Logistics Market
Food Service
Global Sushi Restaurants Market
Food Service
Inflight Catering Market
Food Service
Kamado Grill Market
Food Service
Aquarium Protein Skimmers Market
Food Service
US Food Trucks Services Market