
 Food Processing Ingredients Market | 2026-2036
Food Processing Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Food Processing Ingredients Market Intelligence
ISO 22000 certification is collapsing the supplier base as smaller ingredient traders fail to meet HACCP-integrated audit cycles. Cargill, Incorporated leverages its grain origination network to secure backward integration into modified starch production. Kerry Group anchors European flavor systems capacity through its Naas innovation campus in Ireland. Ingredion Incorporated specializes in plant-based texturizers for meat substitute applications.
Food processing ingredients comprise functional additives, flavor systems, and texturizing agents formulated to specific viscosity, particle size, and thermal stability parameters that govern shelf life extension and sensory performance in manufactured foods. Emulsifiers and stabilizers command margin pools in dairy alternatives where fat-protein suspension challenges multiply with oat and pea base transitions. Flavor enhancers lead volume in snack foods and confectionery as salt-reduction mandates intensify across EU member states. Encapsulation within processing stages represents the fastest-growing technology vector for volatile compound protection and targeted release in baked goods.
FDA GRAS self-determination and EU EFSA novel food authorizations create divergent compliance cost structures that favor multi-territory players with dedicated regulatory affairs functions. ECHA REACH substance evaluation and EU Green Deal farm-to-fork targets are forcing reformulation timelines toward bio-based emulsifier alternatives. Stakeholders must monitor emerging genome-edited ingredient classifications as classification uncertainty threatens to fragment approval pathways across OECD jurisdictions.
Market Dynamics
Clean-label ingredient mandates from dairy alternative manufacturers are forcing simultaneous reformulation across emulsifier, stabilizer, and flavor systems portfolios, collapsing legacy additive approval timelines and supplier qualification cycles into overlapping compliance windows.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Bio-based emulsifier alternatives gain regulatory preference as EFSA novel food pathways accelerate for plant-derived texturizers.
- Encapsulation technology adoption:Baked goods manufacturers deploy microencapsulation for volatile compound protection, extending shelf life without synthetic preservatives.
- Germany's food technology corridor:Concentrated R&D infrastructure around Cologne and Düsseldorf anchors European flavor systems innovation and pilot-scale manufacturing.
Market Restraints
- EU REACH substance evaluation costs:ECHA compliance expenditures disproportionately burden mid-tier ingredient traders lacking dedicated regulatory affairs functions.
- Modified starch input volatility:Grain origination price swings compress margins for backward-integrated producers dependent on corn and wheat feedstocks.
- ISO 22000 audit cycle failures:Smaller suppliers collapse under HACCP-integrated certification requirements, reducing qualified vendor pools for dairy alternative manufacturers.
Strategic Opportunities
- Genome-edited ingredient classifications:OECD jurisdiction fragmentation creates first-mover advantage for multi-territory players with preemptive regulatory dossiers.
- Salt-reduction mandates:EU member state flavor enhancer procurement intensifies as sodium thresholds tighten in snack foods and confectionery.
- F-Gas Regulation reform alignment:Chemical additive approval pathway redesign favors cold-chain ingredient processors with existing sustainability certifications.
Industry Challenges
- Thermal stability parameter expertise:Formulation chemists capable of balancing viscosity, particle size, and shelf-life extension specifications remain scarce across European innovation campuses.
- Legacy equipment retrofitting:Encapsulation technology integration demands capital-intensive extrusion system upgrades incompatible with existing plant configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Processing Ingredients Market |
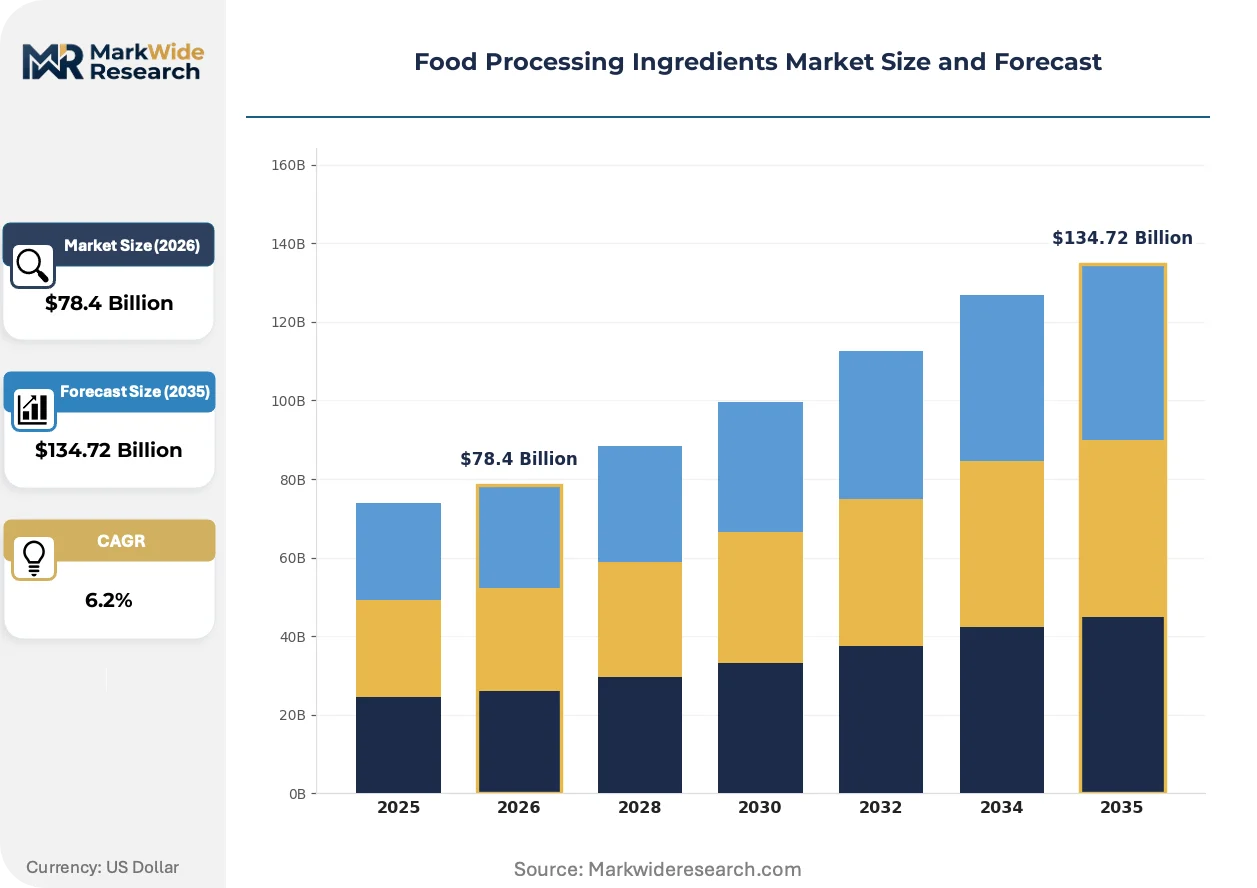
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugars, Emulsifiers, Antioxidants, Flavor Enhancers, Stabilizers, Thickeners Application: Baked Goods, Dairy Alternatives, Meat Substitutes, Beverages, Confectionery, Snack Foods Processing Stage: Pre-mix, Inline Mixing, Coating, Encapsulation, Fortification, Preservation End User: Food Manufacturers, Beverage Producers, Nutraceutical Companies, Catering Services, Institutional Kitchens |
| Companies Covered | Tate & Lyle, Kerry Group, Cargill, Incorporated, Givaudan, BASF SE, Archer Daniels Midland Company, Ingredion Incorporated, Corbion, International Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Processing Ingredients Market Strategic Shifts & Innovations
Processing-stage encapsulation is compressing traditional additive categories while regulatory divergence between FDA GRAS self-determination and EFSA novel food pathways forces parallel compliance architectures.
Microencapsulation systems for volatile compound protection are fragmenting the baked goods additive market. Artisan and industrial bakeries alike adopt lipid-based and biopolymer shell technologies to replace synthetic antioxidant preservatives. This fragmentation is dissolving the historical dominance of bulk chemical antioxidants and creating tiered supply relationships based on release-kinetics customization capabilities.
ECHA REACH substance evaluation combined with EU F-Gas Regulation reforms is tightening chemical additive approval pathways. Industrial consequence includes extended reformulation timelines and elevated toxicology study requirements for synthetic emulsifiers. Dairy alternative manufacturers face the steepest compliance burden as oat and pea base transitions multiply fat-protein suspension challenges already subject to novel food scrutiny.
Buyer concentration among clean-label dairy alternative brands is compressing ingredient supplier switching cycles. Large contract manufacturers now demand dual-source qualification for texturizers and flavor systems, displacing single-source relationships that dominated legacy procurement. This pattern concentrates most visibly in Germany's food technology corridor where innovation campuses anchor accelerated vendor rotation protocols.
Food Processing Ingredients Market Segmentation
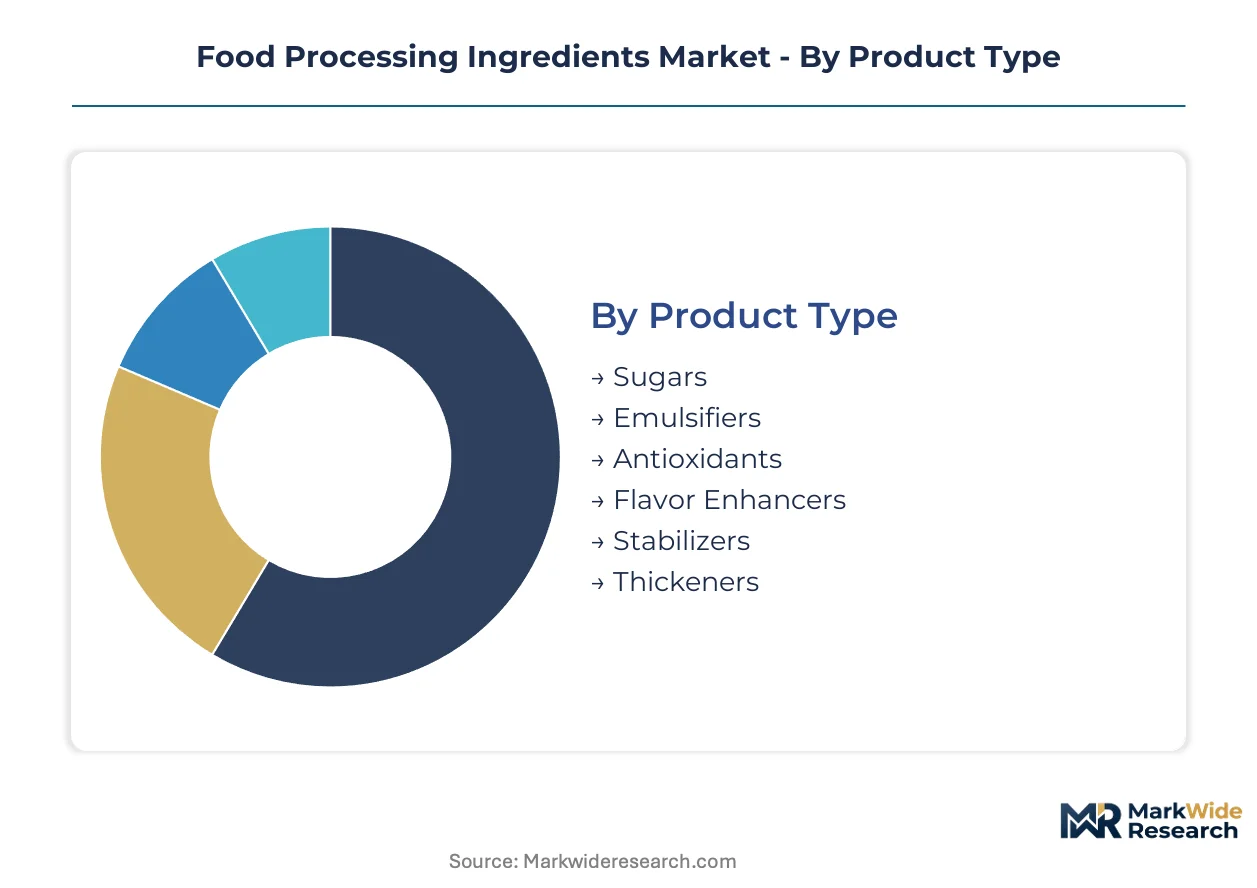
Ingredient specification requirements diverge sharply across processing stages and end-use categories. Manufacturers configure procurement portfolios around functional performance thresholds rather than commodity pricing. Segment boundaries are blurring as encapsulation technology collapses traditional additive categories into integrated delivery systems.
Product Type:
Domestic production dominates sugars and stabilizers, while emulsifiers and flavor enhancers draw heavily on import supply chains from German and Dutch chemical processing hubs.
- Emulsifiers:Lecithin, mono- and diglycerides, and polysorbates stabilize fat-water interfaces in plant-based dairy. German dairy alternative manufacturers drive specification tightening as oat and pea protein transitions multiply suspension challenges.
- Flavor Enhancers:Yeast extracts, nucleotides, and hydrolyzed vegetable proteins intensify taste perception while enabling sodium reduction. EU member state procurement concentrates in snack foods and confectionery as regulatory thresholds tighten across France, Italy, and Spain.
- Sugars:Sucrose, glucose syrups, and maltodextrins provide bulk, browning, and fermentation substrate functionality.
- Antioxidants:Ascorbates, tocopherols, and rosemary extracts interrupt lipid oxidation pathways in extended shelf-life applications.
- Stabilizers:Carrageenan, xanthan gum, and locust bean gum control syneresis and texture in frozen desserts.
- Thickeners:Starches, pectins, and gums modify viscosity and mouthfeel in pourable and spoonable systems.
Flavor enhancers command the established base. The steepest expansion runs through emulsifiers.
Application:
Volume concentration tilts toward baked goods and beverages, while margin pools concentrate in dairy alternatives and meat substitutes where technical barriers exclude commodity suppliers.
- Dairy Alternatives:Oat, pea, and almond base formulations demand customized emulsifier-stabilizer systems to suspend fat mimics and prevent phase separation. Clean-label mandates from Scandinavian and German brand owners compress supplier qualification cycles into overlapping compliance windows.
- Meat Substitutes:Texturized vegetable proteins and mycoprotein matrices require binding, juiciness retention, and fibrous structure formation. Dutch and Belgian extrusion technology providers anchor European innovation in high-moisture analog production.
- Baked Goods:Enzymes, emulsifiers, and oxidizing agents control dough rheology and crumb structure in industrial and artisan production.
- Beverages:Acid stability, cloud maintenance, and flavor protection govern ingredient selection in carbonated, still, and functional drink categories.
- Confectionery:Tempering aids, anti-bloom agents, and flavor encapsulation address fat polymorphism and volatile retention in chocolate and sugar confectionery.
- Snack Foods:Seasoning adhesion, oil absorption control, and shelf-life extension drive topical and inclusion additive demand.
Baked goods anchor volume throughput. Dairy alternatives capture the fastest margin expansion trajectory.
Processing Stage:
Capital intensity stratifies sharply: pre-mix and inline mixing deploy widely, while encapsulation and fortification concentrate among large-scale manufacturers with dedicated R&D infrastructure.
- Encapsulation:Spray-drying, fluid bed coating, and extrusion technologies entrap volatiles, lipids, and bioactives within lipid or biopolymer matrices. German baked goods manufacturers adopt microencapsulation at scale to replace synthetic antioxidants while extending shelf life.
- Fortification:Vitamin, mineral, and bioactive incorporation demands stability validation through thermal processing and storage. Irish and Danish dairy processors lead European micronutrient delivery system deployment for functional positioning.
- Pre-mix:Dry blending of multiple functional ingredients simplifies downstream manufacturing and reduces batch variability.
- Inline Mixing:Continuous dispersion and hydration of hydrocolloids and emulsifiers during fluid processing.
- Coating:Surface application of flavors, colors, and functional actives onto finished or intermediate products.
- Preservation:Antimicrobial and antioxidant addition to inhibit microbiological and oxidative deterioration.
Pre-mix operations command the established base. Encapsulation is climbing the fastest as clean-label preservation demand intensifies.
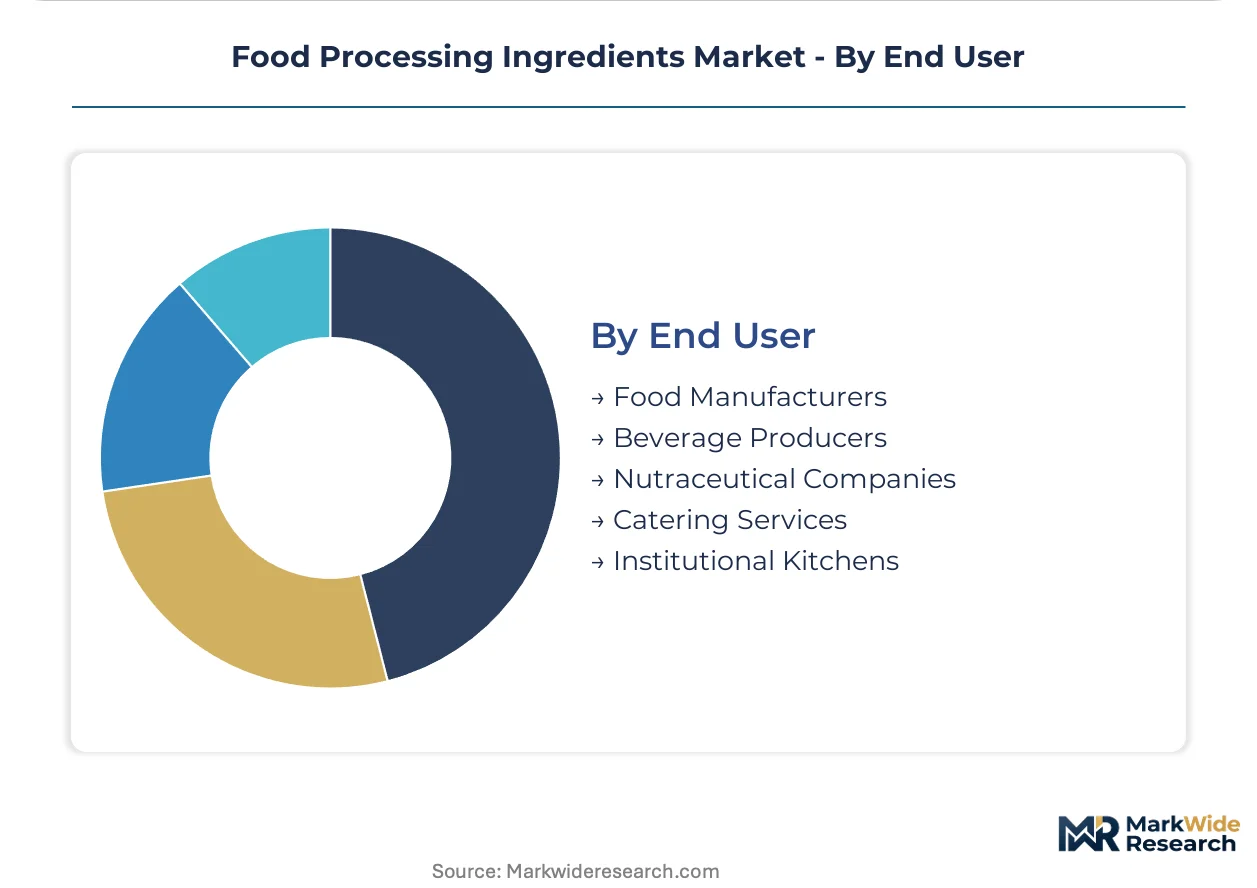
End User:
Food manufacturers and beverage producers drive specification development, while nutraceutical companies and institutional channels absorb commoditized ingredient streams.
- Food Manufacturers:Industrial bakeries, confectioners, and prepared food producers configure multi-ingredient systems around process compatibility and cost targets. Large contract manufacturers in Germany's Cologne-Düsseldorf corridor now mandate dual-source qualification for texturizers and flavor systems.
- Beverage Producers:Still and carbonated drink, juice, and functional beverage formulators prioritize acid stability, clarity, and flavor protection in ingredient selection.
- Nutraceutical Companies:Dietary supplement and functional food developers source bioactive delivery systems with validated stability and bioavailability data.
- Catering Services:Central kitchen and foodservice manufacturing operations emphasize batch consistency and extended holding stability.
- Institutional Kitchens:Hospital, school, and military feeding systems procure standardized ingredient formats with simplified preparation protocols.
Food manufacturers anchor procurement volume. Nutraceutical companies are gaining share fastest as functional positioning penetrates mainstream categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large contract manufacturers and dairy alternative brand owners concentrate procurement decisions in industrial clusters with integrated R&D infrastructure. EFSA novel food pathways and REACH compliance costs reshape supplier qualification across major processing economies.
Germany
Clean-label dairy alternative manufacturers in the Cologne-Düsseldorf corridor drive emulsifier specification tightening for oat and pea protein formulations. ECHA REACH substance evaluation extends reformulation timelines for synthetic additive portfolios. The Naas innovation campus anchors European flavor systems capacity development.
United States
Snack food and confectionery producers intensify flavor enhancer procurement as sodium reduction mandates tighten across state-level regulations. FDA GRAS self-determination creates divergent compliance cost structures from EU pathways. Midwest grain origination networks support modified starch backward integration.
France
Artisan and industrial bakeries adopt microencapsulation systems for volatile compound protection in extended shelf-life applications. EU Green Deal farm-to-fork targets accelerate bio-based emulsifier alternative development. Paris Basin food technology clusters concentrate clean-label preservation research.
Netherlands
High-moisture meat analog extrusion technology providers anchor European texturizer innovation for mycoprotein matrices. F-Gas Regulation reforms tighten chemical additive approval pathways for cold-chain processors. Rotterdam-Antwerp chemical processing hubs supply import-dependent emulsifier streams.
United Kingdom
Salt-reduction procurement intensifies across snack foods as post-Brexit regulatory divergence from EU thresholds creates parallel compliance architectures. ISO 22000 certification failures collapse smaller supplier pools. Greater London contract manufacturers mandate dual-source qualification for texturizer systems.
Food Processing Ingredients Market Key Industry Players
Player mix skews toward integrated ingredient conglomerates with captive supply chains and specialized flavor or texturizer houses with dedicated innovation campuses. Tiered competitive structure separates scale-driven grain processors from premium-positioned clean-label specialists. Dominant strategic archetypes include backward-integrated starch producers and encapsulation technology licensors. Capacity expansion in German R&D corridors and portfolio diversification into plant-based texturizers represent primary competitive vectors.
Within the integrated processing tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven supply chain control through grain origination networks. Kerry Group occupies a position among specialized flavor systems developers with European innovation infrastructure. These three entities represent divergent competitive positioning: commodity-scale backward integration versus premium-tier formulation expertise.
| Leading Market Players |
|---|
| Tate & Lyle |
| Kerry Group |
| Cargill, Incorporated |
| Givaudan |
| BASF SE |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Corbion |
| International Flavors & Fragrances |
| Others |
Cost & Logistics Intelligence
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, collapsing smaller traders from qualified vendor pools while concentrating procurement leverage among multi-territory players with dedicated regulatory affairs functions. Buyers in Germany's food technology corridor now demand dual-source qualification for texturizers and flavor systems, compressing switching cycles and amplifying price premiums for HACCP-integrated audit survivors.
Pricing Analysis
Cost-plus contracts with grain origination indexation dominate modified starch and emulsifier procurement, tethering ingredient pricing to corn and wheat feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels separates clean-label certified suppliers from commodity traders and captive processors. Pricing pressure stems from ECHA REACH compliance expenditures that disproportionately burden mid-tier players lacking scale economies. Large contract manufacturers exhibit lowest price sensitivity due to reformulation risk aversion, while institutional kitchens and catering services drive commodity tier competition.
Supply Chain Analysis
Rotterdam-Antwerp chemical processing hubs anchor European emulsifier import dependence, creating single-source vulnerability for dairy alternative manufacturers transitioning to oat and pea bases. German grain origination networks and Dutch high-moisture extrusion technology centers supply modified starches and texturizers respectively. Supply chain risk concentrates in REACH substance evaluation timelines that extend reformulation windows and disrupt just-in-time ingredient flows. Distribution runs through integrated ingredient conglomerates with captive blending facilities and specialized flavor houses with regional innovation campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat anchored in regulatory entrenchment, where EFSA novel food authorization timelines and REACH compliance costs create structural barriers that multi-territory incumbents exploit to exclude emerging competitors.
For Market Incumbents: Consolidate backward integration into grain origination networks to secure modified starch feedstock control against price volatility. Expand encapsulation technology licensing portfolios to capture clean-label preservation demand from German baked goods manufacturers. Capacity addition in the Cologne-Düsseldorf corridor reinforces proximity to dairy alternative innovation clusters. Certification investment in bio-based emulsifier alternatives aligns with EU Green Deal farm-to-fork targets and preempts regulatory displacement. For New Entrants and Emerging Players: Custom release-kinetics formulation services represent an under-served layer where incumbents lack agility, creating entry paths for specialized encapsulation technology developers. Genome-edited ingredient classifications offer the most penetrable regulatory white space, as OECD jurisdiction fragmentation delays unified approval standards. Target nutraceutical companies seeking validated bioactive delivery systems with stability data packages that commodity suppliers cannot assemble. A technical service-led go-to-market model bypasses capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flavor systems specialists possessing Naas-class innovation campuses but lacking grain origination integration. The five-to-ten year viability window favors acquisition targets with preemptive regulatory dossiers for genome-edited ingredients and established EFSA novel food approval track records. Watch for REACH substance evaluation outcomes on synthetic emulsifiers as the inflection signal that accelerates bio-based alternative valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill-style supply chain control secures modified starch margins against corn price volatility. |
| Encapsulation Technology Licensing | Microencapsulation IP monetization captures clean-label demand from German industrial bakeries. |
| EU Green Deal Alignment Certification | Bio-based emulsifier credentials preempt REACH-driven synthetic additive displacement. |
| Dual-Source Qualification Compliance | HACCP-integrated audit survival qualifies suppliers for Cologne-Düsseldorf contract manufacturer procurement. |
| Genome-Edited Ingredient Dossier Development | Preemptive OECD regulatory filings create first-mover advantage as classification standards fragment. |
Research Approach
A spread of perspectives from food technology R&D directors, dairy alternative procurement leads, flavor systems formulators, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation across EFSA novel food authorization databases, ECHA REACH substance evaluation registers, EU customs trade flows, and SEC filings from integrated ingredient conglomerates. Bottom-up ingredient demand modeling triangulated against top-down sector consumption estimates.
Segmentation dimensions modeled include ingredient functional category, processing stage application, end-use industry vertical, and geographic regulatory cluster across the projection horizon. CAGRs derive from weighted average growth contributions across emulsifier, flavor enhancer, and encapsulation technology sub-segments. Forecast inputs incorporate reformulation timeline assumptions from EU Green Deal implementation schedules and F-Gas Regulation amendment pathways.
Underlying assumptions cover REACH compliance cost trajectories and clean-label mandate diffusion rates, with deviation risk concentrated in genome-edited ingredient classification timing and grain origination price volatility. Revision becomes warranted when EFSA novel food approval throughput or ECHA substance evaluation prioritization crosses thresholds that alter competitive qualification dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
China Food Preservatives Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Natural Food Color Additives Market