
 Commercial Tableware Services Market | 2026-2036
Commercial Tableware Services Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Tableware Services Market Intelligence
China's expanding manufacturing base for high-grade porcelain and melamine is rewriting the supply dynamics for commercial tableware. Steelite International leverages its extensive distribution network to serve hotel and restaurant chains across multiple continents. Villeroy & Boch differentiates through premium brand positioning and design-led collections for the high-end hospitality sector. Churchill China competes on durability and material innovation, particularly with its super-vitrified body products for demanding food service environments.
Commercial tableware services encompass the rental, supply, and maintenance of dishware, flatware, and drinkware for hospitality businesses. This includes managing inventory of items composed of durable materials like 18/10 stainless steel or vitrified porcelain designed to withstand high-temperature commercial dishwashing. Rental services are expanding quickly, driven by a capital-expenditure-averse model preferred by new cafés and catering businesses. The hotels segment maintains a dominant position among end users due to the scale of its high-volume, multi-venue operations.
Regulations from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern food contact material safety. These rules, alongside China's GB standards for ceramics, dictate material composition and testing protocols, influencing sourcing and compliance costs for service providers. Key decisions for operators now center on balancing the cost of compliant, durable inventory against the operational benefits of outsourcing tableware management.
Market Dynamics
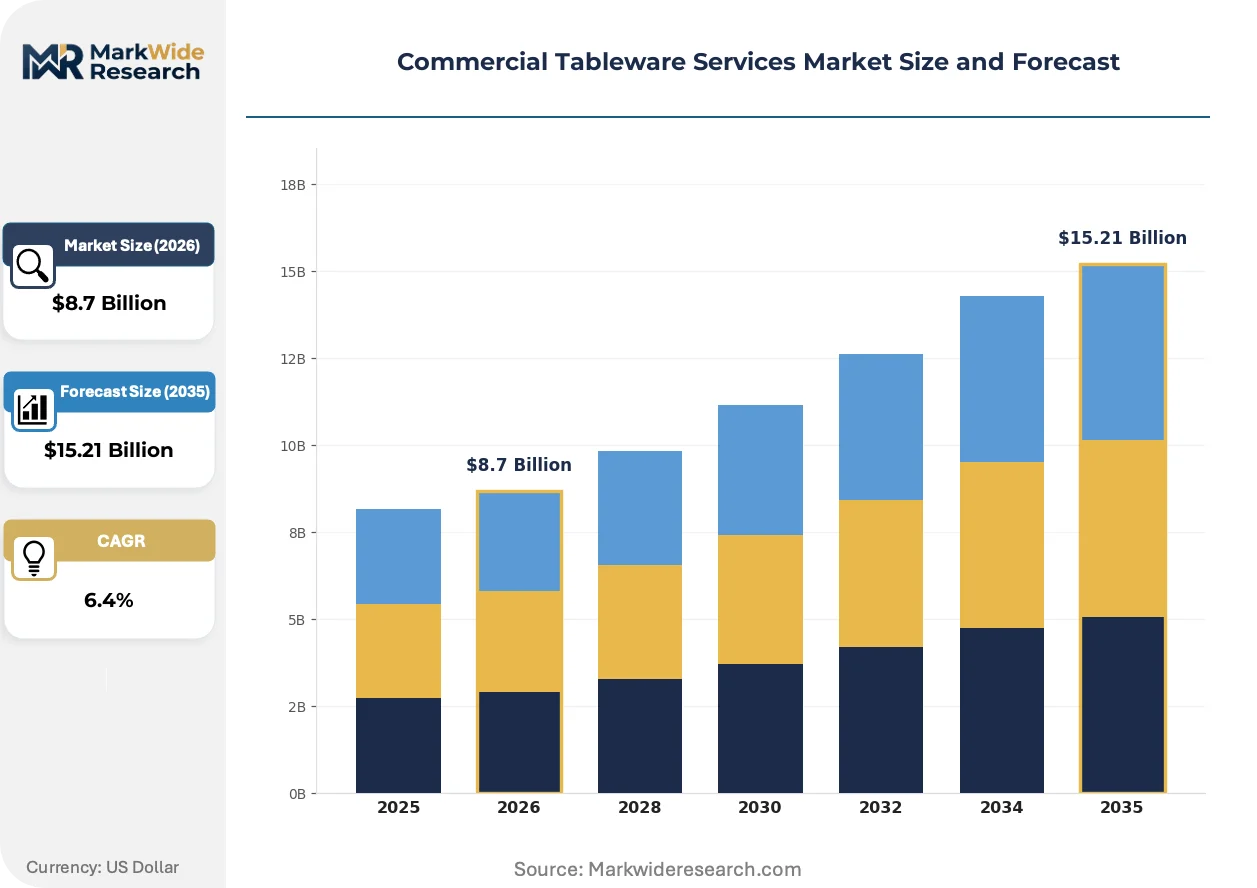
The commercial tableware market's structure is defined by the tension between capital expenditure for owned inventory and the operational benefits of outsourced services. This dynamic is amplified by stringent food contact safety regulations and sustainability mandates pressuring hospitality operators.
Growth Catalysts
- Regulatory Mandates:Stricter EU regulations banning single-use plastics in food service are compelling businesses to adopt durable, reusable tableware, directly benefiting service and rental models.
- End-Use Expansion:The global catering services segment, particularly for large-scale corporate and social events, requires scalable and resilient tableware solutions that rental services are uniquely positioned to provide.
- Hospitality Development:Concentrated growth in major tourism and hospitality centers, including Dubai and Singapore, creates dense demand for professional tableware services in new hotels and restaurants.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw materials, such as high-grade stainless steel for flatware and specific clays for porcelain, directly impact the inventory acquisition costs for service providers.
- Logistical Complexity:Servicing geographically dispersed or low-density clients introduces significant transportation, handling, and breakage costs, which can erode the profitability of rental contracts in non-urban areas.
- Substitution Threat:The availability of premium, aesthetically pleasing disposable tableware continues to present a viable alternative for quick-service restaurants and certain event types, limiting service penetration.
Strategic Opportunities
- Technology Integration:Embedding RFID tags or QR codes into dishware and flatware offers a pathway to automated inventory management, reducing manual counting and tracking losses for large-scale clients.
- Service Specialization:Development of tailored service packages for niche sectors with specific hygiene requirements, such as healthcare facilities and educational institutions, opens new revenue streams beyond traditional hospitality.
- Geographic Expansion:Targeting underpenetrated markets in rapidly urbanizing regions of Southeast Asia and Latin America presents significant growth potential for establishing new service hubs.
Industry Challenges
- Compliance Divergence:Service providers operating across borders must navigate and conform to a complex web of differing food contact material standards, such as the US FDA's rules versus China's GB standards.
- Capital Requirements:The business model necessitates substantial upfront capital investment in a large, durable inventory of items like vitrified porcelain and the industrial-scale dishwashing equipment to maintain it.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Tableware Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dishware, Flatware, Drinkware, Servingware Material: Porcelain, Stainless Steel, Melamine, Glass End User: Restaurants, Cafés, Hotels, Catering Services Service Type: Rental, Customization, Supply, Maintenance |
| Companies Covered | Victorinox, Steelite International, Churchill China, Fiskars Group, Libbey, Cardinal International, Villeroy & Boch, Royal Doulton, Arc Group International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Tableware Services Market Strategic Shifts & Innovations
The industrialization of tableware management is transforming it from a simple operational task into a specialized, technology-enabled service. This evolution is driven by the pursuit of efficiency, heightened compliance demands, and a re-evaluation of asset ownership within the hospitality sector.
Embedded RFID chips in high-grade porcelain and flatware provide real-time asset tracking. Large hotel chains and major convention centers are the primary adopters, seeking to minimize inventory shrinkage. This technology is collapsing the distinction between inventory management and operational logistics, enabling automated billing and loss prevention.
European Food Safety Authority (EFSA) rules imposing stricter limits on leachable heavy metals from ceramic ware are forcing a supply chain realignment. This regulation compels service providers to source higher-grade, certified materials and increases compliance testing costs. The mid-market restaurant segment is most affected, as operators must absorb these costs to ensure safety and avoid liability.
A clear behavioral shift toward flexible, short-term rental agreements is evident, particularly among new businesses. This model bypasses traditional manufacturer-direct sales channels, favoring agile service providers who can accommodate the needs of pop-up restaurants and independent caterers. The trend is most visible in dynamic culinary hubs like New York, London, and Tokyo.
Commercial Tableware Services Market Segmentation
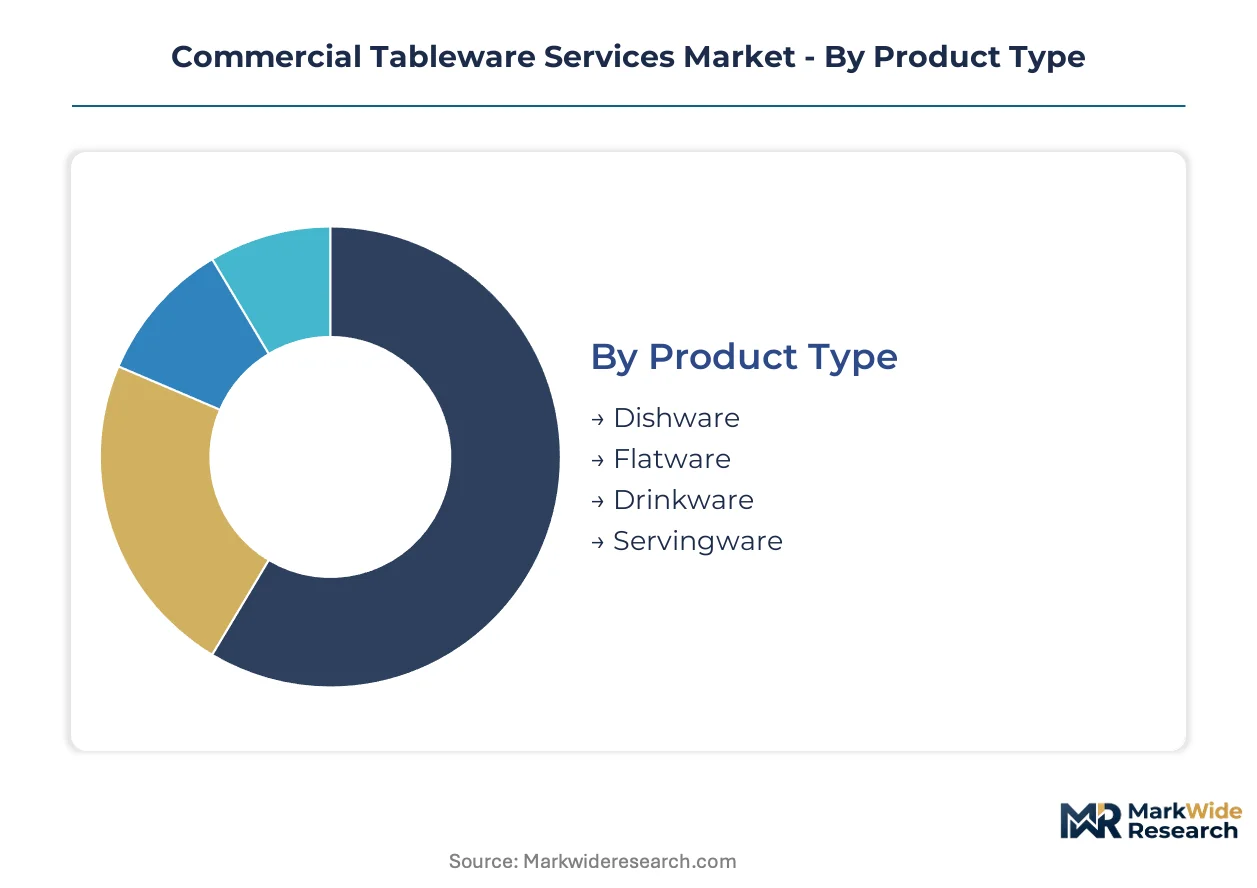
Segmentation within the commercial tableware services market is critical for understanding the diverse demands of hospitality operators and tailoring service offerings effectively. Analyzing these segments reveals varying operational requirements, investment cycles, and compliance pressures across different product types, materials, end users, and service models.
Product Type:
The operational cycle time for tableware varies significantly by product type, with some categories experiencing faster turnover and breakage rates than others.
- Dishware:Plates, bowls, and platters, often manufactured from vitrified porcelain or durable melamine, form the core of commercial food service. Hotels and catering services drive large-scale procurement, requiring high durability for repeated commercial dishwashing cycles and minimizing replacement costs.
- Flatware:Forks, knives, and spoons, primarily composed of 18/10 stainless steel, are essential for dining and designed for corrosion resistance and longevity. Restaurants and institutional food service necessitate robust, easily maintained flatware to minimize replacement costs from loss and wear.
- Drinkware:Glasses and cups, typically made from glass or polycarbonate, are critical for beverage service across all hospitality venues.
- Servingware:Platters, bowls, and specialized utensils are used for presenting food, often in buffet or event settings.
Dishware dominates the installed base. Flatware is where expansion concentrates.
Material:
Supply concentration for commercial tableware materials is influenced by manufacturing capabilities and raw material availability across different global regions.
- Porcelain:This high-fired ceramic ware is known for its non-porosity and strength, often super-vitrified for demanding commercial use. High-end hotels and fine dining establishments prioritize aesthetic appeal and chip resistance, driving sourcing from specialized manufacturers.
- Stainless Steel:Alloys like 18/10 or 18/0 are valued for corrosion resistance, strength, and ease of cleaning in commercial settings. Catering services and large-scale cafeterias require durable, cost-effective flatware that withstands industrial dishwashers.
- Melamine:This durable, lightweight plastic material is favored for casual dining and outdoor events due to its break resistance.
- Glass:A transparent, non-porous material used predominantly for drinkware, selected for clarity and thermal shock resistance.
Procurement patterns for Porcelain are undergoing significant transformation, while Stainless Steel maintains a stable sourcing base.
End User:
The volume requirements for commercial tableware services differ substantially across various end-user segments, impacting inventory scale and logistical complexity.
- Hotels:These multi-venue operations require extensive inventory for diverse dining concepts, from fine dining to banqueting. Large hotel chains often seek integrated service providers for consistent quality and centralized inventory management across properties.
- Catering Services:Event-driven businesses need flexible, scalable tableware solutions for varying guest counts and locations. Corporate events and large social gatherings increasingly rely on rental services to manage peak demand without capital expenditure.
- Restaurants:Independent and chain eateries require durable, aesthetically aligned tableware that reflects brand identity and withstands daily use.
- Cafés:Smaller establishments focused on quick service often opt for rental models to manage inventory and reduce upfront costs.
Hotels generate the highest volume throughput. Catering Services is gaining share fastest.
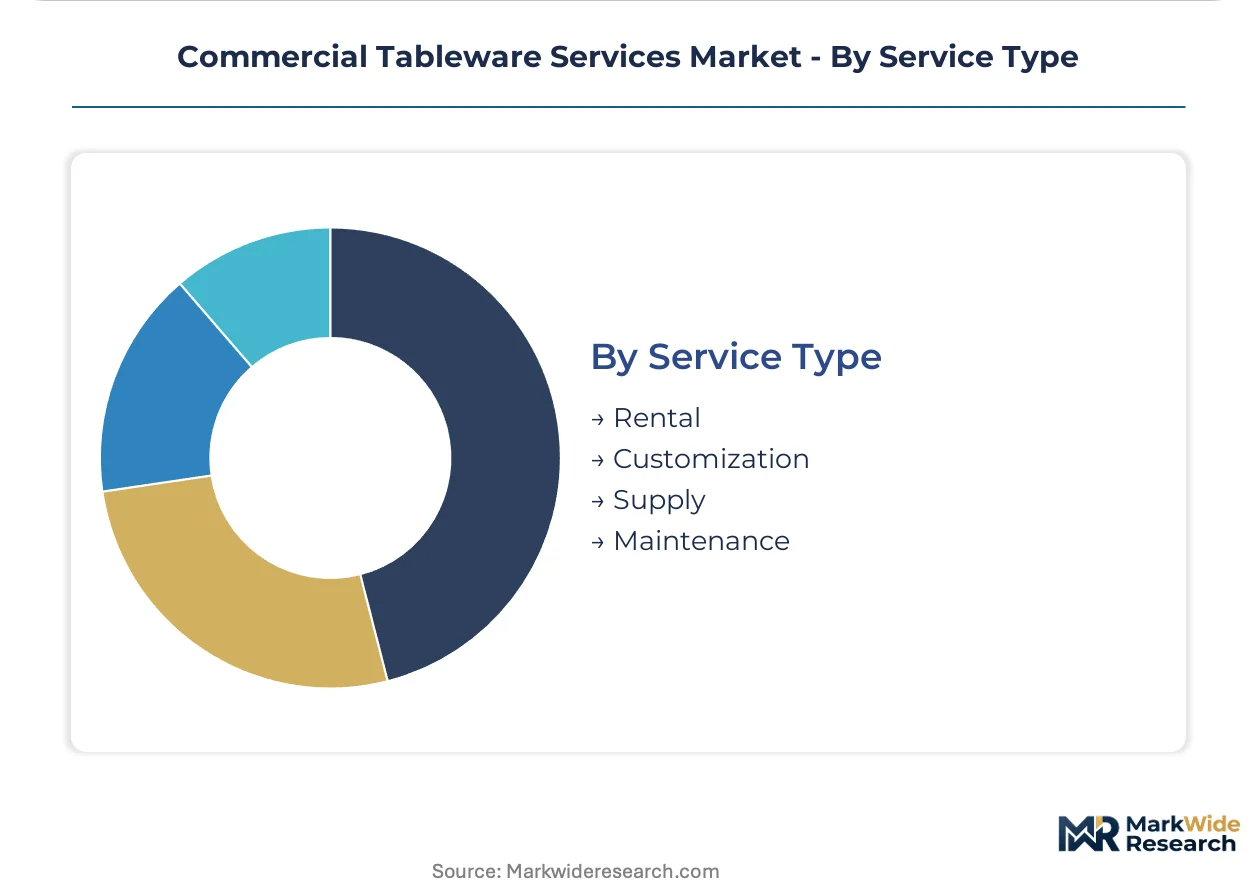
Service Type:
Customer types range from capital-expenditure-averse new businesses to established operators seeking long-term supply and maintenance solutions.
- Rental:This service involves the temporary provision of tableware, including delivery, pickup, and cleaning, bypassing client capital investment. New cafés and pop-up restaurants increasingly adopt rental services for operational flexibility and reduced overhead.
- Supply:This segment encompasses the direct sale of new tableware inventory to hospitality businesses for permanent ownership. Established hotel chains and large restaurant groups with stable operations prefer direct supply for long-term cost efficiency and brand consistency.
- Maintenance:Services include repair, refurbishment, and cleaning of client-owned tableware to extend asset life and ensure hygiene standards.
- Customization:This involves tailoring tableware with specific branding, logos, or unique designs, primarily for premium hospitality venues seeking differentiation.
Supply serves a broad customer base. Customization caters to specialized client needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for commercial tableware materials is influenced by manufacturing capabilities and raw material availability across different global regions. This dynamic shapes sourcing strategies for service providers and end-users. Regulatory frameworks also play a significant role in material selection and compliance costs.
China
China's expanding manufacturing base drives global supply for high-grade porcelain and melamine products. The country's GB standards for ceramics dictate material composition and testing protocols for exports. Production clusters in Jingdezhen continue to innovate in ceramic technology, influencing global pricing and availability for commercial buyers.
United States
Demand for durable tableware in the United States stems from its large hospitality sector and extensive catering services. The US Food and Drug Administration (FDA) governs food contact material safety, impacting sourcing decisions for service providers. Major tourism hubs like Las Vegas and Orlando create concentrated demand for rental and supply services.
Germany
Germany's robust hospitality market, particularly in fine dining, requires premium and design-led tableware solutions. European Food Safety Authority (EFSA) rules impose stricter limits on leachable heavy metals from ceramic ware. Cities such as Berlin and Munich, with their vibrant culinary scenes, drive demand for specialized service providers.
United Arab Emirates
The United Arab Emirates experiences rapid growth in its luxury hospitality and event sectors, fueling tableware service demand. Regulations from the Ministry of Health and Prevention (MOHAP) ensure hygiene and safety standards for food contact materials. Dubai's status as a global tourism and business hub concentrates significant procurement activities.
Commercial Tableware Services Market Key Industry Players
Premium product specialists and volume-driven service providers split the market for commercial tableware services. This structure reflects diverse client needs, from high-end hotels to large-scale catering operations. Strategic archetypes include design-led manufacturers, broad-line distributors, and material innovation leaders, each targeting distinct value propositions. Companies often engage in geographic expansion and portfolio diversification to capture market share and mitigate regional risks.
On the premium-tier vector, Villeroy & Boch exemplifies a brand focused on design-led collections for the high-end hospitality sector, anchoring its market presence through distinct aesthetic appeal. Churchill China, a UK-based ceramic manufacturer, represents durability and material innovation, particularly with its super-vitrified body products for demanding food service environments. Steelite International, an international distributor, occupies a position leveraging its extensive distribution network to serve hotel and restaurant chains across multiple continents, offering broad reach and reliable supply.
| Leading Market Players |
|---|
| Victorinox |
| Steelite International |
| Churchill China |
| Fiskars Group |
| Libbey |
| Cardinal International |
| Villeroy & Boch |
| Royal Doulton |
| Arc Group International |
| Others |
Cost & Logistics Intelligence
Commodity price volatility in high-grade stainless steel and specialized porcelain clays directly determines pricing tier spreads and shapes the global commercial tableware services supply chain.
Pricing Analysis
European Food Safety Authority (EFSA) rules dictating leachable heavy metals directly influence the pricing tier structure for commercial tableware. Pricing stratifies across premium, standard, and economy tiers, driven by quality grade, material certification, and bundled inventory management services. Pricing pressure stems from new businesses seeking rental models to avoid capital expenditure. New cafes and pop-up restaurants exhibit the highest price sensitivity, while large hotel chains prioritize long-term cost efficiency and consistent quality.
Supply Chain Analysis
The upstream feedstock for commercial tableware, particularly high-grade clays for porcelain and 18/10 stainless steel, originates primarily from concentrated global sources. China dominates porcelain and melamine manufacturing, while Germany and the UK contribute specialized materials and design. Regulatory restriction divergence, such as between US FDA and China GB standards, represents a structural risk for cross-border sourcing. Distribution runs through extensive networks and specialized rental service providers, managing inventory acquisition and maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
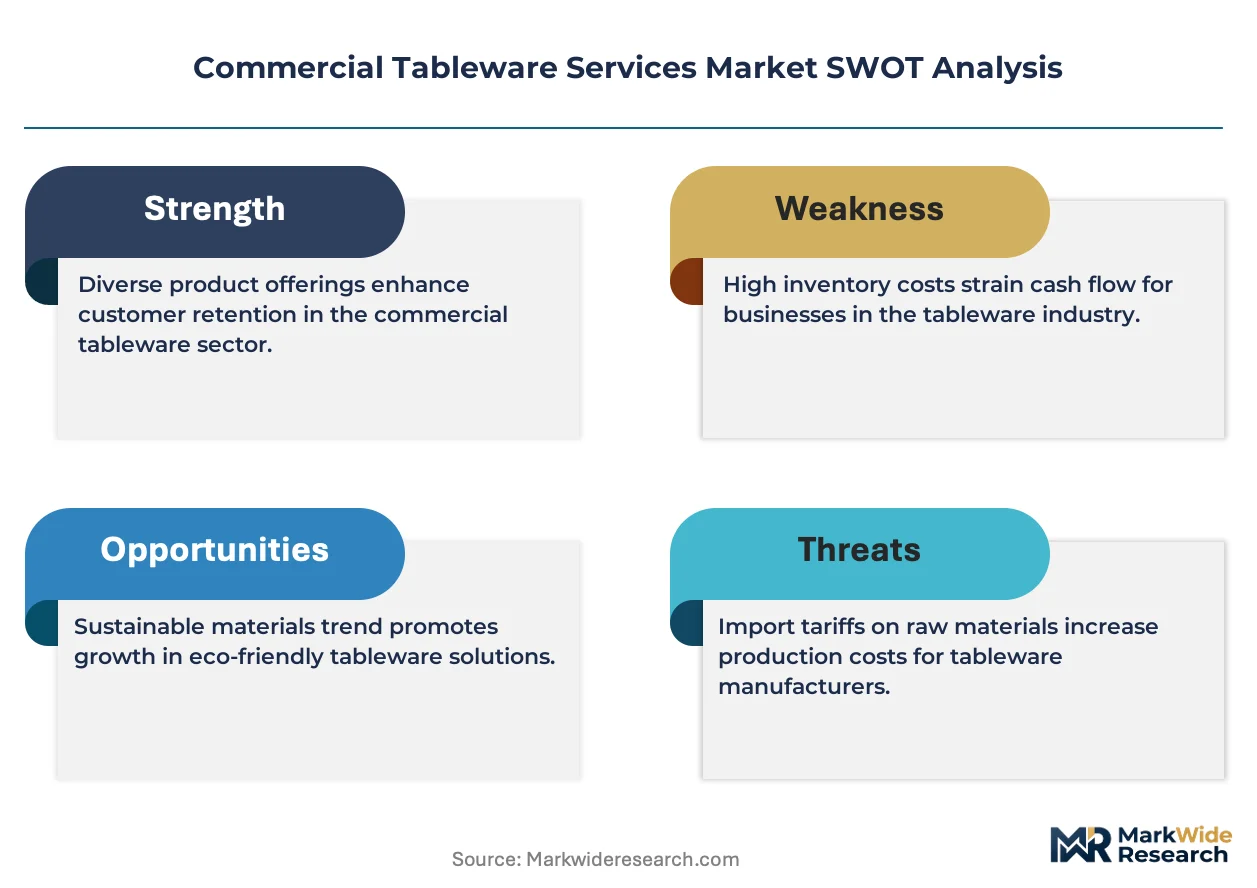
The commercial tableware services market presents a defensive moat, largely due to regulatory entrenchment that imposes significant compliance burdens and capital requirements on new entrants.
For Market Incumbents:Entrench existing client relationships by integrating advanced inventory management technologies like RFID tags into durable dishware. Deepen service specialization for niche sectors such as healthcare facilities, addressing their unique hygiene requirements. This strategy mitigates the threat from premium disposable tableware substitution and new capital-averse rental models, leveraging certification investment and channel control.
For New Entrants and Emerging Players:Pursue underpenetrated geographic markets in rapidly urbanizing regions, such as Southeast Asia, by establishing agile service hubs. Target new cafes, pop-up restaurants, and independent caterers in dynamic culinary hubs. A compelling go-to-market angle involves offering flexible, short-term rental agreements bundled with comprehensive maintenance and inventory tracking services.
For Investors and Strategic Acquirers:Technology-enabled rental service providers with strong regional footprints represent attractive acquisition targets in this stable market. The long-term viability remains robust, driven by persistent demand for outsourced services over the next decade. A key signal to watch for inflection is the increasing consolidation activity among regional tableware rental providers, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Integration (RFID) | Minimizes inventory shrinkage and automates tracking for large hospitality clients. |
| Service Specialization (Healthcare) | Opens new revenue streams by addressing specific hygiene requirements. |
| Geographic Expansion (Southeast Asia) | Captures growing demand in rapidly urbanizing, underpenetrated regions. |
| Material Innovation (Super-vitrified) | Enhances product durability, reducing replacement costs for demanding environments. |
| Compliance Certification Investment | Ensures adherence to evolving food contact material standards, mitigating regulatory risk. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, validating market dynamics with direct insights from hotel procurement managers, catering service owners, and tableware manufacturers. Secondary validation utilized publicly available data from EU food safety reports, US FDA guidelines, and hospitality industry association reports. This approach facilitated bottom-up and top-down triangulation of market size and growth drivers.
Forecast models were calibrated against historical market performance and projected industry-specific growth drivers across the analysis window. Quantitative models incorporated segmentation dimensions including product type, material, end user, service type, and regional regulatory frameworks. Compound annual growth rates were derived from projected volume and value trends, considering factors like hospitality development pipelines and single-use plastic ban enforcement.
Sensitivities concentrate around raw material price fluctuations and unforeseen geopolitical trade policies that could alter supply dynamics. Forecasts reflect assumptions regarding economic stability and regulatory enforcement. Cross-checking against external hospitality sector benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
India Retail Bubble Tea Kits Market
Food Service
Supermarkets Market
Food Service
Food Contract Manufacturing Market
Food Service
United States Full Service Restaurants Market
Food Service
Steam Tables and Food Well Market
Food Service
Commercial Air Fryer Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Food Service Dairy Products Market
Food Service
Lunch Takeout Market
Food Service
Food Trays Market
Food Service
Beverage Napkins Market
Food Service
North America Food Service Disposable Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Stirrers Market