
 US Food Service Market | 2026-2036
US Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
US Food Service Market Insights
Texas is reshaping national food service capacity as restaurant development and commissary construction accelerate across Dallas-Fort Worth and Houston. McDonald's Corporation leverages its scale to dominate drive-thru automation and digital infrastructure. Yum! Brands, Inc. anchors its multi-brand portfolio with sustained investment in KFC and Taco Bell kitchen modernization. Starbucks Corporation differentiates through in-house production of proprietary roasting and beverage systems.
US food service encompasses the preparation, distribution, and sale of meals and beverages through commercial establishments, spanning quick-service restaurants with average ticket times under five minutes to full-service dining with extended guest experiences. The sector operates through centralized supply chains integrating temperature-controlled logistics, standardized portion controls, and point-of-sale data capture to optimize labor deployment and inventory turns. Service type segmentation shows delivery and takeout channels capturing the fastest growth as off-premise consumption becomes habitual, while establishment size reveals large chains extracting margin advantages through procurement scale that independent operators cannot replicate. Cuisine type segmentation demonstrates Asian and Mexican formats expanding fastest in suburban markets where flavor novelty commands premium pricing.
FDA Food Code standards, USDA FSIS inspection protocols, and state-level health department licensing collectively shape operational compliance costs and market access thresholds for new entrants. OSHA workplace safety rules and EPA grease disposal regulations further constrain back-of-house design and labor scheduling decisions. Stakeholders must monitor how municipal zoning boards and state labor classification rules affect ghost kitchen viability and third-party delivery economics.
Market Dynamics
Digital ordering infrastructure is compressing order-to-delivery cycles across US food service, forcing capital reallocation from front-of-house labor to back-of-house automation and data analytics capabilities.
Growth Catalysts
- Off-premise consumption habits:Suburban households now treat delivery and curbside pickup as default meal solutions, expanding addressable market for commissary kitchens and ghost kitchen operators in Texas and Florida metro corridors.
- FDA Food Code modernization:Updated temperature control and allergen disclosure mandates are accelerating equipment replacement cycles, pulling forward demand for IoT-enabled refrigeration and automated labeling systems.
- Dual-income household time scarcity:Working parents in Dallas-Fort Worth and Houston trade meal preparation for convenience, concentrating volume in quick-service formats with sub-five-minute ticket times.
Market Restraints
- Protein input volatility:Beef and poultry price swings compress margin predictability for full-service operators unable to pass through costs via dynamic menu pricing.
- Third-party delivery platform concentration:Route density economics favor two dominant intermediaries, extracting 15-30% per-order commissions that independent restaurants cannot absorb without volume sacrifice.
- Labor classification friction:State-level gig economy rulings in California and New York create compliance template risk that multi-state chains must price into expansion models.
Strategic Opportunities
- Central kitchen consolidation:Regional commissary networks in Houston and Phoenix enable multi-brand operators to share prep capacity, reducing per-unit real estate footprints.
- USDA FSIS alternative protein pathway:Cultivated meat and precision fermentation approvals open premium menu positioning for early-adopter chains with R&D capital.
- Voice-activated drive-thru ordering:Natural language processing convergence with kitchen display systems reduces order error rates and compresses service times during peak traffic windows.
Industry Challenges
- Line cook skill scarcity:Immigration policy constraints and wage competition from warehousing reduce applicant pools for back-of-house positions in high-cost metros.
- Legacy POS integration complexity:Franchise systems running decade-old payment infrastructure face multi-year timelines to unify data streams across ordering, inventory, and labor modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Food Service Market |
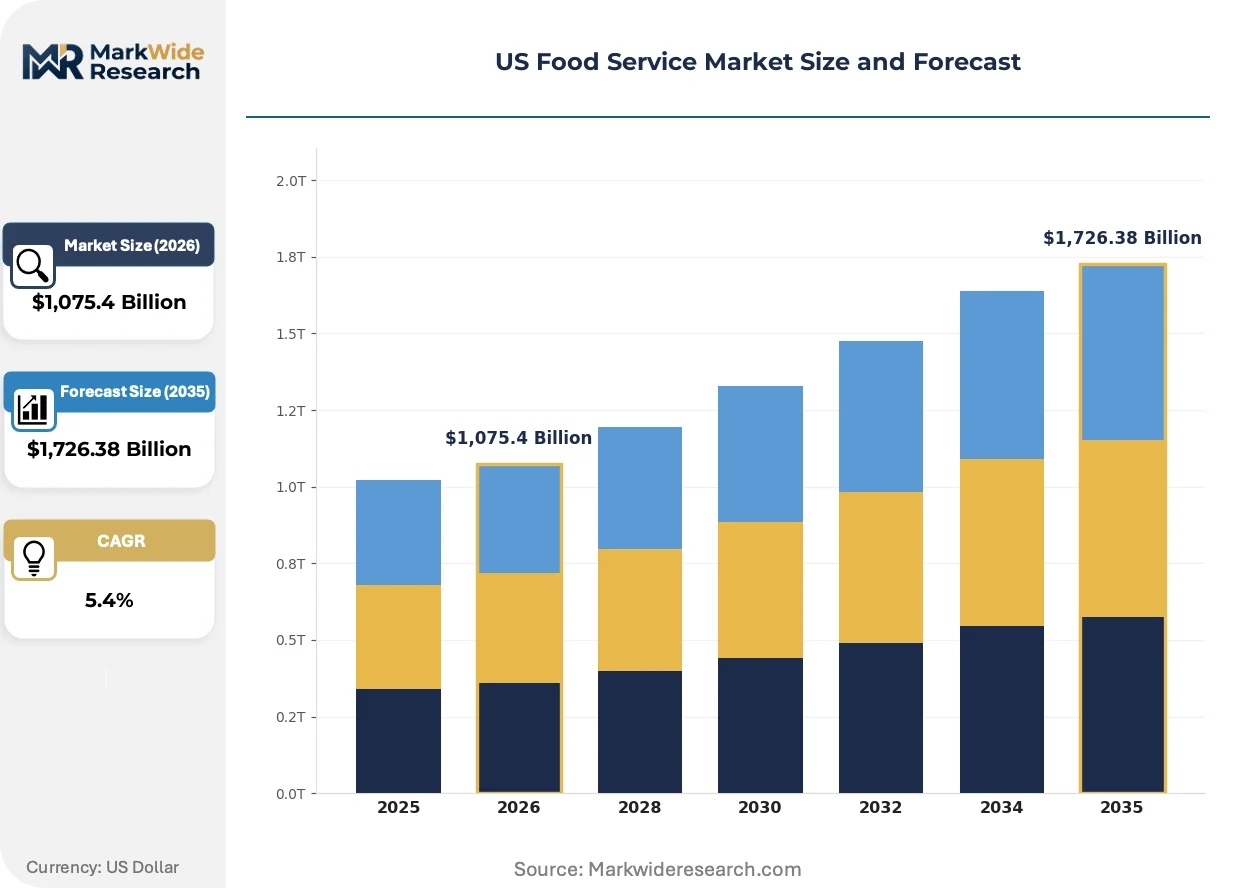
| Market Size in 2026 | $1,075.4 Billion |
| Market Size in 2035 | $1,726.38 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-in, Takeout, Delivery, Catering Customer Type: Families, Couples, Business Professionals, Tourists Cuisine Type: Italian, Asian, American, Mexican Establishment Size: Independent, Small Chain, Large Chain, Franchise |
| Companies Covered | McDonald's Corporation, Yum! Brands, Inc., Starbucks Corporation, Darden Restaurants, Inc., Restaurant Brands International, Compass Group Plc, Aramark Corp, Sodexo SA, Subway IP Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Food Service Market Trends and Innovations
Automation is migrating from experimental pilot to production-scale deployment across US food service, redefining labor allocation and capital intensity benchmarks for both quick-service and full-service formats.
Kitchen robotics is migrating from fry-station automation to integrated prep-line systems. Mid-scale burger chains in Texas and Florida are deploying robotic patty flippers and automated beverage dispensers to maintain throughput during labor shortages. The technology is migrating from point solutions toward end-to-end kitchen orchestration that compresses labor hours per cover.
OSHA workplace safety enforcement is intensifying scrutiny of back-of-house ergonomics and slip hazards. The agency's updated guidance on repetitive motion injuries is forcing equipment redesigns for manual prep stations. Full-service operators in high-litigation states are responding with anti-fatigue flooring investments and automated lifting aids for bulk ingredient handling.
Subscription-based meal programs are displacing traditional loyalty points as the primary customer retention mechanism. Quick-service chains in suburban Dallas and Orlando markets bundle daily coffee or weekly family meal kits into recurring revenue streams. This shift is most visible among dual-income households seeking predictable meal budgeting without cooking time sacrifice.
US Food Service Market Segmentation
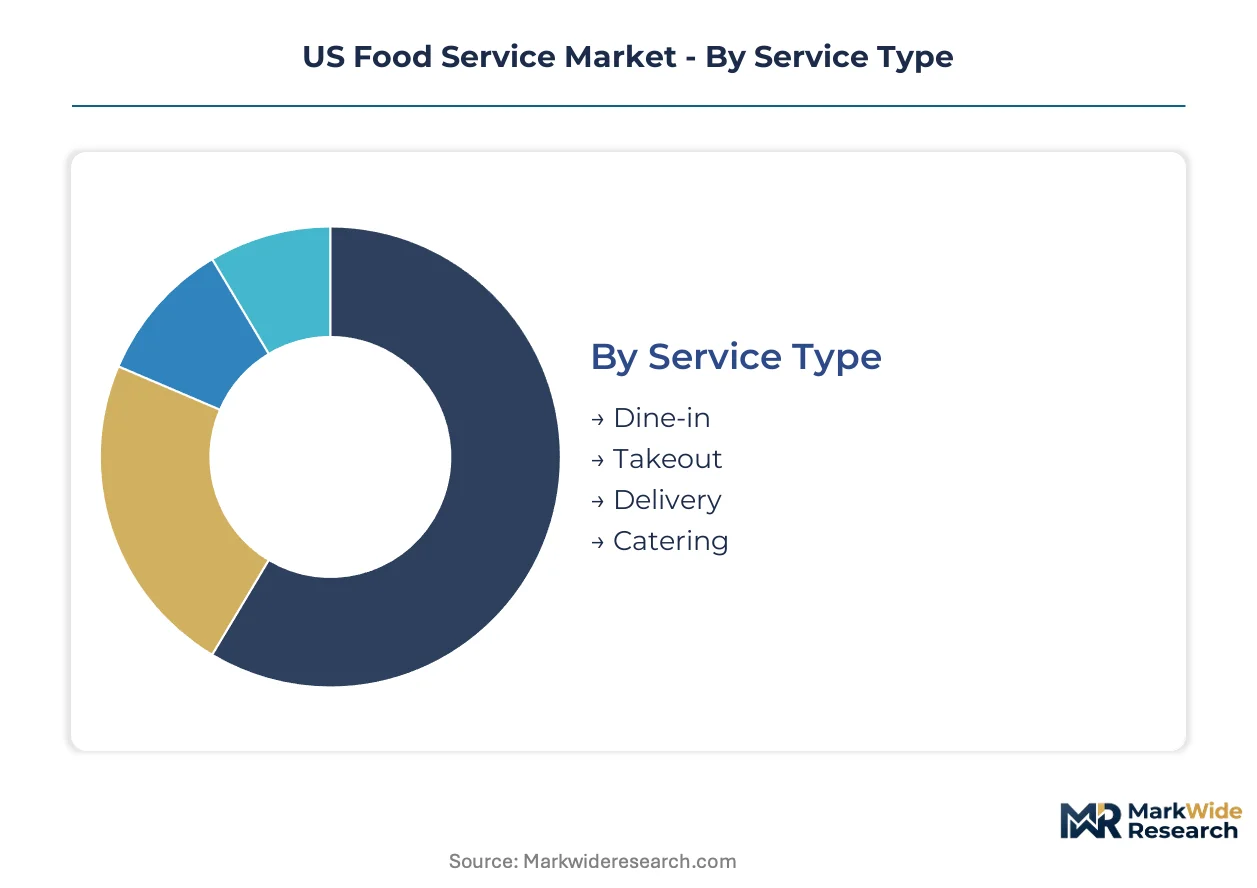
Segmentation in US food service reveals how operational models, customer behaviors, and cuisine preferences concentrate purchasing power across distinct channels. Chains calibrate capital deployment and menu engineering against these divisions to capture volume in Texas and Florida metros where population migration is accelerating.
Service Type:
After-sales service intensity varies sharply across service types, with delivery platforms demanding 24/7 technical support for routing algorithms while dine-in operators prioritize facility maintenance contracts.
- Delivery:Third-party platform integration requires continuous API maintenance and real-time order tracking infrastructure. Dallas-Fort Worth and Houston operators absorb 15-30% per-order commissions while competing on speed guarantees during peak windows.
- Takeout:Curbside pickup systems demand dedicated parking logistics and mobile notification infrastructure. Florida suburban households treat this channel as default meal solutions, expanding addressable market for ghost kitchen operators.
- Dine-in:Full-service formats depend on reservation systems and front-of-house labor scheduling optimization.
- Catering:Large-event contracts require advance production planning and specialized transport equipment for temperature-controlled delivery.
By volume, Takeout leads. By growth pace, Delivery is climbing the fastest.
Customer Type:
Cost tier differentiation separates premium experience seekers from convenience-driven segments, with business professionals commanding highest per-check averages during weekday lunch windows.
- Business Professionals:Time-constrained weekday demand concentrates in quick-service formats with sub-five-minute ticket times. Downtown Dallas and Houston CBD locations capture recurring corporate catering contracts.
- Families:Multi-person checks drive value-menu engineering and kid-friendly portion standardization. Suburban Orlando and Phoenix operators bundle family meal kits into subscription revenue streams.
- Couples:Date-night occasions support premium pricing for full-service establishments with extended guest experiences.
- Tourists:Seasonal volume spikes in Florida and Texas destination markets require flexible staffing models.
By volume, Families dominate. By margin expansion, Business Professionals show steepest trajectory.
Cuisine Type:
Application versatility distinguishes cuisines with modular prep systems from those requiring specialized equipment, affecting kitchen capital requirements and real estate flexibility.
- Asian:Wok stations and steam equipment demand dedicated ventilation infrastructure. Suburban Texas markets command premium pricing for flavor novelty in fast-casual formats.
- Mexican:Tortilla production lines and salsa prep stations enable high-throughput assembly. Florida metro corridors show fastest format expansion among cuisine types.
- American:Burger and sandwich formats dominate drive-thru automation investments with standardized portion controls.
- Italian:Pasta and pizza production requires specialized ovens and extended prep timelines for sauce bases.
By unit count, American leads. By format innovation, Asian is gaining share fastest.
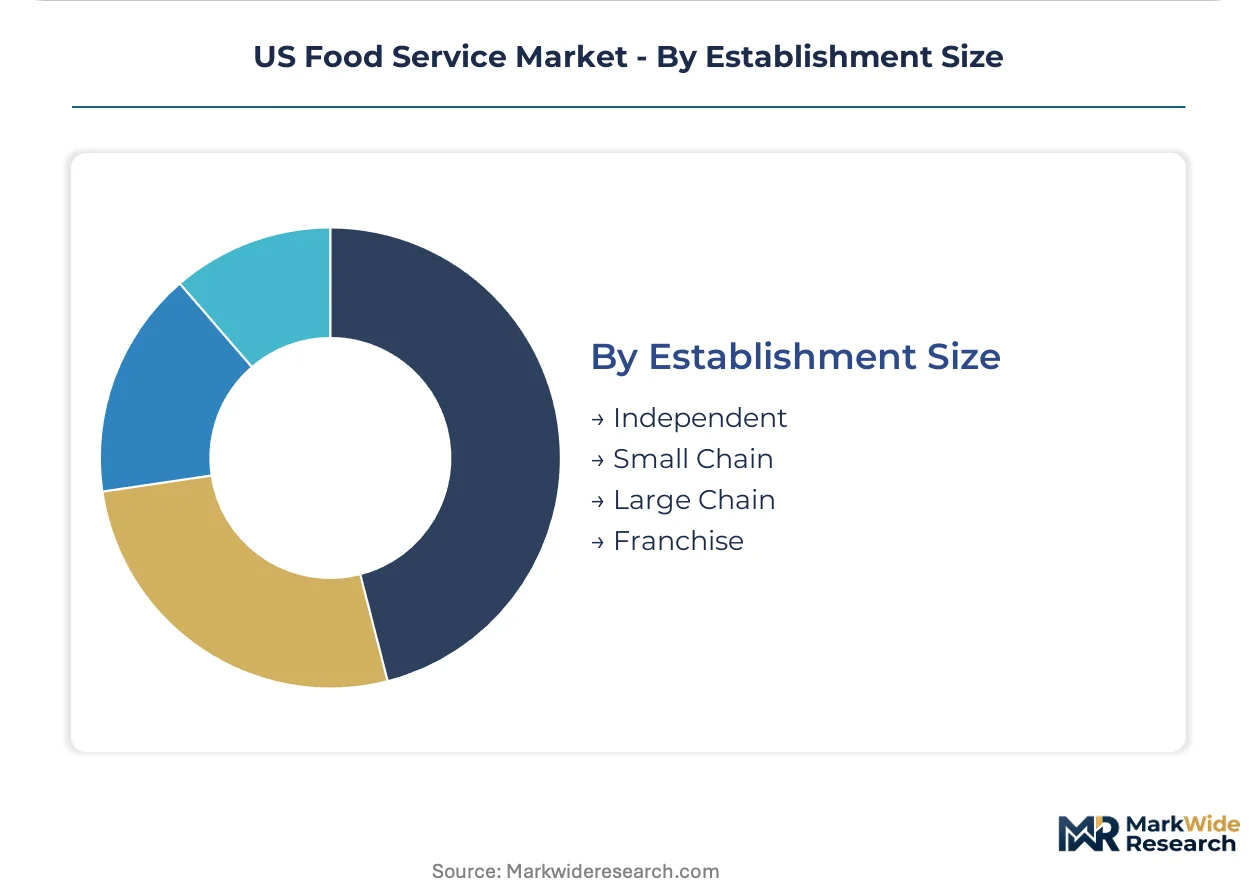
Establishment Size:
Supply concentration creates divergent procurement economics, with large chains extracting margin advantages through centralized purchasing that independent operators cannot replicate.
- Large Chain:National procurement scale enables direct supplier negotiations and private-label ingredient development. McDonald's and Yum! Brands leverage this structure for drive-thru automation and digital infrastructure deployment.
- Franchise:Royalty structures and mandated equipment packages standardize operations across dispersed ownership. Texas and Florida franchisees absorb compliance costs from FDA Food Code modernization.
- Small Chain:Regional density supports limited centralized commissary investment without national distribution complexity.
- Independent:Single-location operators face third-party delivery commission burdens and legacy POS integration constraints.
By revenue concentration, Large Chain leads. By entry velocity, Franchise shows strongest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Restaurant development and commissary construction concentrate in Texas and Florida metros where population migration accelerates. Dallas-Fort Worth and Houston anchor national food service capacity expansion. Orlando and Miami corridors drive Southeast format innovation.
Texas
Dual-income household time scarcity and suburban sprawl fuel quick-service demand across Dallas-Fort Worth and Houston. FDA Food Code modernization tightens temperature control compliance for operators. McDonald's and Yum! Brands deploy drive-thru automation at scale in Houston's Energy Corridor and Dallas's Legacy West.
Florida
Tourist volume spikes and retiree population density sustain year-round restaurant demand in Orlando and Miami-Dade. State health department licensing aligns with federal allergen disclosure mandates. Ghost kitchen operators cluster in Tampa Bay and Jacksonville suburbs serving delivery-first households.
California
Tech sector employment density supports premium fast-casual expansion in San Francisco Bay and Los Angeles basins. State-level gig economy rulings on labor classification create compliance template risk for multi-state chains. Central kitchen consolidation accelerates in Ontario and Fresno to serve regional franchise networks.
New York Metro
Business professional lunch demand concentrates in Manhattan and Brooklyn quick-service corridors with sub-five-minute ticket requirements. OSHA workplace safety enforcement intensifies back-of-house ergonomics scrutiny. Full-service operators in Hudson Yards and Long Island City absorb anti-fatigue flooring investments.
Arizona
Phoenix metro population growth and retiree migration expand addressable market for commissary kitchen networks. EPA grease disposal regulations constrain back-of-house design in desert water-scarce environments. Regional commissary networks enable multi-brand operators to share prep capacity across Scottsdale and Tempe.
US Food Service Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in equipment and ingredient supply. The vendor base stratifies into national chains with procurement scale, franchise systems with standardized operations, and independent operators facing third-party delivery commission burdens. Two dominant competitive moves define current positioning: drive-thru automation deployment compressing service times, and central kitchen consolidation reducing per-unit real estate footprints.
Within the platform integrator tier, McDonald's Corporation and Yum! Brands, Inc. exemplify scale-driven automation strategies, while Starbucks Corporation occupies a position emphasizing in-house production systems. These three anchors demonstrate how large chains extract margin advantages through procurement scale that independent operators cannot replicate.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Yum! Brands, Inc. |
| Starbucks Corporation |
| Darden Restaurants, Inc. |
| Restaurant Brands International |
| Compass Group Plc |
| Aramark Corp |
| Sodexo SA |
| Subway IP Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Texas commissary networks is compressing procurement timelines and forcing large chains to front-load equipment investments while independent operators absorb spot-market protein premiums. FDA Food Code modernization tightens compliance thresholds that reshape supplier qualification criteria and equipment replacement cycles across Dallas-Fort Worth and Houston corridors.
Pricing Analysis
FDA Food Code standards dictate the pricing tier structure across quick-service and full-service formats. Three-tier pricing structure across premium, standard, and economy levels separates enterprise chains with procurement scale from franchise systems with mandated equipment packages and independent operators facing third-party delivery commission burdens. Price differentiation rests on volume scale and vertical integration depth. Cost compression in the independent tier is intensifying because third-party platform concentration extracts 15-30% per-order commissions. Business professionals show lowest price sensitivity due to time-scarcity premiums, while families exhibit highest elasticity around value-menu positioning.
Supply Chain Analysis
Export-control restrictions on IoT-enabled refrigeration components limit equipment upgrade velocity for mid-scale operators. Geographic supply concentration centers on domestic protein processing hubs in Nebraska and Iowa, temperature-controlled logistics networks spanning Texas and Florida, and automated kitchen equipment manufacturing clusters in Illinois and Ohio. Raw material dependencies include beef and poultry inputs, specialized refrigeration compressors, and automated labeling systems. Single-source vulnerability runs through concentrated third-party delivery platform intermediaries. Distribution runs through centralized commissary networks feeding multi-brand operators in Houston and Phoenix metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large chains with procurement scale as independent operator fragmentation accelerates consolidation pressure across Texas and Florida markets.
For Market Incumbents: Insulate margin position through backward integration into proprietary commissary networks and captive supply of temperature-controlled logistics capacity. McDonald's and Yum! Brands demonstrate how drive-thru automation deployment compresses labor hours per cover while digital infrastructure locks in repeat purchase frequency. Threat substitution from ghost kitchen operators demands channel control investments in delivery-first suburban corridors. For New Entrants and Emerging Players: Establish a beachhead in Asian fast-casual formats across suburban Dallas and Orlando markets where flavor novelty commands premium pricing. White-space targets include voice-activated drive-thru systems for mid-scale burger chains and subscription-based meal programs for dual-income households. Go-to-market angle centers on USDA FSIS alternative protein pathway positioning for cultivated meat menu integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based meal program operators with established suburban household penetration. Long-term viability favors franchise systems with standardized equipment packages and mandated digital infrastructure compliance. Acquisition target archetype includes regional commissary networks enabling multi-brand prep capacity sharing. Signal to watch is FDA alternative protein approval velocity as inflection indicator for premium menu positioning capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Central Kitchen Consolidation | Reduces per-unit real estate footprints across Houston and Phoenix metro networks. |
| Drive-Thru Automation Deployment | Compresses service times during peak traffic windows at McDonald's and Yum! Brands locations. |
| Alternative Protein Menu Integration | Captures premium positioning through USDA FSIS cultivated meat approval pathway. |
| Subscription Revenue Program Launch | Locks in predictable cash flows from dual-income households in suburban Dallas corridors. |
| Third-Party Platform Diversification | Mitigates 15-30% commission exposure for independent operators in Florida delivery markets. |
Research Methodology
Cross-validation between franchise operations executives and equipment procurement directors anchors the qualitative findings across the US food service landscape. Primary interviews with supply chain managers, restaurant development officers, FDA compliance consultants, and third-party delivery platform strategists combine with secondary validation from FDA Food Code documentation, USDA FSIS inspection protocols, state health department licensing records, and SEC 10-K filings from publicly traded chains. Bottom-up unit economics modeling and top-down market sizing triangulate volume estimates.
Calibration against historical equipment replacement cycles and protein price volatility patterns shapes the analytical framework across the projection horizon. Segmentation dimensions include service type, customer archetype, cuisine format, and establishment size tier. CAGRs derive from trend extrapolation of digital ordering penetration and automation deployment curves. Industry-specific inputs incorporate FDA Food Code modernization timelines and off-premise consumption habit stickiness indices.
Sensitivities concentrate around labor classification rulings in California and New York, protein input volatility, and third-party delivery platform commission structures. Forecasts reflect assumptions on population migration velocity into Texas and Florida corridors. Material shifts in FDA alternative protein approval timelines or OSHA workplace safety enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Vending Machine Market
Food Service
Turkey Food Service Market
Food Service
Commercial Tableware Services Market
Food Service
Rotisseries Market
Food Service
Singapore Food Service Market
Food Service
Food Service Dairy Products Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Sandwich Toasters Market
Food Service
Gas Floor Fryers Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
Hospital Food Services Market
Food Service
Foodservice Coffee Market
Food Service
Germany Foodservice Market
Food Service
Spain Food Service Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Pasteurized Eggs Market