
 SF6 Gas Circuit Breaker Market | 2026-2036
SF6 Gas Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
SF6 Gas Circuit Breaker Market Intelligence
Utility procurement channels across Asia-Pacific and the Middle East is rewriting how OEMs allocate manufacturing capacity and field-service resources. Mitsubishi Electric Corporation leverages its domestic Japanese production base to anchor high-voltage contracts across Southeast Asian grid operators. Siemens AG competes through localized assembly footprints in India and the Gulf, while ABB Group sustains aftermarket service revenues through long-term asset-management contracts with European transmission system operators.
An SF6 gas circuit breaker is a high-voltage switching device that uses sulfur hexafluoride gas as an arc-quenching and insulating medium, typically rated from 72.5 kV to 800 kV, with interrupting capacities exceeding 63 kA in extra-high-voltage configurations. The gas's dielectric strength roughly three times that of air permits compact designs essential for urban substations where land scarcity constrains equipment footprints. Outdoor circuit breakers dominate installed-base volumes across mature transmission grids, though gas-insulated circuit breakers command premium positioning in dense metropolitan corridors and offshore platform applications. High-voltage and extra-high-voltage categories concentrate margin pools, while medium-voltage segments face price pressure from vacuum interrupter substitution in distribution networks.
The European Environment Agency enforces F-Gas Regulation phasedown mandates that constrain SF6 procurement volumes and mandate comprehensive leak-detection protocols across switchgear fleets. The EPA in the United States parallels this trajectory through voluntary partnership programs and emerging state-level reporting requirements that elevate total-cost-of-ownership calculations for utilities. China's MEE has incorporated SF6 emissions monitoring into provincial environmental compliance audits, reshaping procurement criteria for domestic grid equipment tenders. Stakeholders must weigh gas recycling infrastructure investments against accelerated development of fluoronitrile and vacuum hybrid technologies before regulatory thresholds harden across multiple jurisdictions.
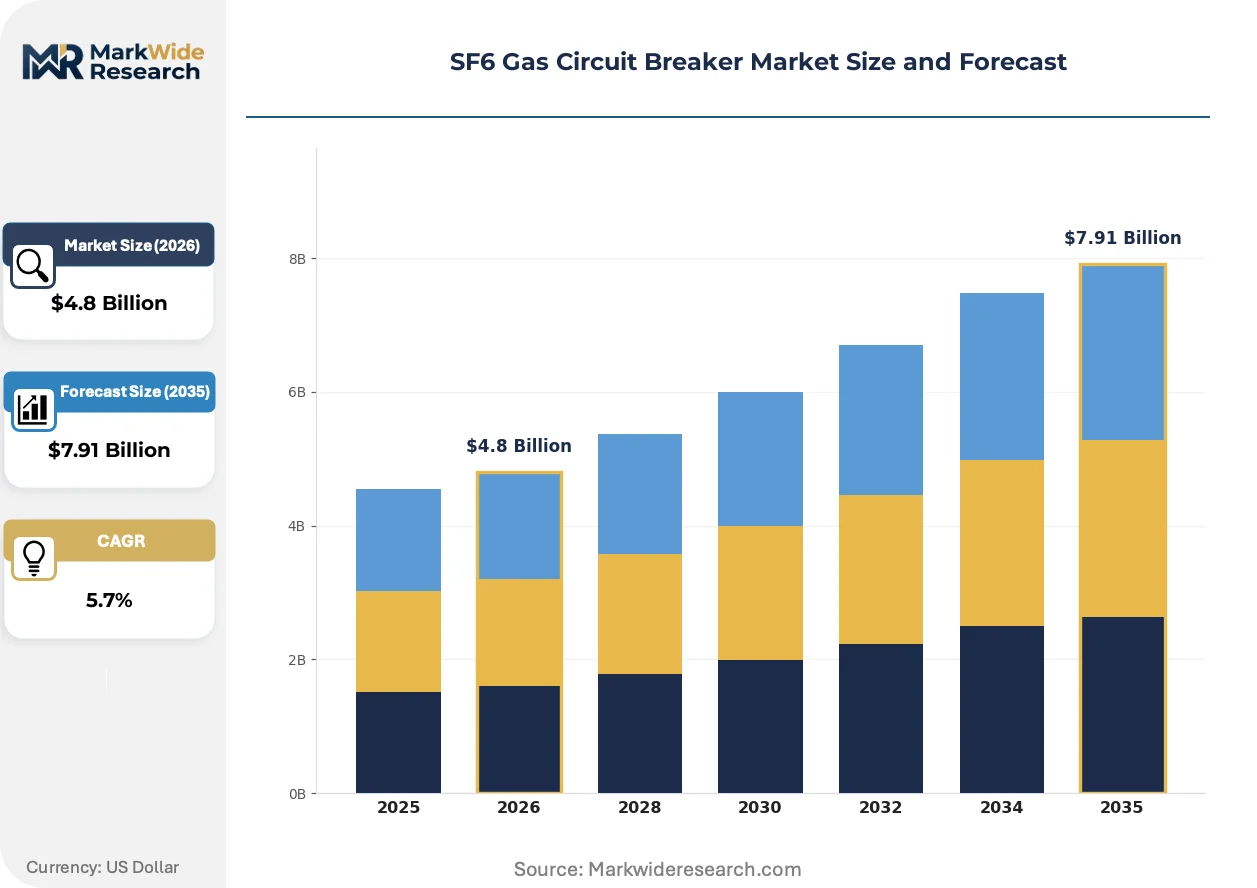
Market Dynamics
EU F-Gas Regulation phasedown mandates are compressing available SF6 volumes while simultaneously accelerating capital flows into alternative arc-quenching chemistries and gas recycling infrastructure across transmission equipment supply chains.
Growth Catalysts
- Utility-scale renewable integration:State transmission utilities in India are modernizing aging substations under central grid-strengthening programs to accommodate solar and wind capacity additions.
- F-Gas Regulation compliance:The European Environment Agency's tightening emission thresholds are compelling manufacturers to accelerate gas recycling and alternative insulation R&D investments.
- Urban land scarcity:Metropolitan substation operators in Japan and South Korea are specifying compact gas-insulated designs where dielectric strength requirements exceed air-insulated alternatives.
Market Restraints
- SF6 supply concentration:Specialty gas production concentrates among a limited cohort of chemical manufacturers, exposing procurement costs to feedstock volatility and capacity allocation decisions.
- Fluoronitrile technical limitations:Alternative insulation mediums currently exhibit lower interrupting performance at extra-high-voltage ratings above 420 kV, constraining substitution timelines.
- Leak-detection compliance costs:Comprehensive monitoring protocols mandated by EPA partnership programs and emerging state-level reporting requirements elevate total-cost-of-ownership calculations for North American utilities.
Strategic Opportunities
- Offshore platform electrification:North Sea and Gulf of Mexico oilfield operators are specifying gas-insulated switchgear for space-constrained topside installations where salt corrosion accelerates equipment degradation.
- China's dual carbon alignment:The Ministry of Ecology and Environment has incorporated SF6 emissions monitoring into provincial environmental compliance audits, reshaping procurement criteria for domestic grid equipment tenders.
- Vacuum-SF6 hybrid architectures:Converging vacuum interrupter technology with gas-insulated housing designs offers medium-voltage migration paths for distribution network operators seeking phased transition strategies.
Industry Challenges
- Field technician certification gaps:Gas handling and leak-detection protocols require specialized training that outpaces workforce development programs at utilities and service contractors.
- Legacy asset integration complexity:Retrofitting digital monitoring systems onto installed-base circuit breakers manufactured before 2010 demands custom engineering that fragments project economics.
- Recycling infrastructure capex intensity:On-site gas reclamation facilities require substantial capital deployment that conflicts with transmission operator OPEX preference structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SF6 Gas Circuit Breaker Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor Circuit Breakers, Indoor Circuit Breakers, Hybrid Circuit Breakers, Gas-insulated Circuit Breakers End User: Utilities, Industrial, Commercial, Renewable Energy Voltage Level: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage Installation Type: Fixed Installation, Portable Installation, Modular Installation, Retrofitting |
| Companies Covered | Mitsubishi Electric Corporation, Toshiba Corporation, Schneider Electric SE, Larsen & Toubro Limited, Fuji Electric Co., Ltd., Siemens AG, Hitachi T&D Solutions, Inc., Kirloskar Electric Company, ABB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SF6 Gas Circuit Breaker Market Strategic Shifts & Innovations
Technology substitution pressures and regulatory emission ceilings are converging to restructure competitive advantage around gas management capabilities rather than pure manufacturing scale.
Fluoronitrile (C4F7N) blended with carbon dioxide is collapsing the technical barrier between vacuum interrupters and gas-insulated designs for medium-voltage applications. European transmission system operators are piloting this chemistry in 145 kV substations where footprint constraints previously mandated SF6. The substitution is collapsing premium pricing power for conventional gas-insulated equipment in the 72.5-145 kV range.
China's MEE has embedded SF6 emissions intensity metrics into provincial environmental audits for grid equipment procurement. Industrial consequence includes mandatory gas recycling documentation and leak-rate disclosure in state-owned utility tenders. High-voltage categories face the steepest compliance burden, while medium-voltage segments pivot faster toward vacuum alternatives.
Long-term asset-management contracts are displacing transactional equipment sales among European transmission system operators. ABB Group and Siemens AG are restructuring revenue models around availability guarantees and predictive maintenance subscriptions. This behavioral shift concentrates most visibly in Germany and France where regulator-approved cost-recovery mechanisms favor operational expenditure treatment over capitalized equipment purchases.
SF6 Gas Circuit Breaker Market Segmentation
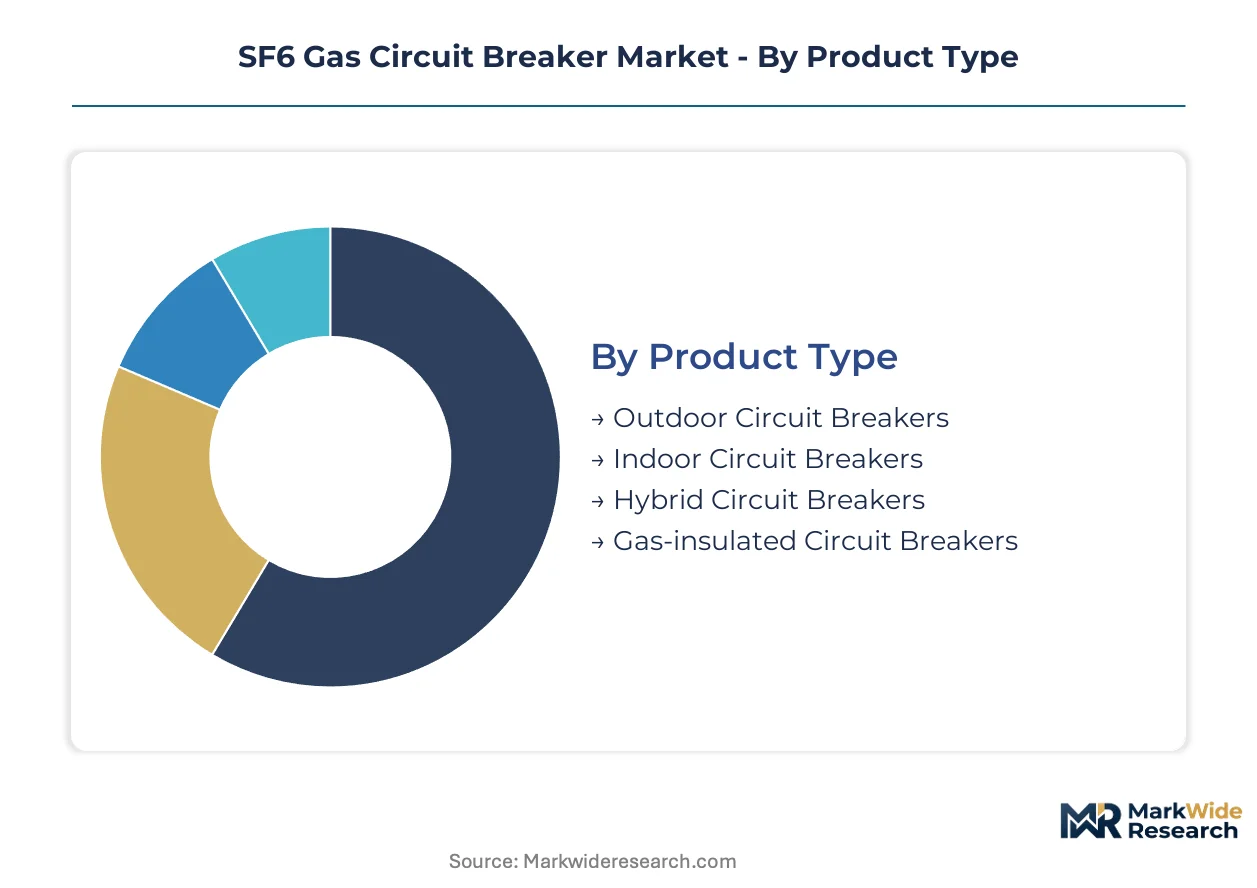
SF6 circuit breaker procurement varies sharply by operating environment and voltage class. Replacement cycles stretch from 15 years in distribution networks to 40-plus years in transmission infrastructure, creating divergent revenue timing for manufacturers.
Product Type:
Outdoor designs turn over slowest due to transmission-grade durability, while indoor and hybrid formats refresh faster as urban utilities modernize space-constrained substations.
- Outdoor Circuit Breakers:Air-insulated designs rated 72.5 kV to 800 kV dominate rural and suburban transmission corridors. State transmission utilities in India are modernizing aging outdoor installations under central grid-strengthening programs to accommodate solar and wind integration.
- Gas-insulated Circuit Breakers:Compact SF6-insulated housings achieve dielectric strength roughly three times that of air, essential for metropolitan substations where land scarcity constrains equipment footprints. Metropolitan operators in Japan and South Korea specify these designs where density exceeds air-insulated alternatives.
- Indoor Circuit Breakers:Enclosed switchgear for controlled-environment substations and industrial facilities.
- Hybrid Circuit Breakers:Combine gas-insulated bus sections with air-insulated breaker compartments for mid-cost installations.
Outdoor circuit breakers dominate installed base. Gas-insulated designs are where expansion concentrates.
End User:
Cost tiering separates capital-intensive transmission utilities from price-sensitive commercial buyers, with industrial and renewable segments occupying intermediate positions.
- Utilities:Transmission system operators specify 245 kV to 800 kV equipment with interrupting capacities exceeding 63 kA. European TSOs are restructuring procurement toward long-term asset-management contracts with availability guarantees and predictive maintenance subscriptions.
- Renewable Energy:Utility-scale solar and wind farms require circuit breakers for collector substations and grid-connection points. Asia-Pacific developers are expanding transmission networks to accommodate renewable capacity additions, driving specification of high-voltage outdoor designs.
- Industrial:Manufacturing complexes and process plants specify medium-voltage protection for captive substations.
- Commercial:Data centers, hospitals, and large facilities procure low-to-medium voltage switchgear with emphasis on footprint and reliability.
Utilities command the premium tier. Renewable energy developers are gaining share fastest.
Voltage Level:
Volume concentrates at medium voltage where distribution networks proliferate, while margin pools deepen at extra-high voltage where technical barriers limit competition.
- High Voltage:Equipment rated 72.5 kV to 245 kV serves regional transmission and large industrial interconnections. China's MEE has embedded SF6 emissions intensity metrics into provincial environmental audits, reshaping procurement criteria for high-voltage state-owned utility tenders.
- Extra High Voltage:Systems above 245 kV handle interstate and interregional power transfers with minimal losses. Fluoronitrile alternatives currently exhibit lower interrupting performance above 420 kV, constraining substitution timelines and preserving SF6 demand in this tier.
- Medium Voltage:Distribution networks from 1 kV to 72.5 kV face price pressure from vacuum interrupter substitution.
- Low Voltage:Secondary distribution and end-user protection, largely served by air and vacuum technologies.
Medium voltage ships the highest unit volumes. Extra high voltage captures the steepest expansion trajectory.
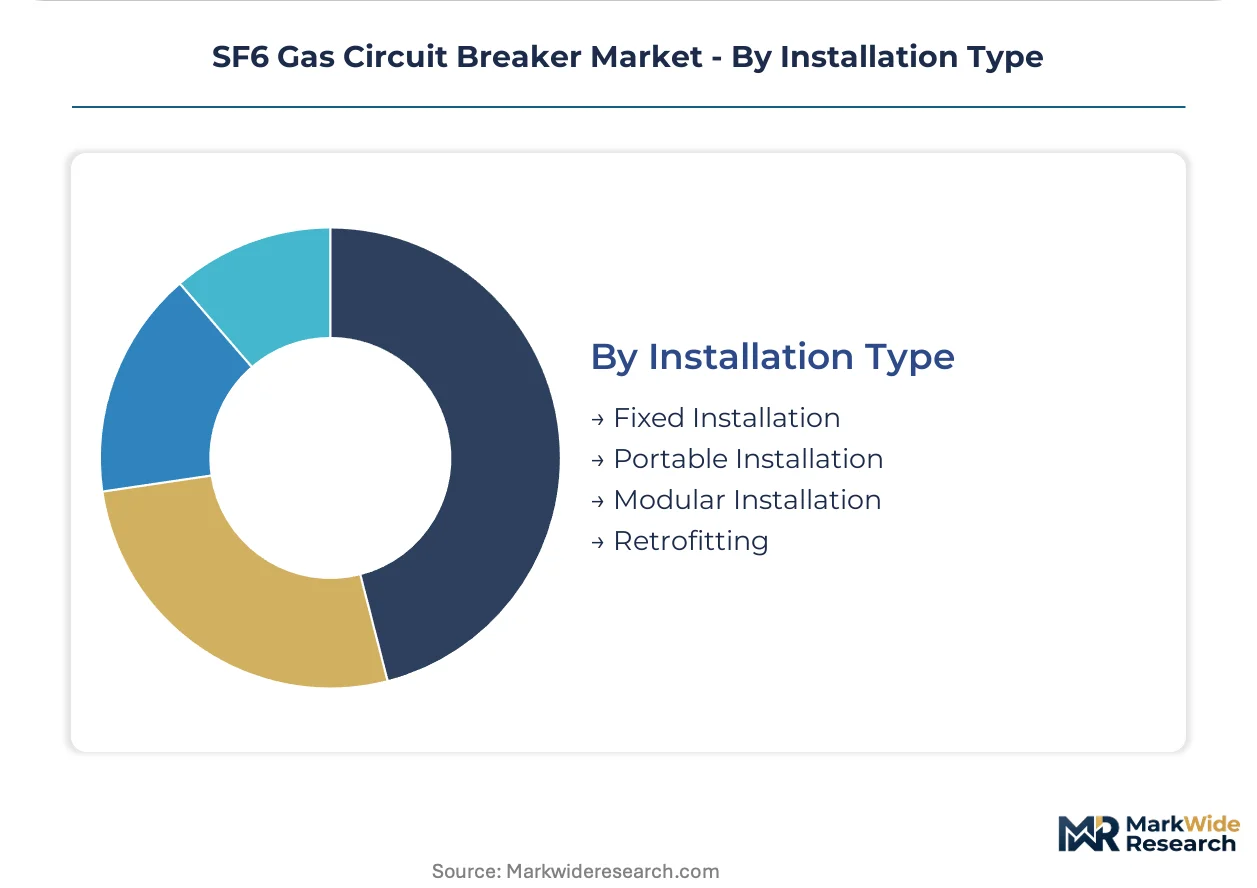
Installation Type:
Customer type stratification separates greenfield utilities specifying fixed installations from industrial operators preferring modular flexibility for expansion planning.
- Fixed Installation:Permanently mounted circuit breakers in purpose-built substation structures constitute the standard for transmission utilities. North Sea and Gulf of Mexico oilfield operators are specifying fixed gas-insulated switchgear for space-constrained topside installations where salt corrosion accelerates equipment degradation.
- Retrofitting:Digital monitoring system integration onto pre-2010 circuit breakers demands custom engineering. The EPA's emerging state-level reporting requirements elevate total-cost-of-ownership calculations, making retrofit decisions more complex for North American utilities.
- Portable Installation:Mobile substations for emergency restoration and temporary construction power.
- Modular Installation:Prefabricated substation blocks for rapid deployment in growing load centers.
Fixed installation dominates installed base. Retrofitting is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The India-Bangladesh grid interconnector and ASEAN Power Grid initiatives are underwriting Asia-Pacific's centrality in high-voltage transmission expansion, while EU cross-border interconnectors and US regional transmission organizations reshape procurement geographies.
India
State transmission utilities are modernizing aging substations under central grid-strengthening programs to accommodate solar and wind capacity additions. The Central Electricity Authority mandates SF6 emissions monitoring in environmental compliance audits for high-voltage tenders. Maharashtra and Gujarat host the densest concentrations of manufacturing and utility procurement activity.
China
Provincial grid operators are expanding ultra-high-voltage corridors to transmit remote renewable generation to coastal load centers. The Ministry of Ecology and Environment has embedded SF6 emissions intensity metrics into environmental audits, reshaping procurement criteria. The Yangtze River Delta and Pearl River Delta clusters concentrate domestic equipment fabrication and state-owned utility headquarters.
Germany
Transmission system operators are restructuring procurement toward long-term asset-management contracts with availability guarantees. The EU F-Gas Regulation's tightening phasedown schedules compel accelerated gas recycling infrastructure investment. The industrial corridor spanning North Rhine-Westphalia and Bavaria anchors European manufacturing and TSO engineering centers.
Japan
Metropolitan substation operators specify compact gas-insulated designs where urban land scarcity exceeds air-insulated alternatives. METI efficiency standards and carbon neutrality targets pressure manufacturers toward alternative insulation R&D. The Kanto region around Tokyo and the Kansai corridor near Osaka concentrate utility procurement and domestic OEM production bases.
United States
Regional transmission organizations are evaluating grid hardening investments against emerging state-level SF6 reporting requirements. The EPA's voluntary partnership programs elevate total-cost-of-ownership calculations for leak-detection compliance. Texas and California utilities lead procurement volumes for renewable integration and urban substation densification.
SF6 Gas Circuit Breaker Market Key Industry Players
On the supply side, the industry is consolidating around integrated electrical equipment conglomerates with captive gas handling capabilities and established utility relationships. Tier-one participants combine high-voltage breaker manufacturing with turnkey substation engineering, while mid-tier specialists compete on regional service proximity and retrofit expertise. Strategic differentiation centers on gas recycling infrastructure ownership and predictive maintenance platform development.
Within the integrated conglomerate tier, Mitsubishi Electric Corporation and Siemens AG exemplify archetypes combining domestic production anchoring with regional assembly localization. ABB Group occupies a position emphasizing long-term service contracts over transactional equipment sales. Among Asia-Pacific-centric fabricators, Larsen & Toubro Limited and Kirloskar Electric Company represent regional specialists with utility-proximate manufacturing footprints. Fuji Electric Co., Ltd. and Toshiba Corporation anchor Japanese-origin technology licensing and domestic utility relationships. The competitive terrain rewards backward integration into gas reclamation capabilities and forward integration into digital asset management platforms.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Schneider Electric SE |
| Larsen & Toubro Limited |
| Fuji Electric Co., Ltd. |
| Siemens AG |
| Hitachi T&D Solutions, Inc. |
| Kirloskar Electric Company |
| ABB Group |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese fluorochemical production facilities is compressing SF6 feedstock margins and forcing specialty gas manufacturers toward aggressive volume-discount negotiations with transmission equipment OEMs. This utilization imbalance simultaneously accelerates backward integration into captive gas recycling capabilities among European and Japanese circuit breaker producers seeking supply security.
Pricing Analysis
Volume-discount tiering separates multinational transmission utilities purchasing 245-800 kV equipment under long-term framework agreements from smaller distribution operators procuring medium-voltage units on spot terms. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with F-Gas Regulation compliance documentation commanding substantial premiums in European tenders. Cost compression in the medium-voltage tier is intensifying because vacuum interrupter substitution erodes SF6 breaker pricing power. State-owned utilities in India and China exhibit lowest price sensitivity due to regulator-approved cost-recovery mechanisms, while commercial and industrial buyers in Southeast Asia drive hardest bargain.
Supply Chain Analysis
Upstream fluorochemical feedstock production concentrates in China, Germany, and Japan, with specialty gas purification and blending operations clustering near major OEM assembly facilities. Sulfur hexafluoride manufacturing draws from elemental fluorine, sulfur feedstocks, and precision pressure-vessel fabrication capabilities concentrated among a limited supplier cohort. Single-source vulnerability in high-purity gas supply exposes procurement costs to capacity allocation decisions by dominant chemical producers. Distribution runs through authorized OEM service networks and specialized industrial gas distributors with certified handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among state transmission utilities and multinational grid operators with multi-year framework agreements, fragmenting pricing leverage for smaller distribution network operators and commercial buyers.
For Market Incumbents: Build regulatory compliance moats through captive gas recycling infrastructure and predictive maintenance platform development. Accelerate backward integration into fluoronitrile blending capabilities before EU F-Gas Regulation thresholds harden. Defend high-voltage margins by anchoring long-term asset-management contracts with European transmission system operators. For New Entrants and Emerging Players: Build out regional service networks targeting retrofit opportunities in North American utilities facing EPA leak-detection compliance cost escalation. Focus penetration on medium-voltage vacuum-SF6 hybrid architectures where technical barriers are lowest and procurement criteria favor local service proximity. Pursue joint development agreements with offshore platform electrification contractors in the Gulf of Mexico. For Investors and Strategic Acquirers: Capital is best deployed toward gas management specialists with established utility relationships and digital asset management platforms. Long-term viability hinges on regulatory trajectory rather than manufacturing scale, favoring targets with demonstrated F-Gas compliance infrastructure. Monitor fluoronitrile technical performance validation above 420 kV as the critical substitution inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Gas Recycling Infrastructure Buildout | Captive reclamation capabilities secure supply continuity under tightening EU F-Gas Regulation phasedown mandates. |
| Fluoronitrile Blending Partnership | Early access to C4F7N-CO2 formulations collapses substitution barriers in 72.5-145 kV metropolitan substations. |
| Long-Term Asset-Management Contracting | Availability guarantees with German and French transmission operators convert capital equipment sales into recurring revenue streams. |
| Predictive Maintenance Platform Development | Digital monitoring integration addresses legacy asset retrofit demand and elevates switching equipment to service-led positioning. |
| Offshore Platform Electrification Targeting | Space-constrained North Sea and Gulf of Mexico installations specify gas-insulated switchgear resistant to salt corrosion degradation. |
Research Approach
Desk research of regulatory filings from the EPA, EU F-Gas Regulation implementing acts, and China's MEE provincial audit protocols preceded structured interviews with transmission system operator procurement directors, high-voltage equipment plant managers, specialty gas distribution channel partners, and aftermarket service heads. Primary fieldwork across India, Germany, Japan, and the United States captured utility procurement criteria, OEM manufacturing capacity allocation decisions, and gas handling protocol evolution. Secondary validation drew from Central Electricity Authority tender documentation, Bundesnetzagentur grid development plans, FERC interconnection queue data, and customs trade statistics for SF6 and fluoronitrile feedstocks. Bottom-up unit shipment estimates by voltage class and installation type were triangulated against top-down transmission infrastructure investment forecasts.
Assumptions regarding EU F-Gas Regulation phasedown trajectory, China's dual carbon policy enforcement intensity, and fluoronitrile technical performance maturation were held fixed across baseline scenarios while sensitivity bands varied renewable integration pace and raw material feedstock availability. Segmentation modeling spanned product type, voltage level, end-user category, and installation format, with geographic clustering by national regulatory framework. CAGRs were derived from regression analysis of historical transmission equipment procurement cycles against grid-strengthening program announcements and interconnector project development timelines. Industry-specific inputs included SF6 emissions intensity metrics embedded in provincial environmental audits and state-level reporting requirement emergence patterns.
Stress conditions across fluorochemical feedstock price volatility, alternative insulation technology substitution rates, and utility capital expenditure prioritization shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology performance validation milestones. Cross-checking against IEA electricity transmission investment benchmarks and national grid development plan disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Capacitor Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Copper Ground Rod Market