
 High Voltage Direct Current (HVDC) Capacitor Market | 2026-2036
High Voltage Direct Current (HVDC) Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Direct Current (HVDC) Capacitor Market Analysis
The EU Green Deal is consolidating procurement criteria for HVDC infrastructure across European transmission operators. Siemens AG leverages its converter station expertise to anchor large-scale offshore projects in the North Sea. Hitachi Energy Ltd. competes on voltage source converter integration, while ABB Ltd. dominates high-voltage cable system pairings with specialized capacitor banks. TDK Corporation sustains film dielectric R&D for extended temperature cycling in subsea installations.
High Voltage Direct Current capacitors store and regulate electrical energy in converter stations operating above 100 kV, typically employing polypropylene film dielectrics with metallized electrodes to withstand repetitive voltage transients and harmonic stress. Their primary purpose is to stabilize DC-link voltage in line-commutated and voltage-source converter topologies that enable long-distance power transmission with lower losses than AC alternatives. Film capacitors lead installed base due to self-healing properties and reliability in outdoor converter halls, while ceramic capacitors occupy niche roles in compact modular HVDC units where space constraints dominate design tradeoffs. Voltage source converter technology is displacing older line-commutated systems in new projects, shifting margin pools toward suppliers with semiconductor-capacitor co-design capabilities.
FERC in the United States mandates grid reliability standards that shape capacitor qualification timelines for interregional DC ties, while China's GB standards and MEE emissions rules tighten material content and recycling protocols for HVDC components. EMA's environmental risk assessments in Europe add layers of polymer dielectric scrutiny for subsea deployments. Stakeholders must monitor how converter technology roadmaps and evolving certification regimes in multiple jurisdictions reshape supplier qualification requirements.
Market Dynamics
Voltage source converter technology is displacing line-commutated systems across new HVDC corridors, forcing capacitor suppliers to co-design with semiconductor manufacturers and compressing qualification cycles for film dielectric stacks.
Growth Catalysts
- Offshore wind procurement:North Sea developers are scaling orders for DC-link capacitors as converter station deployment accelerates. Germany's TenneT and 50Hertz anchor this demand through corridor expansion mandates.
- China's dual carbon framework:Grid interconnection mandates under the dual carbon goals are tightening certification requirements and forcing local production partnerships for foreign suppliers.
- EU Green Deal consolidation:European transmission operators are harmonizing procurement criteria across HVDC infrastructure, reducing supplier fragmentation and favoring qualified capacitor banks.
Market Restraints
- Polypropylene supply concentration:Biaxially oriented polypropylene film production clusters in Asia, exposing European and North American capacitor manufacturers to input cost volatility and currency risk.
- Subsea certification friction:EMA's environmental risk assessments for polymer dielectrics add 18-24 month qualification timelines for subsea deployments, compressing project IRRs.
- Ceramic substitution in modular units:Compact voltage source converter stations are adopting ceramic capacitors where space constraints override film reliability advantages.
Strategic Opportunities
- US interregional DC ties:FERC reliability standards for grid interconnection are creating first-mover advantages for capacitor suppliers with pre-qualified component portfolios.
- Extended temperature cycling R&D:Film dielectric innovation for subsea thermal stress is converging with offshore wind installation depths beyond 60 meters.
- Recycling protocol premiums:China's MEE emissions rules and material content standards are creating certified-supplier price premiums for compliant capacitor manufacturers.
Industry Challenges
- Semiconductor-capacitor co-design talent scarcity:Voltage source converter integration requires power electronics engineers with simultaneous capacitor physics and IGBT/SiC expertise, a skill set concentrated at fewer than a dozen institutions.
- Multi-jurisdiction certification stacking:Suppliers must simultaneously satisfy FERC reliability standards, GB standards for Chinese projects, and EU Green Deal procurement criteria, fragmenting engineering resources.
- Legacy line-commutated system integration:Retrofit projects demand capacitor banks compatible with both existing thyristor controls and new voltage source converter modules, doubling design validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Direct Current (HVDC) Capacitor Market |
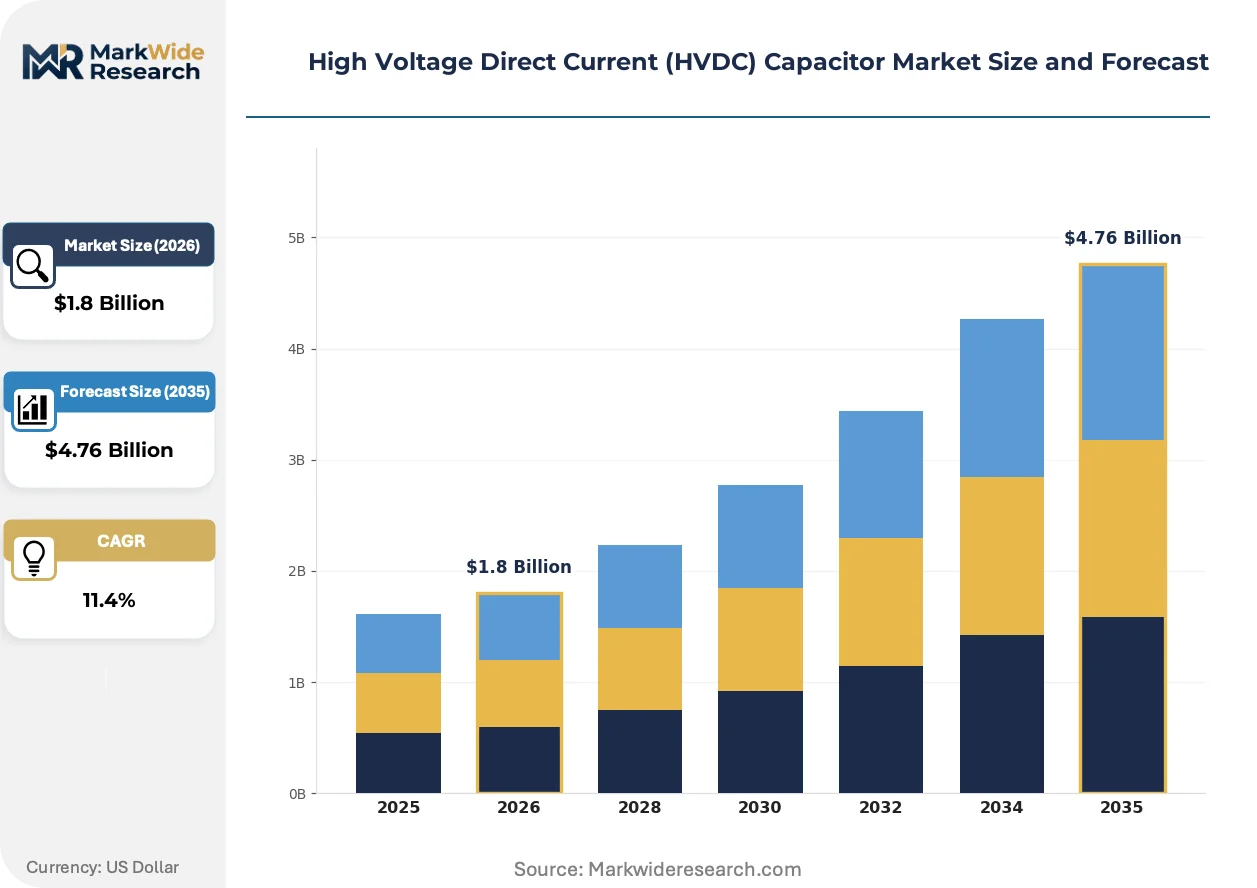
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Capacitors, Ceramic Capacitors, Electrolytic Capacitors, Supercapacitors End User: Utilities, Renewable Energy Sources, Industrial Applications, Data Centers Installation Type: Onshore, Offshore, Indoor, Outdoor Technology: Modular HVDC, Line Commutated Converter, Voltage Source Converter, Hybrid |
| Companies Covered | Eaton Corporation PLC, TDK Corporation, Siemens AG, General Atomics Inc., Vishay Intertechnology Inc., ABB Ltd., Hitachi Energy Ltd., Murata Manufacturing Co. Ltd., General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Direct Current (HVDC) Capacitor Market Emerging Trajectories
Active material science programs and procurement model evolution are compressing traditional supplier-buyer relationships. Three forces are restructuring how capacitor technology reaches installed base.
Metallized polypropylene film with segmented electrode patterns is converging with self-healing dielectric architectures to extend service life in harmonic-rich converter environments. Offshore wind developers in Germany and the Netherlands are specifying these stacks for 40-year design lifetimes. The technology is converging with voltage source converter roadmaps to displace conventional uniform metallization in projects above 500 MW.
REACH substance restrictions and RoHS amendments are tightening phthalate and heavy metal content limits for polymer dielectrics used in European HVDC installations. Capacitor manufacturers are reformulating impregnation compounds and electrode alloys to maintain dielectric strength under compliance. Subsea cable system pairings face the steepest reformulation costs due to EMA's layered environmental scrutiny.
Long-term service agreements are unbundling from hardware procurement as transmission operators seek performance guarantees on capacitor degradation rates. Siemens AG and Hitachi Energy are piloting availability-based contracts where suppliers retain component ownership. This model is most visible in German offshore converter stations where TenneT shifts operational risk to equipment vendors.
High Voltage Direct Current (HVDC) Capacitor Market Segmentation
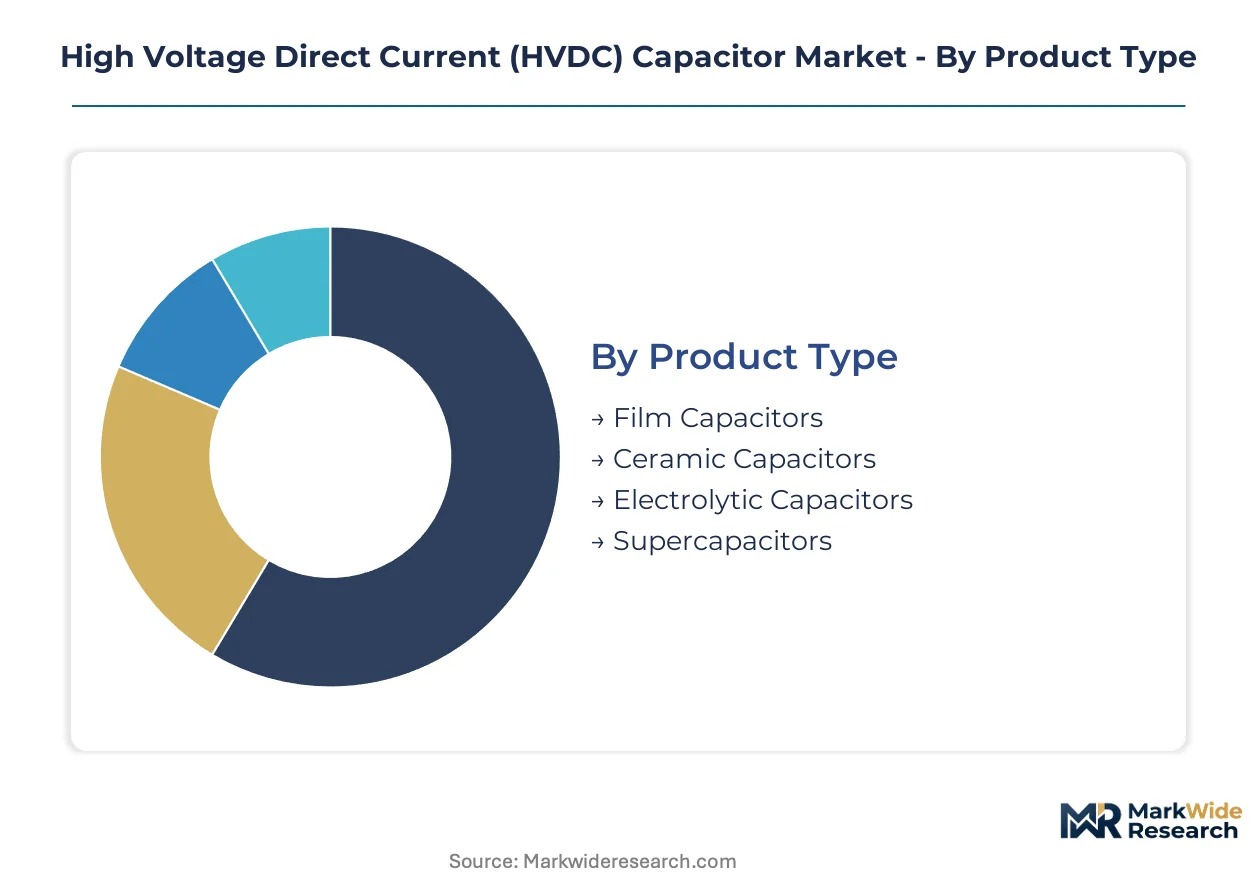
HVDC capacitor procurement splits across four structural dimensions that determine engineering specifications, certification pathways, and supplier qualification requirements. Each segmentation axis carries distinct margin profiles and capital intensity thresholds that reshape competitive positioning.
Product Type:
Film capacitors demand the heaviest upfront capital commitment due to metallized electrode deposition lines and biaxially oriented polypropylene film sourcing infrastructure.
- Film Capacitors:Polypropylene dielectrics with self-healing metallized electrodes dominate converter station DC-link applications above 500 MW. German offshore wind developers in the North Sea specify these stacks for 40-year design lifetimes under harmonic stress.
- Ceramic Capacitors:Multilayer ceramic chip configurations occupy compact modular HVDC units where space constraints override film reliability advantages. China's dual carbon grid interconnection projects are adopting ceramic stacks in distributed converter stations.
- Electrolytic Capacitors:Aluminum oxide dielectric systems serve bulk energy storage in legacy line-commutated converter retrofits.
- Supercapacitors:Electrochemical double-layer architectures provide transient voltage support in hybrid converter topologies.
Most installed capacity flows through Film Capacitors. Expansion is steepest in Ceramic Capacitors.
End User:
Utility procurement concentrates the largest contract values and longest qualification cycles, while renewable energy developers compress delivery timelines.
- Utilities:Transmission system operators like Germany's TenneT and 50Hertz anchor demand through multi-decade service agreements with availability guarantees. FERC reliability standards in the United States extend qualification timelines for interregional DC tie projects.
- Renewable Energy Sources:Offshore wind farm developers in the North Sea are scaling DC-link capacitor orders as converter station deployment accelerates beyond 60-meter installation depths.
- Industrial Applications:Steel and aluminum smelters deploy HVDC ties for stable bulk power import from distant generation.
- Data Centers:Hyperscale facilities are piloting HVDC distribution architectures to reduce conversion losses in campus power delivery.
Utilities command the deepest supplier relationships. Renewable Energy Sources are gaining share fastest.
Installation Type:
Offshore deployments multiply capital requirements through subsea cable system pairings and environmental risk assessment compliance.
- Onshore:Converter halls in Germany and China accommodate the majority of installed film capacitor banks with standard outdoor weatherproofing.
- Offshore:Platform-mounted converter stations face EMA environmental scrutiny and 18-24 month polymer dielectric qualification timelines.
- Indoor:Controlled-environment installations in industrial facilities favor compact ceramic capacitor configurations.
- Outdoor:Direct-exposure converter yards require extended temperature cycling validation for metallized film stacks.
Onshore locations hold the bulk of existing assets. Offshore installations are climbing the fastest.
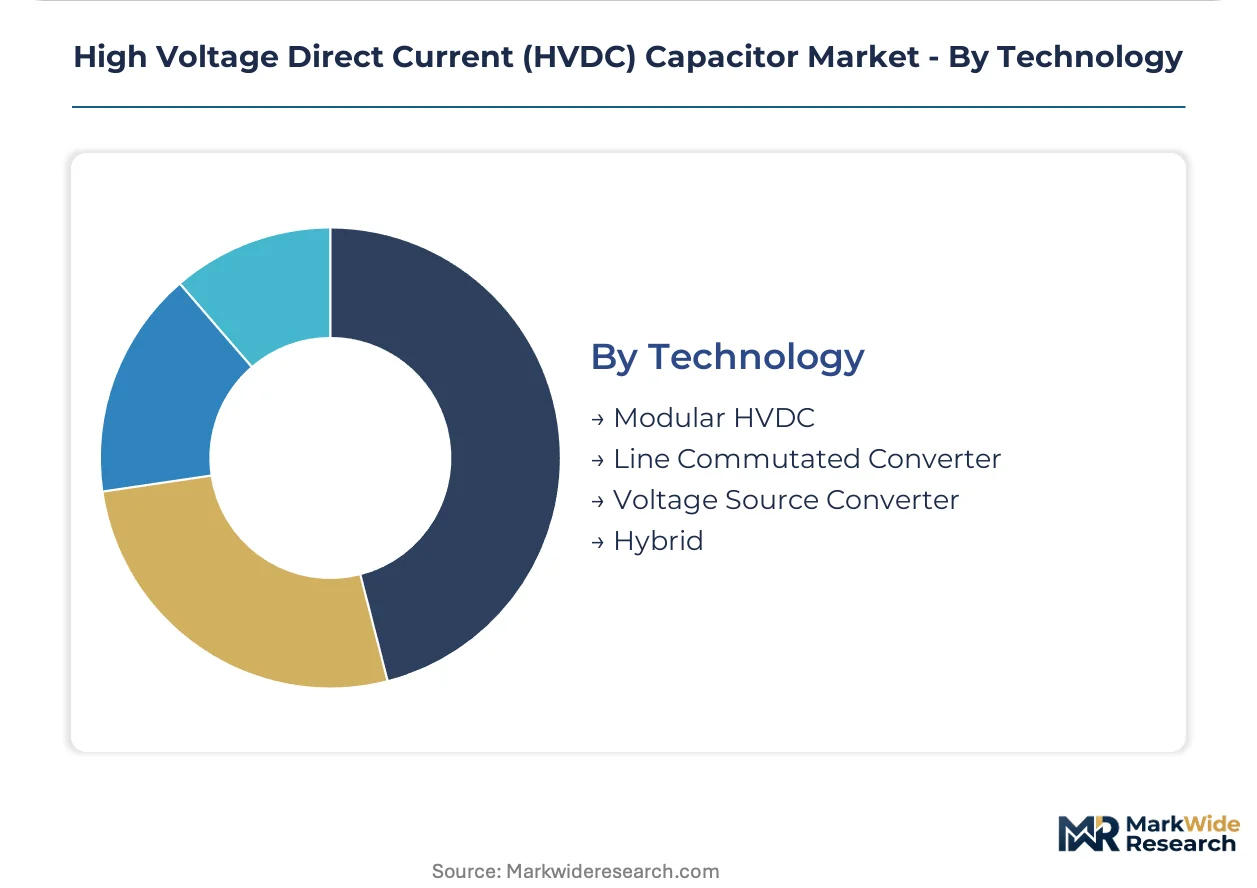
Technology:
Voltage source converter platforms concentrate R&D investment and semiconductor-capacitor co-design talent.
- Modular HVDC:Compact converter building blocks integrate ceramic capacitors for space-constrained urban substations.
- Line Commutated Converter:Thyristor-based legacy systems still require electrolytic capacitor banks for DC-link stabilization in retrofit corridors.
- Voltage Source Converter:IGBT and SiC semiconductor pairings with film capacitors are displacing older topologies in new North Sea offshore projects.
- Hybrid:Combined LCC-VSC architectures demand capacitor banks compatible with both thyristor controls and new modular units.
Voltage Source Converter technology captures the steepest expansion trajectory. Hybrid systems face the most complex integration validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics engineers with semiconductor-capacitor co-design expertise concentrate in Germany, China, and the United States, anchoring procurement decisions for converter station projects across three continents.
Germany
TenneT and 50Hertz drive DC-link capacitor procurement for North Sea offshore corridors. The EU Green Deal harmonizes transmission operator procurement criteria across German HVDC infrastructure. Converter station clusters in Hamburg and Lower Saxony process film capacitor orders for 40-year design lifetimes.
China
Grid interconnection mandates under dual carbon goals force local production partnerships for foreign capacitor suppliers. GB standards and MEE emissions rules tighten material content and recycling protocols for HVDC components. Yangtze River Delta manufacturing bases scale biaxially oriented polypropylene film output for domestic converter stations.
United States
FERC reliability standards shape capacitor qualification timelines for interregional DC tie projects. Grid modernization programs prioritize pre-qualified component portfolios for transmission infrastructure. Texas and California transmission operators anchor demand for voltage source converter-compatible capacitor banks.
Japan
METI industrial policy directs capacitor R&D funding toward extended temperature cycling for subsea installations. JIS standards govern film dielectric quality protocols for export-oriented manufacturers. Osaka and Nagoya industrial corridors supply metallized electrode deposition equipment to European converter station builders.
Netherlands
Offshore wind developers in the Dutch North Sea specify polymer dielectric stacks for platform-mounted converter stations. EMA environmental risk assessments add qualification layers for subsea capacitor deployments. Rotterdam port logistics clusters handle subsea cable system pairings with integrated capacitor banks.
High Voltage Direct Current (HVDC) Capacitor Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the HVDC capacitor value chain, creating a tiered structure where film dielectric manufacturers and converter station integrators occupy distinct margin pools. The vendor base splits between integrated conglomerates with captive semiconductor divisions and specialized capacitor houses focused on metallized film architectures. Three archetypes dominate: diversified industrial conglomerates, pure-play film capacitor specialists, and power electronics integrators with captive component sourcing. Capacity expansion and strategic partnerships represent the dominant competitive vectors as voltage source converter adoption accelerates qualification cycles.
Among diversified industrial conglomerates, Siemens AG and Hitachi Energy Ltd. exemplify the integrated archetype that couples converter station engineering with captive capacitor specification authority. TDK Corporation occupies a position within the pure-play specialist tier, anchoring film dielectric R&D investment for extended temperature cycling applications. These three entities represent the competitive fault lines where semiconductor-capacitor co-design capabilities determine supplier selection outcomes in German and Chinese procurement cycles.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| TDK Corporation |
| Siemens AG |
| General Atomics Inc. |
| Vishay Intertechnology Inc. |
| ABB Ltd. |
| Hitachi Energy Ltd. |
| Murata Manufacturing Co. Ltd. |
| General Electric Company |
| Others |
Supply Flow & Price Mechanics
EMA's environmental risk assessments for polymer dielectrics gate qualified supply access and premium-tier pricing for North Sea offshore deployments. Transmission operators now demand certified capacitor banks with 40-year availability guarantees, compressing margins for non-compliant manufacturers while rewarding pre-qualified suppliers with price premiums.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware procurement from long-term availability contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with German utilities paying premiums for EMA-compliant subsea stacks. Pricing pressure stems from ceramic substitution in compact modular units. Renewable energy developers show highest price sensitivity, while transmission system operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam handle hub-and-spoke patterns for converter station components. Biaxially oriented polypropylene film production concentrates in China, Japan, and South Korea, drawing from metallized electrode deposition equipment sourced from Osaka and Nagoya. Single-source vulnerability in Asian film supply exposes European manufacturers to input cost volatility. Distribution runs through transmission operator procurement clusters with captive specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as voltage source converter adoption forces capacitor-semiconductor co-design capabilities. Offshore wind developers now specify 40-year design lifetimes, elevating premium-tier suppliers with proven subsea track records.
For Market Incumbents: Anchor qualification timelines through backward integration into biaxially oriented polypropylene film production. Siemens AG and Hitachi Energy should compress semiconductor-capacitor co-design cycles to defend against pure-play specialists. EMA's 18-24 month environmental assessments create regulatory moats for pre-qualified suppliers.
For New Entrants and Emerging Players: Ceramic capacitor integration for compact modular HVDC units offers the most penetrable wedge. China's distributed converter station buildout under dual carbon goals presents white-space opportunity. Target local production partnerships with Yangtze River Delta manufacturing bases to satisfy GB standards compliance.
For Investors and Strategic Acquirers: Roll-up economics work for pure-play film capacitor specialists because semiconductor-capacitor co-design talent concentrates at fewer than a dozen institutions. Five-to-ten year viability hinges on voltage source converter roadmap alignment. Monitor FERC pre-qualification timelines as inflection indicator for US interregional DC tie participation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Dielectric Production | Yangtze River Delta manufacturing bases reduce polypropylene supply concentration risk for European capacitor manufacturers. |
| Semiconductor-Capacitor Co-Design Partnership | IGBT and SiC pairing capabilities determine supplier selection in German North Sea offshore converter stations. |
| EMA Pre-Qualification Investment | Subsea environmental risk assessment compliance creates 18-24 month regulatory moats against non-qualified competitors. |
| Long-Term Service Agreement Unbundling | TenneT and 50Hertz shift operational risk to vendors through availability-based contracts with performance guarantees. |
| Ceramic Stack R&D for Modular Units | China's distributed converter station deployment favors compact configurations where space constraints override film reliability. |
Methodological Framework
Bottom-up converter station modeling reconciled against top-down capacitor supply tracking forms the analytical core of this study. Primary interviews with transmission system operators, offshore wind farm developers, EPC contractors, and power electronics engineers combined with secondary validation from FERC filings, EMA environmental assessments, GB standards documentation, and customs trade data. Triangulation across stakeholder inputs and regulatory filings anchors volume estimates.
Historical trendline analysis of voltage source converter adoption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end user, installation type, and technology platform. CAGRs derive from fitted growth curves applied to utility procurement cycles and renewable energy interconnection mandates. Forecast inputs incorporate semiconductor roadmaps and certification timeline compression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to voltage source converter displacement rates and polypropylene supply chain reconfiguration. Outputs reflect documented assumptions around dual carbon policy implementation and EU Green Deal procurement harmonization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
India Gas Insulated Switchgear Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Protective Relay Market