
 Magnet Bearings Market | 2026-2036
Magnet Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Magnet Bearings Market Outlook
ISO 14839 is rotating the competitive landscape by mandating vibration severity standards for active magnetic bearing systems in turbomachinery, effectively filtering out suppliers lacking full-stack sensor and control capabilities. SKF leverages its integrated electromechanical portfolio to anchor European demand for high-speed compressor applications. Waukesha Bearings Corporation sustains its position through specialized oil-free bearing retrofits for energy sector clients. Calnetix Technologies competes on compact, high-speed permanent magnet motor-bearing combinations for aerospace auxiliary power units.
Magnet bearings employ electromagnetic or permanent magnet fields to levitate and stabilize rotating shafts without mechanical contact, typically achieving rotational speeds above 50,000 RPM while eliminating lubricant contamination and friction losses. Active bearings dominate current installations due to their real-time adjustability and fault-tolerant control architectures, though superconducting variants represent the highest-performance tier with near-zero damping for specialized scientific and defense applications. Permanent magnet technology captures growing interest in energy generation for its passive stability and reduced power consumption in backup-bearing configurations.
The EU Machinery Directive and REACH frameworks enforce material traceability and operational safety documentation for industrial bearing deployments across European manufacturing zones. The EPA in the United States regulates oil mist emissions from conventional bearing lubrication systems, indirectly accelerating magnet bearing adoption in food processing and pharmaceutical cleanrooms. Stakeholders must monitor evolving cybersecurity standards for digital bearing control networks as industrial IoT integration becomes standard rather than optional.
Market Dynamics
Active magnetic bearing architectures are displacing conventional oil-lubricated systems across high-speed turbomachinery as ISO 14839 vibration mandates filter supplier capabilities and EU F-Gas Regulation accelerates contact-free retrofits in industrial cooling applications.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is forcing industrial cooling OEMs to eliminate lubricant contamination risks through magnet bearing integration in hermetic compressor designs.
- Power generation retrofit cycles:Aging gas turbine fleets across European utilities are driving contact-free bearing replacements to extend operational life and reduce maintenance intervals.
- Precision engineering clusters:Concentrated R&D infrastructure around Munich and Stuttgart anchors magnet bearing production capacity and specialized technical workforce pipelines.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and samarium-cobalt sourcing dependencies on Chinese processing facilities create input cost volatility and geopolitical exposure for European manufacturers.
- Control system complexity:Real-time sensor fusion and digital signal processing requirements demand specialized electromechanical engineering talent that remains scarce outside established industrial hubs.
- REACH material traceability:The EU framework mandates extensive documentation for magnetic alloy compositions, extending qualification timelines for new bearing designs.
Strategic Opportunities
- Aerospace auxiliary power units:Compact permanent magnet motor-bearing combinations address weight and reliability constraints in next-generation aircraft electrical systems.
- Food processing cleanrooms:EPA oil mist emission regulations in the United States are accelerating magnet bearing adoption where lubricant contamination threatens product integrity.
- Superconducting magnetic bearings:Near-zero damping characteristics open specialized defense and scientific instrumentation applications beyond conventional active system performance envelopes.
Industry Challenges
- ISO 14839 certification timelines:Vibration severity standard compliance requires extensive multiphysics simulation and physical testing protocols that strain development budgets.
- Industrial IoT cybersecurity integration:Digital bearing control networks must satisfy evolving IEC 62443 standards for operational technology security, complicating retrofit deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnet Bearings Market |
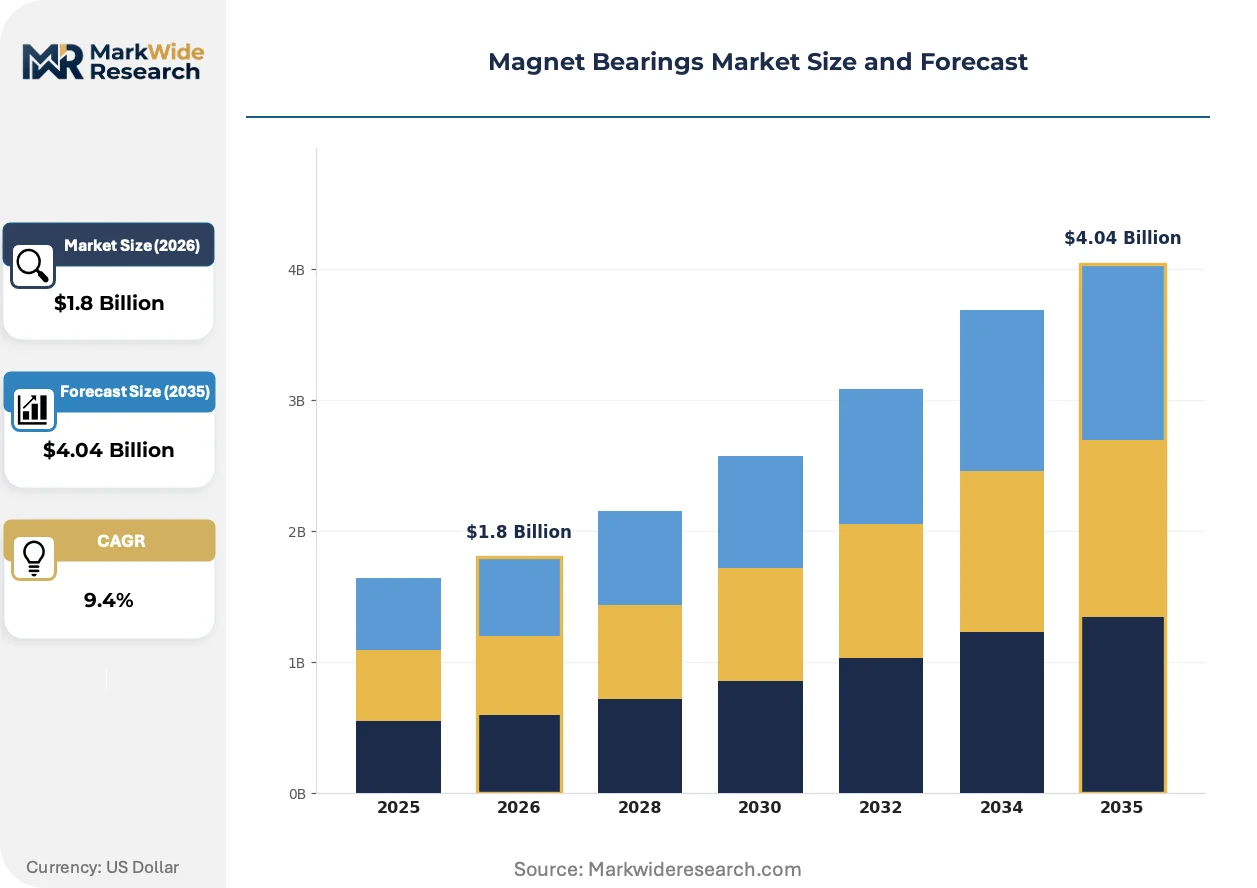
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Bearings, Passive Bearings, Hybrid Bearings, Magnetic Levitation Bearings Application: Aerospace, Industrial Automation, Energy Generation, Magnetic Bearings in Motors End User: Aerospace Manufacturers, Automotive Suppliers, Power Generation Companies, Research Institutions Technology: Electromagnetic, Permanent Magnet, Superconducting, Anisotropic Environmental Technology |
| Companies Covered | SKF, Waukesha Bearings Corporation, Siemens AG, Calnetix Technologies, Schaeffler, Synchrony Magnetic Bearings, Mecos AG, NSK Europe, Levitronix GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnet Bearings Market Strategic Shifts
Magnet bearing technology trajectories are splitting between high-performance active systems for critical turbomachinery and simplified permanent magnet configurations for energy-efficient auxiliary applications, with regulatory pressure and digitalization demands dictating development priorities.
Permanent magnet bearing technology is bifurcating the market into passive stability configurations for backup-bearing energy reduction and hybrid active-passive architectures that balance power consumption with real-time adjustability. Food processing and pharmaceutical cleanroom operators are adopting simplified permanent magnet designs to satisfy EPA oil mist constraints without full active control complexity. This split is compressing supplier R&D budgets between two diverging technical paths rather than consolidating around a single dominant architecture.
REACH enforcement through ECHA is tightening material documentation requirements for magnetic alloys deployed in industrial machinery across European manufacturing zones. Bearing manufacturers must now maintain comprehensive supply chain traceability for rare earth elements and copper windings, extending qualification cycles for new product introductions. German precision engineering clusters are responding by integrating in-house metallurgical analysis capabilities to accelerate compliance verification.
Specification authority is migrating from plant maintenance departments to corporate sustainability offices as ESG reporting frameworks elevate energy efficiency and contamination elimination metrics in capital equipment decisions. Traditional distributor channels face disintermediation as direct OEM engagement models emerge for large-scale turbomachinery retrofits. This shift is most pronounced in German power generation and industrial gas compression sectors where utilities consolidate procurement under centralized technical standards teams.
Magnet Bearings Market Segmentation
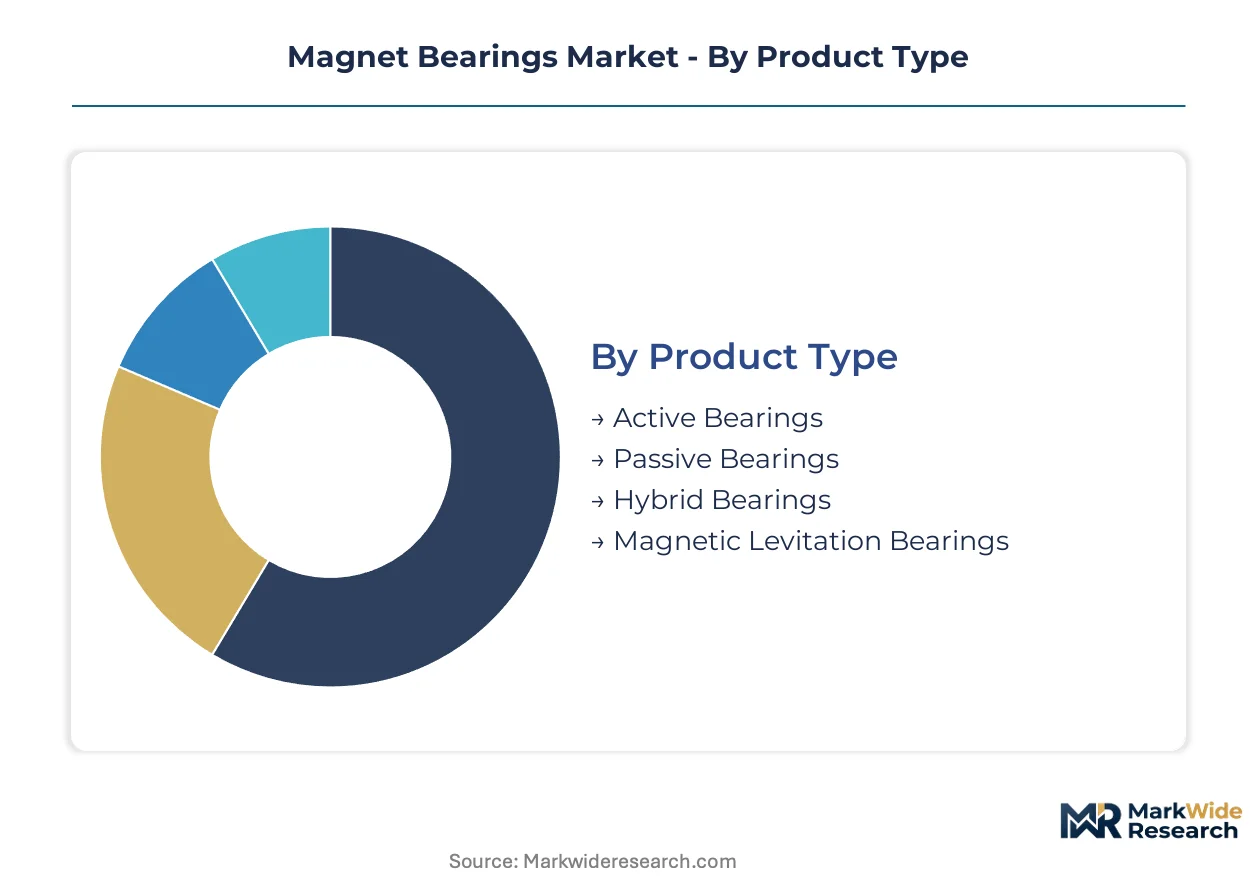
Magnet bearing architectures fragment across competing technical approaches with distinct substitution pressures from conventional oil-lubricated systems. Segment boundaries shift as ISO 14839 compliance requirements filter supplier capabilities and EU F-Gas Regulation accelerates contact-free retrofits in specific end-use verticals.
Product Type:
Passive bearings face the most acute substitution pressure from active systems as real-time adjustability becomes mandatory for high-speed turbomachinery applications.
- Active Bearings:Electromagnetic coil arrays with real-time sensor feedback enable rotational speeds above 50,000 RPM while maintaining fault-tolerant control architectures. Demand concentrates in German power generation retrofits where utilities eliminate lubricant contamination from aging gas turbine fleets under EU F-Gas compliance timelines.
- Passive Bearings:Permanent magnet configurations deliver passive stability without external power input, reducing energy consumption in backup-bearing roles. Aerospace auxiliary power unit manufacturers in Germany and France specify these for weight-constrained aircraft electrical systems where simplified architectures improve mean time between failures.
- Hybrid Bearings:Active-passive combinations balance power consumption with electromagnetic adjustability for mid-speed industrial compressors.
- Magnetic Levitation Bearings:Specialized configurations for ultra-precision scientific instrumentation and defense applications requiring near-zero damping characteristics.
Active bearings retain volume leadership; hybrid configurations hold the steepest expansion curve as industrial OEMs seek cost-optimized middle paths.
Application:
Cost tier stratification separates premium aerospace specifications from standardized industrial automation deployments.
- Aerospace:Auxiliary power units and flight-critical rotating machinery demand compact motor-bearing combinations with MIL-STD-810 environmental qualification. German and French aerospace clusters around Munich and Toulouse anchor specification authority for next-generation aircraft electrical systems.
- Industrial Automation:High-speed spindles and precision positioning systems in automotive manufacturing lines specify magnet bearings for contamination-free operation. Stuttgart precision engineering infrastructure supports localized R&D and production capacity for these deployments.
- Energy Generation:Gas turbine and wind turbine retrofits extend operational life through contact-free bearing replacements.
- Magnetic Bearings in Motors:Integrated motor-bearing combinations for hermetic compressors eliminate refrigerant contamination risks.
Industrial automation captures the largest addressable base; aerospace applications command the highest unit economics.
End User:
Procurement authority migrates from plant maintenance departments to corporate sustainability offices as ESG frameworks elevate energy efficiency metrics.
- Power Generation Companies:European utilities retrofit aging turbomachinery with active magnetic bearing systems to extend operational life and reduce maintenance intervals. E.ON and RWE procurement teams consolidate technical standards under centralized engineering functions in Germany.
- Aerospace Manufacturers:Airbus and Safran specify compact permanent magnet motor-bearing combinations for weight-constrained auxiliary power units.
- Automotive Suppliers:Tier-1 electric vehicle component manufacturers evaluate magnet bearings for high-speed traction motor applications.
- Research Institutions:CERN and Max Planck Institutes deploy superconducting magnetic bearings for specialized scientific instrumentation requiring near-zero damping.
Power generation companies anchor current demand volume; aerospace manufacturers drive specification evolution.
Technology:
Supply concentration in rare earth processing creates input cost volatility across electromagnetic and permanent magnet architectures.
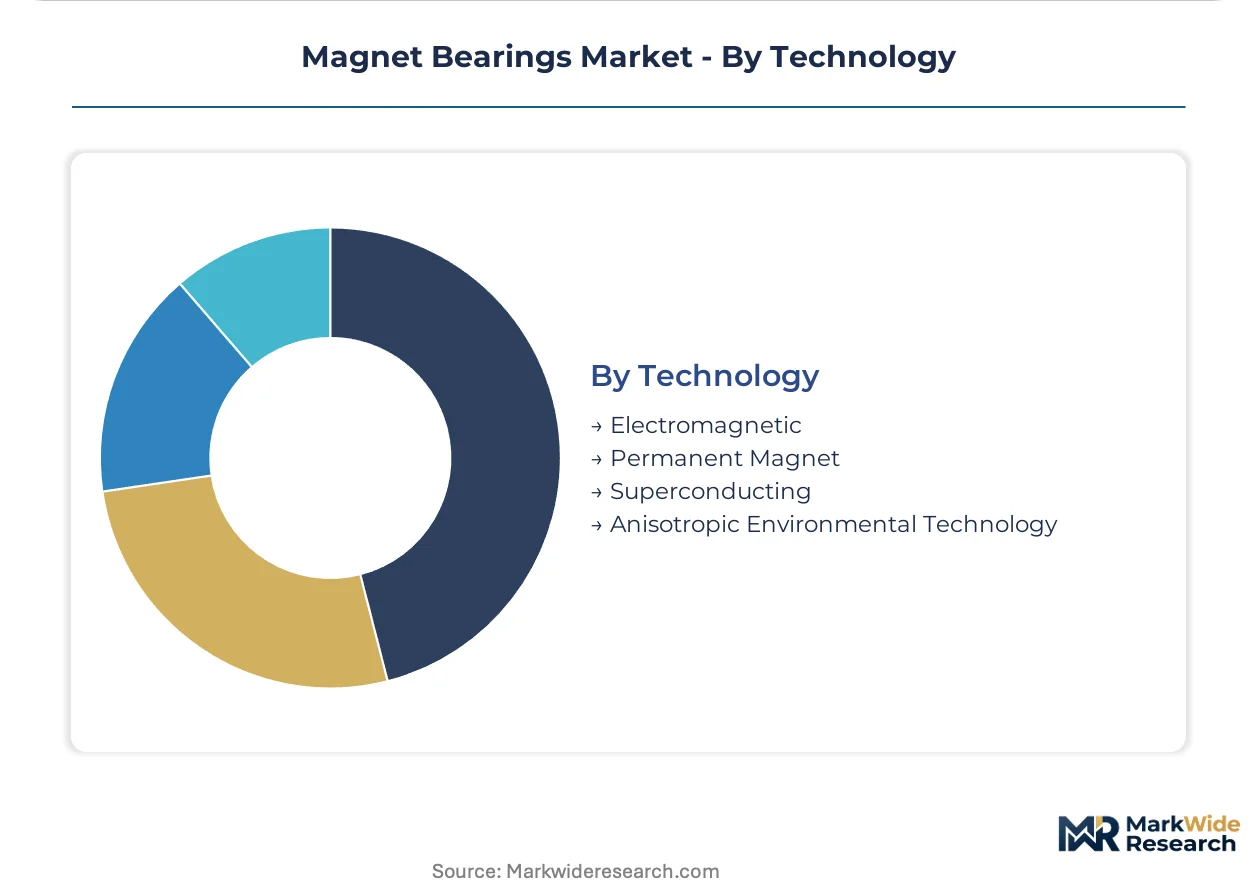
- Electromagnetic:Copper winding and silicon steel laminations enable real-time field modulation through digital signal processing control loops. German precision engineering clusters maintain in-house metallurgical analysis capabilities to satisfy REACH material traceability requirements for magnetic alloy compositions.
- Permanent Magnet:Neodymium-iron-boron and samarium-cobalt configurations deliver passive magnetic fields without continuous power input. Sourcing dependencies on Chinese rare earth processing facilities create geopolitical exposure for European manufacturers qualifying new bearing designs.
- Superconducting:Yttrium-barium-copper-oxide and similar high-temperature superconductors enable near-zero damping for specialized defense and scientific applications.
- Anisotropic Environmental Technology:Directionally optimized magnetic field configurations for extreme operating environments.
Electromagnetic systems dominate installed capacity; permanent magnet architectures gain share fastest as energy efficiency priorities harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation timelines are redistributing production capacity toward jurisdictions with established precision engineering infrastructure and qualified technical workforces for active magnetic bearing systems.
Germany
Utilities including E.ON and RWE are retrofitting aging gas turbine fleets with contact-free bearing systems to extend operational life. The EU F-Gas Regulation accelerates hermetic compressor deployments that eliminate lubricant contamination risks. Precision engineering clusters around Munich and Stuttgart anchor magnet bearing R&D and production capacity for European OEM demand.
United States
EPA oil mist emission regulations are accelerating magnet bearing adoption in food processing and pharmaceutical cleanrooms where product integrity demands contamination-free operation. The agency's enforcement framework indirectly subsidizes contact-free retrofits through compliance cost avoidance. Aerospace auxiliary power unit manufacturers specify compact permanent magnet configurations for weight-constrained aircraft electrical systems.
France
Airbus and Safran procurement teams are consolidating technical standards for next-generation aircraft electrical systems under centralized engineering functions. ANSM and CNIL frameworks govern operational safety documentation for industrial bearing deployments in manufacturing zones. The Toulouse aerospace cluster coordinates specification authority with Munich counterparts for auxiliary power unit bearing designs.
China
MIIT dual carbon goals are driving state-owned power generation companies to evaluate contact-free bearing retrofits for efficiency improvements in aging turbomachinery. GB standards and SAMR enforcement create compliance pathways for imported active magnetic bearing systems. Rare earth processing concentration in Inner Mongolia and Jiangxi creates input cost volatility for neodymium-dependent permanent magnet architectures.
Japan
METI energy efficiency mandates are accelerating magnet bearing integration in high-speed industrial compressors for chemical and semiconductor manufacturing. JIS standards govern vibration severity requirements that parallel ISO 14839 specifications for active system qualification. The Nagoya industrial corridor maintains specialized electromechanical engineering talent pipelines for digital signal processing control architectures.
Magnet Bearings Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with integrated electromechanical portfolios alongside specialized bearing fabricators with concentrated turbomachinery expertise. Market structure exhibits moderate consolidation around European and North American engineering clusters with limited Asian penetration in premium active system tiers. Strategic archetypes include full-stack sensor-control integrators, oil-free retrofit specialists, and compact motor-bearing combination designers. Dominant competitive moves encompass strategic partnerships for rare earth supply security and technology licensing for ISO 14839 certification acceleration.
Within the full-stack integrator tier, SKF leverages its electromechanical portfolio breadth to anchor European demand for high-speed compressor applications, while Siemens AG occupies a position spanning industrial automation and power generation retrofit channels. Waukesha Bearings Corporation exemplifies the oil-free retrofit specialist archetype through concentrated energy sector relationships. Calnetix Technologies sits within the compact combination designer category addressing aerospace auxiliary power unit constraints.
| Leading Market Players |
|---|
| SKF |
| Waukesha Bearings Corporation |
| Siemens AG |
| Calnetix Technologies |
| Schaeffler |
| Synchrony Magnetic Bearings |
| Mecos AG |
| NSK Europe |
| Levitronix GmbH |
| Others |
Value Chain & Pricing Dynamics
ISO 14839 vibration severity standards gate both supplier qualification timelines and price differentiation tiers simultaneously, compressing margins for uncertified fabricators while rewarding full-stack integrators with premium positioning in European power generation retrofits. Buyers face extended procurement cycles as compliance documentation requirements layer onto rare earth magnet cost volatility.
Pricing Analysis
Certification level (ISO 14839-grade versus non-compliant) creates the primary spread between premium active bearing systems and commodity passive configurations. Three-tier pricing structure across ISO-certified, CE-marked, and uncertified tiers reflects control architecture complexity and sensor integration depth. Price differentiation stems from real-time adjustability features and after-sales service bundling for turbomachinery retrofits. Cost compression in mid-tier hybrid configurations is intensifying because Chinese rare earth processing concentration feeds input volatility. Power generation utilities exhibit lowest price sensitivity due to lifecycle cost framing, while food processing cleanroom operators prioritize upfront capital avoidance.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for neodymium-iron-boron magnet shipments from Chinese processing facilities. Geographic supply concentrates in China, Germany, and Japan, with Inner Mongolia and Jiangxi rare earth mines feeding permanent magnet architectures. Raw material dependencies rest on samarium-cobalt alloys, copper windings, and silicon steel laminations. Single-source vulnerability in Chinese rare earth processing creates geopolitical exposure for European manufacturers qualifying new bearing designs. Distribution runs through direct OEM engagement channels for large-scale turbomachinery retrofits, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority fragmentation across corporate sustainability offices, centralized engineering functions, and plant maintenance departments creates niche entry points for specialized players. Diverging technical paths between active and permanent magnet architectures further splinters addressable segments.
For Market Incumbents: Consolidate certification capabilities through in-house metallurgical analysis investments that accelerate REACH compliance verification. Lock in rare earth supply security via long-term offtake agreements with Chinese processors or backward integration into magnet alloy production. Defend against compact motor-bearing combination specialists by expanding electromechanical portfolio integration for aerospace auxiliary power unit applications. For New Entrants and Emerging Players: ISO 14839 fast-track certification partnerships with established testing laboratories enable rapid qualification for hermetic compressor retrofits under EU F-Gas Regulation timelines. White-space concentrates in simplified permanent magnet backup-bearing configurations for food processing cleanrooms where EPA oil mist compliance drives substitution. Target Midwestern United States pharmaceutical manufacturing clusters through direct technical sales engagement bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across superconducting magnetic bearing sub-segments as defense and scientific instrumentation applications demand specialized manufacturing infrastructure. Long-term viability favors full-stack sensor-control integrators with captive electromechanical capabilities over pure-play bearing fabricators. Acquisition target archetype: compact motor-bearing combination designers with MIL-STD-810 environmental qualification and established aerospace procurement relationships. Signal to watch: cybersecurity certification progress under IEC 62443 for digital bearing control networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Production | Captive neodymium supply secures cost predictability for German precision engineering clusters. |
| ISO 14839 Certification Acceleration Program | Fast-tracked vibration compliance opens E.ON and RWE retrofit procurement pipelines. |
| Cybersecurity Certification Investment | IEC 62443 compliance differentiates active bearing systems for industrial IoT integration. |
| Aerospace Auxiliary Power Unit Partnership | Airbus and Safran specifications anchor premium positioning in weight-constrained applications. |
| Food Processing Cleanroom Direct Sales Channel | EPA oil mist compliance framing bypasses traditional distributor markups in pharmaceutical zones. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with turbomachinery maintenance directors, power generation procurement leads, aerospace platform engineers, and precision bearing R&D heads. Secondary validation drew from ECHA REACH filings, EPA oil mist enforcement records, EU F-Gas Regulation implementation timelines, and SEC disclosures from diversified industrial conglomerates. Bottom-up unit economics triangulated against top-down market sizing across product type, application, and technology segmentation dimensions.
Across the projection horizon, the analytical framework modeled active versus passive bearing substitution rates, hermetic compressor retrofit penetration curves, and aerospace motor-bearing combination adoption patterns. CAGRs derived from multiphysics simulation cost trajectories, rare earth price elasticity assumptions, and regulatory compliance timeline enforcement intensity. Industry-specific forecast inputs included ISO 14839 certification backlog durations and EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants.
Decision-makers should treat outputs as directional under stable rare earth supply assumptions and consistent EU regulatory enforcement; material deviation in Chinese export policy or F-Gas timeline acceleration would warrant model refresh. Forecasts reflect bottom-up demand aggregation and top-down capacity constraints without claiming predictive certainty. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
Power Over Ethernet Lighting Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
Europe Electric Space Heaters Market