
 Gas Circuit Breaker Market | 2026-2036
Gas Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Circuit Breaker Market Analysis
Utility procurement consolidation is realigning vendor relationships across the gas circuit breaker supply base. ABB leverages its installed base in Europe to sustain long-term service contracts. Siemens Energy anchors high-voltage orders through integrated grid solutions. Mitsubishi Electric Corporation competes on gas-insulated switchgear specialization in Asian markets.
A gas circuit breaker interrupts fault currents by extinguishing the electric arc within a pressurized gas medium, typically sulfur hexafluoride or fluoronitrile blends, with rated voltages spanning 72.5 kV to 800 kV depending on application. Its primary purpose is protecting transmission networks and substation equipment from overload damage while enabling rapid reclosure. Sulfur Hexafluoride technology still dominates installed capacity despite environmental scrutiny, though Gas Insulated systems command premium pricing in space-constrained urban substations. Hybrid Breakers represent the fastest-expanding product category as utilities seek phased transition paths away from pure SF6 designs.
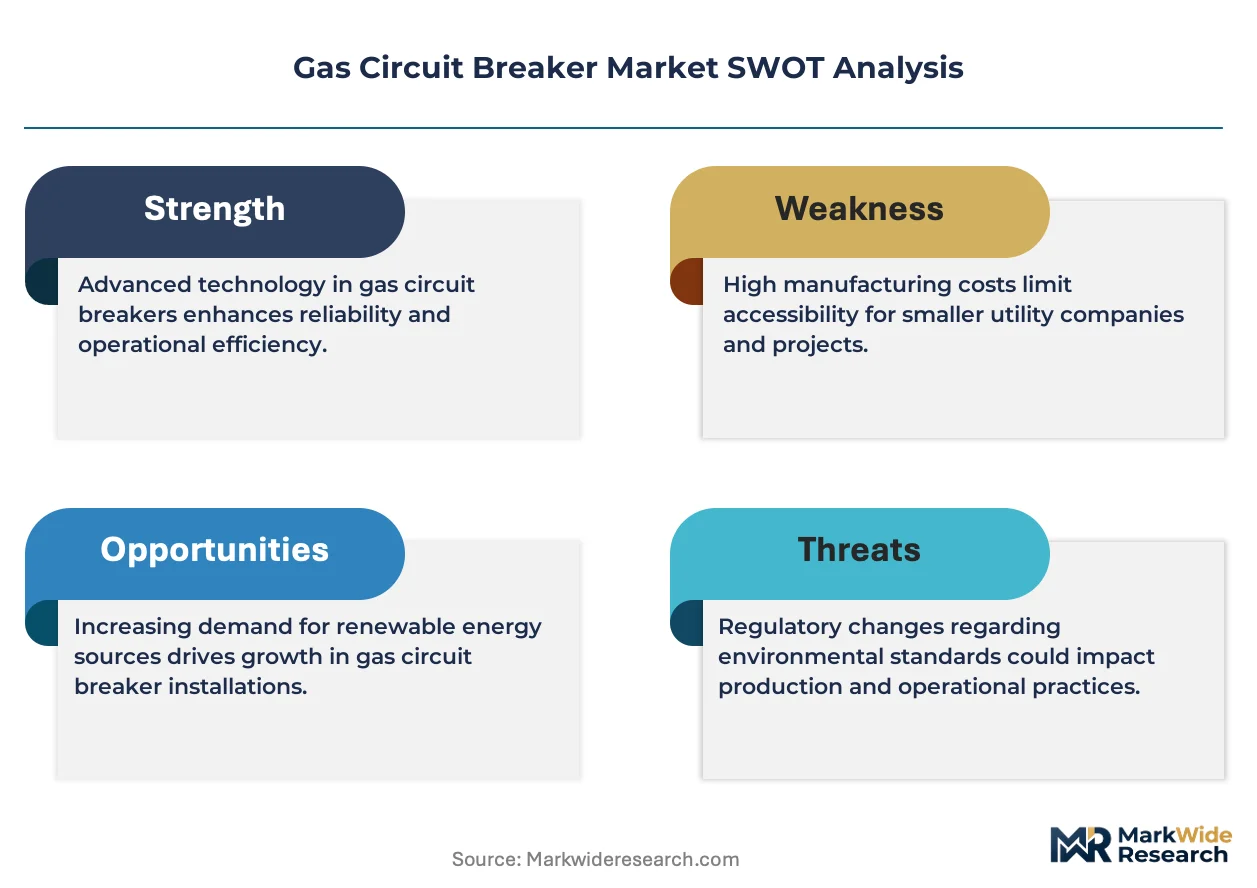
The EPA enforces sulfur hexafluoride emissions reporting under greenhouse gas protocols, while the EU F-Gas Regulation mandates phased reduction of fluorinated gas use in electrical equipment. IEEE and IEC standards govern dielectric withstand ratings and short-circuit breaking capacity, creating compliance barriers for non-certified manufacturers. Stakeholders must monitor regulatory timelines for alternative gas qualification and position R&D investment ahead of mandated phase-down thresholds.
Market Dynamics
The EU F-Gas Regulation's phasedown mandate is compressing sulfur hexafluoride availability while accelerating alternative gas qualification timelines, forcing manufacturers to reconfigure product architectures ahead of compliance deadlines.
Growth Catalysts
- Grid Modernization Programs:Power utilities in China and India are expanding high-voltage transmission corridors to accommodate renewable energy integration, creating sustained demand for 550 kV and 800 kV breaker installations.
- F-Gas Regulation Phase-Down:The EU's mandated reduction in fluorinated gas emissions is accelerating utility procurement of fluoronitrile and fluoroketone-based alternatives ahead of 2030 thresholds.
- Urban Space Constraints:Gas-insulated switchgear specialization is absorbing premium pricing in dense metropolitan substations across Japan and South Korea where footprint reduction commands priority.
Market Restraints
- Alternative Gas Cost Structure:Fluoronitrile blends command three to four times the cost per kilogram of sulfur hexafluoride, compressing margins on new product lines during transition periods.
- Supply Concentration Risk:High-purity sulfur hexafluoride production concentrates among Chinese and German chemical suppliers, exposing breaker manufacturers to input volatility during phase-down periods.
- Technical Limitation:Alternative gases exhibit lower dielectric strength than SF6 at equivalent pressures, requiring larger equipment footprints or higher operating pressures that challenge existing substation designs.
Strategic Opportunities
- Hybrid Breaker Architecture:Utilities seeking phased transition paths are creating white space for designs combining vacuum interrupters with reduced-pressure alternative gas insulation.
- Retrofit and Service Contracts:Europe's installed base of legacy SF6 equipment is generating demand for gas recovery, reprocessing, and end-of-life replacement services.
- Distribution Channel Innovation:Direct procurement relationships between national transmission operators and original equipment manufacturers are displacing traditional distributor networks in India and Brazil.
Industry Challenges
- Alternative Gas Certification Timelines:IEC and IEEE qualification protocols for fluoronitrile mixtures require multi-year testing cycles, delaying product commercialization beyond regulatory phase-down schedules.
- Field Service Skill Gaps:Specialized handling protocols for fluoronitrile and fluoroketone gases demand retraining of installation and maintenance workforces across utility and contractor organizations.
- Legacy System Integration:Mixed-gas substation architectures complicate protection coordination and asset management systems that were standardized around pure SF6 operating characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Circuit Breaker Market |
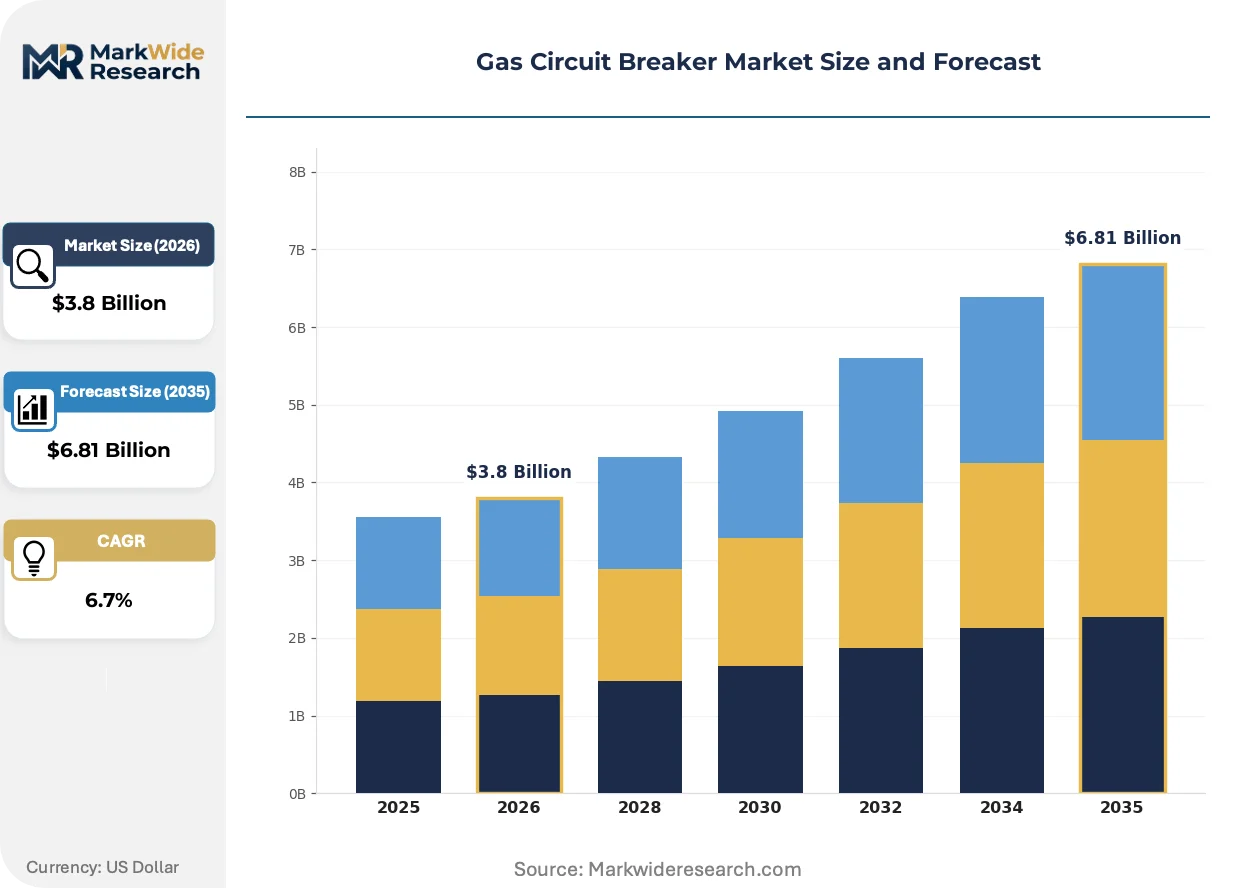
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Breakers, Portable Breakers, Fixed Breakers, Miniature Breakers End User: Industrial Sector, Power Utilities, Commercial Establishments, Renewable Energy Technology: Vacuum Technology, Sulfur Hexafluoride, Air Insulated, Gas Insulated Installation: Indoor, Outdoor, Ground-Mounted, Pole-Mounted |
| Companies Covered | ABB, Schneider Electric, Siemens Energy, Mitsubishi Electric Corporation, GE, Hitachi, Toshiba, Eaton, China XD Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Circuit Breaker Market Emerging Trajectories
Technology substitution pressures and procurement model evolution are simultaneously reshaping product development priorities and vendor-customer relationships across the high-voltage equipment sector.
Fluoronitrile-based gas mixtures are absorbing the technical investment that previously concentrated on sulfur hexafluoride optimization, with dielectric performance now approaching parity at moderate pressure differentials. European transmission operators are piloting these blends in 145 kV and 245 kV applications, compressing the commercialization timeline for full SF6 displacement. The technology is absorbing capital allocation from incumbents who previously treated alternative gases as peripheral R&D lines.
The EU F-Gas Regulation's 2024 tightening of equipment leakage rate thresholds is mandating sealed-pressure system designs that eliminate routine gas handling. This policy shift is accelerating demand for hermetically welded tank constructions and density monitoring systems. Manufacturers serving Germany, France, and the Netherlands are responding with modular platform architectures that simplify compliance documentation across national implementations.
Long-term service agreements are displacing transactional spare parts procurement as the dominant commercial framework for utility relationships. Transmission operators in China and India are unbundling maintenance contracts from initial equipment purchases, creating dedicated aftermarket revenue streams. This behavioral shift is most visible among state-owned grid companies seeking operational expenditure predictability over fifteen to twenty-year asset lifecycles.
Gas Circuit Breaker Market Segmentation
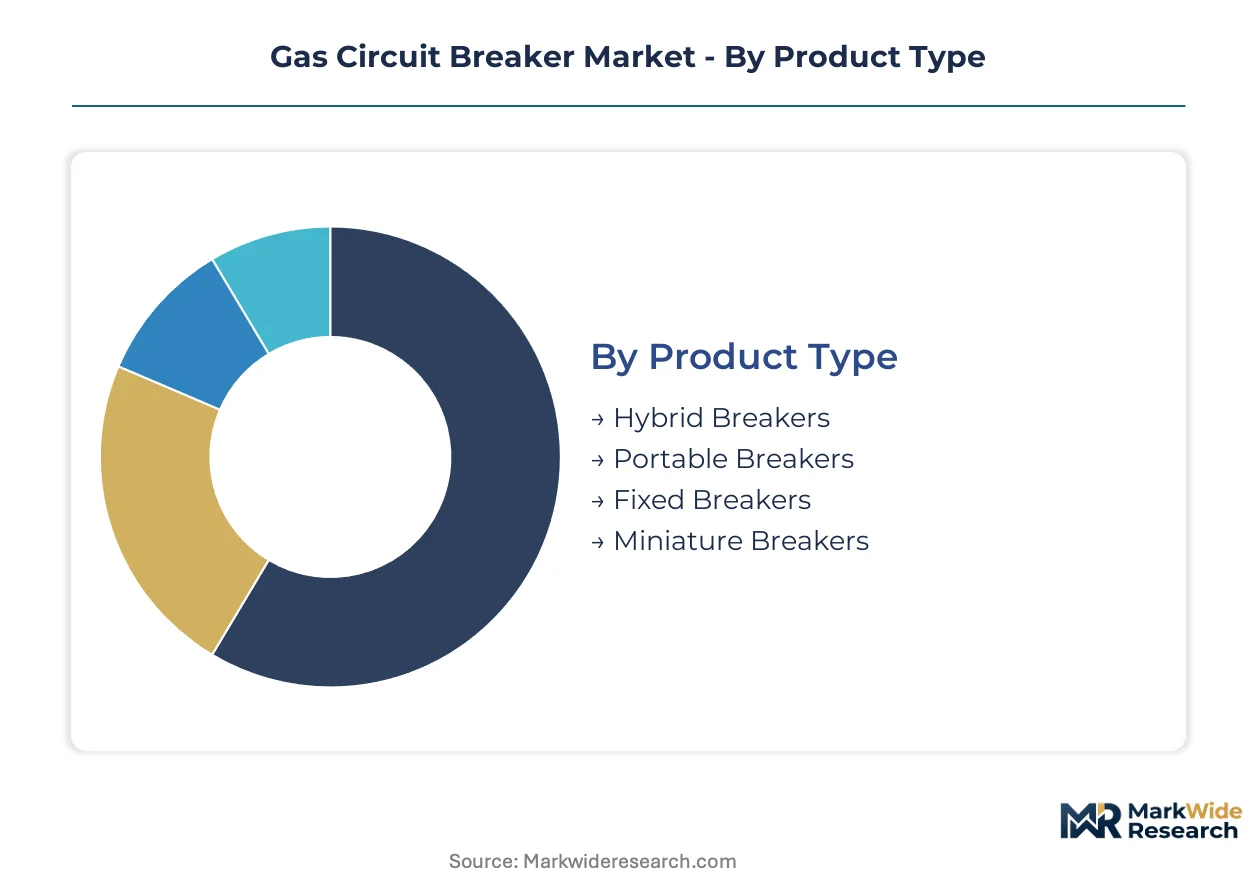
Gas circuit breaker procurement patterns diverge sharply across product architectures and end-use applications, with sulfur hexafluoride phase-down mandates forcing utilities to reevaluate technology portfolios. Segment boundaries are blurring as hybrid designs bridge legacy and alternative gas systems.
Product Type:
Supply concentration in high-voltage manufacturing favors integrated producers with in-house gas handling capabilities.
- Hybrid Breakers:These systems combine vacuum interrupters with reduced-pressure alternative gas insulation, enabling utilities to maintain dielectric performance while cutting fluorinated gas volumes. Demand concentrates in Germany and France where transmission operators pilot 145 kV and 245 kV installations ahead of EU F-Gas compliance deadlines.
- Fixed Breakers:Stationary installations dominate transmission substations and grid interconnect points. Procurement runs through state-owned utilities in China and India as high-voltage corridor expansion accelerates.
- Portable Breakers:Mobile units serve temporary grid configurations and emergency restoration.
- Miniature Breakers:Compact designs address distribution-level protection in space-constrained urban environments.
Fixed breakers absorb the bulk of installed capacity; hybrid breakers are expanding most quickly.
End User:
Customer procurement scale determines service contract structures and equipment specification tiers.
- Power Utilities:National transmission operators in China, India, and Germany drive bulk orders for 550 kV and 800 kV systems. These entities are unbundling fifteen to twenty-year maintenance contracts from initial capital purchases, shifting vendor relationships toward lifecycle partnerships.
- Industrial Sector:Heavy manufacturing and petrochemical facilities require reliable fault protection for captive substations. Demand clusters around process industries with continuous operations that cannot tolerate extended outage windows.
- Commercial Establishments:Data centers and large commercial complexes specify gas-insulated switchgear where footprint constraints override cost premiums.
- Renewable Energy:Wind and solar farm interconnects create intermittent demand tied to project development cycles.
Power utilities anchor procurement volume; renewable energy is climbing the fastest as grid integration accelerates.
Technology:
Margin compression varies across gas technologies as alternative formulations command premium input costs.
- Sulfur Hexafluoride:The incumbent dielectric medium delivers unmatched arc-quenching performance at moderate pressures. Installed base concentration in Europe generates aftermarket revenue through gas recovery and reprocessing services.
- Gas Insulated:Sealed-pressure systems eliminate routine gas handling, satisfying tightened EU F-Gas leakage thresholds. These configurations absorb premium pricing in Japanese and South Korean metropolitan substations where land scarcity dominates design priorities.
- Vacuum Technology:Solid-state interruption eliminates gas dependency entirely in lower voltage classes.
- Air Insulated:Conventional designs persist in cost-sensitive applications with available space.
Sulfur hexafluoride retains the largest installed base; gas insulated systems are gaining share fastest.
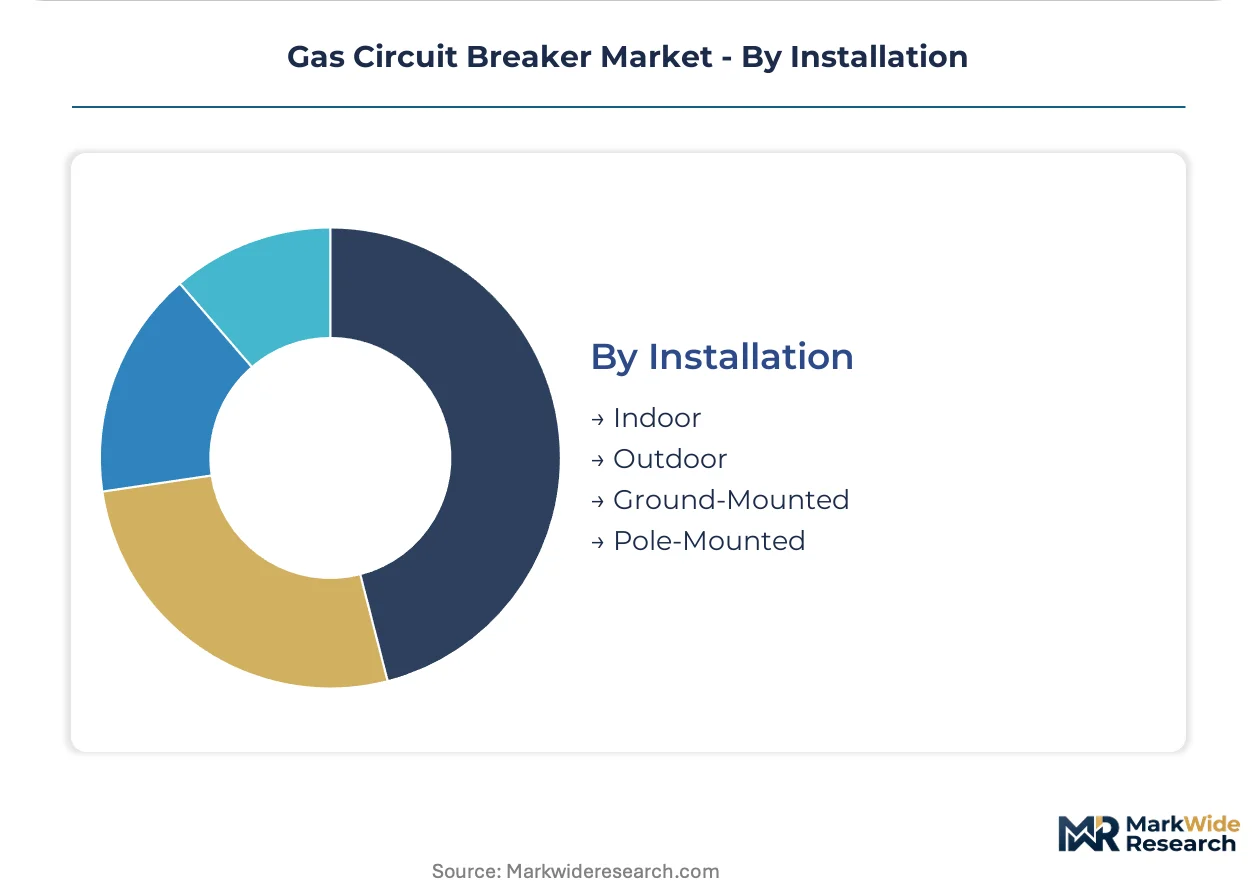
Installation:
Application environment dictates enclosure specifications and accessibility requirements for maintenance crews.
- Outdoor:Exposed installations dominate transmission corridors and rural substations across China and India. These configurations withstand environmental stress but require periodic inspection protocols.
- Indoor:Controlled-environment housing protects sensitive components in urban substations and industrial facilities. Demand concentrates in dense metropolitan clusters where equipment longevity depends on climate control.
- Ground-Mounted:Foundation-based installations provide stability for high-voltage assemblies.
- Pole-Mounted:Elevated configurations serve distribution networks with right-of-way constraints.
Outdoor installations hold the majority of deployed units; indoor configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement concentrates in China, India, and Germany as transmission operators modernize grid infrastructure to accommodate renewable energy integration and comply with tightening environmental regulations.
China
State Grid Corporation and China Southern Power Grid are expanding 800 kV ultra-high-voltage corridors to transmit remote wind and solar generation to coastal load centers. The National Energy Administration mandates SF6 emissions monitoring under dual carbon goals. Manufacturing clusters in Xi'an and Shenyang produce breaker assemblies for domestic deployment and Belt and Road export contracts.
Germany
TenneT and 50Hertz are piloting fluoronitrile-based breakers at 145 kV and 245 kV ratings ahead of EU F-Gas phase-down deadlines. The EU F-Gas Regulation mandates sealed-pressure system designs eliminating routine gas handling. Industrial concentration in Bavaria and North Rhine-Westphalia hosts service operations for Europe's largest installed SF6 base.
India
Power Grid Corporation of India is tendering 765 kV and 400 kV breaker packages for green energy corridor expansion. The Central Electricity Authority mandates technical specifications favoring gas-insulated switchgear for metropolitan substations. Manufacturing activity clusters in Gujarat and Maharashtra where domestic producers assemble systems for state transmission utilities.
Japan
Tokyo Electric Power and Chubu Electric specify compact gas-insulated designs for urban substations where land scarcity commands premium pricing. METI promotes alternative gas qualification through national demonstration programs. Production and testing facilities concentrate in the Kansai region serving domestic utilities and Southeast Asian export markets.
United States
ERCOT and CAISO operators are procuring high-voltage breakers for transmission reinforcement and renewable interconnection queues. The EPA enforces SF6 emissions reporting under greenhouse gas protocols. Equipment specification activity concentrates in Texas and California where grid modernization investments respond to extreme weather resilience mandates.
Gas Circuit Breaker Market Vendor Landscape
European producers anchor the premium-tier service contract segment; Japanese and Korean specialists hold positions in compact gas-insulated architectures. The vendor structure concentrates among integrated electrical equipment conglomerates with in-house gas handling capabilities and certified testing infrastructure. Three archetypes dominate: full-spectrum grid solution providers, gas-insulated switchgear specialists, and regional fabrication houses serving domestic procurement. Competitive moves center on long-term service agreement expansion and alternative gas qualification ahead of regulatory deadlines.
Within the integrated solution provider tier, ABB and Siemens Energy occupy positions defined by installed base scale and lifecycle service relationships. Mitsubishi Electric Corporation exemplifies the gas-insulated specialization archetype, with geographic origin and corporate structure reflecting concentrated Asian market presence. These three entities represent the competitive anchors around which procurement consolidation and technology transition dynamics are reorganizing vendor-customer relationships.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens Energy |
| Mitsubishi Electric Corporation |
| GE |
| Hitachi |
| Toshiba |
| Eaton |
| China XD Group |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China and state-linked transmission operators in India anchor procurement consolidation, compressing vendor margins while concentrating bargaining power among a handful of national buyers. This ownership pattern tightens pricing discipline across the supply base, forcing manufacturers to absorb input volatility or surrender market position.
Pricing Analysis
Volume procurement by State Grid Corporation and Power Grid Corporation of India commands standard-tier pricing, while specialized fluoronitrile blends for EU compliance absorb premium-mid-economy pricing differentiation. Certification under IEC and IEEE protocols separates qualified suppliers from uncertified competitors, creating tiered access to high-voltage tenders. Cost compression in alternative gas product lines is intensifying because fluoronitrile blends command three to four times the cost per kilogram of sulfur hexafluoride. Industrial sector buyers exhibit the highest price sensitivity due to captive substation economics, whereas German transmission operators accept premiums for sealed-pressure system compliance.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and German chemical suppliers for high-purity sulfur hexafluoride production, exposing breaker manufacturers to input constraints during phase-down periods. Manufacturing draws from specialty steel forgings, precision-machined aluminum castings, and gas handling equipment anchored in Germany, Japan, and China. Regulatory restriction through the EU F-Gas Regulation compresses available supply channels for fluorinated gases. Distribution runs through direct procurement relationships between national transmission operators and original equipment manufacturers, displacing traditional distributor networks in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas circuit breaker market functions as a vertical-integration race, with incumbents pursuing backward integration into gas handling capabilities and alternative gas formulation to secure supply certainty ahead of regulatory deadlines.
For Market Incumbents: Extend service contract coverage across Europe's installed SF6 base to lock in fifteen to twenty-year revenue streams before alternative gas displacement accelerates. Deepen in-house production of fluoronitrile blending capabilities to reduce dependency on Chinese and German chemical suppliers. Certification investment under tightened IEC protocols represents the critical defensive lever against emerging Asian competitors. For New Entrants and Emerging Players: Renewable energy project developers present the most penetrable buyer archetype, as intermittent grid interconnection demand creates procurement windows outside incumbent utility relationships. Focus initial commercialization on hybrid breaker architectures serving utilities seeking phased transition paths from pure SF6 designs. A direct EPC partnership model bypasses established distributor networks that incumbent vendors dominate. For Investors and Strategic Acquirers: Distressed-cycle entries favor European service operations with captive installed base access in Germany and France, where gas recovery and reprocessing revenue streams stabilize cash flows through technology transition periods. Target acquisition archetypes include regional fabrication houses with certified testing infrastructure and existing utility relationships. The signal to watch is EU F-Gas Regulation enforcement intensity, which determines the pace of legacy equipment replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Gas Qualification | IEC certification for fluoronitrile blends unlocks EU procurement ahead of phase-down deadlines. |
| Backward Integration into Gas Handling | In-house fluoronitrile blending reduces exposure to Chinese and German chemical supply concentration. |
| Long-term Service Agreement Expansion | Fifteen to twenty-year contracts with State Grid and Power Grid Corporation generate predictable aftermarket revenue. |
| Hybrid Breaker Platform Development | Vacuum interrupter designs bridge legacy SF6 and full alternative gas displacement for risk-averse utilities. |
| Direct Procurement Relationship Building | Bypassing distributor networks in India and Brazil captures margin from national transmission operator consolidation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with utility planning officers, EPC contractors, gas handling equipment procurement leads, and aftermarket service heads. Specific sources included EPA greenhouse gas emission reports, EU ECHA regulatory submissions, Central Electricity Authority technical specifications, and import-export documentation from customs authorities in China, Germany, and India. Bottom-up equipment shipment tracking and top-down grid investment flow analysis provided cross-validation.
Granularity-level modeling addressed voltage class, gas technology type, installation environment, and end-user procurement scale across the projection horizon. CAGRs derived from regression analysis against transmission infrastructure investment cycles and renewable energy capacity addition trajectories. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and national grid modernization program announcements from State Grid Corporation and Power Grid Corporation of India.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to alternative gas certification timelines and regulatory enforcement intensity. Forecasts reflect assumptions about technology substitution rates and utility procurement behavior without predetermined outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
Motor Generator Set Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market