
 Europe Alternating Current (AC) Drive Market | 2026-2036
Europe Alternating Current (AC) Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Alternating Current (AC) Drive Market Foresight
A widening capability gap in power-electronics manufacturing is rotating capital toward integrated semiconductor foundries and in-house module production. ABB Ltd leverages its Swiss-Swedish manufacturing footprint to sustain captive IGBT supply chains across Nordic and DACH markets. Siemens AG anchors its position through deep R&D intensity in digital-twin-enabled drive diagnostics, while Danfoss A/S differentiates via specialized thermal-management architectures for harsh-environment deployments.
An alternating current (AC) drive is a power-electronics system that converts fixed-frequency grid supply into variable-voltage, variable-frequency output to control induction or synchronous motor speed, typically operating across 0.2 kW to multi-MW ranges with switching frequencies between 2–16 kHz. Its primary industrial purpose is to modulate torque and rotational speed for energy savings, process precision, and mechanical stress reduction in motor-driven equipment. VFD technology occupies the dominant share of installed base across European manufacturing and infrastructure, while servo drive configurations are gaining traction in packaging and robotics applications demanding sub-millisecond position control. Vector drive architectures are displacing simpler scalar methods in crane and hoist systems where full torque at zero speed is required.
The EU Ecodesign Directive and F-Gas Regulation are mandating minimum motor-efficiency tiers and phasing down high-global-warming-potential refrigerants, which compels compressor and pump OEMs to specify premium drive systems that optimize partial-load performance. CE marking under the Machinery Directive and harmonized IEC 61800 standards govern electromagnetic compatibility and functional safety, creating compliance barriers for non-European suppliers without localized certification infrastructure. Stakeholders must monitor how the EU AI Act and incoming Cyber Resilience Act will impose algorithmic transparency and software-update obligations on connected drive platforms before their enforcement timelines crystallize.
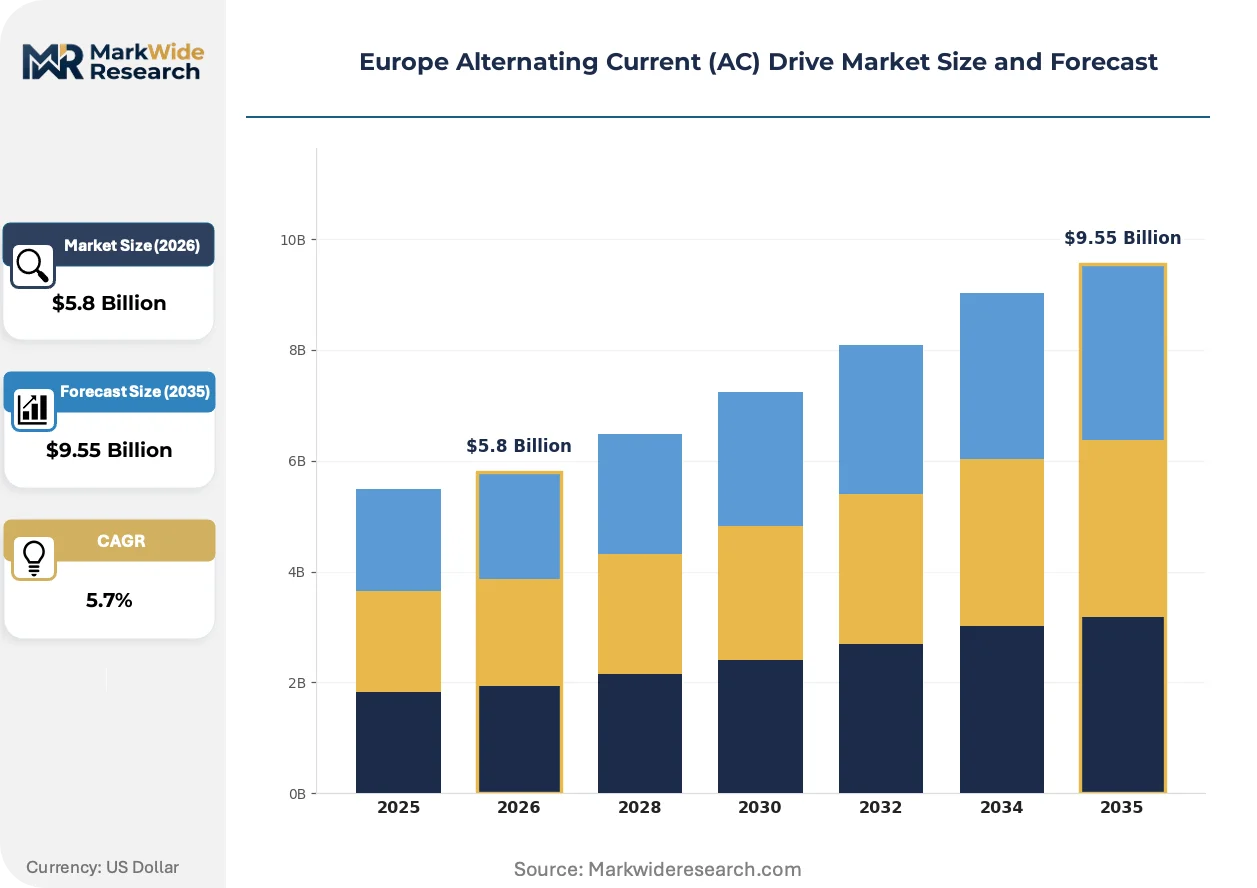
Market Dynamics
EU Ecodesign Directive efficiency tiers and F-Gas Regulation refrigerant phase-downs are compelling compressor and pump OEMs to specify premium drive architectures that optimize partial-load performance, restructuring procurement specifications across German, French, and Italian manufacturing corridors.
Growth Catalysts
- EU Ecodesign Directive:Mandatory IE4/IE5 motor-efficiency tiers force industrial operators to retrofit legacy systems with variable-frequency drives, accelerating replacement cycles in water treatment infrastructure across Germany, France, and Italy.
- Automotive electrification:Battery gigafactory construction in German manufacturing corridors demands precision motor control for electrode coating and cell assembly lines, pulling high-performance servo drive configurations.
- IGBT supply chain regionalization:Integrated semiconductor foundry investments across Nordic and DACH markets reduce import dependency for power modules, shortening lead times for domestic drive manufacturers.
Market Restraints
- Silicon carbide substrate scarcity:Wide-bandgap semiconductor raw material concentration in limited Asian processing facilities creates input cost volatility for next-generation drive inverter designs.
- CE marking compliance burden:Harmonized IEC 61800 electromagnetic compatibility and functional safety certification requirements impose multi-month validation timelines, creating regulatory friction for non-European suppliers without localized testing infrastructure.
- Scalar VFD commoditization:Basic variable-frequency drive architectures face price compression from standardized Chinese imports, eroding margin pools for European manufacturers in low-specification applications.
Strategic Opportunities
- Polish industrial corridor expansion:Central European manufacturing relocation from higher-cost Western markets creates underpenetrated demand for mid-range drive systems in automotive component and appliance production.
- EU AI Act convergence:Algorithmic transparency and software-update obligations for connected drive platforms create first-mover advantage for vendors with embedded digital-twin diagnostics and predictive maintenance capabilities.
- Marine propulsion electrification:Inland waterway vessel retrofit programs in Dutch and German port cities open specialized applications for harsh-environment thermal-management architectures.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized firmware development and thermal design expertise shortages extend product development cycles for advanced vector control algorithms.
- Legacy system integration complexity:Proprietary fieldbus protocols in installed industrial automation bases require custom gateway development, inflating commissioning costs and technical risk for brownfield deployments.
- Cyber Resilience Act preparation:Incoming software-update and vulnerability-disclosure mandates demand organizational restructuring for drive OEMs without established product security functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Alternating Current (AC) Drive Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: VFD, Servo, DC Drive, Vector Drive End User: Manufacturing, Oil & Gas, Water Treatment, Mining Application: Conveyors, Pumps, Fans, Compressors Installation Type: Indoor, Outdoor, Permanent, Portable |
| Companies Covered | ABB Ltd, Siemens AG, Schneider Electric SE, Danfoss A/S, Yaskawa Electric Corporation, Rockwell Automation, Fuji Electric Co. Ltd., Mitsubishi Electric Corporation, Emerson Electric Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Alternating Current (AC) Drive Market Shifts & Advancements
Digital-twin-enabled diagnostics and wide-bandgap semiconductor architectures are restructuring competitive differentiation, while regulatory software obligations and procurement centralization are reshaping vendor-customer relationships across European industrial automation.
Silicon carbide MOSFET power modules enable higher switching frequencies with reduced thermal losses compared to silicon IGBT predecessors. German automotive and chemical producers are adopting these architectures for multi-megawatt compressor and extruder applications. This transition is displacing traditional two-level inverter topologies in premium drive segments where energy recovery and compact form factors command specification priority.
F-Gas Regulation refrigerant phase-down schedules are mandating lower-global-warming-potential alternatives in HVAC and refrigeration systems. Compressor OEMs must specify drives with enhanced partial-load efficiency maps to maintain system performance with reduced refrigerant charge volumes. Italian and Spanish cold-chain infrastructure operators are retrofitting warehouse refrigeration with premium variable-speed drives to meet these tightening environmental compliance thresholds.
Industrial procurement functions are consolidating supplier relationships around full-lifecycle service agreements rather than transactional hardware purchases. German automotive tier-one suppliers now bundle drive specification with predictive maintenance subscriptions and energy-performance guarantees. This reconfiguration concentrates contract awards on vendors with localized service networks and digital platform integration capabilities, marginalizing pure hardware manufacturers without software competencies.
Europe Alternating Current (AC) Drive Market Segmentation
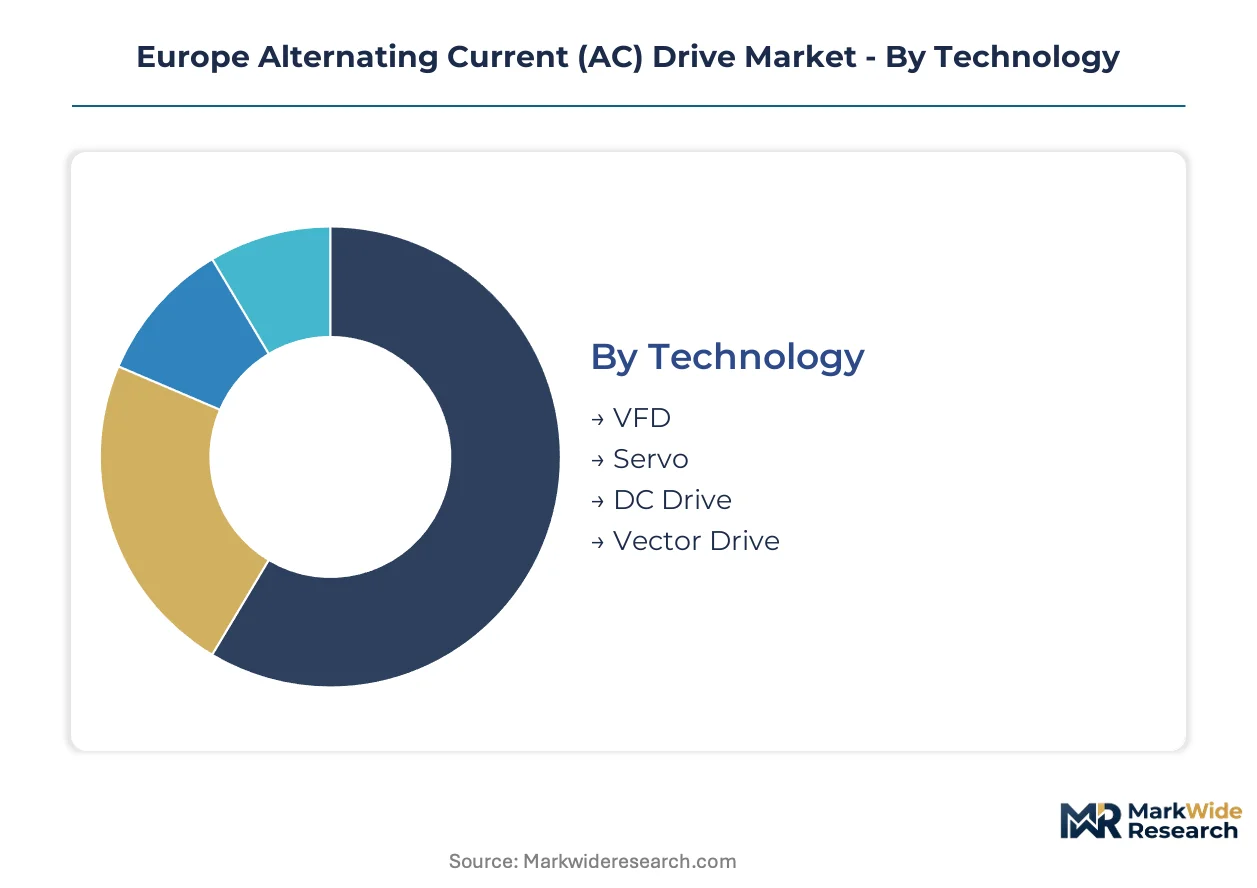
AC drive segmentation in Europe reflects divergent compliance burdens across technology tiers and application environments. Procurement specifications now stratify around IE4/IE5 motor-efficiency mandates under the EU Ecodesign Directive and thermal-performance requirements for F-Gas-regulated refrigerant systems.
Technology:
CE marking under IEC 61800 standards and Machinery Directive safety requirements create divergent certification timelines across power-electronics architectures, concentrating procurement spend on platforms with pre-validated electromagnetic compatibility.
- VFD:Variable-frequency drives convert fixed-frequency grid supply to variable-voltage, variable-frequency output for induction motor speed control. German automotive and chemical producers specify these for energy recovery in multi-megawatt compressor applications, driven by Ecodesign Directive retrofit mandates.
- Servo:Closed-loop motor control systems deliver sub-millisecond position feedback for precision motion applications. Battery gigafactory construction across German manufacturing corridors pulls high-performance configurations for electrode coating and cell assembly lines.
- DC Drive:Legacy thyristor-based architectures persist in crane and hoist retrofits where existing motor infrastructure resists replacement.
- Vector Drive:Field-oriented control algorithms enable full torque at zero speed for extruder and heavy-lift applications.
VFD handles the majority of throughput; Servo is gaining share fastest on battery manufacturing expansion.
End User:
Capital intensity and process-criticality separate price-tolerant specification environments from cost-constrained procurement.
- Manufacturing:Automotive tier-one suppliers bundle drive hardware with predictive maintenance subscriptions and energy-performance guarantees, concentrating contract awards on vendors with localized service networks.
- Oil & Gas:Upstream and midstream operators demand explosion-proof enclosures and extended temperature ranges for North Sea and Caspian corridor deployments.
- Water Treatment:Municipal infrastructure across Germany, France, and Italy retrofits legacy pumping stations with premium drives to meet Ecodesign Directive efficiency tiers.
- Mining:Underground and open-pit extraction operations require ruggedized thermal management for high-altitude and dusty environments.
Manufacturing commands the largest installed base; Water Treatment is expanding most quickly on infrastructure modernization programs.
Application:
Load-profile characteristics determine inverter topology selection and partial-load efficiency mapping priorities.
- Pumps:Centrifugal and positive-displacement pumping systems dominate variable-torque applications. Italian and Spanish cold-chain operators retrofit warehouse refrigeration with premium drives to maintain performance under F-Gas Regulation refrigerant phase-downs.
- Compressors:Rotary and reciprocating compression equipment requires enhanced partial-load efficiency maps for reduced-refrigerant-charge HVAC systems.
- Conveyors:Material handling systems in Polish automotive component plants demand mid-range drive configurations.
- Fans:Centrifugal and axial ventilation equipment specifies scalar control in cost-sensitive building automation.
Pumps absorb the highest volume of installed drives; Compressors is climbing the fastest on refrigerant-regulation compliance.
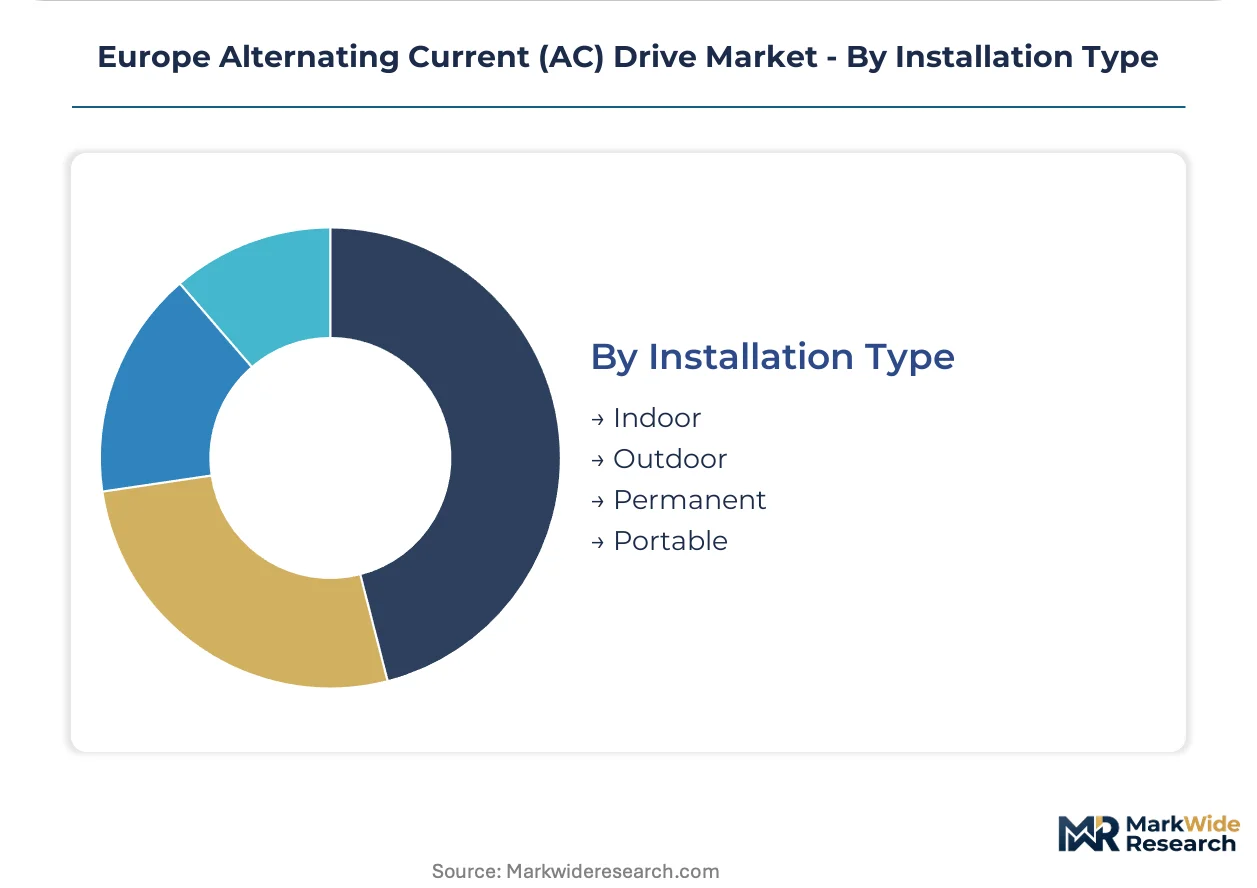
Installation Type:
Environmental exposure and mobility requirements dictate enclosure ratings and thermal-design intensity.
- Indoor:Climate-controlled factory environments specify standard IP ratings with passive cooling.
- Outdoor:Dutch and German inland waterway vessel retrofits demand harsh-environment thermal-management architectures for deck-mounted propulsion drives.
- Permanent:Fixed industrial infrastructure commits to long-lifecycle service agreements with embedded digital-twin diagnostics.
- Portable:Mobile equipment rental pools require plug-and-play commissioning for temporary construction and event power.
Indoor accounts for the greatest deployment volume; Outdoor is the fastest mover on marine electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German manufacturing corridors while Italian and Spanish operators face margin compression from standardized import competition. Nordic markets command premiums for harsh-environment specifications. Central European expansion corridors attract mid-range volume plays.
Germany
Automotive battery gigafactories and chemical extruder retrofits pull high-performance servo and vector drive configurations. The EU Ecodesign Directive mandates IE4/IE5 motor-efficiency tiers, forcing replacement cycles in Baden-Württemberg and Bavaria industrial zones. Stuttgart and Munich manufacturing clusters specify predictive maintenance subscriptions bundled with hardware procurement.
France
Nuclear maintenance programs and pharmaceutical cleanroom automation sustain demand for precision motor control. CE marking under IEC 61800 standards and Machinery Directive safety requirements filter non-compliant imports from tender participation. Lyon and Grenoble industrial corridors prioritize digital-twin-enabled diagnostics for process-critical applications.
Italy
Cold-chain warehouse refrigeration retrofits absorb premium variable-speed drives to meet F-Gas Regulation refrigerant phase-down schedules. Packaging machinery OEMs in Emilia-Romagna specify servo configurations for sub-millisecond position control. Milan and Turin automation clusters face price pressure from standardized Chinese VFD imports in scalar applications.
Netherlands
Rotterdam and Amsterdam port authorities electrify inland waterway vessels, demanding deck-mounted propulsion drives with harsh-environment thermal management. Dutch greenhouse horticulture operators retrofit ventilation systems for partial-load efficiency optimization. The national climate agreement accelerates pump station modernization across delta water management infrastructure.
Poland
Automotive component manufacturing relocation from Western Europe creates underpenetrated demand for mid-range conveyor and pump drive systems. Warsaw and Krakow industrial zones attract appliance production facilities specifying cost-optimized VFD architectures. EU cohesion funds finance water treatment infrastructure upgrades with Ecodesign-compliant motor systems.
Europe Alternating Current (AC) Drive Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure with limited overlap. Swiss-Swedish and German conglomerates anchor the premium segment through captive semiconductor supply chains and embedded software platforms. Mid-tier specialists compete on application-specific thermal architectures and regional service density. Consolidation pressure intensifies as procurement centralization favors vendors with full-lifecycle service capabilities.
Within the integrated multinational tier, ABB Ltd and Siemens AG exemplify divergent strategic positioning. ABB leverages its Swiss-Swedish manufacturing footprint to sustain captive IGBT supply chains across Nordic and DACH markets. Siemens anchors its position through deep R&D intensity in digital-twin-enabled drive diagnostics. Danfoss A/S occupies a specialized position via thermal-management architectures for harsh-environment deployments.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Danfoss A/S |
| Yaskawa Electric Corporation |
| Rockwell Automation |
| Fuji Electric Co. Ltd. |
| Mitsubishi Electric Corporation |
| Emerson Electric Co. |
| Others |
Supply & Pricing Matrix
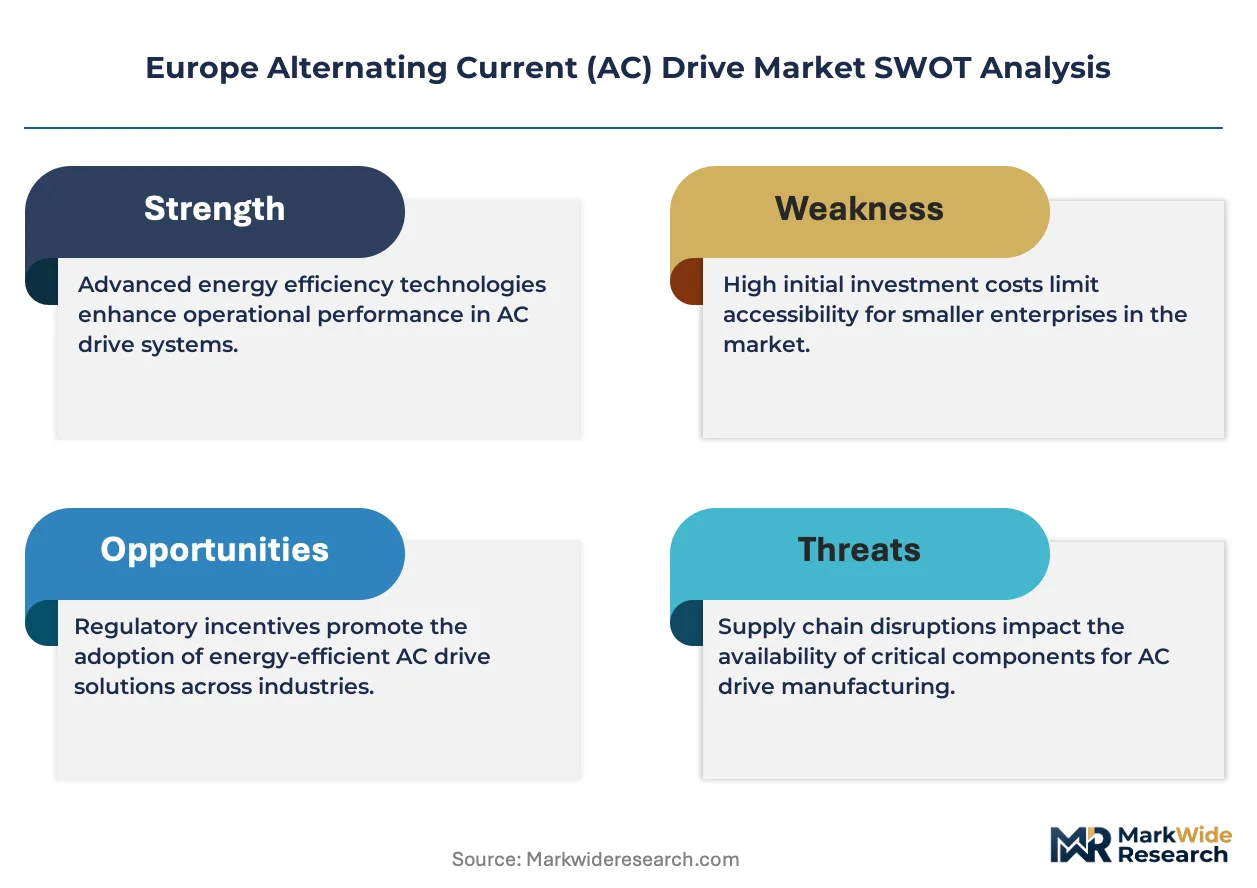
Capacity utilization at integrated semiconductor foundries across Nordic and DACH markets establishes scale thresholds that compress unit economics for power modules, concentrating pricing power among manufacturers with captive IGBT supply while forcing smaller European drive OEMs toward standard component sourcing or margin sacrifice.
Pricing Analysis
Configured-to-order pricing for vector and servo architectures commands substantial premiums over scalar VFD spot pricing, with differentiation driven by CE marking certification grade and embedded digital-twin diagnostics capability. Pricing pressure stems from standardized Chinese VFD imports flooding low-specification applications in Italian and Spanish manufacturing corridors. Automotive tier-one suppliers in Germany exhibit lowest price sensitivity due to bundled lifecycle service agreements, while Polish appliance manufacturers remain most cost-constrained.
Supply Chain Analysis
Strategic stockpiling of silicon carbide substrates and IGBT modules dominates inventory strategy as lead time volatility from Asian processing facilities disrupts just-in-time preferences. Power electronics manufacturing draws from Taiwan, Germany, and Japan for semiconductor components, with raw material dependencies on silicon carbide wafers, copper busbars, and rare-earth magnetic materials. Single-source vulnerability in wide-bandgap substrate processing creates structural risk. Distribution runs through authorized system integrators and OEM direct channels for premium tiers, with volume resellers handling standardized imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against direct-drive permanent magnet motors and integrated motor-drive units that bypass discrete VFD architectures in high-efficiency applications.
For Market Incumbents: Fortify captive semiconductor supply through backward integration into module packaging or long-term foundry offtake agreements with Nordic suppliers. Deepen software platform stickiness by embedding EU AI Act-compliant predictive maintenance algorithms that raise switching costs for manufacturing customers. The CE marking compliance burden and incoming Cyber Resilience Act mandates create defensive moats against non-European competitors lacking localized certification infrastructure. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany or France enables market entry before full IEC 61800 validation timelines conclude. Polish industrial corridors offer the most penetrable geography for mid-range drive systems, with EU cohesion funds financing water treatment infrastructure that specifies Ecodesign-compliant equipment. A servo-drive specialization for battery gigafactory electrode coating lines provides the clearest go-to-market angle against entrenched VFD incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor-integrated drive specialists with digital-twin capabilities over pure hardware manufacturers. Long-term viability hinges on software recurring revenue attachment rates and service network density across DACH manufacturing clusters. The inflection signal to monitor is silicon carbide MOSFET cost parity against silicon IGBT, which would accelerate topology transitions and reshape competitive tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Foundry Partnership | Secures captive IGBT supply for ABB and Siemens against Asian substrate volatility. |
| Digital-Twin Platform Launch | Enables predictive maintenance subscriptions that German automotive tier-ones now require. |
| CE Marking Fast-Track Investment | Shortens multi-month IEC 61800 validation timelines for non-European market entrants. |
| Polish Service Network Expansion | Captures mid-range volume from automotive component relocation into Central Europe. |
| Silicon Carbide Topology Transition | Positions premium drive portfolios for F-Gas Regulation compressor retrofit cycles. |
Research Methodology
A spread of perspectives from drive OEM product managers, industrial plant engineers, semiconductor procurement leads, and aftermarket service heads converged on the working assumptions that shape this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed automation suppliers, EU Ecodesign Directive implementation reports, and customs data on power electronics trade flows. Bottom-up unit shipment estimates by technology tier and top-down industrial automation spending analysis were triangulated against Nordic and DACH manufacturing investment disclosures.
Segmentation dimensions modeled span technology architecture, end-user industry vertical, application load profile, and installation environment across the projection horizon. CAGRs were derived from installed base replacement cycles, Ecodesign Directive enforcement timelines, and battery manufacturing capacity expansion in German corridors. Industry-specific forecast inputs include F-Gas Regulation refrigerant phase-down schedules and EU AI Act algorithmic transparency obligations.
Underlying assumptions cover stable EU regulatory enforcement, intact semiconductor supply from Taiwan and Germany, and continued automotive electrification investment, with deviation risk concentrated in silicon carbide substrate availability and Cyber Resilience Act implementation timing. Revision becomes warranted when wide-bandgap semiconductor cost curves cross silicon IGBT parity thresholds or when EU AI Act enforcement timelines accelerate beyond current guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Marine Switchboard Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market