
 Skid Mounted Unit Substations Market | 2026-2036
Skid Mounted Unit Substations Market Size, Share, and Industry Trends Forecast 2026-2036
Skid Mounted Unit Substations Market Analysis
Data center power infrastructure is hardening demand for skid mounted unit substations as hyperscale operators prioritize rapid deployment and space-constrained installations. ABB leverages its medium voltage technology leadership to dominate European utility tenders, while Siemens sustains competitive positioning through integrated digital monitoring platforms. General Electric anchors North American market presence with heavy industrial and oilfield applications.
A skid mounted unit substation is a factory-assembled electrical power distribution system mounted on a structural steel base, typically integrating transformers, switchgear, and protection equipment rated from low voltage through extra high voltage for rapid field deployment. These systems serve critical industrial, commercial, and utility applications where minimized on-site construction time and standardized quality control are essential. Three phase configurations command the largest installed base due to universal industrial compatibility, while custom built designs capture premium margin pools from project-specific engineering requirements. Medium voltage ratings represent the fastest-growing power class as distributed generation and microgrid integration expand across commercial and utility end users.
The National Electrical Manufacturers Association sets enclosure and busbar standards that govern product interoperability across US installations, while IEC frameworks shape export market access for manufacturers targeting Europe and Asia-Pacific regions. IEEE standards for transformer and switchgear integration directly influence procurement specifications from utilities and large industrial buyers. Stakeholders must monitor evolving grid interconnection codes and carbon disclosure requirements as these frameworks increasingly specify modular equipment lifecycle documentation and efficiency thresholds.
Market Dynamics
Factory pre-assembly of medium voltage substations is compressing project timelines for data center operators and industrial cluster developers who cannot tolerate extended on-site construction windows. IEEE 1547 interconnection standards and NEMA enclosure classifications are tightening procurement specifications, forcing manufacturers to integrate digital monitoring and arc-flash mitigation at the design stage rather than as field add-ons.
Growth Catalysts
- Data center power densification:Hyperscale operators in Northern Virginia, Frankfurt, and Singapore are specifying skid-mounted solutions to accelerate energization timelines for facilities exceeding 100MW capacity.
- IEEE 1547-2018 revision:Updated grid interconnection requirements for distributed energy resources are mandating factory-tested protection coordination that favors pre-integrated substation architectures.
- Industrial cluster electrification:Chemical processing hubs along the US Gulf Coast and refining complexes in Gujarat, India are replacing aging outdoor switchyards with compact modular units to minimize footprint constraints.
Market Restraints
- Grain-oriented electrical steel concentration:Supply of transformer core material concentrates among Japanese and Chinese metallurgical producers, exposing lead times to export quota volatility.
- Medium voltage switchgear qualification costs:Type testing to IEC 62271-200 standards for internal arc classification requires capital-intensive high-current laboratories accessible only through third-party facilities in Europe and East Asia.
- On-site commissioning complexity:Despite factory pre-wiring, final energization still demands specialized medium voltage technicians whose certification pools remain shallow outside established industrial markets.
Strategic Opportunities
- Offshore wind marshaling ports:US East Coast and North Sea offshore wind installation hubs require mobile substation solutions for construction-phase power that can relocate between lease areas.
- CEA technical standards harmonization:India's Central Electricity Authority is consolidating state-level electrical inspectorate requirements, creating a single national certification pathway for factory-assembled substations.
- Digital twin integration:Convergence of SCADA-ready switchgear with asset performance management platforms enables predictive maintenance contracts that extend manufacturer revenue streams beyond equipment sale.
Industry Challenges
- Arc flash engineering specialization:Design of incident energy mitigation systems requires certified power system engineers whose training programs have not scaled with market expansion.
- Legacy oil-filled transformer replacement:Decommissioning PCB-contaminated units from 1970s industrial installations triggers extended environmental remediation timelines that stall greenfield skid-mounted deployments on brownfield sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skid Mounted Unit Substations Market |
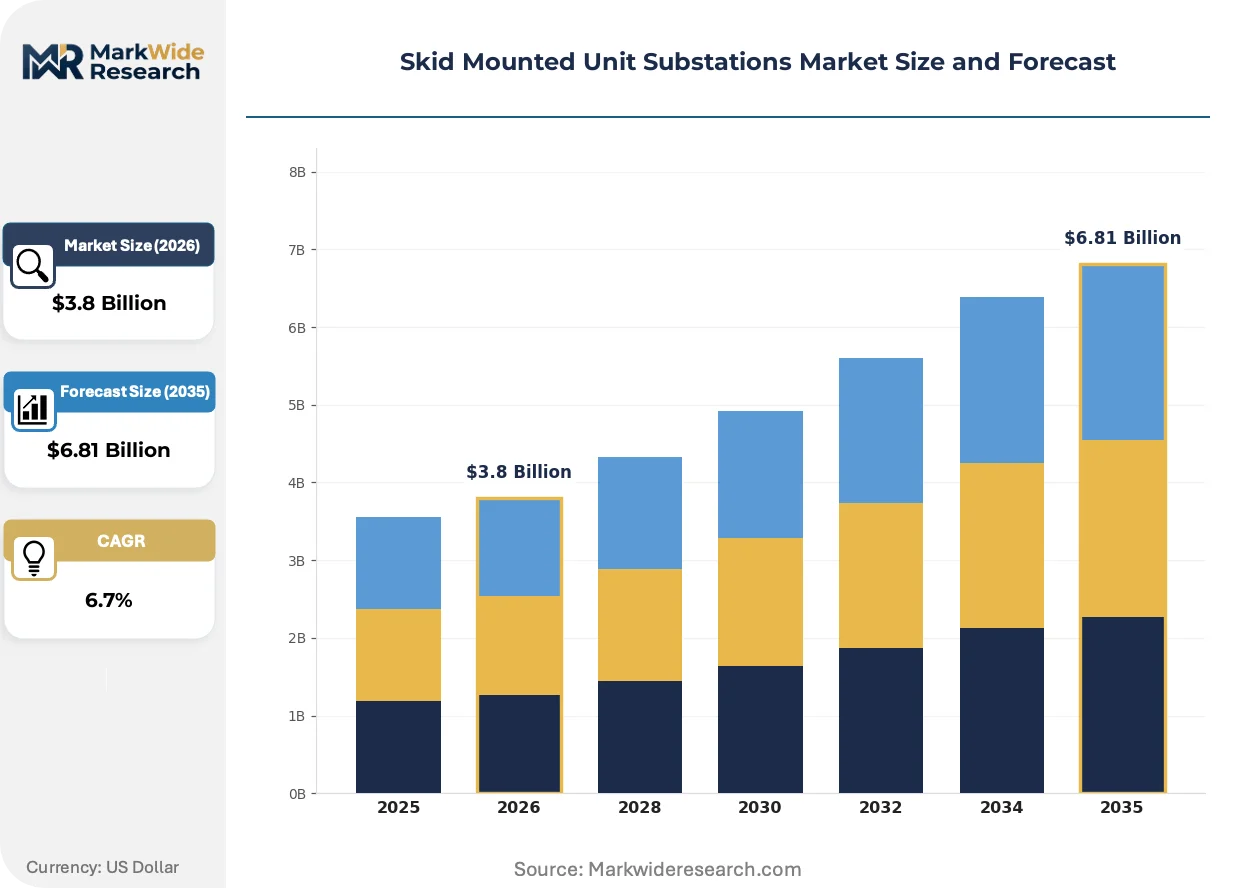
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Phase, Three Phase, Compact, Custom Built End User: Industrial, Commercial, Utilities, Construction Installation Type: Onshore, Offshore, Urban, Rural Power Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | General Electric, WEG, ABB, Toshiba, CG Power and Industrial Solutions, Siemens, Mitsubishi Electric, Mobile Energy, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skid Mounted Unit Substations Market Emerging Trajectories
Silicon carbide power electronics and gas-insulated switchgear miniaturization are redefining thermal management and spatial efficiency expectations for modular substation platforms. These advances intersect with tightening carbon disclosure mandates and compressed project delivery schedules across utility and industrial procurement.
Solid-state transformer architectures incorporating silicon carbide MOSFETs are electrifying medium voltage distribution efficiency benchmarks. Data center operators in Phoenix and Amsterdam are piloting 10kV-class units that eliminate conventional liquid-immersed transformers entirely. This topology is compressing substation footprints by sixty percent while enabling direct DC microgrid coupling for battery storage integration.
The EU F-Gas Regulation phase-down of sulfur hexafluoride is compelling switchgear manufacturers to accelerate vacuum interrupter and fluoronitrile insulation development. Industrial buyers in Germany and France now specify SF6-free alternatives in tender documents, forcing design cycle retooling across European supply chains. Medium voltage ratings between 15kV and 38kV face the steepest compliance timeline pressure.
Engineer-procure-construct contractors are unbundling after-sales service from equipment supply, creating standalone commissioning and long-term maintenance markets. This disintermediation is most visible in US utility-scale solar and storage projects where independent service providers now compete directly with OEM service organizations for multi-year operations contracts.
Skid Mounted Unit Substations Market Segmentation
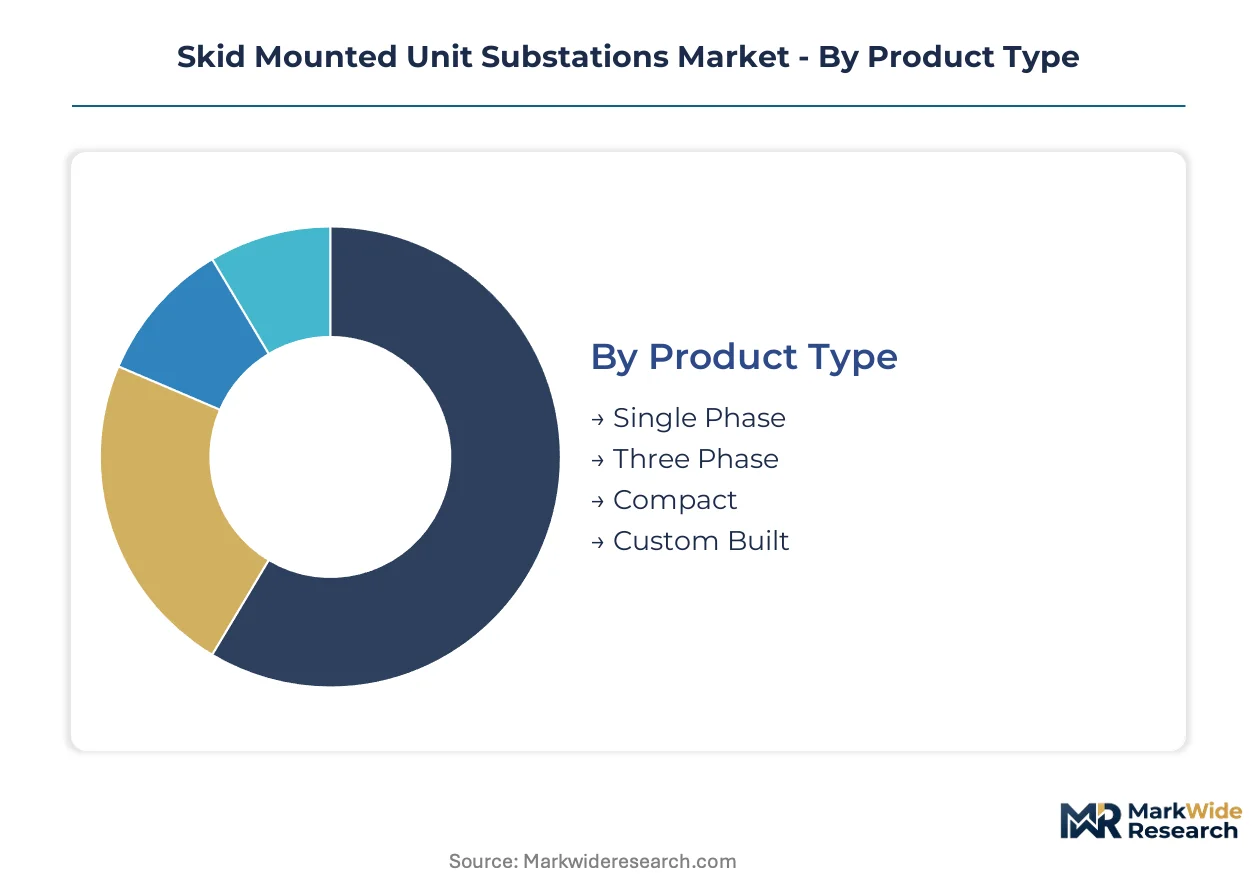
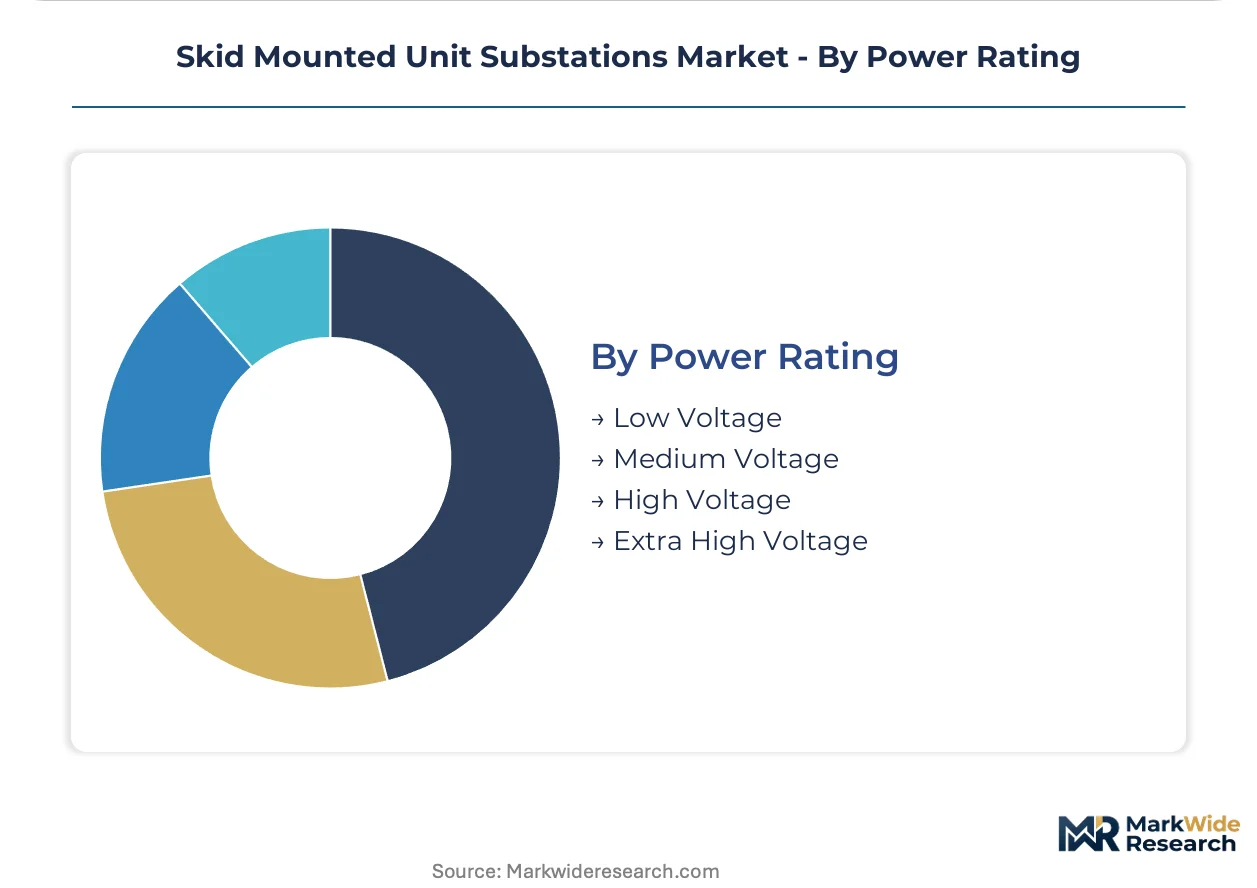
Skid mounted unit substation buyers prioritize different technical specifications based on their deployment constraints. Voltage class, phase configuration, and factory customization depth each create distinct procurement segments with diverging margin profiles and supplier qualification requirements.
Product Type:
Electrical configuration and physical footprint drive the primary differentiation between buyers in this category.
- Three Phase:Industrial-grade configuration delivering balanced power distribution across heavy machinery loads. Chemical processing facilities along the US Gulf Coast specify these units for their 480V distribution networks, constrained by IEEE 1547 harmonic compliance mandates.
- Custom Built:Engineer-to-order systems integrating project-specific transformer impedances, busbar ratings, and arc-flash containment. Offshore wind marshaling ports in Germany and Denmark commission these for mobile construction-phase power that relocates between lease areas.
- Single Phase:Residential and light commercial applications requiring simplified protection coordination.
- Compact:Space-constrained urban installations prioritizing reduced footprint over service accessibility.
Three Phase leads volumes today; Custom Built is gaining share fastest.
End User:
Application environment dictates the severity of uptime requirements and regulatory exposure.
- Industrial:Heavy manufacturing and petrochemical operations demanding fault-tolerant architectures with redundant transformer configurations. Refining complexes in Gujarat, India replace aging outdoor switchyards with these units to minimize footprint constraints under state electrical inspectorate consolidation.
- Utilities:Grid interconnection and distribution reinforcement applications requiring IEC 61850-compliant digital substation integration. US rural electric cooperatives deploy these for distributed solar and storage tie-ins facing FERC interconnection queue pressures.
- Commercial:Data center and retail facility power infrastructure prioritizing rapid energization schedules.
- Construction:Temporary power for infrastructure projects with mobile deployment requirements.
Industrial anchors revenue concentration; Utilities shows the steepest expansion trajectory.
Installation Type:
Environmental exposure and site accessibility determine enclosure ratings and structural engineering requirements.
- Onshore:Ground-mounted installations in controlled industrial environments with standard NEMA 3R or 4X enclosures. Northern Virginia data center clusters specify these for hyperscale facilities exceeding 100MW, compressed by land scarcity and permitting timelines.
- Offshore:Marine-rated platforms and vessels requiring corrosion-resistant coatings and motion-compensated transformer anchoring. North Sea wind installation contractors source these for turbine commissioning power that transfers between construction vessels.
- Urban:Space-constrained metropolitan deployments with reduced clearances and noise restrictions.
- Rural:Remote installations prioritizing transportability and minimal foundation requirements.
Onshore dominates current deployment; Offshore climbs the fastest as marine renewable construction accelerates.
Power Rating:
Voltage class selection correlates directly with grid interconnection tier and arc-flash engineering complexity.
- Medium Voltage:15kV through 38kV class integrating vacuum interrupters and SF6-free insulation alternatives. German and French industrial buyers now mandate these specifications under EU F-Gas Regulation phase-down timelines, forcing design retooling across European supply chains.
- Low Voltage:Sub-1kV distribution for commercial and light industrial facilities with simplified protection schemes.
- High Voltage:69kV through 138kV transmission-level interconnection requiring specialized bushing and surge arrester integration.
- Extra High Voltage:230kV and above for utility bulk power transfer with gas-insulated switchgear miniaturization.
Medium Voltage captures the largest share of new orders; High Voltage is expanding most quickly for utility-scale solar and storage integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting factory-assembled substation production toward jurisdictions with harmonized certification pathways and lower compliance friction. Manufacturers prioritize markets where IEEE, IEC, and national electrical inspectorate standards align to minimize design-to-delivery cycles.
United States
Hyperscale data center construction in Northern Virginia and Phoenix is compressing energization timelines below twelve months. FERC interconnection queue reforms and IEEE 1547-2018 compliance mandates favor factory-tested protection coordination. Texas Gulf Coast petrochemical clusters specify redundant transformer configurations to replace aging outdoor switchyards.
China
Dual carbon goals and industrial cluster electrification in Jiangsu and Shandong provinces are accelerating medium voltage substation procurement. MIIT efficiency standards and GB certification frameworks govern transformer integration specifications. Yangtze River Delta manufacturing hubs deploy mobile units for construction-phase power at offshore wind marshaling ports.
Germany
EU F-Gas Regulation phase-down timelines are forcing SF6-free switchgear retooling across Baden-Württemberg and Bavaria industrial corridors. REACH compliance and CE marking requirements shape enclosure and insulation material selection. North Sea wind installation contractors source corrosion-resistant platforms for turbine commissioning power transfer between lease areas.
India
CEA technical standards harmonization is consolidating state-level electrical inspectorate requirements into a single national certification pathway. PLI scheme incentives support domestic transformer core manufacturing in Gujarat and Maharashtra refining complexes. Telangana data center parks specify rapid-deployment substations to meet hyperscale operator land-leasing schedules.
Japan
METI grid modernization programs and JIS standards for modular electrical systems are tightening integration specifications for factory-assembled equipment. Osaka-Kobe industrial belt chemical processors replace oil-filled transformers from the 1970s with compact gas-insulated alternatives. Chubu region automotive battery gigafactories demand space-constrained urban installations with reduced clearances.
Skid Mounted Unit Substations Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electrical conglomerates dominating utility-scale tenders and regional fabricators capturing industrial project-specific orders. The vendor base concentrates among transformer-original-equipment manufacturers with captive switchgear integration capabilities and independent packagers sourcing components from tier-two suppliers. Three archetypes prevail: full-stack electrical majors with digital monitoring platforms, transformer-centric specialists backward-integrating into switchgear assembly, and EPC-affiliated packagers unbundling commissioning from equipment supply. Dominant competitive moves include geographic expansion through local certification partnerships and portfolio diversification into predictive maintenance service contracts.
Among the full-stack electrical majors, General Electric anchors North American positioning through heavy industrial and oilfield application expertise, while ABB leverages medium voltage technology leadership to dominate European utility tenders. Siemens occupies a position integrating digital monitoring platforms with factory-assembled architectures. These three exemplify the tier where scale and standards compliance create qualification barriers for mid-cap entrants.
| Leading Market Players |
|---|
| General Electric |
| WEG |
| ABB |
| Toshiba |
| CG Power and Industrial Solutions |
| Siemens |
| Mitsubishi Electric |
| Mobile Energy |
| Eaton |
| Others |
Supply Flow & Price Mechanics
Certified medium voltage technician pools in the US Gulf Coast and German industrial corridors create labor-cost differentials that widen pricing spreads between premium factory-tested units and standard configurations. This workforce concentration forces buyers in skill-scarce regions to absorb higher commissioning premiums or accept extended lead times for qualified installation teams.
Pricing Analysis
Distributor margins on skid mounted unit substations typically compress project-based quotations by eight to fifteen percent below direct-OEM procurement for utilities and hyperscale data center operators. Three-tier pricing structure across premium, standard, and economy levels separates arc-flash engineered custom builds from catalog medium voltage units and compact commercial configurations. Cost compression in the standard tier is intensifying because grain-oriented electrical steel supply volatility forces transformer OEMs to hedge material exposure through forward pricing clauses. Industrial cluster developers in India and China exhibit highest price sensitivity due to PLI scheme capital constraints, while North Sea offshore wind contractors show lowest sensitivity given mobilization-cost dominance over equipment procurement.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore anchor hub-and-spoke patterns for transformer core materials and vacuum interrupter assemblies serving project sites across three continents. Manufacturing concentration in China, Germany, and the United States shapes tier-one supply availability, with secondary sourcing from India and Japan for specialized busbar and insulation components. The supply chain draws from grain-oriented electrical steel mills in Japan and China, copper rod producers in Chile and Indonesia, and cast resin insulation compounders in Germany and Italy. Single-source vulnerability concentrates in Japanese metallurgical producers controlling transformer core material export quotas. Distribution runs through EPC contractor procurement desks for utility-scale deployments and direct OEM relationships for industrial repeat buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skid mounted unit substations market functions as a regulatory compounder where IEEE 1547-2018 grid interconnection mandates and EU F-Gas Regulation phase-down timelines continuously refresh equipment replacement cycles and specification upgrades.
For Market Incumbents: Cement technology leadership in silicon carbide solid-state transformer architectures before patent landscapes solidify around thermal management IP. Deepen backward integration into grain-oriented electrical steel trading desks to insulate margin exposure from Japanese export quota volatility. Arc-flash engineering certification scarcity among power system engineers threatens service revenue capture if training pipelines do not scale with installation base expansion.
For New Entrants and Emerging Players: Digital direct-sales platforms targeting mid-sized industrial facilities bypass entrenched distributor relationships that lock out unfamiliar brands from utility tender channels. White-space concentration sits with CEA harmonization-ready standard designs for Indian state electrical inspectorates consolidating certification pathways. Mobile commissioning service apps addressing technician shortage pain points offer the most penetrable service-layer entry before OEMs bundle predictive maintenance contracts.
For Investors and Strategic Acquirers: Electrical infrastructure private equity funds are the most active acquirer in this space, consolidating regional packagers with captive switchgear integration capabilities. Five-to-ten year viability hinges on digital twin platform penetration extending manufacturer revenue streams beyond equipment sale into recurring service contracts. Monitor offshore wind marshaling port deployment velocity as the critical inflection signal for mobile substation demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transformer Core Materials | Captive supply of grain-oriented electrical steel insulates margin exposure from Japanese export quota volatility. |
| Digital Twin Platform Development | SCADA-ready switchgear convergence with asset performance management enables predictive maintenance contract recurring revenue. |
| SF6-Free Switchgear Certification | EU F-Gas Regulation compliance opens German and French utility tenders to qualified European suppliers. |
| CEA Harmonization-Ready Design Investment | Single national certification pathway capture accelerates Indian industrial cluster and data center park penetration. |
| Offshore Wind Mobile Unit Fleet Expansion | North Sea and US East Coast turbine commissioning power demand relocates between lease areas without permanent installation. |
Methodological Framework
Direct dialogue with substation OEM product managers, EPC contractor procurement directors, utility interconnection planners, and certified medium voltage commissioning technicians grounded qualitative insights in operational reality. Secondary validation drew from IEEE standards documentation, NEMA enclosure classification databases, FERC interconnection queue filings, and customs trade records for transformer and switchgear component flows. Bottom-up unit economics triangulated against top-down industrial electrification capex projections.
Bottom-up modeling segmented volume and value across voltage class, phase configuration, installation environment, and end-user vertical throughout the projection horizon. CAGRs derived from unit shipment trajectories mapped to named data center development pipelines, offshore wind lease area awards, and industrial cluster electrification announcements. Forecast inputs incorporated IEEE 1547 revision implementation timelines, EU F-Gas Regulation phase-down milestones, and CEA technical standards harmonization progress.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide solid-state transformer commercialization would alter the outlook if thermal reliability thresholds delay utility-scale deployment. Forecasts reflect documented assumptions regarding grid interconnection queue reform velocity and carbon disclosure mandate enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Taiwan Electric Power Equipment Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Power Over Ethernet Lighting Market
Electrical Power Equipment
Portable Space Heater Market