
 MV Protection Relay Market | 2026-2036
MV Protection Relay Market Size, Share, and Industry Trends Forecast 2026-2036
MV Protection Relay Market Outlook
Project finance structures for greenfield substations and renewable integration projects is tilting procurement decisions toward vendors with balance-sheet capacity to underwrite long-term service contracts. Schneider Electric leverages its integrated digital energy platform to bundle protection relays with asset management software. Siemens anchors its position through deep manufacturing scale in IEC-rated protection hardware. ABB competes by specializing in transformer protection applications where fault discrimination algorithms command technical premiums.
An MV protection relay is an electrical protection device designed to detect abnormal conditions in medium-voltage power systems, typically operating at voltage levels between 1 kV and 52 kV, and to initiate circuit isolation through breaker tripping logic. These devices incorporate current transformers, voltage sensing elements, and microprocessor-based logic to execute overcurrent, differential, and distance protection functions that prevent equipment damage and service interruption. Digital device types now lead the product mix, as utilities prioritize relays with IEC 61850 protocol compliance and embedded disturbance recording for grid analytics. Feeder protection applications represent the fastest-growing segment, driven by distribution network expansion and the need for selective coordination in meshed renewable-heavy grids. Electromechanical relays retain residual share in emerging markets where capital constraints and technical familiarity sustain demand for proven analog architectures.
Grid codes issued by FERC in the United States and the EU Green Deal framework in Europe mandate enhanced fault-ride-through capabilities and faster clearing times that directly tighten protection relay performance specifications. India's CEA technical standards for substation automation and Germany's BNetzA requirements for distribution system operators both drive demand for digital relays with standardized communication interfaces. Stakeholders must monitor how evolving cybersecurity mandates for critical energy infrastructure reshape product certification pathways and vendor qualification criteria.
Market Dynamics
Grid modernization mandates are compressing replacement cycles for electromechanical protection hardware and forcing utilities to requalify procurement specifications around IEC 61850 protocol compliance.
Growth Catalysts
- FERC Order 2023:The US federal mandate for enhanced fault-ride-through capabilities tightens relay response-time specifications and accelerates digital platform upgrades across transmission utilities.
- Renewable integration stress:Distributed solar and wind penetration in meshed distribution networks creates selective coordination requirements that only microprocessor-based relays can satisfy.
- India:State transmission utilities under CEA technical standards are deploying advanced protection schemes to manage asynchronous renewable infeed at 33 kV and 66 kV substations.
Market Restraints
- Semiconductor supply concentration:Relay manufacturers depend on analog-to-digital converter chips sourced primarily from East Asian foundries, exposing delivery timelines to geopolitical friction.
- Copper and rare-earth magnet costs:Current transformer cores and trip coil assemblies face input price volatility that compresses margin on economy-tier electromechanical units.
- Legacy skill base:Utilities in emerging markets retain maintenance crews trained on electromechanical adjustment procedures, slowing digital platform acceptance despite superior performance.
Strategic Opportunities
- Sub-Saharan Africa:Greenfield rural electrification projects present first-mover advantage for vendors bundling protection relays with prepaid metering and SCADA infrastructure.
- Cybersecurity certification pathways:EU NIS2 Directive and US CISA critical infrastructure mandates create service revenue pools for vendors offering firmware update subscriptions and intrusion detection.
- Edge analytics convergence:Protection relays integrating PMU functionality with machine learning-based disturbance classification command premium positioning in European transmission upgrades.
Industry Challenges
- IEC 61850 interoperability testing:Multi-vendor substation automation projects require expensive third-party conformance certification that extends project timelines by four to six months.
- Legacy protocol integration:Digital relays must maintain DNP3 and Modbus backward compatibility with existing SCADA hierarchies, adding firmware complexity and validation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MV Protection Relay Market |
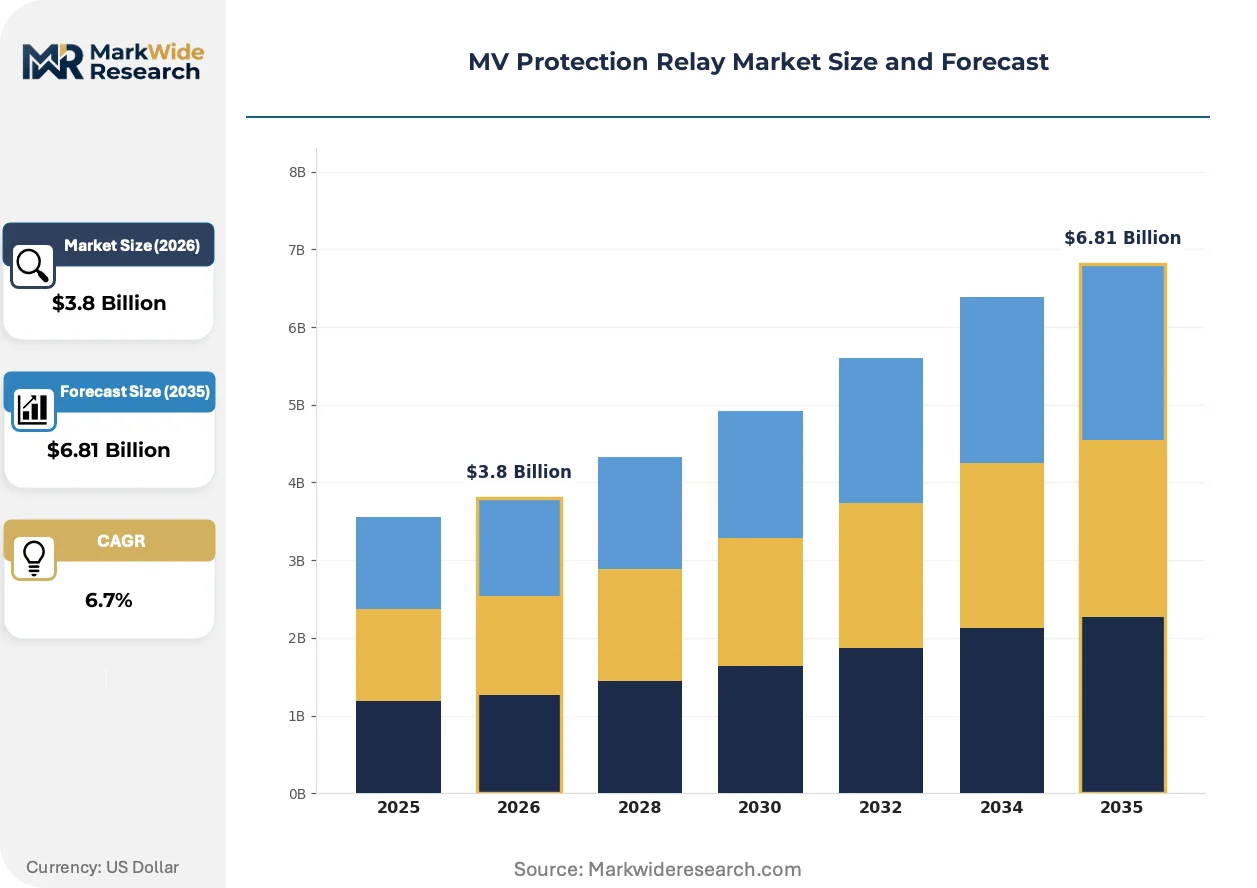
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Electromechanical, Digital, Hybrid, Static End User: Utilities, Industrial, Commercial, Renewable Energy Application: Substation Protection, Motor Protection, Transformer Protection, Feeder Protection Connectivity: Wired, Wireless, Serial Communication, Ethernet |
| Companies Covered | Schneider Electric, Siemens, ABB, General Electric, Eaton, Schweitzer Engineering Laboratories, Mitsubishi Electric Corporation, Rockwell Automation, Larsen & Toubro Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MV Protection Relay Market Strategic Shifts
Digital protection platforms are absorbing functions previously executed by standalone power quality analyzers and fault recorders, collapsing the traditional device hierarchy in substation architectures.
Adaptive protection algorithms are digitizing relay settings in real time based on network topology changes. Distribution utilities in Germany and Australia deploy these systems to manage bidirectional power flows from rooftop solar clusters. The technology is digitizing commissioning workflows by reducing manual coordination studies and enabling remote parameter adjustment.
The EU Green Deal framework mandates standardized communication interfaces for all new substation automation assets installed after 2027. This regulation compresses vendor proprietary protocol advantages and forces convergence on IEC 61850 Edition 2.1 implementations. European distribution system operators under BNetzA supervision are pre-qualifying only relays with embedded cybersecurity modules.
Asset-as-a-service contracting is displacing capital purchase models for protection hardware. Indian state transmission utilities and Southeast Asian independent power producers now lease relay functionality with bundled maintenance and firmware updates. This shift concentrates vendor relationships with balance-sheet-capable platform providers and marginalizes pure hardware suppliers in these procurement channels.
MV Protection Relay Market Segmentation
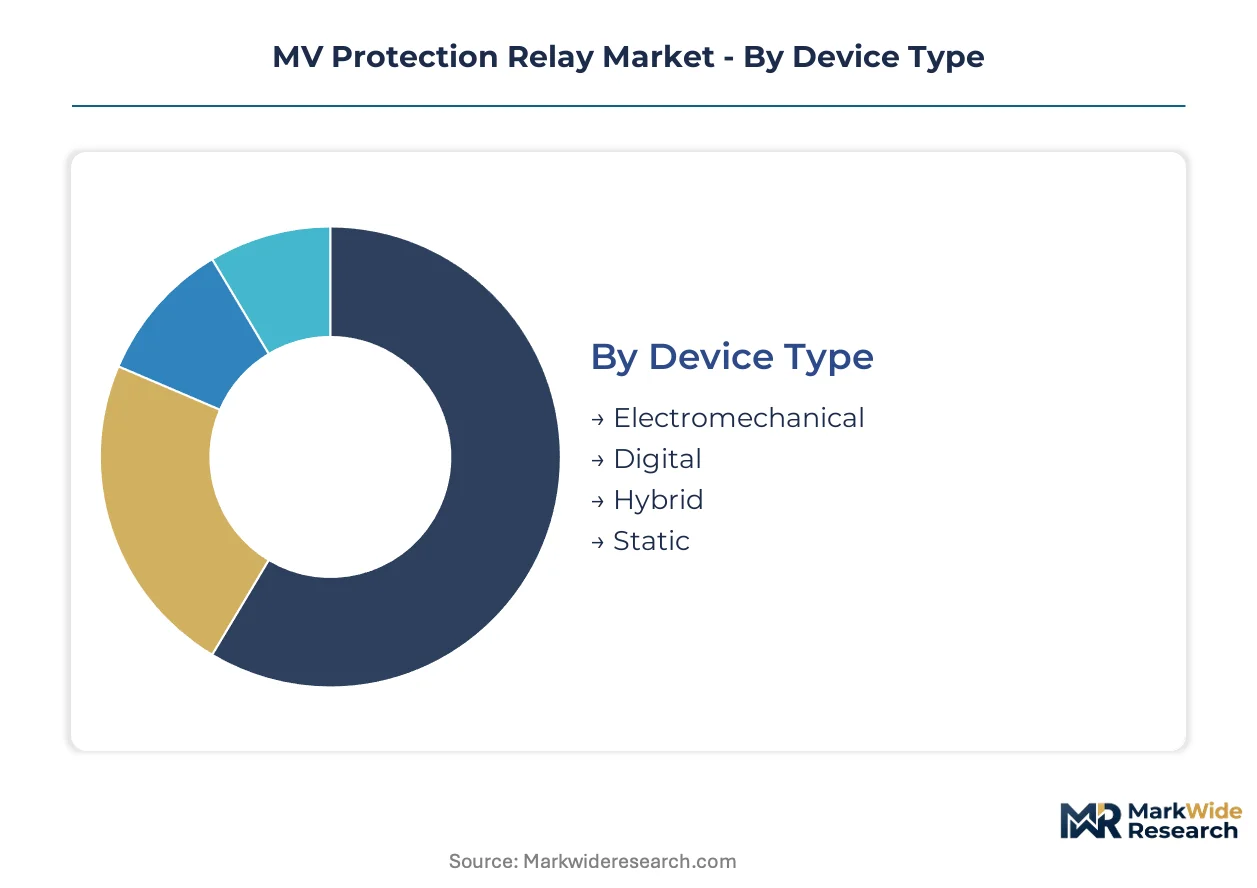
MV protection relay procurement varies sharply by segment, with digital platforms commanding premium service contracts while electromechanical units sustain residual demand through lower lifecycle costs. Understanding these segment boundaries clarifies where vendors must build calibration expertise versus where firmware subscriptions drive recurring revenue.
Device Type:
After-sales service intensity separates digital platforms from legacy hardware, with firmware-dependent relays requiring continuous vendor engagement through upgrade cycles.
- Digital:Microprocessor-based architectures execute overcurrent, differential, and distance protection through configurable logic. Indian state transmission utilities under CEA standards prioritize these units for 33 kV and 66 kV substations managing asynchronous renewable infeed. Firmware update subscriptions and cybersecurity certification create recurring revenue streams that alter vendor-customer relationships.
- Electromechanical:Analog induction-disk mechanisms rely on mechanical torque balance for fault detection without software dependencies. Utilities in emerging markets retain maintenance crews trained on mechanical adjustment procedures, sustaining demand despite digital performance advantages. Copper current transformer cores and trip coil assemblies face input price volatility that compresses margins.
- Hybrid:Combines electromechanical output reliability with electronic sensing elements for intermediate functionality.
- Static:Solid-state analog circuits without microprocessors serve niche applications requiring deterministic response times.
Digital holds the largest share; momentum sits with hybrid configurations bridging legacy skill bases toward full digitization.
End User:
Capital commitment scale distinguishes procurement patterns, with utilities underwriting decade-long service contracts while industrial buyers prioritize capital efficiency.
- Utilities:Electric transmission and distribution operators deploy relays across meshed networks where selective coordination prevents cascading failures. FERC Order 2023 mandates enhanced fault-ride-through capabilities that tighten response-time specifications and accelerate platform upgrades. Asset-as-a-service contracting is displacing capital purchase models in India and Southeast Asia.
- Industrial:Manufacturing and process facilities protect motor drives and transformer assets against arc flash and thermal damage. These buyers prioritize capital efficiency over embedded analytics, often selecting economy-tier units with basic Modbus connectivity.
- Commercial:Data centers and large facility operators specify relays with power quality monitoring integration.
- Renewable Energy:Solar and wind farm developers require adaptive protection algorithms for bidirectional power flow management.
Utilities dominate volume; renewable energy developers are expanding most quickly as grid codes tighten distributed generation interconnection standards.
Application:
Technical complexity gradients determine where algorithmic premiums command pricing power versus where commodity specifications prevail.
- Feeder Protection:Distribution circuit applications require selective coordination in meshed renewable-heavy grids where fault current direction varies with generation availability. German and Australian utilities deploy adaptive algorithms that digitize relay settings in real time based on network topology changes. The technology collapses commissioning timelines by reducing manual coordination studies.
- Transformer Protection:Differential and restricted earth fault schemes protect high-value assets where fault discrimination algorithms command technical premiums. ABB specializes in this segment where harmonic restraint and inrush detection differentiate vendor capability.
- Substation Protection:Busbar and breaker failure schemes integrate with IEC 61850 process bus architectures.
- Motor Protection:Thermal overload and stall protection for medium-voltage motor drives in industrial processes.
Transformer protection commands the highest unit margins; feeder applications are gaining share fastest through distribution network expansion.
Connectivity:
Protocol standardization pressure reshapes competitive positioning, with IEC 61850 compliance becoming table stakes for transmission-grade procurement.
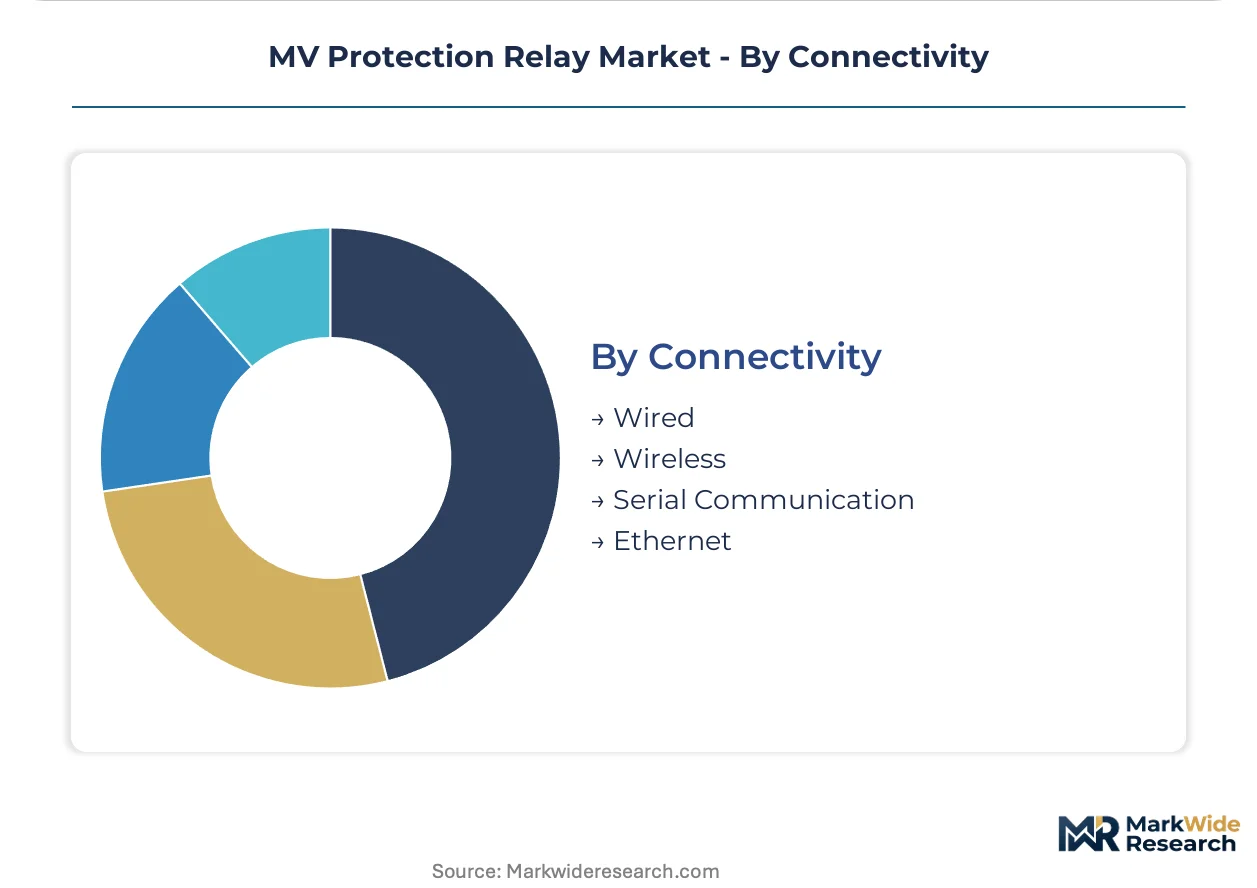
- Ethernet:High-bandwidth IEC 61850 implementations enable sampled value streaming and peer-to-peer GOOSE messaging between protection devices. EU Green Deal framework mandates standardized communication interfaces for substation automation assets, compressing proprietary protocol advantages. European distribution system operators under BNetzA supervision pre-qualify only relays with embedded cybersecurity modules.
- Wireless:Cellular and mesh radio configurations serve remote feeder applications where fiber deployment is uneconomical. Sub-Saharan African rural electrification projects bundle wireless-enabled relays with prepaid metering and SCADA infrastructure.
- Wired:Copper-based serial and parallel interfaces persist in retrofit applications.
- Serial Communication:RS-485 and fiber-optic Modbus maintain backward compatibility with legacy SCADA hierarchies.
Ethernet dominates new-build specifications; wireless is climbing the fastest as last-mile distribution automation accelerates in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in MV protection relays favor manufacturing hubs with integrated semiconductor supply chains. Germany and China maintain trade surpluses in digital relay platforms. India and Brazil remain net importers, dependent on European and East Asian suppliers for IEC 61850-compliant hardware.
United States
FERC Order 2023 mandates enhanced fault-ride-through capabilities across transmission utilities. The Federal Energy Regulatory Commission tightens relay response-time specifications and accelerates digital platform upgrades. Texas and California utilities deploy adaptive protection algorithms for renewable-heavy distribution networks.
Germany
BNetzA supervision drives pre-qualification of relays with embedded cybersecurity modules for distribution system operators. The EU Green Deal framework mandates standardized communication interfaces for substation automation assets after 2027. Bavarian and North Rhine-Westphalia utilities lead European adoption of IEC 61850 Edition 2.1 implementations.
India
State transmission utilities under CEA technical standards deploy advanced protection schemes for 33 kV and 66 kV substations managing asynchronous renewable infeed. The Central Electricity Authority mandates IEC 61850 compliance for new substation automation projects. Maharashtra and Gujarat transmission networks concentrate procurement of digital feeder protection systems.
China
Grid modernization investments prioritize domestic relay manufacturing for ultra-high voltage transmission corridors. MIIT industrial policy supports local production of microprocessor-based protection platforms. Yangtze River Delta and Pearl River Delta clusters supply both domestic utilities and Belt and Road infrastructure projects.
Brazil
Rural electrification programs create demand for wireless-enabled protection relays in remote distribution feeders. ANEEL regulatory frameworks require selective coordination standards for distributed generation interconnection. São Paulo and Minas Gerais utilities upgrade substation protection to accommodate bi-directional power flows from solar clusters.
MV Protection Relay Market Competitive Environment
On the supply side, the industry is consolidating around integrated digital energy platforms with embedded software ecosystems. Relay manufacturing requires deep competence in analog-to-digital conversion, real-time operating systems, and cybersecurity certification. Two strategic archetypes dominate: diversified industrial conglomerates bundling protection hardware with asset management software, and specialized protection technology firms competing on algorithmic differentiation. Capacity expansion in IEC-rated manufacturing and strategic partnerships for firmware subscription services represent the dominant competitive vectors.
Within the diversified industrial tier, Schneider Electric, Siemens, and ABB occupy anchor positions. Schneider Electric leverages its integrated digital energy platform to bundle protection relays with software ecosystems. Siemens anchors its position through manufacturing scale in IEC-rated protection hardware. ABB competes by specializing in transformer protection applications where technical premiums attach to fault discrimination algorithms.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| General Electric |
| Eaton |
| Schweitzer Engineering Laboratories |
| Mitsubishi Electric Corporation |
| Rockwell Automation |
| Larsen & Toubro Limited |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing clusters anchor global digital relay production capacity, concentrating firmware development expertise and analog-to-digital converter sourcing that downstream utilities leverage for procurement leverage. This geographic concentration creates asymmetric pricing power where East Asian foundry capacity constraints transmit directly into relay delivery premiums and extended lead-time penalties.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on IEC 61850 certification grade and embedded cybersecurity module inclusion, with transmission-grade units commanding substantial premiums over distribution-tier hardware. Cost compression in economy-tier electromechanical units is intensifying because copper current transformer core volatility compresses margins. Utilities under long-term service contracts exhibit lowest price sensitivity, while emerging market rural electrification projects face acute budget constraints.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from tier-one vendors have become critical liquidity tools for mid-tier relay assemblers managing working capital cycles. Semiconductor inputs draw from Taiwan, South Korea, and Japan, while copper and rare-earth magnet sourcing centers on China and Australia. Single-source vulnerability in analog-to-digital converter chips exposes delivery timelines to geopolitical friction. Distribution runs through authorized electrical distributors and direct utility procurement channels with embedded firmware subscription bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
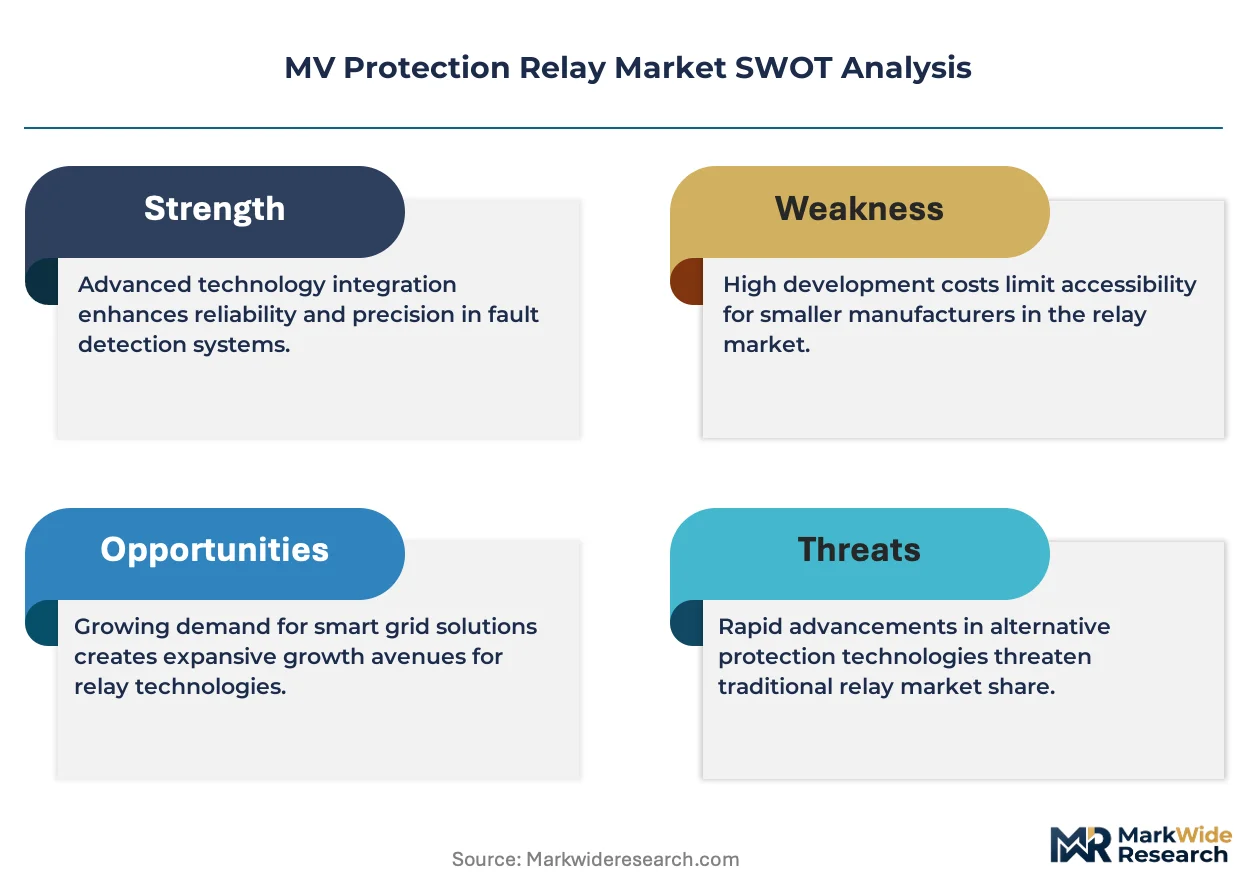
Digital protection platforms face substitution pressure from integrated edge-computing nodes that collapse relay, PMU, and power quality analyzer functions into unified hardware. Incumbents must navigate this functional convergence threat while defending installed base relationships.
For Market Incumbents: Entrench through backward integration into semiconductor sourcing partnerships that secure analog-to-digital converter allocation priority during supply crunches. Deepen firmware subscription attach rates to transform transactional hardware sales into recurring revenue streams that lock out substitute platform providers.
For New Entrants and Emerging Players: Sub-Saharan African rural electrification projects with bundled SCADA and prepaid metering requirements represent the most penetrable entry point for platform-agnostic relay vendors. Wireless-enabled feeder protection for last-mile distribution automation offers a second white-space target with reduced incumbent saturation. A hardware-as-a-service go-to-market angle bypasses capital-constrained utility procurement committees.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because vendor relationships concentrate with balance-sheet-capable platform providers capable of underwriting decade-long service contracts. Acquisition targets should display IEC 61850 Edition 2.1 certification readiness and embedded cybersecurity module development. The signal to watch is EU NIS2 Directive enforcement tightening vendor qualification criteria and accelerating mid-tier exit pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Secures analog-to-digital converter allocation priority from Taiwan and South Korean foundries during supply crunches. |
| IEC 61850 Edition 2.1 Certification Investment | Qualifies hardware for EU Green Deal mandated substation automation deployments after 2027. |
| Firmware Subscription Service Launch | Transforms capital equipment sales into recurring revenue under asset-as-a-service utility procurement models. |
| Embedded Cybersecurity Module Development | Meets BNetzA pre-qualification requirements for European distribution system operator contracts. |
| Wireless-Enabled Relay Platform Expansion | Captures Sub-Saharan African rural electrification projects bundling protection with SCADA infrastructure. |
Study Parameters
Operator-level perspectives from utility protection engineers, substation automation architects, EPC procurement managers, and relay firmware developers anchored the qualitative base. Primary interviews triangulated against secondary validation from FERC filings, CEA technical standards documentation, EU Green Deal regulatory texts, and IEC 61850 conformance testing records. Bottom-up demand modeling across device type, end user, application, and connectivity segments converged with top-down macroeconomic calibration.
Scenario-bracketing framed low, base, and high cases across renewable penetration rates, semiconductor supply normalization, and grid code enforcement intensity over the projection horizon. Segmentation dimensions modeled include device architecture, voltage class, communication protocol, and regional regulatory framework. CAGRs derived from unit shipment trajectories and average selling price evolution analysis, with specific inputs from utility capital expenditure cycles and greenfield substation project pipelines.
Stress conditions across copper price volatility, East Asian foundry capacity utilization, and EU cybersecurity certification timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding grid modernization mandate continuity and IEC 61850 adoption curves. Macroeconomic contraction, regulatory enforcement deviation, or breakthrough solid-state protection technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
US Air Filter Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
AC Residential Switchgear Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Global Hazardous Location Motor Starters Market
Electrical Power Equipment
India Gas Insulated Switchgear Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Magnet Bearings Market