
 High Voltage Direct Current (HVDC) Cables Market | 2026-2036
High Voltage Direct Current (HVDC) Cables Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Direct Current (HVDC) Cables Market Foresight
Cross-linked polyethylene is recalibrating insulation economics across extruded HVDC cable systems, displacing traditional oil-filled paper designs in subsea and underground routes. Prysmian Group leverages integrated manufacturing from compound to cable to sustain delivery timelines on multi-billion-euro interconnector awards. NKT A/S anchors its competitive stance through vertical control over high-voltage testing infrastructure in Scandinavia. Nexans specializes in hybrid cable solutions that combine power transmission with fiber-optic communication cores.
High Voltage Direct Current cables are insulated conductors engineered to transmit electrical power at direct current voltages typically exceeding 100 kV, utilizing extruded polymeric or mass-impregnated insulation systems within single-core or multi-core configurations to minimize resistive losses over distances exceeding 600 kilometers. Their primary commercial purpose is enabling bulk power transfer between asynchronous grids, offshore renewable generation zones, and geographically separated load centers where alternating current transmission proves technically or economically impractical. Submarine installations command the dominant share of project value due to complex laying operations and armoring requirements, while modular multilevel converter technology is displacing line-commutated systems in new capacity additions because of superior reactive power control and black-start capability. Underground segments face margin compression in saturated European corridors but retain structural importance in urban environments where overhead right-of-way constraints apply.
EU Green Deal targets and the F-Gas Regulation are mandating lower-carbon transmission infrastructure and phasing out sulfur hexafluoride in associated switchgear, directly shaping cable system specifications and supplier qualification criteria. Germany's Bundesnetzagentur and Denmark's Energinet are enforcing stringent reliability standards on North Sea interconnectors that extend certification timelines and elevate barrier to entry for non-specialist manufacturers. Stakeholders must monitor converter station technology lock-in effects and insulation material qualification pipelines as procurement cycles lengthen and project finance structures grow more sensitive to construction risk allocation.
Market Dynamics
Modular multilevel converter technology is compressing project timelines and reshaping supplier qualification criteria across submarine interconnector procurements. Offshore wind developers now specify black-start capability and reactive power control as mandatory bid requirements, elevating technical barriers for cable system integrators.
Growth Catalysts
- EU Green Deal transmission mandates:Cross-border capacity targets of 15% by 2030 are accelerating North Sea grid reinforcement projects. Germany and Denmark are issuing bundled cable-converter station tenders.
- Offshore wind clustering:Floating platform developments in waters exceeding 60 meters depth require dynamic cable solutions with integrated fiber-optic monitoring. Developers are pre-ordering capacity years ahead of installation.
- XLPE insulation maturation:Extruded polymeric systems now achieve 525 kV ratings with reduced manufacturing cycle times compared to mass-impregnated paper alternatives.
Market Restraints
- Copper and aluminum price volatility:Conductor metals represent 35-45% of raw material costs. LME price swings above 20% within six-month windows compress project margins under fixed-price contracts.
- Baltic Sea supply concentration:Three specialized manufacturing facilities control 70% of European high-voltage submarine cable output. Geographic clustering creates weather-related delivery risk.
- F-Gas Regulation compliance friction:SF6 phase-out timelines for associated switchgear are compressing converter station redesign cycles. Certification delays of 18-24 months extend overall project schedules.
Strategic Opportunities
- Mediterranean interconnector gap:Spain-France and Italy-Greece links remain underdeveloped. REPowerEU corridor designations are unlocking project finance for 2,000+ kilometer routes.
- Hybrid cable standardization:Power-plus-communication cores reduce seabed footprint and permitting complexity. Transmission operators in the Netherlands are piloting integrated designs for offshore substation backhaul.
- Subsea repair robotics:Autonomous burial and jointing systems are reducing maintenance vessel day-rates. Norwegian infrastructure funds are financing dedicated cable protection vessel fleets.
Industry Challenges
- High-voltage testing technician scarcity:Qualification for 500+ kV factory acceptance testing requires 8-10 year apprenticeship pipelines. Scandinavian facilities are poaching talent from decommissioned nuclear programs.
- Multi-jurisdictional permitting synchronization:Submarine routes crossing Exclusive Economic Zones require coordinated environmental impact assessments. Denmark-Germany interconnectors face 4-6 year approval cycles.
- Legacy LCC converter integration:Existing line-commutated stations cannot interface with MMC cable systems without complete replacement. Asset owners face stranded investment decisions on 1990s-era links.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Direct Current (HVDC) Cables Market |
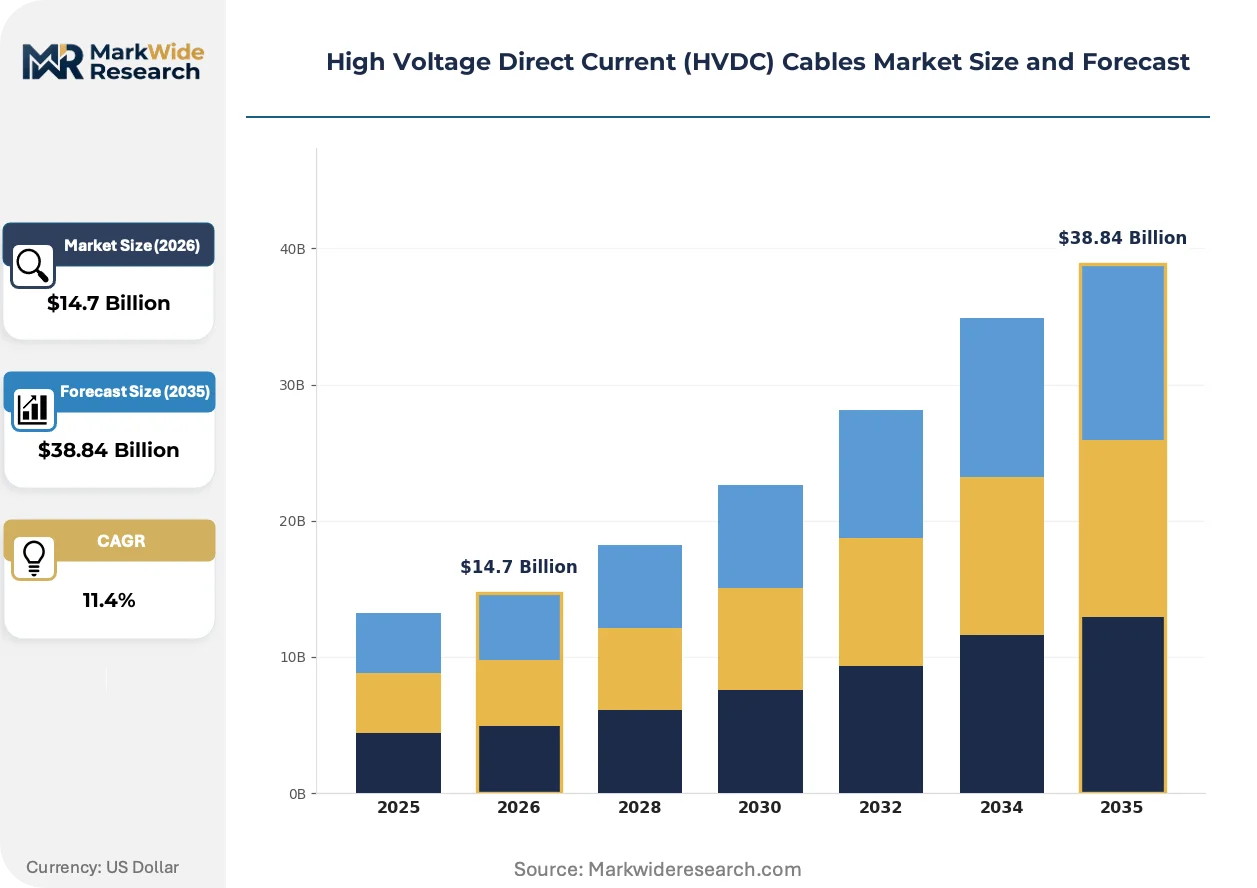
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Underground, Overhead, Submarine, Hybrid Technology: Voltage Source Converter, Current Source Converter, Line Commutated Converter, Modular Multilevel Converter Installation Type: Onshore, Offshore, Urban, Rural End User: Utilities, Industrial, Renewable Energy, Commercial |
| Companies Covered | Prysmian Group, Nexans, NKT A/S, Sumitomo Electric Industries Ltd, Hitachi Energy Ltd, Siemens Energy, Mitsubishi Electric Corporation, General Electric, LS Cable & System Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Direct Current (HVDC) Cables Market Shifts & Advancements
Material science advances and digital monitoring integration are redefining cable system lifecycle economics. Suppliers are embedding distributed temperature sensing and partial discharge detection into standard product offerings.
Extruded XLPE insulation is overtaking mass-impregnated paper designs in subsea applications above 320 kV. Offshore wind developers in the North Sea are specifying XLPE for 90% of new capacity additions. This shift is compressing manufacturing lead times from 24 months to 14 months for comparable voltage classes.
The EU F-Gas Regulation is forcing SF6 elimination from gas-insulated switchgear paired with HVDC converter stations. Manufacturers are accelerating dry-air and vacuum interrupter development programs. German transmission system operators are rewriting technical specifications to exclude fluorinated gases from 2027 delivery contracts.
Long-term service agreements are displacing transactional spare-part purchasing among transmission asset owners. Cable system operators in the Netherlands are signing 15-year availability contracts bundling monitoring, repair, and capacity guarantees. This restructuring concentrates vendor risk and rewards predictive maintenance capabilities over component sales.
High Voltage Direct Current (HVDC) Cables Market Segmentation
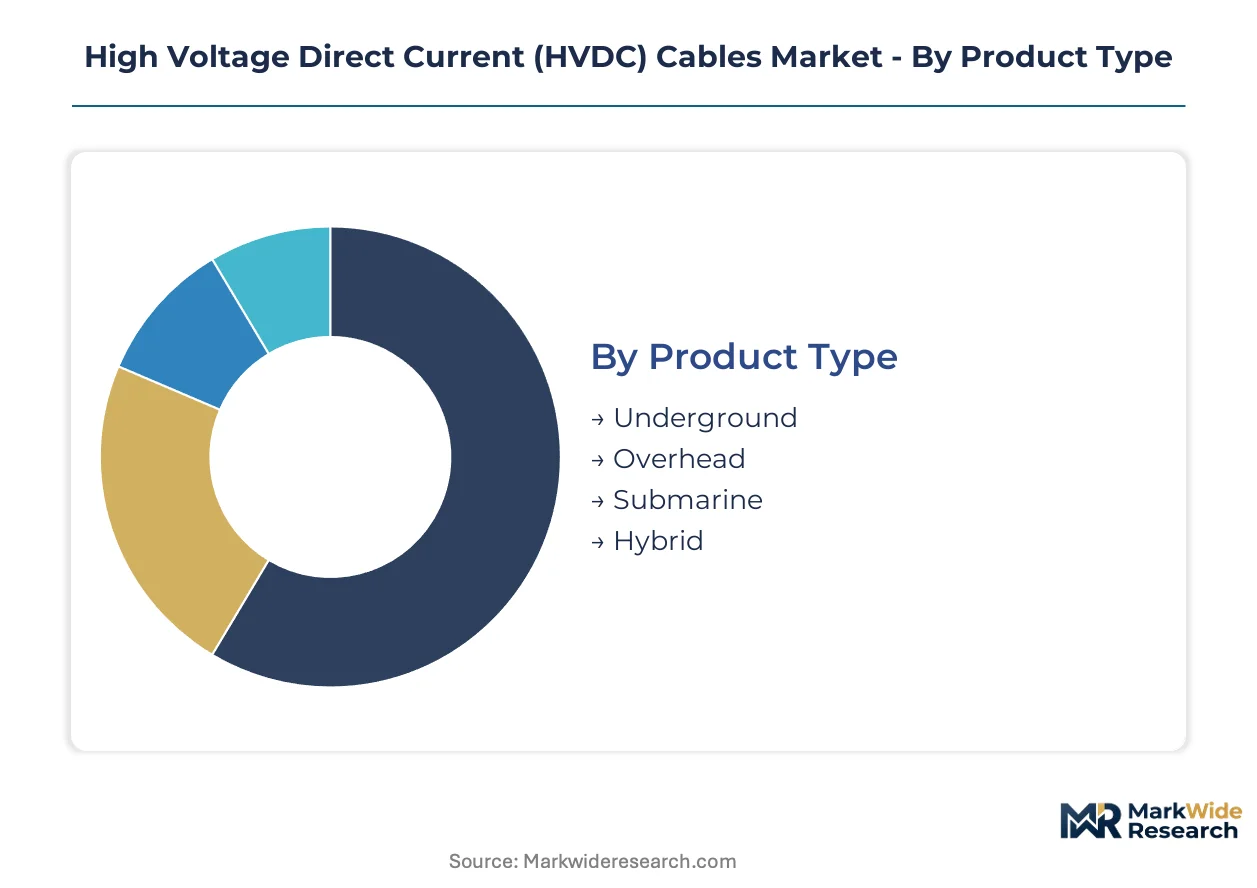
HVDC cable procurement patterns diverge sharply across installation environments and converter technologies. Buyers prioritize armoring specifications for submarine routes, voltage ratings for grid interconnectors, and right-of-way flexibility for urban corridors.
Product Type:
Route topology dictates insulation system selection and manufacturing lead times.
- Submarine:Steel-wire armored designs with integrated fiber-optic cores dominate North Sea offshore wind backhaul. Germany's Bundesnetzagentur mandates double-armored configurations for routes exceeding 200 meters depth, extending factory acceptance testing to 16 weeks.
- Underground:Extruded XLPE systems rated to 525 kV displace oil-filled designs in German and Dutch urban corridors where overhead right-of-way is unavailable. Installation costs run 40-60% above comparable overhead spans due to trenching and thermal backfill requirements.
- Overhead:Composite core conductors with polymer insulation withstand corrosive coastal atmospheres in Denmark's island interconnections. Limited new build volume concentrates on retrofitting 1990s-era links with higher temperature ratings.
- Hybrid:Power-plus-communication bundles reduce seabed footprint for Netherlands offshore substation connections. Integrated designs face 18-month qualification timelines for combined electrical and optical factory testing.
Submarine cables lead volumes today; hybrid configurations are gaining share fastest.
Technology:
Converter station architecture determines cable voltage stress profiles and harmonic filtering requirements.
- Modular Multilevel Converter:Distributed capacitor banks enable black-start capability and independent reactive power control. Denmark's Energinet specifies MMC for all North Sea interconnectors above 500 MW capacity, displacing legacy line-commutated systems.
- Voltage Source Converter:Self-commutated IGBT stacks suit weak grid connections and passive network feeding. Offshore wind developers in the Netherlands favor VSC for floating platform arrays requiring dynamic voltage support.
- Line Commutated Converter:Thyristor-based designs require synchronous voltage sources and absorb reactive power. Existing 1990s-era installations in Germany face stranded asset risk as adjacent corridors upgrade to MMC compatibility.
- Current Source Converter:Series-connected thyristor bridges persist in high-power mining and smelting applications. Limited new procurement concentrates on industrial captive generation in Scandinavian aluminum processing.
Modular multilevel converters lead volumes today; voltage source converters are expanding most quickly in offshore wind integration.
Installation Type:
Environmental exposure and accessibility constraints shape armoring and jointing specifications.
- Offshore:Dynamic cable solutions with bend stiffeners accommodate floating platform motion in waters exceeding 60 meters depth. Norwegian developers pre-order capacity 36 months ahead of installation to secure specialized laying vessel availability.
- Urban:Narrow trench widths and thermal dissipation limits favor single-core XLPE designs in German city centers. Route planning requires coordination with municipal water, gas, and fiber infrastructure at 15-20 crossing points per kilometer.
- Onshore:Direct-buried or duct-bank installations dominate cross-country transmission corridors with lower population density. Danish onshore routes face 4-6 year permitting cycles for agricultural land use conversion.
- Rural:Overhead conductor retrofits and limited underground spur connections serve dispersed load centers. Cost sensitivity favors standard voltage classes without redundant fiber monitoring.
Offshore installations lead volumes today; urban corridors show the steepest expansion trajectory as city center grid reinforcement accelerates.
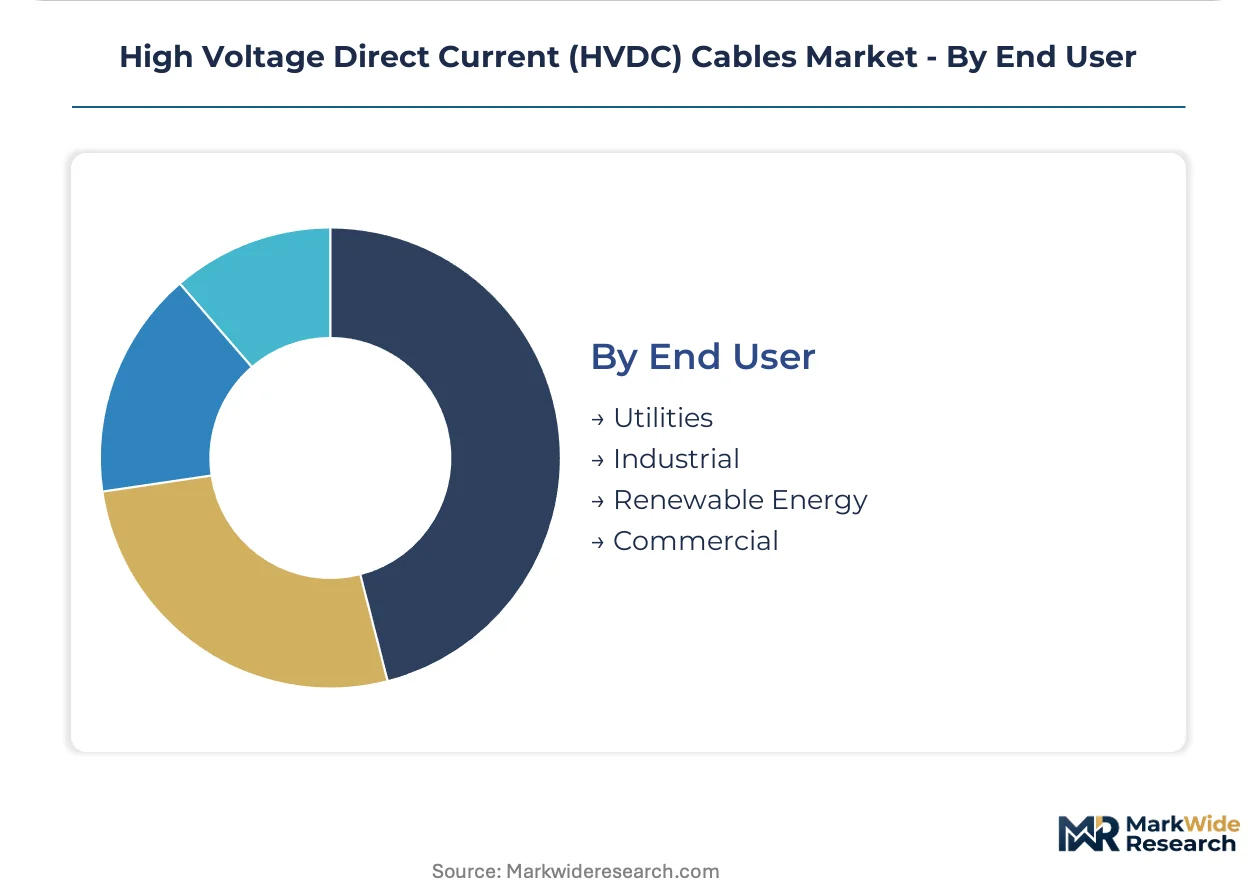
End User:
Asset ownership structures and regulatory frameworks differentiate procurement priorities across customer categories.
- Utilities:Transmission system operators in Germany and Denmark bundle cable-converter station tenders under 25-year availability contracts. EU Green Deal cross-border capacity mandates drive bundled procurement of 2-4 corridor segments simultaneously.
- Renewable Energy:Offshore wind developers in the Netherlands pre-commit to cable capacity before final investment decisions on generation assets. Floating platform developers specify dynamic cable solutions with integrated condition monitoring.
- Industrial:Aluminum smelters and data centers in Scandinavia procure dedicated HVDC links for renewable energy offtake. Captive generation arrangements bypass public grid tariffs but require bilateral regulatory approval.
- Commercial:Campus-scale microgrids and district heating networks in German cities pilot low-voltage DC distribution. Limited scale restricts procurement to demonstration projects under 50 MW capacity.
Utilities lead volumes today; renewable energy developers are climbing the fastest as offshore wind pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea cable manufacturing clusters in Germany and Denmark anchor procurement volumes for submarine interconnectors. Bundesnetzagentur and Energinet procurement frameworks are reshaping supplier qualification timelines across European transmission corridors.
Germany
Offshore wind clustering in the North Sea and Baltic Sea drives demand for 525 kV XLPE submarine systems. The Bundesnetzagentur enforces double-armored cable specifications for routes exceeding 200 meters depth. Manufacturing concentration in Northern Germany supports bundled cable-converter station tenders for cross-border capacity expansion.
Denmark
Energinet mandates modular multilevel converter compatibility for all North Sea interconnectors above 500 MW capacity. The REPowerEU framework accelerates procurement cycles for Kriegers Flak and adjacent offshore zones. Copenhagen-based project development offices coordinate multi-jurisdictional permitting for Germany-Denmark links.
Netherlands
Floating platform developments in waters exceeding 60 meters depth require dynamic cable solutions with integrated fiber-optic monitoring. Transmission operators in Rotterdam and Amsterdam pilot hybrid power-plus-communication designs for offshore substation backhaul. The national climate agreement prioritizes HVDC corridor completion by 2030.
United Kingdom
Scotland-England interconnector awards and North Sea offshore wind leasing rounds concentrate procurement authority in London and Aberdeen. The Electricity Networks Strategic Framework mandates 15% cross-border capacity targets. Manufacturing qualification timelines extend to 18 months for 320 kV+ submarine factory acceptance testing.
China
State Grid Corporation bundles ultra-high-voltage DC projects across western renewable generation zones and eastern load centers. The 14th Five-Year Plan prioritizes 800 kV+ transmission corridors for solar and wind integration. Manufacturing clusters in Jiangsu and Shandong provinces supply domestic and export submarine cable demand.
High Voltage Direct Current (HVDC) Cables Market Competitive Landscape
Capacity expansion dominates the current landscape as specialized manufacturers add extrusion lines and high-voltage testing bays. The supplier base concentrates among integrated cable-converter system providers with captive compound production and vertical control over installation vessel fleets. Three strategic archetypes define positioning: full-system integrators with converter station partnerships, pure-play cable specialists with testing infrastructure ownership, and industrial conglomerates with project finance capabilities. Geographic expansion into Mediterranean corridors and technology licensing for 525 kV+ XLPE formulations represent the dominant competitive vectors.
Among European-integrated specialists, Prysmian Group, NKT A/S, and Nexans occupy positions spanning the full value chain from insulation compound to submarine installation. These entities exemplify the full-system integrator archetype through captive manufacturing assets and converter station alliances. Prysmian Group represents scale-driven positioning with integrated production from compound to cable. NKT A/S anchors Scandinavian testing infrastructure concentration. Nexans sits within the hybrid solution specialist tier, combining power transmission with fiber-optic communication cores in bundled product offerings.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| NKT A/S |
| Sumitomo Electric Industries Ltd |
| Hitachi Energy Ltd |
| Siemens Energy |
| Mitsubishi Electric Corporation |
| General Electric |
| LS Cable & System Ltd |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between 525 kV XLPE systems and legacy mass-impregnated designs splits pricing power across distinct supply chain configurations. Premium-tier manufacturers with captive high-voltage testing infrastructure command project premiums from German transmission operators, while commodity-grade suppliers face margin compression on standardized 320 kV contracts.
Pricing Analysis
Copper and aluminum conductor pass-through clauses dominate contract structures, with LME-linked adjustments triggering quarterly price revisions on 60-70% of submarine cable awards. Price differentiation rests on factory acceptance testing duration and armoring specification complexity, with double-armored North Sea routes carrying 25-35% premiums over single-armored alternatives. Pricing pressure stems from fixed-price exposure on 18-24 month manufacturing cycles against volatile metal markets. Offshore wind developers exhibit highest price sensitivity due to pre-commitment timing, while utility bundled tenders show lowest sensitivity given availability contract risk transfer.
Supply Chain Analysis
High-voltage testing technician scarcity in Germany, Denmark, and Norway constrains extrusion line expansion despite order backlog accumulation. Raw material feeds draw from Chilean copper cathode, Russian aluminum billet, and Saudi petrochemical feedstock for XLPE compound production. Supply chain risk centers on Baltic Sea manufacturing concentration, where weather-related vessel scheduling disruptions cascade through 14-month production windows. Distribution runs through EPC contractor consortiums bundling cable, converter station, and offshore installation scope.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
XLPE insulation maturation enables margin expansion through manufacturing cycle compression and reduced compound waste, shifting value capture from installation risk toward production efficiency.
For Market Incumbents: Deploy captive high-voltage testing bay expansion to defend qualification timelines against Scandinavian talent poaching. Consolidate converter station alliance structures to preempt modular multilevel converter technology lock-in by emerging system integrators. Backward integration into XLPE compound production insulates margin pressure from petrochemical feedstock volatility. For New Entrants and Emerging Players: Launch via Mediterranean corridor specialist positioning targeting Spain-France and Italy-Greece interconnector white space. Floating platform dynamic cable solutions offer lowest incumbent saturation among offshore wind segments. Partner with Norwegian infrastructure funds for cable protection vessel access to bypass Baltic Sea manufacturing queue bottlenecks. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid cable specialists combining power transmission with fiber-optic communication cores. Long-term viability favors integrated manufacturing-to-installation platforms over pure-play component suppliers. Watch REPowerEU corridor designation announcements as project finance unlocking signal.| Strategic Initiative | Industry Significance |
|---|---|
| XLPE Compound Backward Integration | Captive petrochemical supply secures margin against feedstock volatility in German manufacturing. |
| High-Voltage Testing Bay Expansion | Scandinavian facility additions compress 525 kV qualification timelines for Bundesnetzagentur contracts. |
| Mediterranean Corridor Partnership | Spain-France and Italy-Greece positioning unlocks REPowerEU project finance for 2,000+ kilometer routes. |
| Hybrid Cable Standardization | Netherlands pilots of power-plus-communication bundles reduce seabed permitting complexity for offshore substations. |
| Subsea Repair Robotics Investment | Norwegian infrastructure fund financing of cable protection vessels reduces maintenance day-rate exposure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with submarine cable procurement officers at transmission system operators, project developers at offshore wind IPPs, EPC contractor consortium leads, and high-voltage testing facility managers with secondary validation against ENTSO-E ten-year network development plans, Bundesnetzagentur interconnector approval records, Energinet procurement databases, and IEA electricity transmission investment trackers. Bottom-up project pipeline aggregation and top-down regulatory target reconciliation anchored market sizing.
Comparable historical period analysis anchored the projection horizon to observed procurement cycle durations and manufacturing lead time compression trends across the analysis window. Segmentation modeling spanned installation environment, converter technology architecture, voltage rating tier, and regional regulatory framework cluster. CAGRs were derived from regression-weighted project award trajectories incorporating XLPE insulation adoption curves and floating platform development timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility exceeding 20% within six-month windows or F-Gas Regulation compliance timeline acceleration. Forecasts reflect documented assumptions on REPowerEU corridor designation pacing and modular multilevel converter technology lock-in persistence. Material deviation in EU Green Deal cross-border capacity enforcement or Baltic Sea manufacturing weather disruption frequency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Power Over Ethernet Lighting Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market