
 High Voltage Oil Insulated Switchgear Market | 2026-2036
High Voltage Oil Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Oil Insulated Switchgear Market Insights
Asian transformer manufacturers is rebalancing capacity toward higher-voltage classes as transmission investment accelerates across developing economies. Siemens leverages its European engineering base to anchor premium bulk-oil switchgear contracts in mature grids. ABB competes through integrated digital monitoring packages that extend equipment lifecycle value for utilities.
High voltage oil insulated switchgear comprises enclosed assemblies rated above 72.5 kV that use mineral or ester oil as both electrical insulation and arc-quenching medium, manufactured through precision tank welding, vacuum oil filling, and high-voltage testing protocols to ensure dielectric integrity under fault conditions. Circuit breakers dominate product-type revenue due to their critical protective function in transmission networks, while ester oil variants represent the fastest-growing technology segment as biodegradable insulation fluids gain regulatory preference in environmentally sensitive installations. Transmission projects command the largest application share because national grid interconnections require bulk-oil breakers at voltage classes that gas-insulated alternatives have not yet displaced economically.
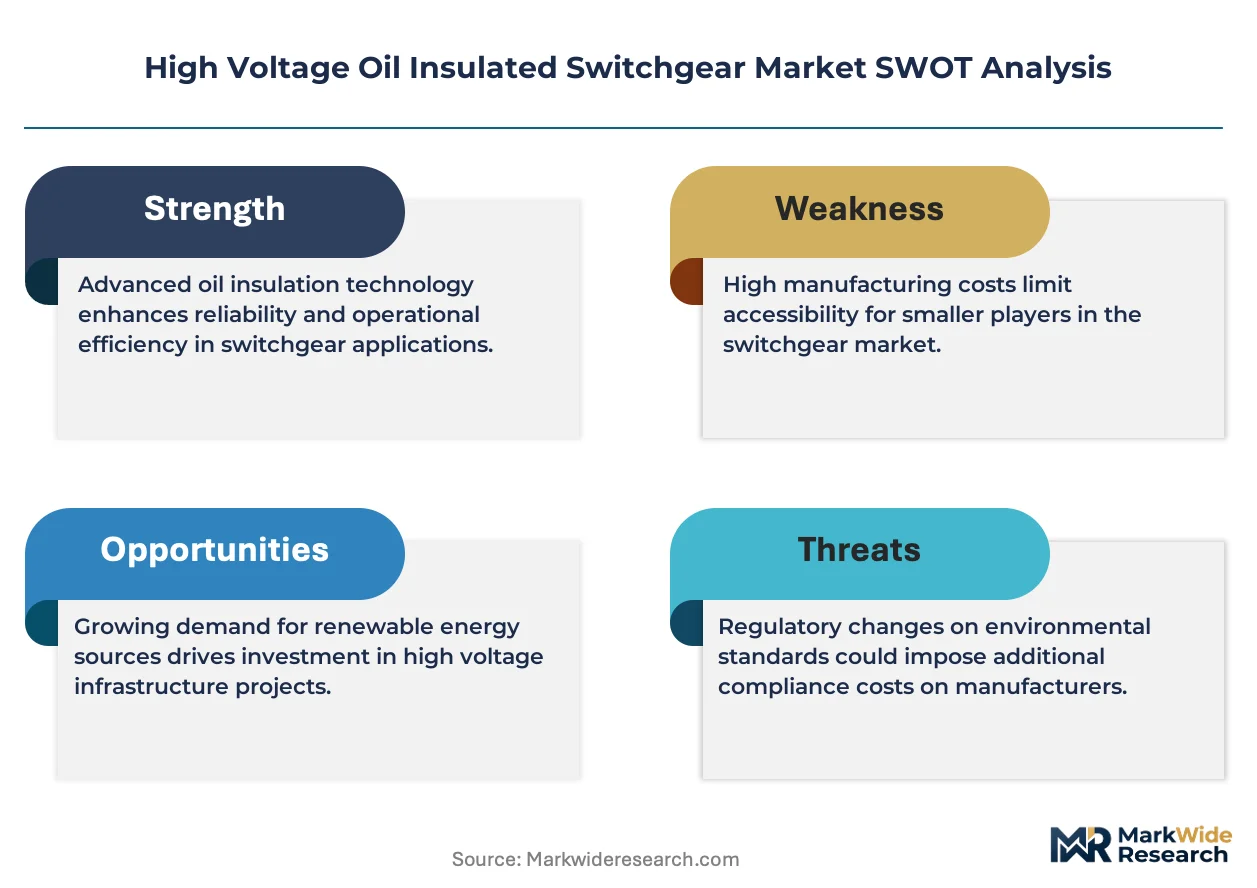
IEC 62271 and IEEE C37 series standards govern dielectric withstand, short-circuit ratings, and seismic performance, compelling manufacturers to maintain dual-certification testing facilities for market access across regulatory zones. The EU F-Gas Regulation indirectly steers investment toward oil-insulated alternatives where SF6 phase-out timelines accelerate utility procurement decisions. Stakeholders must monitor ester oil supply chain maturation and evolving carbon-border adjustments that could restructure competitive cost positions between mineral-oil incumbents and synthetic-fluid challengers.
Market Dynamics
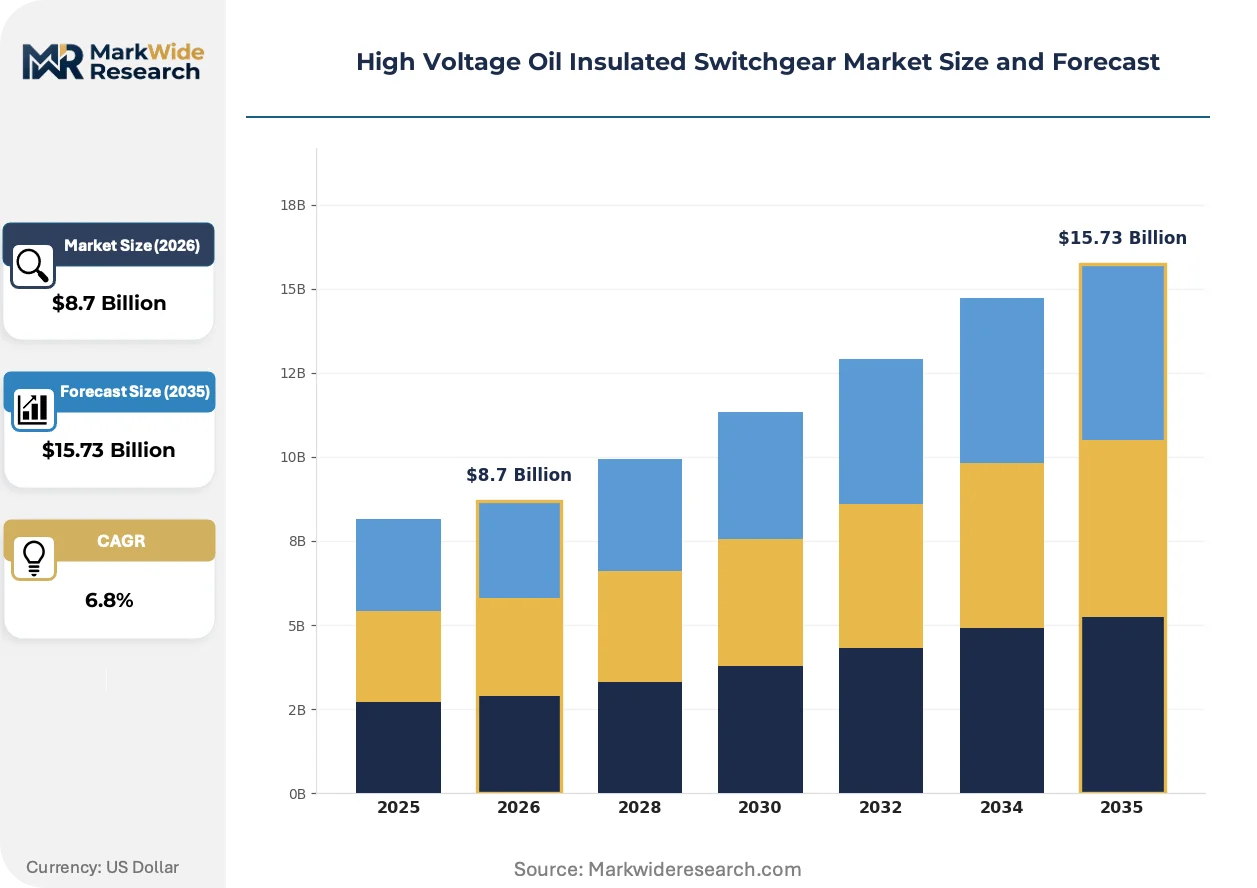
The High Voltage Oil Insulated Switchgear Market is being fundamentally restructured by the EU F-Gas Regulation's phase-out mandates, which are accelerating utility procurement of oil-insulated alternatives ahead of SF6 displacement timelines across European transmission networks.
Growth Catalysts
- Grid Modernization Mandates:China's State Grid Corporation is expanding ultra-high voltage transmission corridors, requiring bulk-oil switchgear at voltage classes where gas-insulated alternatives remain economically unviable for interconnection projects.
- Ester Oil Regulatory Preference:The EU F-Gas Regulation creates procurement tailwinds for biodegradable insulation fluids in environmentally sensitive installations across Nordic and Alpine regions.
- Rural Electrification Programs:India's Rural Electrification Corporation is driving demand for robust outdoor switchgear in distribution networks where maintenance access is limited and mineral-oil reliability is proven.
Market Restraints
- Mineral Oil Price Volatility:Crude oil derivative costs create margin pressure for manufacturers locked into long-term utility supply contracts with fixed pricing structures.
- Specialized Tank Fabrication Concentration:Precision welding capacity for high-voltage enclosures concentrates in German and Japanese supplier clusters, creating bottleneck risks for project timelines.
- SF6 Technology Lock-In:Gas-insulated switchgear incumbents in urban substations resist displacement where space constraints favor compact designs despite regulatory pressure.
Strategic Opportunities
- Sub-Saharan Transmission Buildout:Kenya and Ethiopia are greenfield markets for 132kV and 220kV oil-insulated installations where no legacy gas-insulated base exists to displace.
- Digital Monitoring Convergence:Integration of dissolved gas analysis sensors with transformer monitoring platforms creates lifecycle service revenue streams for switchgear OEMs.
- US Inflation Reduction Act:Grid resilience funding prioritizes domestic manufacturing of high-voltage equipment, creating localized production incentives for oil-insulated switchgear assembly.
Industry Challenges
- High-Voltage Testing Technician Scarcity:Specialized dielectric testing expertise for 245kV+ equipment is concentrated among retiring European and Japanese engineers, constraining quality assurance throughput.
- Dual-Certification Burden:Manufacturers must maintain parallel IEC 62271 and IEEE C37 testing facilities to access both European and North American utility procurement channels, doubling capital requirements.
- Legacy Asset Integration Complexity:New ester oil switchgear must interface with decades-old mineral-oil transformer fleets, creating compatibility risks in mixed-technology substations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Oil Insulated Switchgear Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breaker, Disconnector, Current Transformer, Voltage Transformer, Earthing Switch Technology: Bulk Oil, Minimum Oil, Self Blast, Synthetic Oil, Ester Oil Application: Power Generation Plants, Substations, Industrial Facilities, Renewable Energy Plants, Transmission Projects End User: Independent Power Producers, Grid Operators, Heavy Industries, Infrastructure Developers, Utilities |
| Companies Covered | General Electric, Siemens, ABB, Schneider Electric, Hitachi Energy, Mitsubishi Electric, Toshiba Energy Systems & Solutions, Hyundai Electric, Fuji Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Oil Insulated Switchgear Market Trends and Innovations
Digitalization of asset monitoring and fluid chemistry is compressing maintenance cycles while regulatory pressure on SF6 is accelerating material substitution in high-voltage insulation systems.
Natural ester fluids derived from seed oils are integrating dissolved gas analysis capabilities directly into switchgear tank designs. Nordic transmission utilities are adopting these systems fastest, driven by both environmental compliance and reduced fire-risk insurance premiums. This integration is enabling predictive maintenance contracts that extend equipment lifecycle value beyond traditional warranty periods.
The EU F-Gas Regulation's 2030 phase-down targets are forcing transmission operators to accelerate oil-insourced procurement ahead of SF6 availability constraints. German grid operators now specify ester oil as default for new 145kV installations in water protection zones. Manufacturers with pre-certified biodegradable fluid designs are capturing premium positioning in these mandated substitution cycles.
Utility procurement departments are unbundling switchgear supply from installation and commissioning services, creating direct OEM-to-utility relationships that bypass traditional EPC intermediaries. This pattern is most pronounced in India's state transmission utilities, where competitive bidding rules favor equipment-only contracts with separate civil works packages. Channel restructuring is compressing margin pools for integrated project contractors while expanding aftermarket service opportunities for manufacturers.
High Voltage Oil Insulated Switchgear Market Segmentation
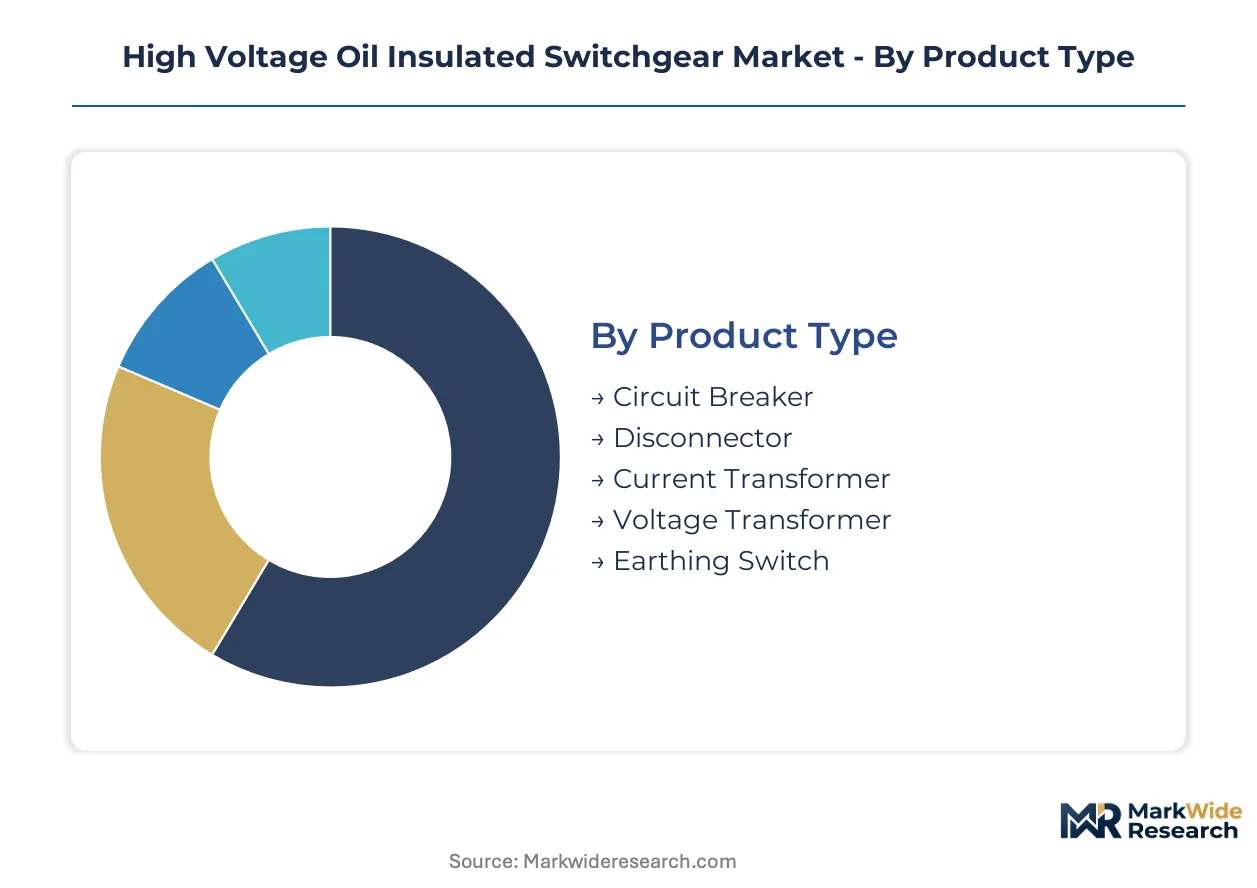
Segmentation in high voltage oil insulated switchgear reveals how procurement priorities diverge between transmission utilities seeking bulk-oil reliability and industrial operators favoring compact minimum-oil designs. Technology choices increasingly hinge on regulatory pressure rather than pure cost economics.
Product Type:
Buyers differentiate primarily by the criticality of protective functions within their network architecture.
- Circuit Breaker:Enclosed assemblies rated above 72.5 kV use mineral or ester oil for simultaneous insulation and arc-quenching under fault conditions. China's State Grid Corporation drives procurement for ultra-high voltage transmission corridors where bulk-oil breakers remain economically dominant over gas-insulated alternatives.
- Disconnector:Mechanical switching devices isolate circuit sections during maintenance but lack load-breaking capability. India's Rural Electrification Corporation specifies robust outdoor disconnectors for distribution networks where maintenance access is severely constrained.
- Current Transformer:Oil-immersed instrument transformers measure line currents for protection relaying. Heavy industries in Germany specify these for steel mill substations requiring precise fault detection.
- Voltage Transformer:Step-down transformers provide metering and protection voltage signals. Grid operators across Nordic countries favor ester-oil variants in water protection zones.
- Earthing Switch:Safety devices discharge residual voltages during equipment servicing. Infrastructure developers in Kenya specify these for greenfield 132kV installations lacking legacy protection systems.
Volume sits with Circuit Breaker; growth tilts toward Ester Oil variants in environmentally sensitive jurisdictions.
Technology:
Cost tier stratification separates mature mineral-oil incumbent technologies from premium biodegradable alternatives commanding regulatory preference.
- Bulk Oil:Large-volume oil tanks submerge all live parts for dielectric insulation and arc quenching in high-current interruption. Transmission projects across developing economies anchor demand where capital constraints favor proven reliability over compact footprint.
- Minimum Oil:Reduced oil volumes concentrate arc-quenching function in specialized interrupter chambers. Industrial facilities in Japan specify these where space constraints and seismic requirements intersect.
- Self Blast:Arc-generated gas pressure enhances oil flow for interruption without mechanical pumps. Grid operators in Brazil deploy these in remote substations where maintenance logistics are prohibitive.
- Synthetic Oil:Laboratory-engineered hydrocarbons offer controlled dielectric properties. Heavy industries in Saudi Arabia specify these for extreme temperature environments where mineral oil viscosity degrades.
- Ester Oil:Seed-oil-derived biodegradable fluids reduce fire risk and environmental liability. The EU F-Gas Regulation accelerates procurement across German and Austrian water protection zones.
Revenue concentrates in Bulk Oil for transmission scale; Ester Oil climbs fastest on regulatory tailwinds.
Application:
Project scale and grid integration complexity determine whether buyers prioritize lifecycle reliability or initial capital efficiency.
- Power Generation Plants:Switchgear isolates generator outputs and synchronizes unit connections to transmission networks. Coal and hydro facilities in India specify mineral-oil bulk breakers for their proven fault-withstand capability.
- Substations:Centralized switching and transformation points require coordinated protection across multiple voltage levels. Grid operators in China expand ultra-high voltage substations along interprovincial corridors.
- Industrial Facilities:Steel, cement, and chemical plants need robust switchgear for captive power distribution. Heavy industries in Germany specify ester-oil variants to satisfy environmental compliance.
- Renewable Energy Plants:Wind and solar farms require switchgear rated for intermittent generation profiles and remote locations. Infrastructure developers in Ethiopia specify outdoor oil-insulated equipment for geothermal tie-ins.
- Transmission Projects:National grid interconnections demand bulk-oil breakers at voltage classes exceeding economic viability of gas-insulated alternatives. Kenya's 220kV backbone expansion exemplifies greenfield procurement.
Transmission Projects anchor volume; Renewable Energy Plants show steepest expansion trajectory on capacity addition mandates.
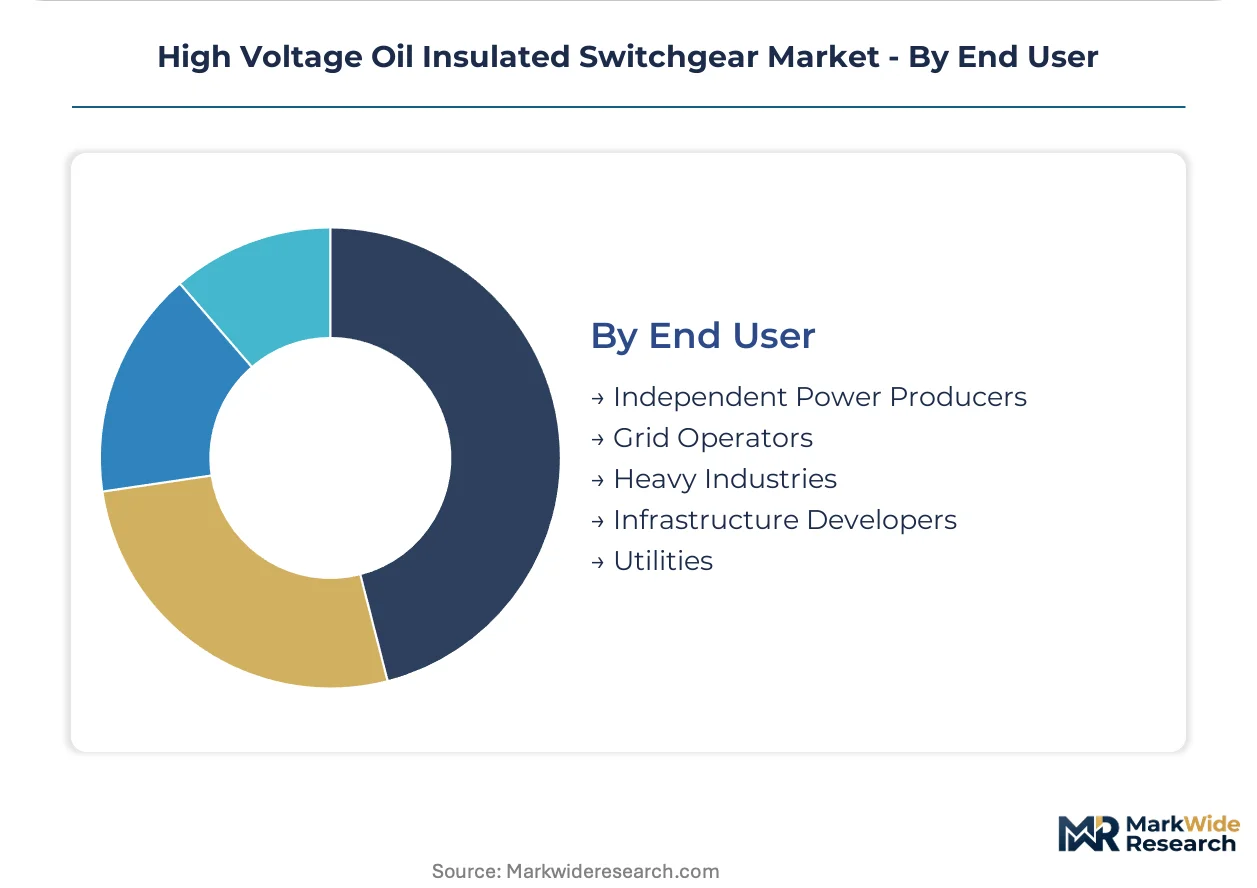
End User:
Procurement sophistication varies from standardized utility tenders to customized industrial specifications.
- Independent Power Producers:Non-utility generators require switchgear optimized for merchant power dispatch and grid code compliance. IPPs in Turkey specify standardized 145kV bulk-oil breakers for gas-fired combined cycle plants.
- Grid Operators:Transmission and distribution utilities drive standardization through centralized procurement frameworks. State Grid Corporation of China and Power Grid Corporation of India dominate global volume through corridor expansion programs.
- Heavy Industries:Steel, aluminum, and petrochemical operators specify switchgear for internal power distribution and process reliability. German steel mills favor integrated digital monitoring packages from ABB and Siemens.
- Infrastructure Developers:Greenfield project sponsors procure switchgear as part of turnkey substation packages. Developers in Kenya and Ethiopia source equipment-only contracts to bypass EPC intermediaries.
- Utilities:Integrated generation-transmission-distribution entities balance standardization against regional network peculiarities. European utilities accelerate ester-oil procurement ahead of EU F-Gas Regulation phase-down timelines.
Grid Operators command volume concentration; Infrastructure Developers gain share fastest on Sub-Saharan transmission buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mineral oil feedstock availability from Middle Eastern crude suppliers anchors manufacturing cost structures across major production clusters. Grid interconnection mandates in Asia-Pacific and European decarbonization timelines reshape regional procurement priorities for high-voltage assemblies.
China
State Grid Corporation's ultra-high voltage corridor expansion drives procurement of bulk-oil breakers at 550kV and above. MIIT's dual carbon goals accelerate domestic manufacturing capacity for biodegradable fluid alternatives. Xi'an and Shenyang host precision welding clusters supplying tank enclosures for transmission projects.
Germany
Transmission system operators advance ester oil procurement ahead of EU F-Gas Regulation phase-down deadlines. The Federal Network Agency mandates environmental compatibility assessments for new substation installations. Bavarian engineering centers develop integrated dissolved gas analysis systems for predictive maintenance contracts.
India
Power Grid Corporation's green energy corridors require robust outdoor switchgear for remote renewable tie-ins. CEA technical standards mandate seismic withstand ratings for Himalayan substation deployments. Gujarat and Maharashtra manufacturing hubs scale tank fabrication capacity for 245kV class equipment.
United States
FERC interconnection queue reforms accelerate transmission buildout requiring bulk-oil switchgear at voltage classes SF6 alternatives cannot yet displace. IRA grid resilience funding prioritizes domestic assembly of high-voltage equipment. Texas and California transmission developers specify mineral-oil designs for extreme temperature reliability.
Kenya
Kenya Electricity Transmission Company expands 220kV backbone infrastructure with no legacy gas-insulated base to displace. The national energy regulator mandates local content requirements for substation equipment procurement. Nairobi-based contractors source equipment-only contracts bypassing traditional EPC intermediaries.
High Voltage Oil Insulated Switchgear Market Competitive Landscape
Global majors compete with regional champions across certification standards and service integration models. The vendor base stratifies into three tiers: integrated electrical conglomerates with dual IEC-IEEE testing facilities, national champions serving protected domestic procurement channels, and specialized tank fabricators concentrated in German and Japanese industrial clusters. Strategic moves center on ester oil pre-certification for EU F-Gas substitution cycles and unbundled equipment supply bypassing EPC intermediaries.
Among European-based engineering groups, Siemens AG and ABB Ltd occupy positions anchoring premium bulk-oil contracts through integrated digital monitoring platforms. Hitachi Energy Ltd exemplifies the cross-regional consolidator archetype, bridging Japanese precision manufacturing with European utility relationships.
| Leading Market Players |
|---|
| General Electric |
| Siemens |
| ABB |
| Schneider Electric |
| Hitachi Energy |
| Mitsubishi Electric |
| Toshiba Energy Systems & Solutions |
| Hyundai Electric |
| Fuji Electric |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between IEC 62271-premium and economy-tier mineral-oil equipment manifests in both pricing spreads and supplier clustering. German and Japanese precision-welding clusters capture premium contracts for 245kV+ ester oil assemblies, while Indian and Chinese fabricators compete on standardized bulk-oil volumes for transmission utilities.
Pricing Analysis
Warranty bundling separates full-lifecycle service contracts from equipment-only procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity and fluid type. Price differentiation rests on dual-certification testing overhead and ester oil pre-certification status. Cost compression in mineral-oil tiers intensifies because crude derivative volatility squeezes fixed-price utility contracts. State transmission utilities in India exhibit highest price sensitivity; Nordic grid operators show lowest sensitivity due to regulatory-mandated environmental compliance premiums.
Supply Chain Analysis
Kenya's local-content requirements and India's PLI scheme are reshaping sourcing patterns for tank fabrication and final assembly. Precision welding capacity concentrates in Germany, Japan, and China. Raw material dependencies include cold-rolled steel plate, transformer-grade mineral oil, and seed-oil ester feedstocks. Single-source vulnerability sits with specialized high-voltage testing technicians concentrated among retiring European and Japanese engineers. Distribution runs through direct OEM-to-utility channels that bypass traditional EPC intermediaries, particularly in India's competitive bidding environment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into precision tank fabrication and dissolved gas analysis sensor production is becoming the decisive competitive lever as procurement unbundles and service revenue pools expand.
For Market Incumbents: Deepen backward integration into high-voltage testing technician training programs and captive ester oil blending capacity. SF6 technology lock-in in urban substations and emerging digital-native competitors threaten premium positioning. Secure dual-certification testing facilities in both IEC and IEEE zones to defend channel access. For New Entrants and Emerging Players: The 30-40% price-point gap between premium ester oil and economy mineral-oil tiers opens white-space at the standard certification level. Target Kenya and Ethiopia for greenfield 132kV-220kV installations where no legacy gas-insulated base exists. Pursue equipment-only contract models that bypass EPC intermediaries and capture direct utility relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated electrical conglomerates seeking regional certification footholds. Long-term viability favors suppliers with pre-certified biodegradable fluid designs and dissolved gas analysis integration capabilities. Watch EU F-Gas Regulation enforcement acceleration as the inflection signal for ester oil demand step-change.| Strategic Initiative | Industry Significance |
|---|---|
| Ester Oil Pre-Certification Investment | EU F-Gas Regulation phase-down timelines accelerate procurement preference for biodegradable fluid designs. |
| Precision Welding Capacity Expansion | German and Japanese supplier clusters face bottleneck risks as transmission investment accelerates across developing economies. |
| Dissolved Gas Analysis Integration | Nordic utilities adopt sensor-embedded tank designs fastest, enabling predictive maintenance contract revenue streams. |
| Dual-Certification Testing Facility Buildout | Parallel IEC 62271 and IEEE C37 facilities unlock procurement access across European and North American utility channels. |
| Direct Utility Channel Development | India's competitive bidding rules favor equipment-only contracts that compress EPC intermediary margins. |
Research Methodology
Document review covered regulatory filings from FERC and the Federal Network Agency, trade data from customs authorities, and technical standards from IEC and IEEE, complemented by interviews with transmission planning officers, substation project developers, EPC contractors, and aftermarket service heads at switchgear OEMs. Secondary validation drew from utility procurement databases, grid interconnection queue records, and equipment certification registries. Bottom-up volume estimates triangulated against top-down transmission investment forecasts.
Segment-level projections across product type, technology, application, and end user combined with voltage-class tier and regional regulatory cluster dimensions generated value estimates across the projection horizon. CAGRs were derived from regression analysis of historic procurement patterns against announced transmission corridor investments. Industry-specific inputs included dissolved gas analysis adoption curves and EU F-Gas Regulation substitution timelines.
Underlying measurement precision varies by segment; transmission project and circuit breaker categories carry tighter precision than industrial facility and earthing switch segments due to public procurement disclosure requirements. Forecasts reflect assumptions regarding mineral oil price stability and ester oil supply chain maturation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Portable Space Heater Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Capacitor Market
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
South America Air Insulated Switchgear Market