
 Copper Ground Rod Market | 2026-2036
Copper Ground Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Ground Rod Market Insights
Project finance tied to transmission infrastructure buildouts is narrowing the competitive field to capitalized manufacturers. Southwire Company, LLC leverages its integrated copper supply chain to secure utility-scale contracts. KGHM Polska Miedź S.A. anchors European production with captive smelting capacity. Jiangxi Copper Corporation Limited dominates raw material sourcing across Asia-Pacific markets.
Copper ground rods are cylindrical conductors, typically 0.5 to 1 inch in diameter and 8 to 10 feet in length, composed of pure electrolytic copper or copper-clad steel, manufactured through extrusion or electroplating processes to achieve electrical conductivity below 0.153 ohm-meter for dissipating fault currents into earth. Solid rods command premium pricing in substation applications where corrosion resistance spans decades, while copper-clad variants penetrate cost-sensitive telecommunications deployments. The certification landscape fragments procurement, with UL Listed products governing North American utility specifications and CE Marked equivalents enabling European market access.
The National Electrical Code in the United States, enforced by local authorities having jurisdiction, mandates maximum grounding electrode resistance thresholds that directly specify copper rod dimensions and burial depth. India's Central Electricity Authority technical standards prescribe similar impedance limits for distribution transformers, creating parallel compliance requirements. China's GB standards and NMPA-aligned quality protocols govern product certification for grid infrastructure imports. Stakeholders must monitor evolving carbon border adjustments that could restructure raw material sourcing economics for copper-intensive grounding products.
Market Dynamics
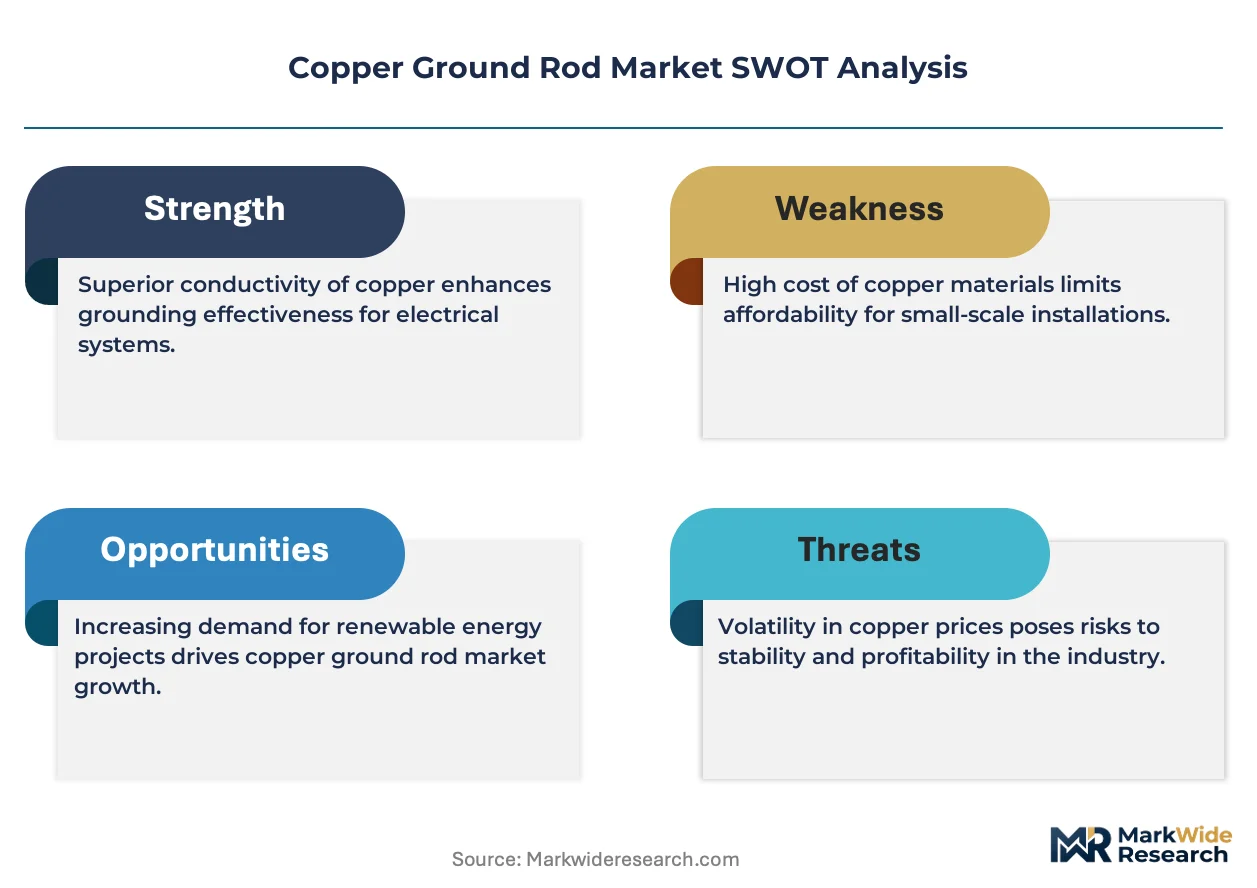
Utility-scale grid modernization programs across India, China, and the United States are concentrating procurement power among capitalized manufacturers with integrated copper supply chains. Project finance tied to transmission infrastructure buildouts now screens suppliers on smelting capacity and captive raw material access.
Growth Catalysts
- India's CEA Technical Standards:Distribution transformer impedance mandates are specifying copper rod dimensions and burial depth for grid infrastructure, creating compliance-driven replacement cycles.
- Data center construction:Asia-Pacific hyperscale facilities are expanding procurement of copper grounding systems for fault current dissipation in high-density electrical environments.
- Electrolytic copper conductivity:Extrusion processes achieving below 0.153 ohm-meter ratings are qualifying rods for substation applications where decades-long corrosion resistance commands specification priority.
Market Restraints
- Copper price volatility:London Metal Exchange pricing swings directly compress margins on copper-clad and solid rod production, forcing hedging costs onto smaller manufacturers.
- Smelting concentration:Captive copper supply chains in Poland and China create sourcing asymmetries for non-integrated competitors lacking backward integration into primary metal production.
- Galvanic corrosion limitations:Copper ground rods in high-salinity soil environments require supplemental corrosion protection, adding installation complexity and lifecycle cost.
Strategic Opportunities
- Telecommunications 5G rollout:Cost-sensitive cell tower deployments are penetrating copper-clad steel variants where impedance requirements permit material substitution from solid copper.
- Carbon border adjustments:Emerging EU tariff structures on embodied carbon in copper-intensive products are restructuring raw material sourcing economics for grounding system exporters.
- Modular grounding kits:Pre-assembled rod, clamp, and conductor packages are displacing field-fabricated installations in commercial construction channels.
Industry Challenges
- UL Listed certification timelines:North American utility specifications require third-party listing that extends product qualification cycles by 8-14 months.
- Electroplating process control:Maintaining consistent copper thickness on steel cores demands capital-intensive continuous monitoring equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Ground Rod Market |
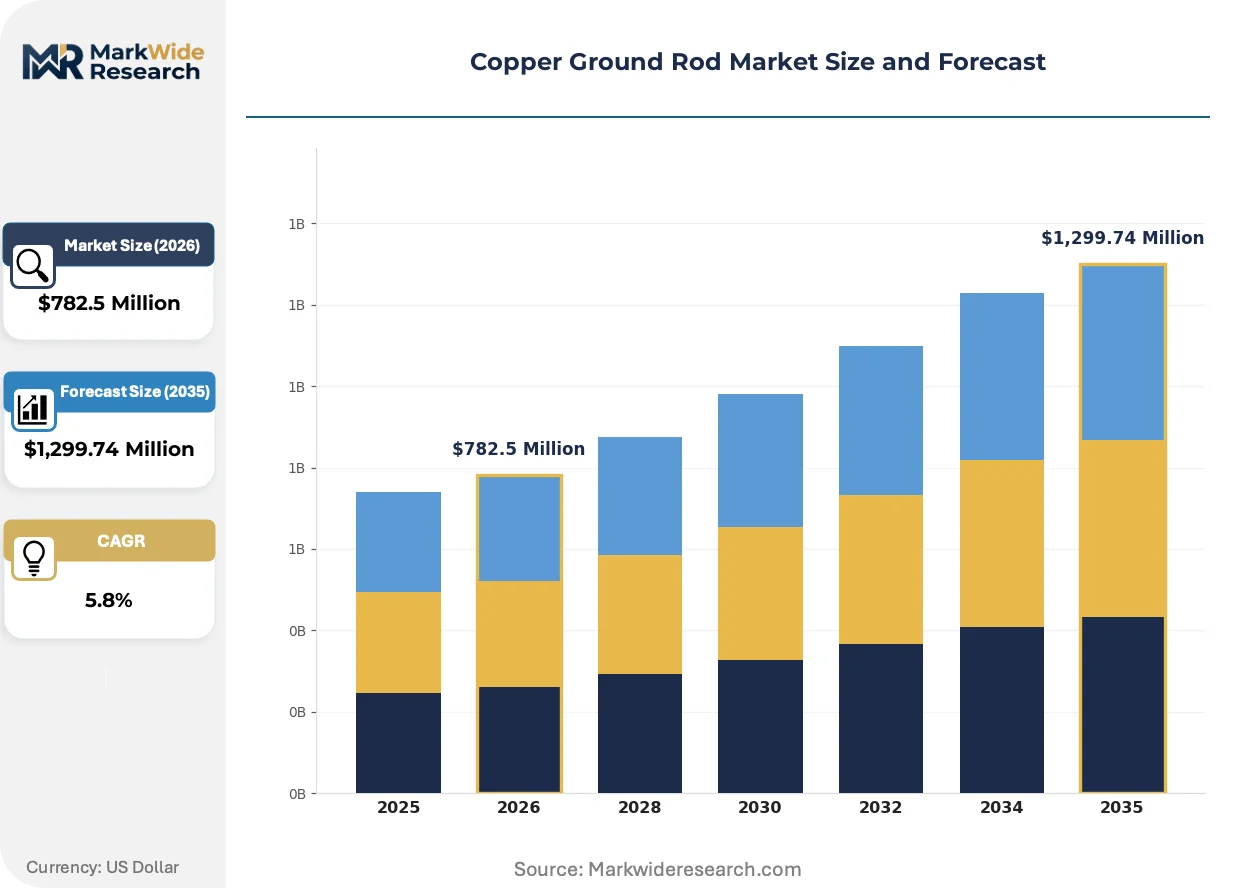
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,299.74 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Rods, Bonded Rods, Copper-Clad Rods, Extruded Rods End User: Electrical Utilities, Telecommunications, Data Centers, Residential Underpinning Installation Method: Direct Burial, Concrete Embedment, Surface Mounting, Electrical Grounding Certification: UL Listed, CSA Approved, ISO Certified, CE Marked |
| Companies Covered | Aurubis AG, Jiangxi Copper Corporation Limited, Southwire Company, LLC, LS Cable & System Ltd., Hindalco Industries Limited, Prysmian S.p.A., KGHM Polska Miedź S.A., Galvan Electrical, Nexans S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Ground Rod Market Trends and Innovations
Digital twin technology is virtualizing grounding system design workflows. Engineers now simulate earth resistance before physical installation. This compresses specification cycles and reduces field remediation costs.
Continuous electroplating systems with real-time thickness monitoring are virtualizing quality assurance for copper-clad steel rods. Manufacturers in South Korea and Taiwan are adopting these lines to serve telecommunications OEMs with batch-traceable conductivity data. The technology is virtualizing the traditional post-production testing bottleneck, compressing lead times from six weeks to ten days.
China's GB standards alignment with NMPA quality protocols is tightening import certification for grid infrastructure copper products. Foreign manufacturers must now submit metallurgical test reports from accredited Chinese laboratories. European exporters are responding by pre-certifying production lines through joint ventures with domestic partners.
Engineering-procurement-construction firms are consolidating grounding system specifications into master service agreements with tier-one electrical distributors. This disintermediates traditional manufacturer-direct relationships. The pattern is most visible in United States commercial construction, where national contractors like Turner and DPR are mandating distributor-stocked UL Listed inventory with same-day availability.
Copper Ground Rod Market Segmentation
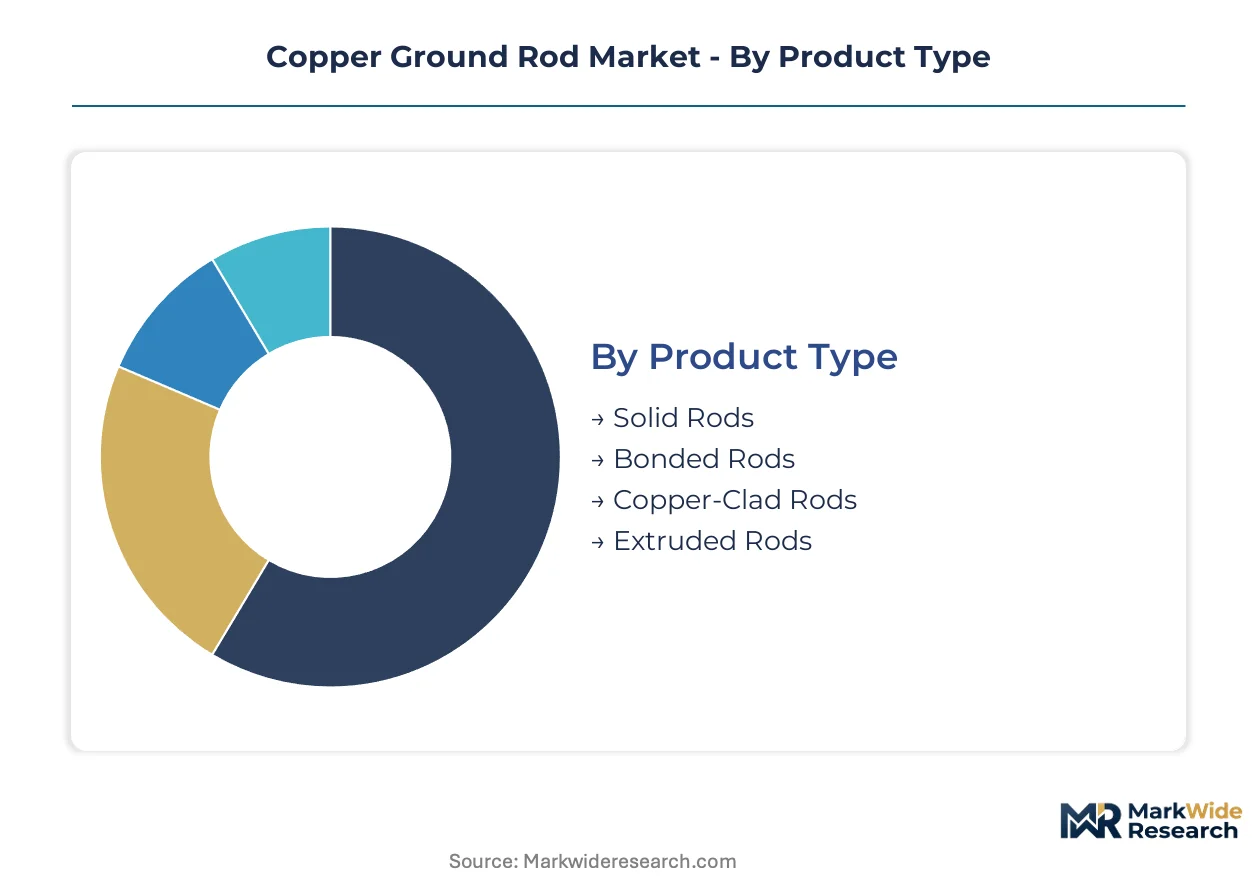
Segmentation in copper ground rods reflects divergent procurement cycles across infrastructure verticals. Utility-scale transmission projects operate on multi-year capital planning horizons, while data center deployments compress specification-to-installation timelines to months. Understanding these rhythm differences enables manufacturers to align inventory and certification investments with actual demand velocity.
Product Type:
Replacement cycles vary dramatically by rod construction—solid copper installations persist for decades in substation environments, while copper-clad variants in telecommunications turn over faster due to impedance degradation and tower reconfiguration needs.
- Solid Rods:Fabricated from pure electrolytic copper with conductivity below 0.153 ohm-meter, these rods command specification priority in utility substations where India's CEA technical standards mandate burial depths exceeding three meters for distribution transformers. The material cost premium is amortized across thirty-plus year service lives in high-corrosion soil conditions.
- Copper-Clad Rods:Steel cores electroplated with copper layers achieve 80% of solid rod conductivity at 40-60% of material cost, penetrating telecommunications 5G tower deployments where South Korean manufacturers now deliver batch-traceable conductivity data within ten-day lead times using continuous monitoring lines.
- Bonded Rods:Molecular bonding of copper to steel substrates creates mechanical adhesion superior to electroplating in high-vibration environments such as railway electrification corridors.
- Extruded Rods:Continuous extrusion of copper alloys produces uniform grain structures favored in European CE Marked specifications for industrial grounding grids.
Solid rods anchor the volume base in utility procurement while copper-clad rods gain share at the steepest rate in telecommunications infrastructure.
End User:
Customer concentration patterns split between regulated utilities with centralized procurement desks and fragmented commercial construction channels where distributor relationships govern specification access.
- Electrical Utilities:India's grid modernization programs and United States transmission buildouts concentrate annual procurement through integrated copper supply chains, with project finance screening suppliers on captive smelting capacity and backward integration into primary metal production.
- Data Centers:Asia-Pacific hyperscale facilities in Singapore and Sydney are expanding fault current dissipation systems for high-density electrical environments, with specifications prioritizing below 0.153 ohm-meter conductivity ratings and corrosion resistance in coastal humidity.
- Telecommunications:Cost-sensitive cell tower operators specify copper-clad variants where impedance requirements permit material substitution, with modular grounding kits displacing field-fabricated installations to reduce labor hours.
- Residential Underpinning:Single-family and multi-family construction channels source through electrical distributors stocking UL Listed inventory for same-day availability, with National Electrical Code compliance mandating maximum grounding electrode resistance thresholds.
Electrical utilities dominate absolute tonnage while data centers expand most quickly as a specification channel.
Installation Method:
Application environments dictate mechanical attachment strategies, with soil chemistry and existing infrastructure density determining method selection.
- Direct Burial:Standard eight to ten foot rod lengths driven into earth dominate utility-scale deployments, with India's CEA standards prescribing burial depths and impedance testing protocols for distribution transformer grounding.
- Concrete Embedment:Building foundation integration provides supplementary grounding electrodes in commercial construction, particularly in urban United States markets where soil resistivity varies block by block.
- Surface Mounting:Above-grade installations serve temporary power scenarios and equipment retrofit markets where excavation costs exceed rod material expense.
- Electrical Grounding:Integrated busbar and conductor systems in substations combine multiple rods into engineered grounding grids with calculated mesh resistance.
Direct burial commands the installed base while concrete embedment climbs fastest in urban commercial construction.
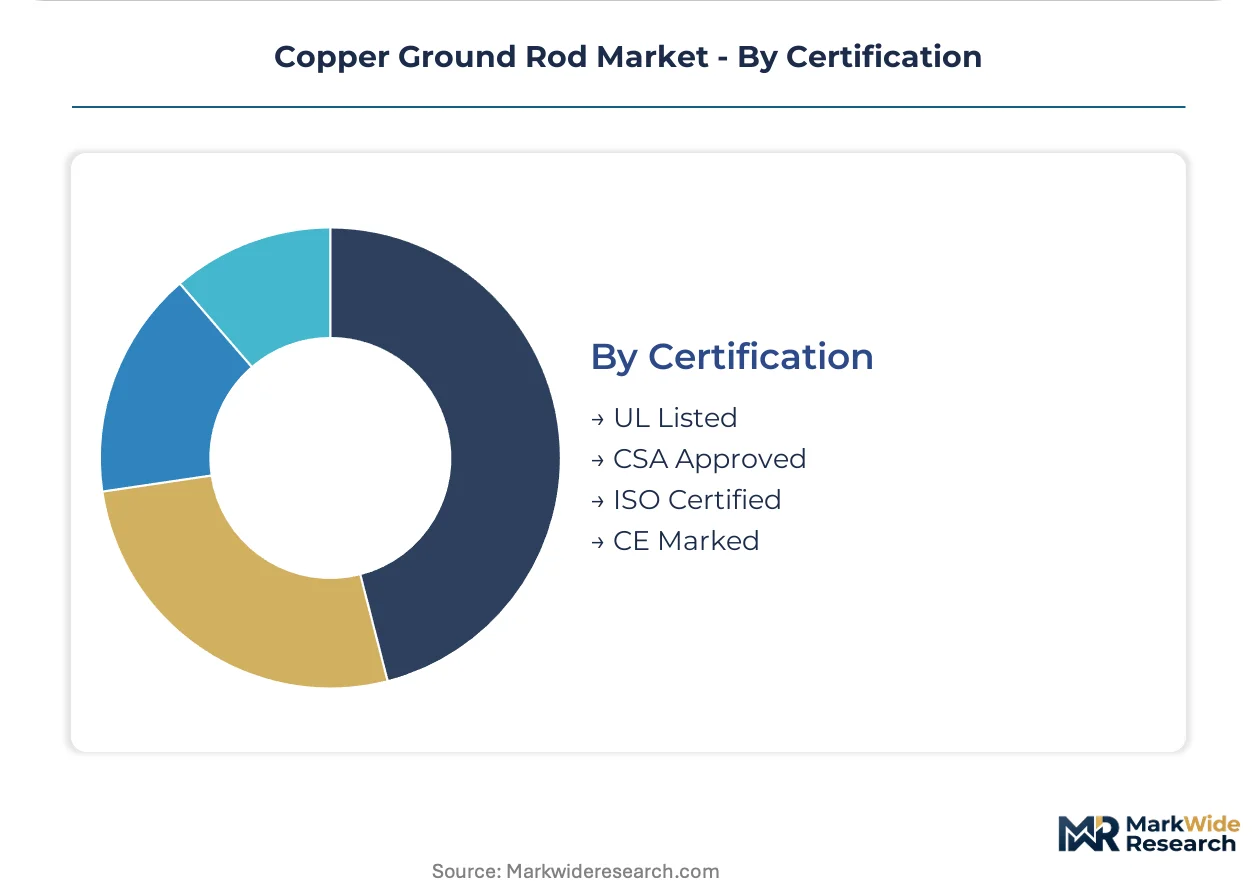
Certification:
Regulatory fragmentation creates parallel qualification tracks, with third-party listing timelines extending product commercialization cycles by eight to fourteen months in North American markets.
- UL Listed:North American utility specifications mandate third-party listing through Underwriters Laboratories, with qualification cycles compressing competitive field to capitalized manufacturers capable of sustaining extended product development timelines.
- CE Marked:European market access requires conformity with EU safety directives, with emerging carbon border adjustments on embodied copper content restructuring raw material sourcing economics for exporters.
- CSA Approved:Canadian electrical codes recognize CSA Group certification for grounding electrode acceptance, with harmonization to UL standards reducing duplicate testing burden for cross-border suppliers.
- ISO Certified:Quality management system certification supports OEM relationships in telecommunications and industrial markets where batch traceability and process documentation govern supplier qualification.
UL Listed products anchor specification authority in North America while CE Marked equivalents expand fastest as European carbon accounting tightens import requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Central Electricity Authority technical standards are mandating copper rod specifications for distribution transformer grounding, creating compliance-driven procurement across utility-scale grid programs. Stricter electrical safety codes in multiple jurisdictions are specifying burial depths and impedance thresholds. Project finance tied to transmission buildouts is screening suppliers on captive smelting capacity and backward integration.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth is expanding fault current dissipation systems for hyperscale electrical environments. The National Electrical Code, enforced by local authorities having jurisdiction, mandates maximum grounding electrode resistance thresholds that specify copper rod dimensions. Southwire Company leverages its integrated copper supply chain to secure utility-scale contracts across Texas and the Southeast.
China
Grid modernization programs are concentrating procurement power among manufacturers with captive raw material access. GB standards and NMPA-aligned quality protocols govern product certification for infrastructure imports. Jiangxi Copper Corporation dominates raw material sourcing across Yangtze River Delta manufacturing clusters serving state-owned utility tenders.
India
Distribution transformer impedance mandates under CEA technical standards are specifying copper rod burial depths exceeding three meters for grid infrastructure. Stricter electrical safety protocols are creating parallel compliance requirements across Maharashtra and Gujarat. Mumbai-Pune industrial corridors are seeing expanded grounding system deployment for substation upgrades.
Germany
European carbon border adjustments on embodied copper content are restructuring raw material sourcing economics for grounding product exporters. ECHA REACH compliance and CE marking requirements govern market access for grid infrastructure components. KGHM Polska Miedź anchors European production with captive smelting capacity serving German utility specifications.
South Korea
Telecommunications 5G tower deployments are penetrating copper-clad steel variants where impedance requirements permit material substitution. Continuous electroplating systems with real-time thickness monitoring are compressing lead times from six weeks to ten days. Seoul-Incheon manufacturing corridors are supplying batch-traceable conductivity data to regional OEMs.
Copper Ground Rod Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. Integrated copper producers with captive smelting capacity command utility-scale transmission contracts, while regional fabricators serve cost-sensitive telecommunications deployments. Two archetypes dominate: backward-integrated metal producers and electroplating specialists serving impedance-tolerant applications. Competitive moves center on certification pre-qualification for national grid tenders and continuous monitoring line investments for lead time compression.
Among integrated producers, Jiangxi Copper Corporation Limited and KGHM Polska Miedź S.A. exemplify the smelter-anchored archetype with captive raw material control. Southwire Company, LLC occupies a position representing North American channel dominance through distributor-stocked UL Listed inventory. These three companies illustrate how geographic concentration of primary metal production shapes competitive access to project-financed infrastructure buildouts.
| Leading Market Players |
|---|
| Aurubis AG |
| Jiangxi Copper Corporation Limited |
| Southwire Company, LLC |
| LS Cable & System Ltd. |
| Hindalco Industries Limited |
| Prysmian S.p.A. |
| KGHM Polska Miedź S.A. |
| Galvan Electrical |
| Nexans S.A. |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's container cost dynamics amplify pricing power for Jiangxi Copper Corporation while forcing smaller electroplating specialists toward copper-clad steel variants. Supply concentration in Chinese smelting capacity creates asymmetric cost absorption across solid rod and bonded rod tiers, with downstream price differentiation widening between utility-scale procurement and telecommunications deployments.
Pricing Analysis
Certification level creates the primary spread, with UL Listed products commanding substantial premiums over ISO Certified equivalents in North American utility specifications. Three-tier pricing structure across premium solid copper, standard copper-clad steel, and economy bonded rod segments reflects conductivity grade and corrosion resistance warranties. Cost compression in the copper-clad tier is intensifying because South Korean continuous electroplating lines are compressing lead time advantages. Electrical utilities exhibit the least price sensitivity due to project finance structures, while telecommunications tower operators prioritize unit economics over specification compliance.
Supply Chain Analysis
Electrolytic copper cathodes draw from smelting concentration in China, Poland, and Chile, with Jiangxi Copper and KGHM Polska Miedź anchoring captive raw material access. Steel core substrates, sulfuric acid for electroplating baths, and continuous monitoring equipment constitute critical input dependencies. Single-source vulnerability in Chinese GB standards certification creates structural risk for European exporters seeking grid infrastructure access. Distribution runs through EPC master service agreements with tier-one electrical distributors, disintermediating traditional manufacturer-direct channels in United States commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through EPC master service agreements that consolidate procurement desks, fragmenting access for non-integrated manufacturers. Engineering-procurement-construction firms like Turner and DPR now mandate distributor-stocked UL Listed inventory with same-day availability.
For Market Incumbents: Insulate utility-scale contract positions by deepening backward integration into primary copper smelting and pre-qualifying production lines for India's CEA technical standards. Southwire Company's integrated supply chain model demonstrates how captive raw material access secures project-financed transmission buildouts. Threats from carbon border adjustments on embodied copper content require European production footprint expansion. Certification investment in Chinese GB standards alignment represents the critical lever for grid infrastructure tender access. For New Entrants and Emerging Players: Establish a beachhead in telecommunications 5G tower deployments where impedance tolerance permits copper-clad steel substitution and modular grounding kits displace field-fabricated installations. The South Korean manufacturing corridor offers the most penetrable geography, with continuous electroplating technology enabling batch-traceable conductivity data delivery. Partner with regional OEMs on ten-day lead time contracts to bypass UL Listed certification timelines that extend qualification cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electroplating specialists with continuous monitoring line investments over traditional extrusion-dependent solid rod producers. Long-term viability across the projection horizon hinges on carbon-adjusted sourcing economics and smelter-anchored backward integration. Acquisition targets should display captive copper supply chains or pre-certified Chinese laboratory access. The signal to watch is EU carbon border adjustment implementation pace, which could restructure raw material sourcing economics for grounding product exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Smelting | Captive copper cathode supply secures project-financed utility contracts against LME price volatility. |
| Continuous Electroplating Line Investment | Real-time thickness monitoring compresses lead times for telecommunications OEM relationships. |
| GB Standards Pre-Certification | Joint ventures with Chinese partners enable grid infrastructure tender access under NMPA protocols. |
| Modular Grounding Kit Development | Pre-assembled packages displace field fabrication in commercial construction distributor channels. |
| Carbon Border Adjustment Hedging | European production footprint expansion insulates export economics from EU tariff structures. |
Research Methodology
The analysis maps solid rod, copper-clad rod, bonded rod, and extruded rod sub-sectors, each validated through utility procurement managers, EPC specification engineers, telecommunications OEM buyers, and electrical distributor category heads. Primary interviews with Jiangxi Copper Corporation supply chain executives and Southwire Company distribution directors combined with secondary validation from SEC 10-K filings, London Metal Exchange copper price data, Indian CEA technical standard notifications, and Chinese GB standards documentation. Bottom-up demand modeling across installation methods and certification tiers triangulated against top-down copper consumption forecasts for grounding applications.
Assumptions held fixed include current UL Listed and CE Marked certification requirements, while copper price volatility trajectories and carbon border adjustment implementation timelines were varied across scenarios. Segmentation dimensions modeled encompass product construction type, end-use vertical, installation environment, and regional regulatory cluster. CAGRs were derived from utility capital expenditure cycles, data center construction pipelines, and telecommunications infrastructure rollout schedules. Industry-specific forecast inputs included India's distribution transformer grounding mandates and Asia-Pacific hyperscale facility electrical density specifications.
Sensitivities concentrate around London Metal Exchange copper price swings, EU carbon border adjustment implementation pace, and Chinese GB standards alignment with NMPA protocols. Forecasts reflect documented assumptions regarding grid modernization program funding continuity and telecommunications 5G deployment velocity. Cross-checking against Indian Central Electricity Authority procurement disclosure data and United States EPC firm master service agreement filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
Train Contactor Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
Instrument Transformers Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market