
 Alternators Market | 2026-2036
Alternators Market Size, Share, and Industry Trends Forecast 2026-2036
Alternators Market Intelligence
New production capacity additions in India, supported by government initiatives, is fragmenting the traditional manufacturing landscape. Global supplier Bosch leverages its extensive R&D in high-efficiency components to serve both OEM and aftermarket channels. Denso Corporation sustains its strong position through deep relationships with Japanese vehicle manufacturers. Meanwhile, Cummins Inc. specializes in integrated power systems for heavy-duty commercial and industrial applications.
An alternator is an electromechanical device that converts mechanical energy into AC electrical power. It functions by rotating a magnetic field within a stationary winding, with output typically rectified to DC for vehicle systems. Brushless alternators represent the fastest-growing product segment due to their enhanced durability and lower maintenance needs. The OEM channel dominates sales, with demand for high-output units particularly strong from the commercial vehicles application.
Component standards are shaped by a complex web of national and regional rules. Regulations like the EU's RoHS directive and China's GB standards govern material composition and performance, while US EPA emissions targets indirectly push for higher electrical system efficiency. The critical decision for suppliers now is how to position their portfolio as vehicle electrification alters the role and necessity of traditional engine-driven alternators.
Market Dynamics
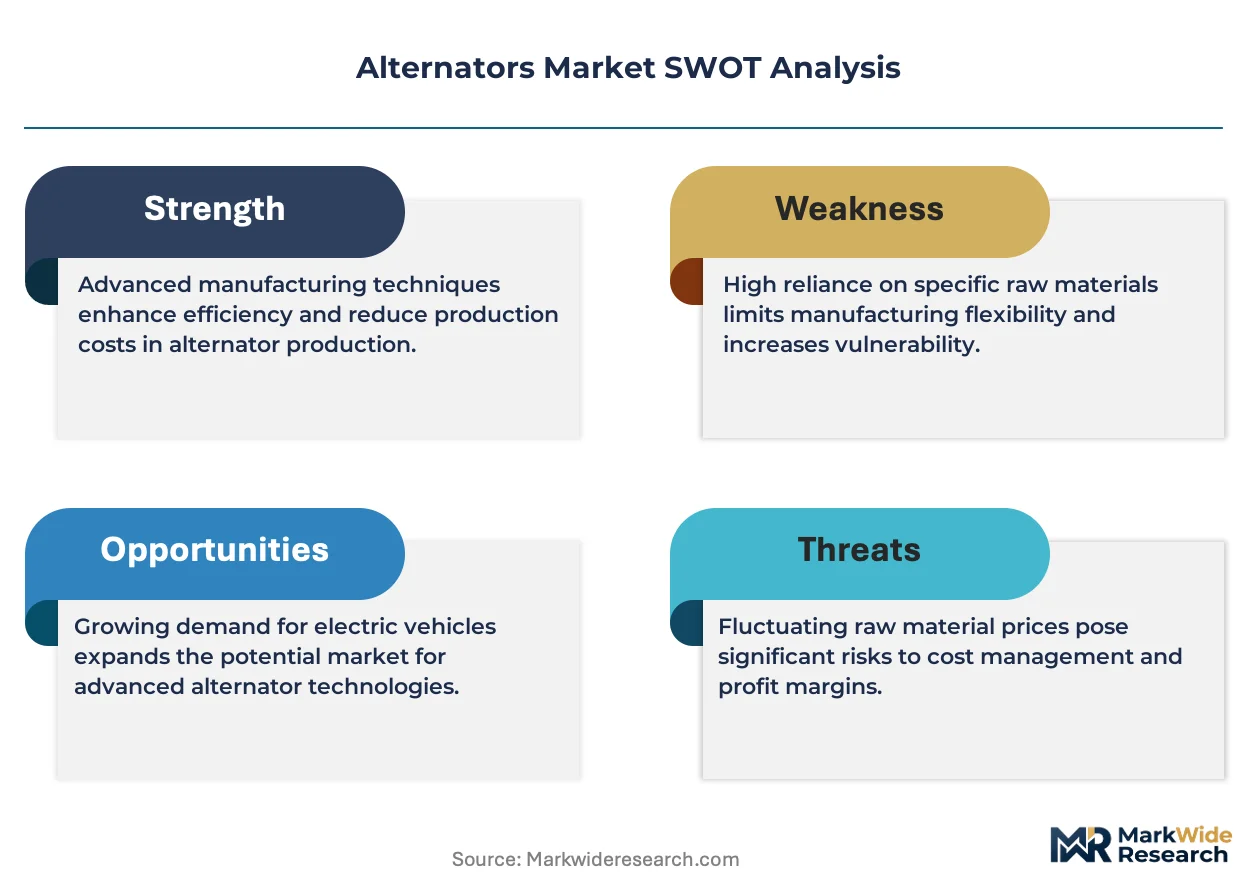
The alternator market is defined by a core tension. Rising electrical loads in vehicles, driven by advanced electronics and efficiency mandates from bodies like the US EPA, push for higher-output units, while the long-term shift to full vehicle electrification threatens the traditional alternator's role.
Growth Catalysts
- Regulatory Modernization:The EU's RoHS directive, governing material composition, accelerates the replacement cycle in the aftermarket as older, non-compliant alternators are phased out.
- Agricultural Mechanization:Demand from the agricultural machinery sector for robust power generation in tractors and harvesters, especially in South Asia and Latin America, provides consistent volume.
- Mild-Hybrid Systems:The integration of 48-volt mild-hybrid architectures in passenger cars to meet emissions targets creates a new, high-value segment for belt-starter generators.
Market Restraints
- BEV Substitution:The long-term transition to battery electric vehicles (BEVs) fundamentally eliminates the requirement for an engine-driven alternator, shrinking the addressable OEM market.
- Input Cost Volatility:Fluctuations in the global prices of copper for windings and high-strength magnets for rotors introduce significant cost pressure on component manufacturers.
- Geographic Concentration:A high dependency on component suppliers clustered in specific industrial zones within China introduces risks related to trade policy and logistical bottlenecks.
Strategic Opportunities
- Indian Aftermarket Growth:India's expanding vehicle parc and government support through the PLI scheme create a significant opportunity for aftermarket suppliers and local manufacturing ventures.
- Specialized Commercial Units:There is an opening for high-output, ruggedized alternators designed specifically for auxiliary power units in refrigerated trucking and heavy-duty off-highway equipment.
- Power System Integration:Developing integrated power generation modules that combine the alternator, regulator, and basic battery management functions offers a value-added solution for start-stop systems.
Industry Challenges
- Fragmented Compliance Burden:Suppliers face high costs and long lead times to ensure products meet a patchwork of regional rules, including China's GB standards and EU vehicle type approvals.
- Complex System Integration:Integrating smart alternators with sophisticated vehicle electronic control units and CAN bus communication protocols requires specialized software and validation expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternators Market |
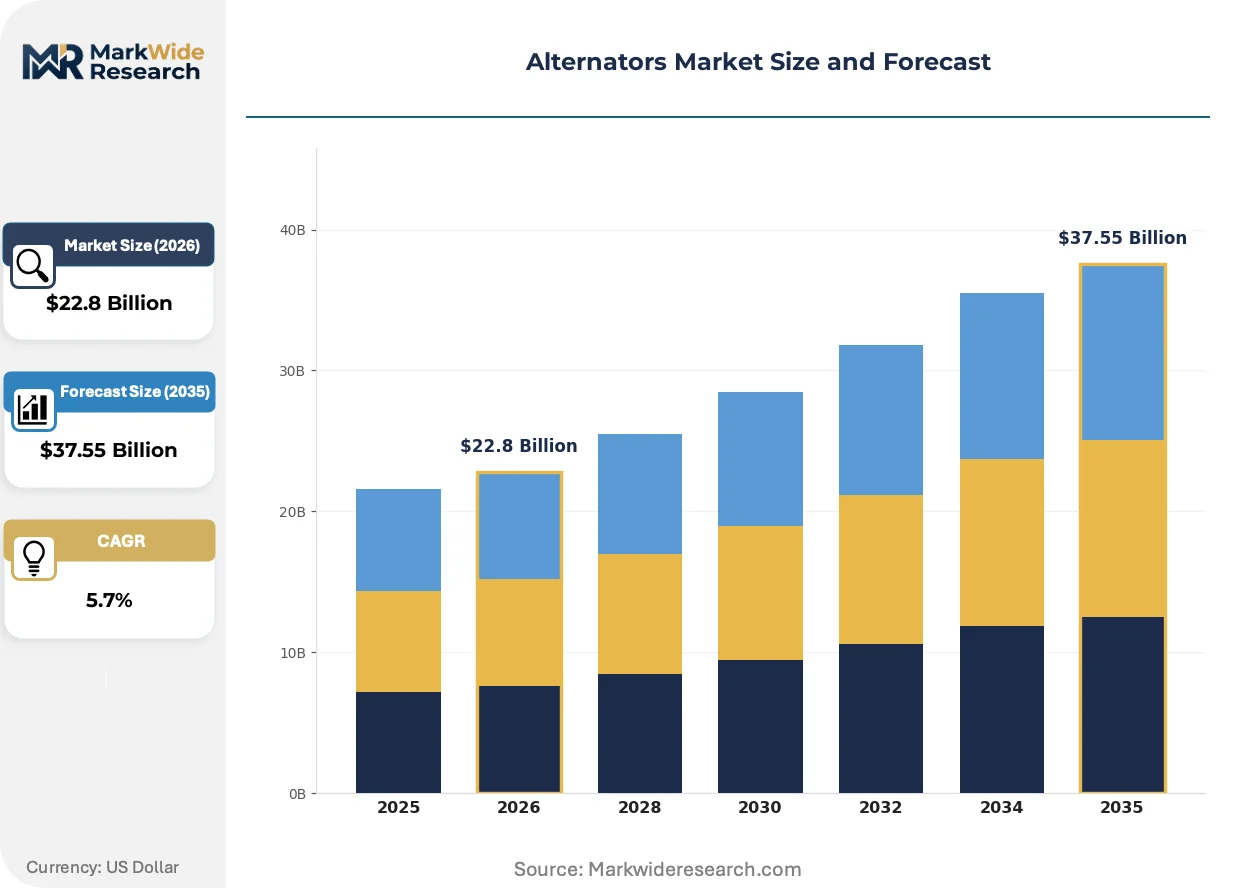
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless Alternators, Brushed Alternators, Brushless AC Generators, Brushed AC Generators Application: Passenger Vehicles, Commercial Vehicles, Agricultural Machinery, Marine Vessels, Construction Equipment Technology: Permanent Magnet, Synchronous, Asynchronous, Electronically Controlled End User Industry: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Repair Workshops |
| Companies Covered | Mecc Alte Spa, Denso Corporation, ABB Ltd., Delphi Technologies, Bosch, Cummins Inc., Siemens AG, Mitsubishi Electric, Leroy Somer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternators Market Strategic Shifts & Innovations
The evolution of the alternator is driven by the need for greater electrical system efficiency to meet stringent emissions regulations. This pressure forces a strategic re-evaluation of the alternator's function, pushing innovation toward more integrated and intelligent power generation solutions.
Brushless alternator designs provide enhanced durability and efficiency, especially in high-demand applications. Commercial vehicle and heavy-duty equipment operators are primary adopters due to lower maintenance and higher reliability. This technology is hybridizing the alternator's role, transforming it into an integrated component that supports start-stop systems and limited energy recuperation.
Vehicle efficiency mandates, such as the US EPA’s GHG emissions standards, are a primary force shaping component design. These regulations compel truck manufacturers to reduce parasitic engine losses, increasing demand for higher-efficiency alternators. The heavy-duty commercial vehicle segment is most affected, prioritizing alternators with superior output-to-weight ratios and lower mechanical drag.
Aftermarket purchasing is moving from traditional distribution towards direct sourcing via online B2B platforms. This disintermediates smaller, regional parts distributors, empowering repair chains and mechanics with greater price transparency. This channel shift is particularly pronounced in the North American and European aftermarket, where digital tools for parts procurement are widespread.
Alternators Market Segmentation
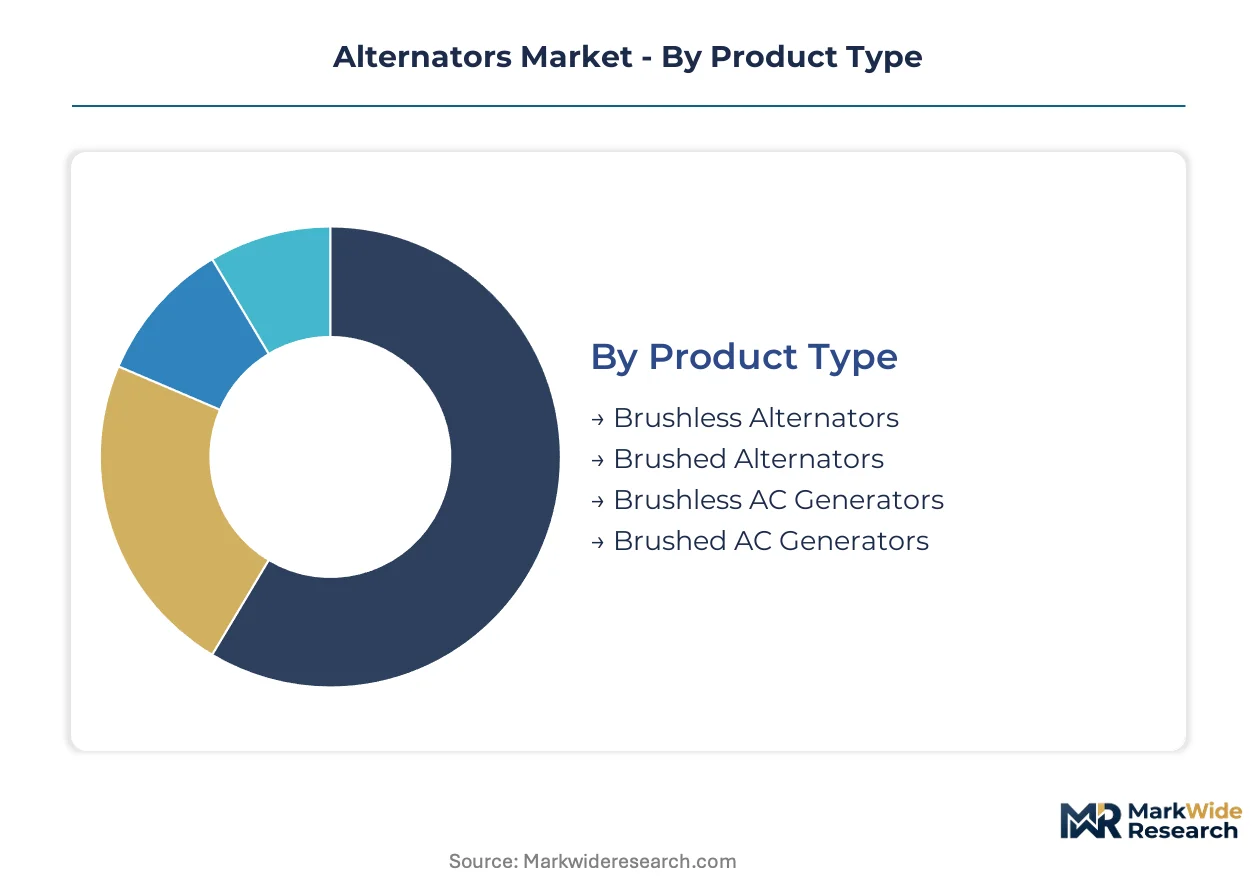
Understanding the alternator market through segmentation reveals critical insights into product lifecycles, technological adoption rates, and end-user purchasing behaviors. This analysis dissects the market by product type, application, underlying technology, and the diverse end-user industries driving demand, highlighting distinct value propositions across each category.
Product Type:
Product type segmentation often dictates the replacement cycle and maintenance frequency within the alternator market. Traditional brushed units typically have shorter service intervals compared to their brushless counterparts, influencing aftermarket demand dynamics.
- Brushless Alternators:These units offer enhanced durability and lower maintenance requirements due to the absence of brushes, making them ideal for continuous operation in demanding environments. Commercial vehicles and heavy-duty equipment operators are primary adopters, seeking reliability and reduced downtime.
- Brushed Alternators:Employing carbon brushes for current transfer, these conventional alternators represent an established technology with a proven track record across various vehicle platforms. Passenger vehicles and older agricultural machinery continue to utilize brushed designs due to cost-effectiveness and widespread availability.
- Brushless AC Generators:Designed for robust power generation without the need for periodic brush replacement, these generators convert mechanical energy directly into alternating current. Industrial power systems and some specialized marine vessels utilize brushless AC generators for their inherent reliability.
- Brushed AC Generators:These generators use brushes and slip rings to transfer current, providing a straightforward and cost-effective solution for AC power generation. Smaller portable power units and certain legacy industrial applications still incorporate brushed AC generators.
Brushed Alternators anchors the volume base while Brushless Alternators gains share at the steepest rate.
Application:
The application segment illuminates how varying operational demands and regulatory pressures shape alternator specifications and market volume. Each application presents unique requirements for power output, ruggedness, and integration with vehicle electrical systems.
- Passenger Vehicles:This segment represents the largest volume driver, requiring alternators that balance efficiency, cost, and compact design for standard electrical loads. Automakers prioritize integrated solutions for start-stop systems and mild-hybrid architectures in passenger cars.
- Commercial Vehicles:Demand in this segment focuses on high-output and ruggedized alternators capable of powering extensive electrical systems and auxiliary loads in trucks and buses. Fleet operators and logistics companies require reliable units to minimize operational downtime.
- Agricultural Machinery:Tractors, harvesters, and other farm equipment demand robust alternators designed to withstand harsh operating conditions, including dust, vibration, and extreme temperatures. South Asia and Latin America drive significant volume in this application.
- Marine Vessels:Alternators for marine applications require corrosion resistance and reliable performance in wet, saline environments. Recreational boats and commercial fishing vessels depend on these units for consistent onboard power.
- Construction Equipment:Heavy machinery like excavators and bulldozers utilize alternators built for extreme durability and high power output to support hydraulic systems and various electrical accessories. Construction companies prioritize longevity and resistance to shock.
Commercial Vehicles demand high-output units, while Passenger Vehicles represent the largest installed base.
Technology:
Technological differentiation within the alternator market reflects efforts to enhance efficiency, integrate with advanced vehicle systems, and meet evolving performance requirements. Innovations in this area directly influence component design and manufacturing complexity.
- Permanent Magnet:These alternators are compact and highly efficient, often found in smaller applications or where space and weight are critical considerations. Electric bicycles and some auxiliary power units utilize permanent magnet technology due to its inherent efficiency.
- Synchronous:Synchronous alternators are widely used for stable frequency and voltage output, making them suitable for many industrial and automotive applications. Traditional vehicle alternators frequently employ synchronous principles for power generation.
- Asynchronous:Asynchronous alternators, also known as induction generators, offer simplicity and robustness, often used in less demanding applications or where variable speed operation is common. Some specialized industrial equipment incorporates asynchronous designs.
- Electronically Controlled:These alternators integrate sophisticated control units to optimize power output based on vehicle electrical load and engine conditions, improving fuel efficiency. Modern commercial vehicles and mild-hybrid systems increasingly adopt electronically controlled units.
Electronically Controlled technology is gaining traction for efficiency, while Synchronous designs remain a foundational element.
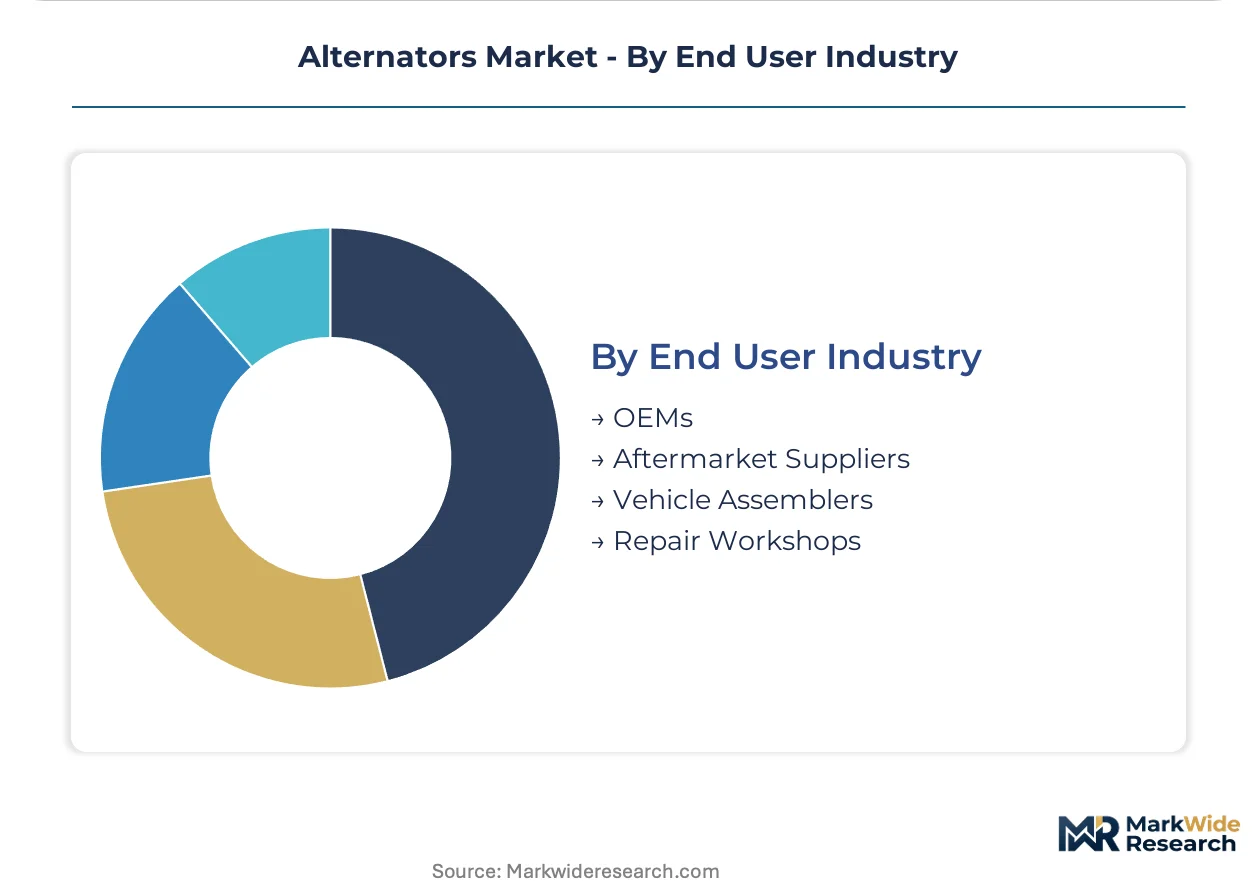
End User Industry:
Segmentation by end-user industry highlights the distinct purchasing patterns and supply chain structures within the alternator market. Each industry has specific requirements for product specification, volume, and service support, influencing supplier strategies.
- OEMs:Original Equipment Manufacturers represent the primary channel for new vehicle installations, demanding high volumes, stringent quality control, and close integration with vehicle design cycles. Automotive industrial clusters in China serve a significant portion of global OEM demand.
- Aftermarket Suppliers:This segment caters to replacement demand for alternators in existing vehicles, driven by wear-and-tear and regulatory modernization. India's expanding vehicle parc offers a significant opportunity for aftermarket suppliers.
- Vehicle Assemblers:These entities integrate alternators into the final vehicle assembly process, often sourcing from multiple suppliers to meet diverse model requirements. Global vehicle production lines heavily rely on timely component delivery from specialized manufacturers.
- Repair Workshops:Local and regional repair workshops serve the immediate needs of vehicle owners, requiring readily available and cost-effective replacement alternators. Online B2B platforms are shifting procurement patterns for repair shops in North America.
OEMs drive initial market volume, while Aftermarket Suppliers benefit from the ongoing replacement cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The alternator market's supply side exhibits distinct regional concentrations, with manufacturing and aftermarket demand heavily focused within specific industrial clusters. This geographic distribution shapes global trade flows and influences component availability for vehicle manufacturers and repair networks alike. Government initiatives in emerging economies are also fostering new production hubs.
China
China's automotive industrial clusters drive substantial manufacturing and aftermarket demand for alternators. Stricter GB standards govern material composition and performance, influencing local production specifications. These clusters, particularly in the Yangtze River Delta, serve as global production centers for both OEM and aftermarket components.
India
India's expanding vehicle parc offers significant opportunities for aftermarket suppliers and local manufacturing ventures. The government's PLI scheme supports new production capacity additions, aiming to boost domestic output. This initiative is fostering new manufacturing hubs in regions like Maharashtra and Tamil Nadu, diversifying the global supply chain.
United States
The United States market experiences strong demand for higher-output alternators, driven by increased electrical loads and efficiency mandates. US EPA emissions targets indirectly push for higher electrical system efficiency across vehicle platforms. The heavy-duty commercial vehicle segment, particularly around Detroit and the Midwest, prioritizes robust power generation units.
Germany
German suppliers, exemplified by Bosch, leverage extensive R&D in high-efficiency components for both OEM and aftermarket channels. The EU's RoHS directive impacts material composition, accelerating replacement cycles for older, non-compliant alternators. Automotive industrial regions like Baden-Württemberg remain central to advanced alternator development and production.
Japan
Japanese vehicle manufacturers maintain deep relationships with domestic suppliers like Denso Corporation, sustaining a strong market position. The country's robust domestic regulatory framework ensures high-quality and reliable alternator components. Major automotive production centers, such as those in the Kanto region, continue to drive stable demand for advanced units.
Alternators Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical electromechanical devices. The alternator market features a tiered structure, with global Tier-1 suppliers dominating the OEM channel while regional manufacturers cater to diverse aftermarket needs. Strategic partnerships with vehicle manufacturers and continuous R&D in high-efficiency components represent dominant competitive moves.
Global Tier-1 suppliers like Bosch and Denso Corporation exemplify the market's entrenched players, leveraging extensive R&D and deep OEM relationships. Cummins Inc., a US-based company, occupies a specialized niche, focusing on integrated power systems for heavy-duty commercial and industrial applications. These companies anchor different segments of the market through their distinct product portfolios and customer engagement models.
| Leading Market Players |
|---|
| Mecc Alte Spa |
| Denso Corporation |
| ABB Ltd. |
| Delphi Technologies |
| Bosch |
| Cummins Inc. |
| Siemens AG |
| Mitsubishi Electric |
| Leroy Somer |
| Others |
Cost & Logistics Intelligence
China's automotive industrial clusters, particularly the Yangtze River Delta, influence global alternator pricing by concentrating manufacturing capacity. This geographic concentration allows for economies of scale, but also introduces supply-side vulnerabilities that can impact cost structures downstream.
Pricing Analysis
EU's RoHS directive dictates the pricing tier structure for aftermarket alternators, accelerating replacement cycles for non-compliant units. Per-unit transactional pricing dominates, with long-term contracts securing OEM volumes. Price differentiation stems from quality grade and brand premium, especially for high-efficiency brushless designs. Pricing softness reflects raw material price volatility, particularly for copper and high-strength magnets. Aftermarket buyers in price-sensitive segments exhibit the highest price sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, supporting component manufacturers within the complex alternator ecosystem. Geographic supply concentration centers on industrial zones in China, alongside established hubs in Germany and Japan, with India emerging. Raw material dependencies include copper for windings and rare earth magnets for high-efficiency units. A structural risk involves single-source vulnerability from specific component suppliers in concentrated regions. Distribution runs through direct OEM channels and a fragmented aftermarket network, increasingly utilizing online B2B platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alternators market demands a robust substitution defense against the long-term transition to battery electric vehicles. Incumbents must navigate this fundamental threat to traditional engine-driven power generation.
For Market Incumbents: Entrench core OEM relationships by investing in advanced R&D for 48-volt mild-hybrid systems. Diversify product portfolios into integrated power generation modules that support start-stop functionality and limited energy recuperation. Mitigate the BEV transition threat through strategic partnerships with vehicle manufacturers on next-generation electrical system architectures.
For New Entrants and Emerging Players: Pursue specialized niches within the heavy-duty commercial and off-highway equipment segments. Develop ruggedized, high-output alternators designed for auxiliary power units in demanding applications like refrigerated trucking. The Indian aftermarket presents a penetrable segment due to its expanding vehicle parc and government support for local manufacturing. Go-to-market strategies should leverage online B2B platforms for direct access to repair chains.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists in brushless designs and integrated power management. Long-term viability hinges on companies with strong intellectual property in high-efficiency components and connectivity for smart alternators. Acquisition targets should include mid-cap firms with established OEM relationships or advanced manufacturing capabilities. The adoption rate of 48-volt mild-hybrid systems serves as a critical inflection indicator for investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Diversifies manufacturing footprint and capitalizes on the growing South Asian aftermarket demand. |
| Product Launch: Integrated Power Module | Addresses the evolving demand for advanced start-stop and mild-hybrid vehicle electrical systems. |
| Strategic Partnership with Commercial Vehicle OEMs | Secures long-term supply agreements for high-output, ruggedized alternators in a stable segment. |
| Acquisition of Brushless Technology Specialist | Enhances portfolio with durable, low-maintenance products crucial for heavy-duty applications. |
| Green Manufacturing Transition | Aligns with global sustainability mandates and improves material compliance, such as EU RoHS. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews. This included OEM procurement leads, aftermarket distributors, heavy-duty fleet managers, and R&D engineers specializing in power electronics. Secondary validation drew from US EPA reports, EU RoHS directives, China's GB standards, and global automotive industry association publications. Bottom-up market sizing was triangulated with top-down industry revenue figures.
Calibration of the analytical framework involved assessing historical market trends and projecting future growth drivers across the analysis window. Segmentation dimensions modeled included product type, application, underlying technology, end-user industry, and regional regulatory environments. Compound Annual Growth Rates were derived from a synthesis of historical performance and anticipated technological shifts. Key inputs included global vehicle production forecasts and electrification roadmap projections.
Sensitivities concentrate around raw material price volatility and the pace of battery electric vehicle adoption. Forecasts reflect assumptions regarding technological evolution and regulatory stability over the projection horizon. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Middle East and Africa High Voltage Switchgear Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Capacitor Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Taiwan Electric Power Equipment Market
Electrical Power Equipment
Power Over Ethernet Lighting Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Electrodialysis System Market