
 Rig and Oilfield Mats Market | 2026-2036
Rig and Oilfield Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Rig and Oilfield Mats Market Outlook
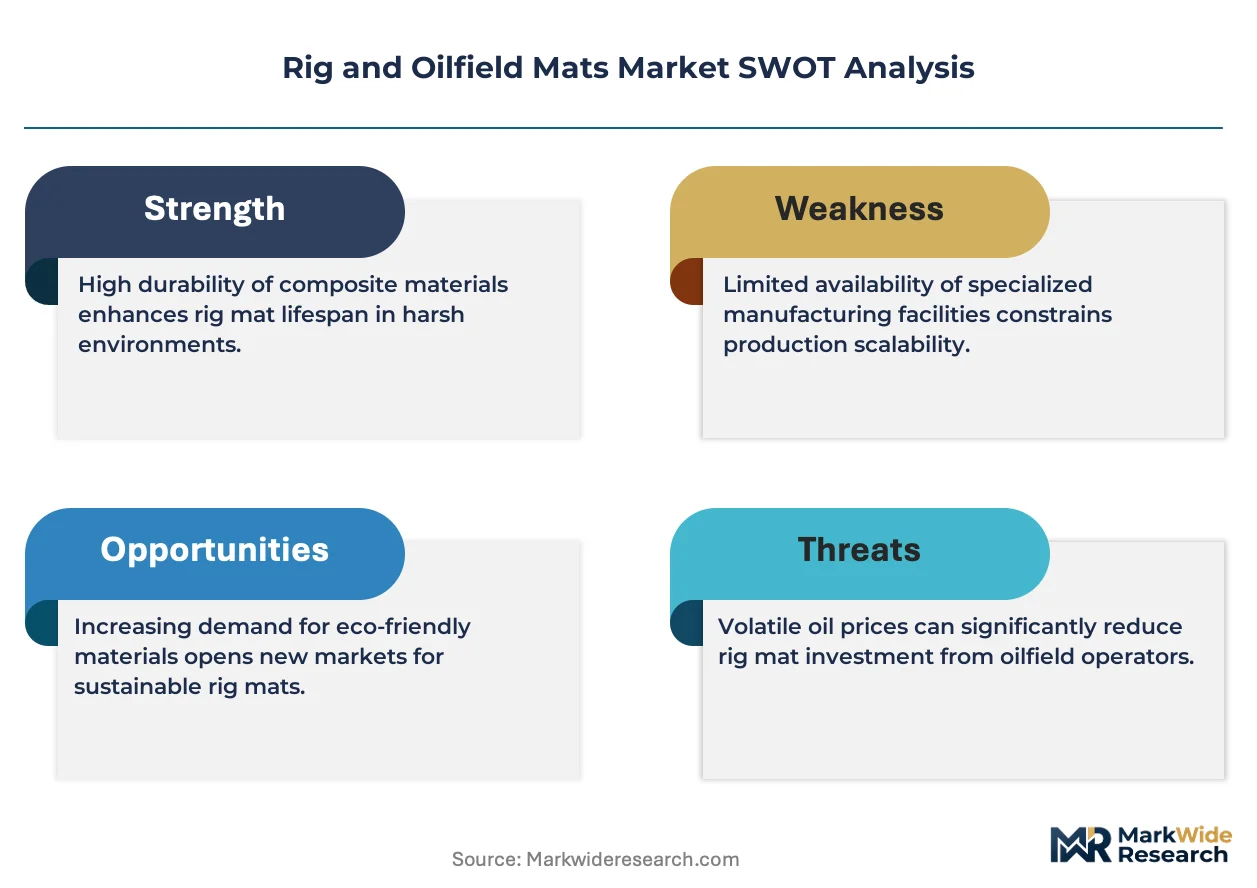
Composite resin is decoupling rig mat economics from traditional timber supply chains. Newpark Resources leverages its integrated composite manufacturing to sustain margin structures despite volatile petrochemical feedstock costs. Quality Mat Company anchors its position through hardwood sourcing networks across the southern United States. Signature Systems Group differentiates via specialized heavy-duty mat designs for extended-use drilling pads.
Rig and oilfield mats are modular surface systems engineered to distribute concentrated loads across unstable terrain, typically fabricated from laminated hardwood, extruded HDPE composites, or aluminum alloys rated for axle loads exceeding 80,000 pounds. Their primary function is to prevent rutting, contamination, and equipment immobilization during drilling, completion, and production operations in remote or environmentally sensitive locations. Composite mats now command the fastest expansion trajectory as operators prioritize reusable substrates that withstand multi-well pad cycling, while wood retains cost leadership in single-use applications. Drilling applications generate the deepest demand pool, though construction and mining segments are widening procurement volumes as infrastructure spending accelerates.
OSHA workplace safety standards and EPA spill prevention regulations under the Clean Water Act shape product specifications by mandating impermeable surfaces and load-bearing documentation for temporary access ways. The U.S. Bureau of Land Management's stipulations for surface disturbance mitigation on federal leases further constrain material choices toward certified composite or treated timber systems. Stakeholders must weigh capital recovery periods against rental utilization rates as pad construction cycles compress and environmental liability frameworks tighten.
Market Dynamics
Composite resin maturation is compressing traditional timber economics while EPA substrate protection mandates force capital rotation toward reusable systems. Drilling contractors now face shortened payback windows as multi-well pad cycling accelerates.
Growth Catalysts
- EPA Spill Prevention Rules:Tightened Clean Water Act enforcement mandates impermeable surfaces for drilling pads, forcing substrate upgrades across the Permian Basin and Bakken formation.
- HDPE Composite Durability:Extended lifecycle performance across 50+ well cycles reduces per-well surface costs and eliminates disposal liability for onshore operators.
- Pad Construction Intensity:Multi-well pad drilling in Texas and North Dakota concentrates mat demand where rig mobilization frequency remains highest.
Market Restraints
- Petrochemical Feedstock Volatility:HDPE resin prices track ethylene cracker output swings, compressing composite manufacturer margins during upstream supply disruptions.
- Hardwood Supply Concentration:Southern United States timber networks face climate-induced harvest variability, constraining treated wood mat availability for single-use applications.
- Aluminum Alloy Substitution Ceiling:Lightweight metal mats fail to achieve cost parity for extended-cycle deployment, limiting penetration beyond helicopter-accessible remote sites.
Strategic Opportunities
- Mining Infrastructure Expansion:Copper and lithium extraction in Nevada and Arizona requires temporary access matting for environmentally sensitive high-altitude terrain.
- Carbon Capture Construction:Pipeline and injection well builds create new demand for load-distributed surface systems across saline formation regions.
- Rental Utilization Models:Third-party mat fleet operators capture margin from contractors seeking to avoid capital deployment on compressed drilling timelines.
Industry Challenges
- Load Certification Documentation:Bureau of Land Management lease stipulations require axle-load testing records that smaller fabricators struggle to maintain across decentralized manufacturing.
- Cross-Contamination Protocols:Biosecurity requirements for mats moving between ecologically distinct drilling zones impose cleaning and tracking costs that erode rental economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rig and Oilfield Mats Market |
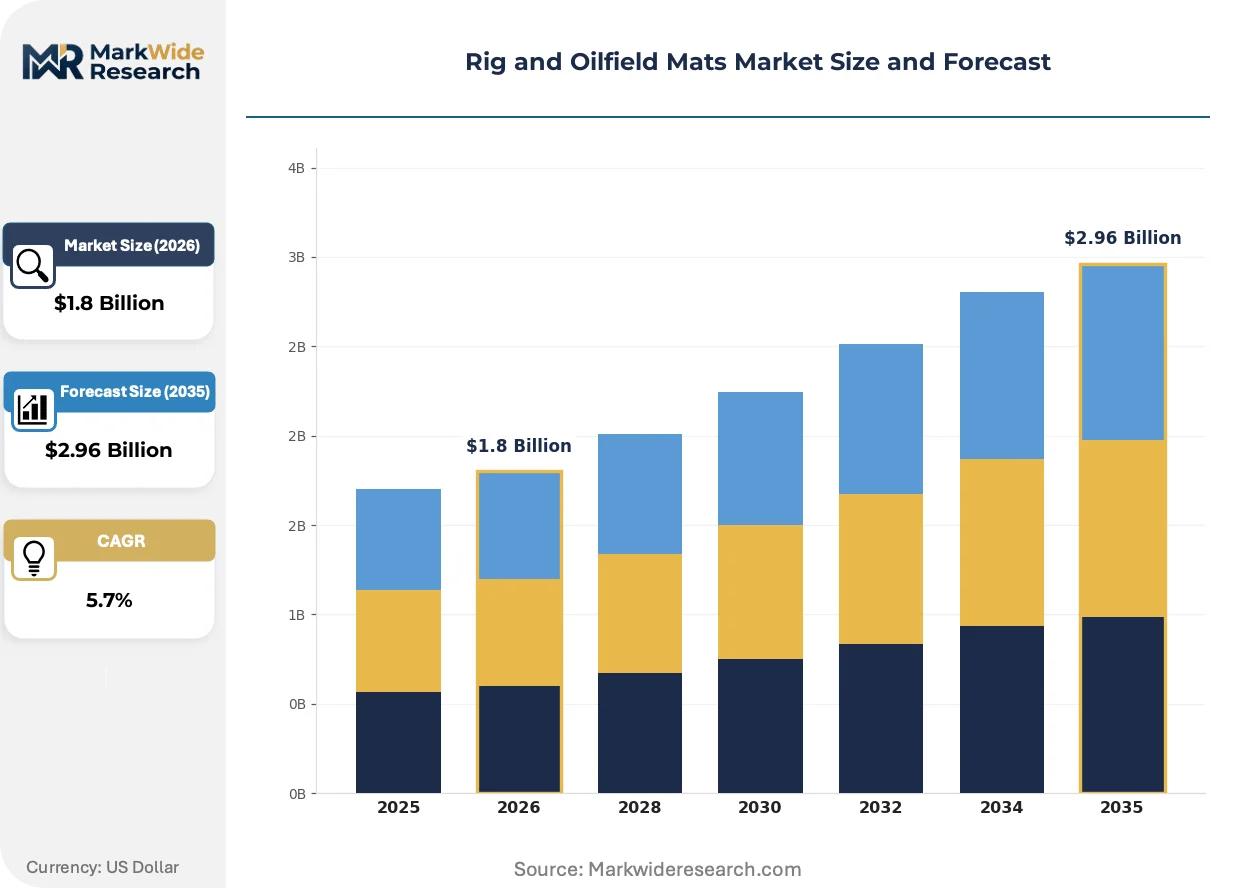
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Mats, Ground Protection Mats, Swamp Mats, Heavy Duty Mats Material: Rubber, Wood, Synthetic, Aluminum Application: Construction, Drilling, Mining, Events End User: Oil & Gas Companies, Construction Firms, Event Organizers, Government Agencies |
| Companies Covered | Newpark Resources, Quality Mat Company, Signature Systems Group, STRAD Energy Services, United Rentals, Dura-Base, Horizon North Logistics, Checkers Safety Group, YAK MAT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rig and Oilfield Mats Market Strategic Shifts
Material science advances and regulatory stringency are converging to displace established procurement patterns. Three developments are restructuring competitive advantage.
Modular composite systems with interlocking HDPE lattice structures are rewriting deployment economics for extended-use pads. Large independent operators in the Delaware Basin are standardizing on 12-foot by 40-foot composite sections that withstand 100-ton crane loads. The technology is compressing replacement cycles from annual to quadrennial intervals.
REACH substance restrictions in Europe are accelerating phasing of creosote-treated timber for cross-border equipment deployment. Industrial users face compliance verification costs for mats entering EU-adjacent North Sea operations. The regulation is redirecting procurement toward certified composite inventory for contractors with international asset mobility.
Short-term rental agreements are displacing capital purchase commitments among mid-size drilling contractors. Fleet operators in the Eagle Ford Shale now offer per-day pricing with maintenance inclusion, transferring utilization risk from end-users to mat providers. This restructuring is most visible among private equity-backed exploration companies with variable rig counts.
Rig and Oilfield Mats Market Segmentation
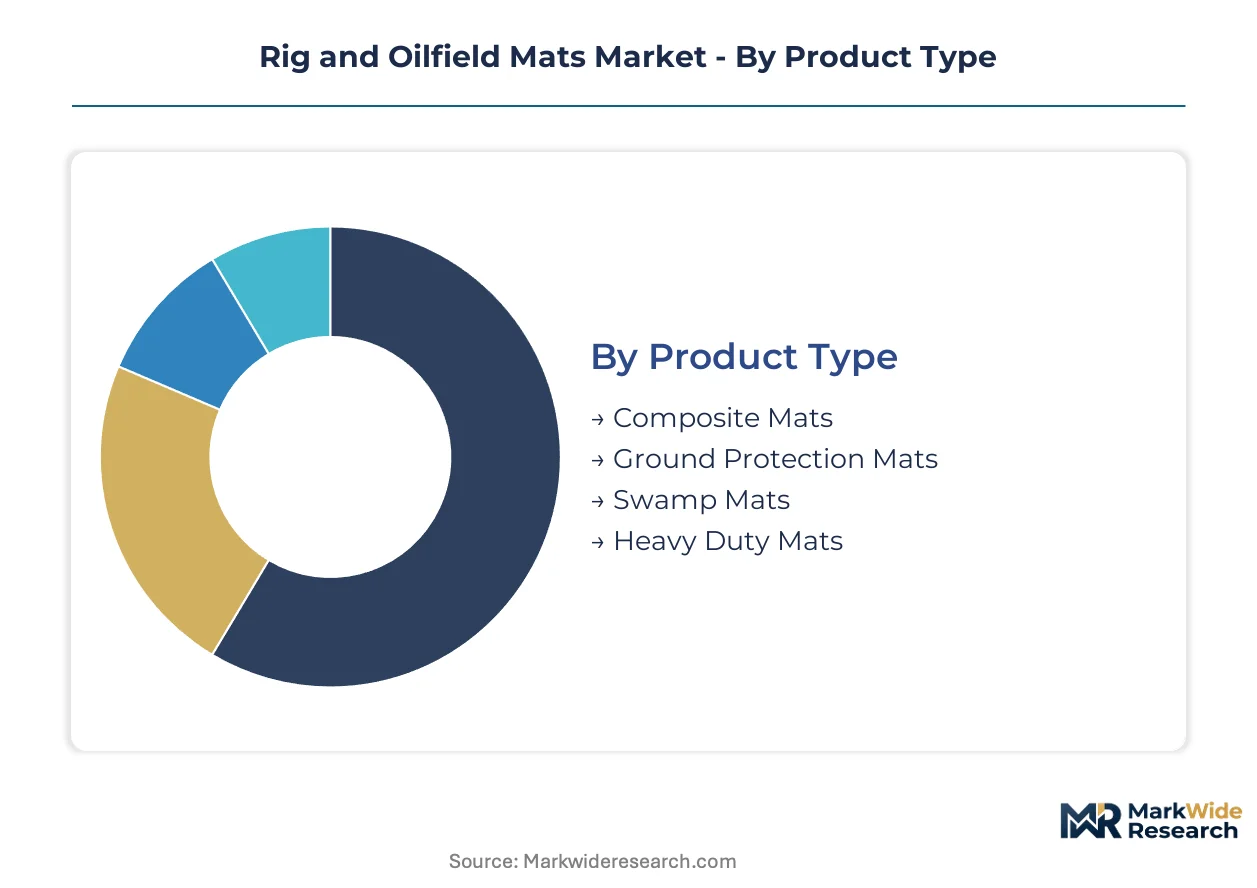
Product differentiation in rig and oilfield mats follows substrate durability requirements and regulatory compliance tiers rather than simple price positioning. Procurement patterns cluster around lifecycle economics and pad cycling intensity, with material selection directly constraining operator liability exposure.
Product Type:
Supply concentration favors manufacturers with integrated composite fabrication capabilities, as HDPE resin processing creates barriers to rapid capacity scaling.
- Composite Mats:Engineered from extruded HDPE lattice structures rated for 100-ton crane loads and 50-plus well cycles. Demand concentrates in the Permian Basin where multi-well pad drilling requires impermeable, reusable substrates under tightened EPA spill-prevention enforcement.
- Heavy Duty Mats:Laminated hardwood or aluminum alloy systems designed for axle loads exceeding 80,000 pounds in extended-use configurations. Procurement runs highest in North Dakota's Bakken formation where freeze-thaw cycling demands superior load distribution.
- Ground Protection Mats:Standardized interlocking panels for temporary access ways and staging areas. Contractors deploy these for rapid mobilization in pipeline construction corridors.
- Swamp Mats:Specialized buoyant platforms for marshland and wetland drilling access. Louisiana coastal operations and Alaska North Slope developments drive niche procurement volumes.
Heavy duty mats absorb the bulk of installed capacity; composite mats are expanding most quickly.
Material:
Cost tier differentiation separates capital-intensive resin systems from commodity timber alternatives, with aluminum occupying a narrow premium niche.
- Synthetic:HDPE and composite resin formulations offering impermeable surfaces and quadrennial replacement cycles. Operators in Texas prioritize synthetic substrates to satisfy BLM surface disturbance mitigation requirements on federal leases.
- Wood:Treated hardwood laminates from southern United States timber networks, retaining cost leadership in single-use applications. Climate-induced harvest variability is constraining availability for spot market purchases.
- Rubber:Recycled tire-derived matting for secondary access ways and environmental containment. Mining contractors in Nevada copper extraction sites specify rubber for high-altitude terrain protection.
- Aluminum:Lightweight alloy panels for helicopter-accessible remote sites where transport weight dictates material choice. Penetration remains limited by cost parity gaps against composite alternatives.
Wood commands the greatest installed base; synthetic materials are climbing the fastest.
Application:
Volume concentration tracks infrastructure spending cycles and hydrocarbon development intensity across onshore basins.
- Drilling:Pad construction and rig mobilization generate the deepest demand pool, with multi-well pad standardization in the Delaware Basin driving composite mat procurement at scale.
- Construction:Pipeline right-of-way preparation and temporary access for renewable energy installations. Federal infrastructure appropriations are widening procurement volumes for load-distributed surface systems.
- Mining:Copper and lithium extraction in Nevada and Arizona requires temporary matting for environmentally sensitive high-altitude terrain. Battery supply chain investments are accelerating site development timelines.
- Events:Temporary flooring for outdoor industrial exhibitions and emergency response staging. This segment remains marginal compared to extractive industry applications.
Drilling absorbs the dominant share of mat deployment; mining is gaining share fastest.
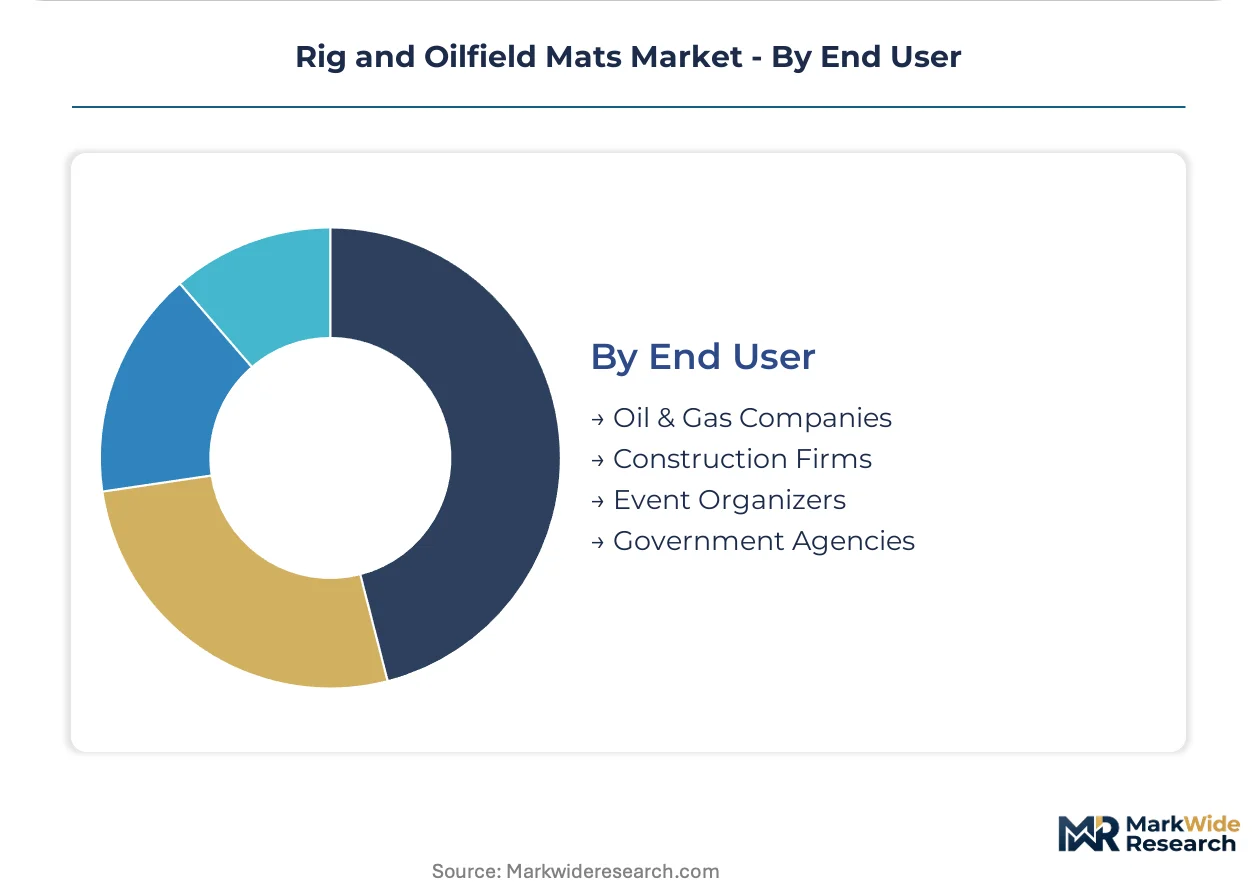
End User:
Customer type determines procurement structure, with capital availability dictating rental-versus-purchase decisions.
- Oil & Gas Companies:Integrated operators and large independents with balance sheet capacity for composite fleet ownership. These entities prioritize lifecycle cost optimization over upfront capital constraints.
- Construction Firms:Infrastructure contractors with project-based matting needs and preference for third-party rental arrangements. Fleet operators capture margin through per-day pricing with maintenance inclusion.
- Government Agencies:Federal land management and emergency response entities with mandated sustainability procurement criteria. BLM lease stipulations require certified load-bearing documentation.
- Event Organizers:Commercial and municipal entities with intermittent, short-duration requirements. This customer type exhibits highest price sensitivity and rental dependency.
Oil and gas companies represent the largest committed capital base; construction firms are shifting fastest toward rental utilization models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for rig and oilfield mats concentrates in North American shale basins where pad construction intensity drives procurement volumes, with secondary clusters emerging in mining corridors of South America and Australia's remote extraction zones.
United States
Multi-well pad drilling in the Permian Basin and Bakken formation generates the deepest demand pool for composite and heavy-duty mat systems. EPA spill-prevention enforcement under the Clean Water Act mandates impermeable substrates, accelerating capital rotation toward reusable HDPE systems. Midland-Odessa anchors procurement activity as Delaware Basin operators standardize on extended-cycle composite deployments.
Canada
Oil sands development in Alberta and Saskatchewan requires specialized matting for seasonal mobilization across muskeg terrain. Federal surface disturbance mitigation guidelines on Crown leases constrain material choices toward certified composite or treated timber with documented load-bearing capacity. Calgary-based energy service companies coordinate fleet logistics for remote northern drilling campaigns.
Australia
Coal seam gas extraction in Queensland and Western Australian iron ore corridors drive temporary access matting requirements. The country's national environmental regulator enforces strict biosecurity protocols for equipment crossing ecologically distinct zones, elevating cleaning and tracking costs for rental operators. Pilbara mining clusters prioritize synthetic substrates for high-tonnage haul road applications.
Brazil
Pre-salt offshore logistics and onshore shale exploration in the Paraná Basin create dual demand vectors for helicopter-portable aluminum mats and extended-use composite systems. The national petroleum regulator mandates surface protection standards for environmentally sensitive Amazon transition zone operations. Rio de Janeiro service hubs coordinate import logistics for specialized matting inventory.
Saudi Arabia
Unconventional gas development in the Jafurah Basin and remote desert drilling campaigns require load-distributed surface systems for sand stabilization. The national oil company's domestic procurement preferences favor suppliers with localized manufacturing or assembly capabilities. Eastern Province industrial zones concentrate fabrication capacity for regional export.
Rig and Oilfield Mats Market Competitive Environment
Capacity expansion dominates the current landscape as composite resin fabricators scale HDPE lattice production to capture multi-well pad standardization trends. The vendor base organizes into three tiers: integrated energy service conglomerates with captive mat fleets, specialized composite manufacturers with proprietary extrusion capabilities, and regional hardwood treaters serving single-use spot markets. Strategic archetypes include backward-integrated resin compounders, rental fleet operators with logistics networks, and niche aluminum fabricators for remote-access applications. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players extending rental service footprints into mining and carbon capture construction corridors.
Among North American integrated service providers, Newpark Resources exemplifies the resin-integration archetype through captive HDPE manufacturing, while Quality Mat Company anchors the hardwood-sourcing tier with southern United States timber network control. Signature Systems Group occupies a position within the specialized heavy-duty design segment. These three entities collectively illustrate how substrate choice and supply chain configuration stratify competitive positioning across the Permian and Bakken demand centers.
| Leading Market Players |
|---|
| Newpark Resources |
| Quality Mat Company |
| Signature Systems Group |
| STRAD Energy Services |
| United Rentals |
| Dura-Base |
| Horizon North Logistics |
| Checkers Safety Group |
| YAK MAT |
| Others |
Value Chain & Pricing Dynamics
Multi-well pad standardization in the Permian Basin is compressing procurement timelines and forcing suppliers to absorb utilization risk through rental restructuring, which in turn squeezes margins on capital-intensive composite manufacturing while elevating price competition among hardwood treaters serving spot markets.
Pricing Analysis
Volume concentration in extended-cycle drilling applications splits margin capture between fleet-owning incumbents and rental intermediaries. Three-tier pricing structure across premium composite, standard heavy-duty, and economy wood tiers reflects certification grade and cycle durability. Cost compression in the wood segment is intensifying because climate-induced harvest variability constrains southern United States timber availability. Mid-size drilling contractors exhibit highest price sensitivity, while integrated operators with balance sheet capacity prioritize lifecycle economics over per-unit rates.
Supply Chain Analysis
Direct-to-drilling-contractor channels handle fleet-scale composite deployments, while third-party rental operators intermediate fragmented construction demand. HDPE resin compounding concentrates in Texas and Louisiana petrochemical corridors, with hardwood sourcing anchored in southern United States timber networks and aluminum fabrication distributed across Midwest industrial zones. Manufacturing draws from ethylene cracker output, treated hardwood laminates, and recycled rubber feedstocks. Single-source vulnerability in HDPE resin supply exposes composite fabricators to upstream petrochemical disruption. Distribution runs through Midland-Odessa supply hubs for Permian Basin demand, Calgary logistics nodes for Canadian oil sands, and Eagle Ford Shale rental depots for variable rig count operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA substrate protection mandates and multi-well pad cycling economics are consolidating procurement power among fleet-scale composite suppliers, forcing smaller hardwood treaters and undifferentiated metal fabricators toward exit or acquisition.
For Market Incumbents: Extend composite manufacturing capacity in Texas petrochemical corridors to capture Delaware Basin standardization trends. Anchor fleet utilization through long-term rental agreements with private equity-backed exploration companies facing variable rig counts. Defend against aluminum substitution in helicopter-accessible remote sites by emphasizing quadrennial replacement cycles against metal's cost parity gaps. For New Entrants and Emerging Players: Modular HDPE lattice systems with interlocking deployment mechanisms offer entry into carbon capture construction corridors where load-distributed surface demand is emerging. Target Nevada and Arizona mining infrastructure for copper and lithium extraction matting, where battery supply chain investments accelerate site development timelines. Pursue biosecurity-compliant cleaning and tracking capabilities as a service differentiator for ecologically distinct drilling zone requirements. For Investors and Strategic Acquirers: The window for entry favors rental fleet operators with logistics networks spanning multiple shale basins. Long-term viability rests on utilization rate management across compressed drilling timelines rather than manufacturing scale alone. Watch EPA enforcement intensity in the Bakken formation as an inflection indicator for accelerated composite substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HDPE Resin Compounding | Captures margin from ethylene cracker output swings while securing supply for Permian Basin fleet expansion. |
| Rental Fleet Utilization Optimization | Transfers cycle risk from mid-size drilling contractors to mat providers through per-day pricing structures. |
| Carbon Capture Construction Corridor Entry | Positions composite systems for pipeline and injection well builds across saline formation regions. |
| Biosecurity Compliance Service Layer | Captures value from cross-contamination protocols imposed by Australia's national environmental regulator. |
| Hardwood Supply Network Consolidation | Defends treated timber positioning against climate-induced harvest variability in southern United States. |
Study Parameters
Document review covered EPA spill-prevention enforcement records, BLM surface disturbance mitigation guidelines, and petrochemical feedstock trade data, complemented by interviews with drilling contractors, composite manufacturing plant managers, and third-party rental fleet operators. Secondary validation drew from SEC filings of integrated energy service providers, customs records of HDPE resin imports, and oilfield equipment procurement databases. Bottom-up well count projections and top-down infrastructure spending estimates were triangulated to ground market sizing.
Segment-level outputs across product type, material substrate, application intensity, and end-user capital structure were generated over the projection horizon. CAGRs were derived from elasticity modeling of drilling activity against mat deployment rates, with inputs including pad construction cycle compression, multi-well pad standardization adoption curves, and regulatory compliance cost pass-through assumptions.
Several conditions sit outside the modeled scope, including abrupt shifts in federal land lease policy, breakthrough displacement of HDPE by alternative resin formulations, and sustained petrochemical supply chain disruptions beyond historical volatility bands. Forecasts reflect documented assumptions about enforcement continuity and substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Oil and Chemical Spill Kits Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Well Testing Services Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market