
 Servo Motors and Drives Market | 2026-2036
Servo Motors and Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Servo Motors and Drives Market Analysis
Digital closed-loop control architectures is fragmenting legacy analog servo ecosystems into modular, software-defined platforms. Siemens anchors European industrial automation through its integrated drive systems portfolio. Yaskawa Electric Corporation dominates precision motion control in robotics and CNC applications. Mitsubishi Electric Corporation leverages its factory automation stack to compete across Asia-Pacific manufacturing corridors.
Servo motors and drives are electromechanical systems that convert electrical signals into precise mechanical motion through closed-loop feedback, typically achieving positioning accuracy within micrometers via encoder resolution and vector control algorithms. Their primary purpose is to deliver controlled torque, velocity, and position in automated machinery where repeatability exceeds human capability. AC servo motors lead installed base across CNC machines and packaging equipment due to superior power density and regenerative braking. Closed-loop technology captures expanding margin pools as end-users prioritize energy recovery and predictive maintenance over basic open-loop configurations. Linear servo motors represent the fastest-growing product type in semiconductor lithography and high-speed conveyor systems where rotary-to-linear mechanical conversion introduces unacceptable backlash.
The IEC 61800-5-2 safety standard and the EU Machinery Directive constrain product design for European market access, forcing drive manufacturers to embed safe torque-off circuitry and functional safety certifications. China's GB/T 12668 series and Japan's JIS C 4003 shape electromagnetic compatibility and efficiency benchmarks across East Asian supply chains. Stakeholders must monitor how regional efficiency mandates and cybersecurity requirements for industrial networks reshape R&D allocation between hardware optimization and embedded software development.
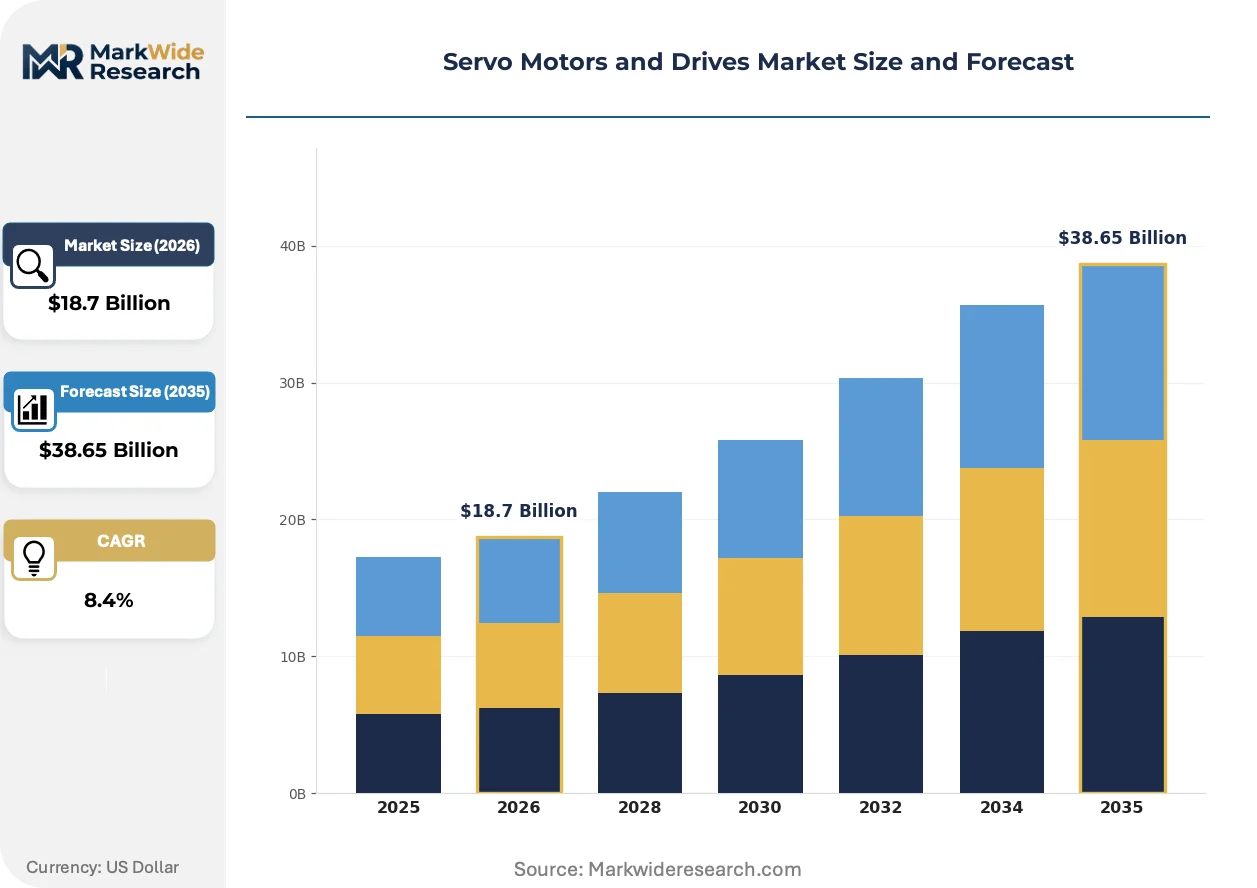
Market Dynamics
Factory automation in automotive assembly lines is accelerating servo adoption across Germany, China, and the United States, compressing replacement cycles from ten-year hardware refresh to software-defined upgrade paths.
Growth Catalysts
- IEC 61800-5-2 Safety Standard:European machinery manufacturers must embed safe torque-off circuitry, forcing drive replacement across installed base and expanding addressable market for certified suppliers.
- Semiconductor Lithography Equipment:Linear servo motors displace ball-screw mechanisms in wafer steppers where nanometer positioning tolerance eliminates mechanical backlash.
- Shenzhen-Nagoya Manufacturing Corridor:East Asian electronics and automotive clusters concentrate demand for high-speed pick-and-place robotics requiring sub-millisecond torque response.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium processing concentrates in China's Inner Mongolia and Jiangxi provinces, exposing motor manufacturers to export quota volatility.
- EU Machinery Directive Compliance Burden:Functional safety certification for STO circuitry extends product development timelines and raises barrier to European market entry.
- AC Induction Motor Substitution:Open-loop variable frequency drives satisfy low-precision conveyor applications at 40-60 percent lower installed cost, capping servo penetration in price-sensitive segments.
Strategic Opportunities
- India PLI Scheme for Manufacturing:Production-linked incentives for electronics and automotive sectors attract servo system suppliers to establish local assembly capacity in Tamil Nadu and Gujarat.
- Predictive Maintenance Convergence:Integration of vibration sensors with edge analytics creates recurring revenue streams through condition-monitoring subscriptions.
- Direct-to-Machine Builder E-Commerce:Configurator platforms bypass traditional distributor markup, capturing margin in mid-volume OEM segments.
Industry Challenges
- Motion Control Firmware Talent Scarcity:Vector control algorithm development requires specialized expertise in field-oriented control mathematics, constraining R&D expansion.
- Legacy Analog Retrofit Complexity:Tachometer-to-encoder signal conversion in aging machine tools demands custom interface engineering, fragmenting project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Servo Motors and Drives Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Servo Motors, DC Servo Motors, Servo Drives, Linear Servo Motors Technology: Open Loop, Closed Loop, Digital, Analog End User: Automotive, Aerospace, Industrial Automation, Robotics Application: CNC Machines, Conveyor Systems, Packaging Equipment, Textile Machinery |
| Companies Covered | Yaskawa Electric Corporation, Mitsubishi Electric Corporation, Siemens, Rockwell Automation, ABB, Schneider Electric, FANUC Corporation, Delta Electronics, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Servo Motors and Drives Market Emerging Trajectories
Digital closed-loop architectures are fragmenting legacy analog servo ecosystems into modular, software-defined platforms where firmware updates displace hardware replacement cycles.
Single-chip motor control SoCs with integrated ARM Cortex-M7 cores are digitizing drive electronics by collapsing gate driver, power factor correction, and safety PLC functions onto unified silicon. Automotive tier-one suppliers adopt these consolidated architectures for electric power steering and brake-by-wire systems. This integration is digitizing supplier margins from discrete component sales toward recurring firmware licensing.
REACH restrictions on hexavalent chromium plating are forcing manufacturers to transition servo motor housings to nickel-tungsten alloy coatings or stainless steel extrusions. Surface treatment suppliers in Germany and Italy are scaling electrochemical deposition capacity to serve industrial motor OEMs. The coating transition compresses supply lead times for European-bound production during qualification periods.
Machine builders are unbundling servo sizing and commissioning services from hardware procurement, purchasing drives through distributor stock programs while contracting motion engineering separately. This bifurcation erodes traditional system integrator margins and shifts technical risk to end-user engineering teams. The unbundling is most advanced in German and Japanese packaging machinery sectors where in-house automation competency exceeds North American benchmarks.
Servo Motors and Drives Market Segmentation
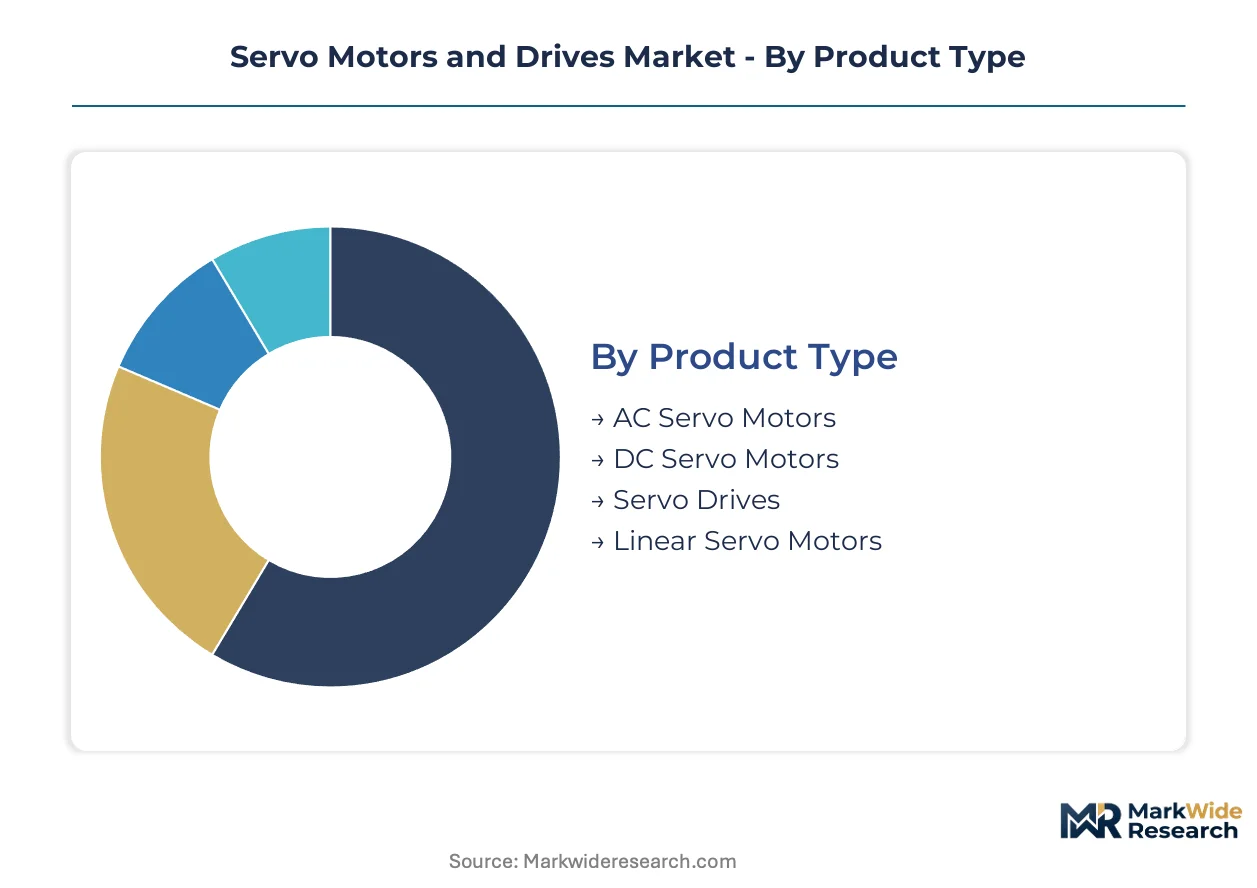
Servo system procurement patterns diverge sharply by motion precision requirements and control architecture maturity. Segment-specific replacement cycles and certification burdens create distinct margin profiles across hardware categories.
Product Type:
AC servo motors turn over on 7-10 year factory automation refresh cycles, while linear servo systems in semiconductor equipment compress replacement to 3-5 years under cleanroom contamination protocols.
- AC Servo Motors:Permanent magnet synchronous designs with vector control achieve power densities exceeding 5 kW/kg in compact frame sizes. Automotive assembly lines in Stuttgart and Shanghai specify these for robotic welding and paint application where regenerative braking recovers 15-30% of kinetic energy.
- Linear Servo Motors:Direct-drive electromagnetic actuation eliminates mechanical transmission losses and backlash in wafer steppers. ASML and Nikon lithography systems in Veldhoven and Kumagaya demand sub-nanometer positioning repeatability that only ironless linear motors deliver.
- DC Servo Motors:Brushed and brushless DC architectures persist in legacy machine tool retrofits and battery-powered mobile robotics where simple torque control suffices.
- Servo Drives:Power electronics modules convert AC mains to variable frequency output with encoder feedback loops; standalone drives enable retrofit of existing induction motors to closed-loop servo performance.
AC servo motors dominate installed base. Linear servo motors are where expansion concentrates.
Technology:
Cost tier stratification separates budget-constrained retrofit applications from greenfield digital deployments where firmware licensing generates recurring revenue.
- Closed Loop:Encoder-based position feedback with PID compensation achieves positioning accuracy within ±1 arc-minute. Packaging machinery OEMs in Bologna and Osaka specify closed-loop drives for high-speed carton erecting where repeatability prevents product damage.
- Digital:ARM Cortex-based drive SoCs integrate motion control, safety PLC, and industrial Ethernet on unified silicon. Siemens and Rockwell automation platforms leverage digital architectures to push firmware updates over-the-air, displacing hardware replacement revenue streams.
- Open Loop:Stepper-derived motion without position verification satisfies low-precision indexing at 40-60% lower installed cost; conveyor applications in bulk material handling tolerate occasional lost steps.
- Analog:Tachometer feedback and ±10V command signals persist in 1990s-era machine tools where encoder retrofit wiring costs exceed drive replacement economics.
Closed-loop systems dominate installed base. Digital architectures are where expansion concentrates.
End User:
Volume concentration varies by sector automation maturity and capital expenditure cyclicality.
- Industrial Automation:Factory-wide motion control networks in process industries and discrete manufacturing represent the largest addressable hardware base. Food and beverage packaging lines in Wisconsin and Bavaria deploy synchronized multi-axis servo systems for continuous-motion cartoning.
- Automotive:Electric vehicle powertrain assembly and battery module handling drive precision motion demand. Tesla's Gigafactory in Nevada and BYD's plants in Shenzhen specify high-torque servo systems for cell stacking and module welding.
- Robotics:Collaborative and industrial robot joints require compact servo motors with integrated harmonic drives; payload-to-weight ratios determine competitive selection.
- Aerospace:Flight control surface actuation and fuel valve positioning demand DO-178C certified servo electronics with 10^-9 failure probability per flight hour.
Industrial automation dominates installed base. Automotive electrification is where expansion concentrates.
Application:
Motion complexity and throughput requirements segment procurement specifications across machinery categories.
- CNC Machines:Multi-axis milling centers and turning lathes require spindle servo synchronization with nanometer-scale contouring accuracy. DMG Mori and Mazak machine tools in Nagoya and Chicago specify high-bandwidth current loops for mold and die machining.
- Packaging Equipment:Continuous-motion cartoners and flow wrappers demand electronic cam profiling and flying shear synchronization. Bosch and Krones machinery in Germany deploy servo-driven sealing jaws that maintain 600+ cycles per minute.
- Conveyor Systems:Accumulation and sortation conveyors use distributed servo drives for zone control; e-commerce fulfillment centers in Pennsylvania and Hebron specify regenerative drives for energy recovery on downhill sections.
- Textile Machinery:Warping and weaving machines require precise tension control through dancer-arm feedback; Italian and Turkish textile OEMs specify specialized servo drives with constant torque across speed ranges.
CNC machines dominate installed base. Packaging equipment is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision motion control systems to German automotive assembly lines and Chinese electronics manufacturing clusters, creating a triangular trade flow that concentrates servo technology transfer across three continents.
United States
Tesla's Gigafactory in Nevada and legacy automotive plants in Michigan drive demand for high-torque servo systems in battery module handling and robotic welding applications. The Department of Energy's industrial efficiency programs incentivize regenerative drive adoption. Detroit and Austin manufacturing corridors concentrate servo system integration for electric vehicle powertrain assembly.
Germany
Bosch and Krones packaging machinery OEMs in Bavaria specify synchronized multi-axis servo systems for continuous-motion cartoning at 600+ cycles per minute. The EU Machinery Directive and IEC 61800-5-2 safety standard mandate safe torque-off circuitry in new installations. Stuttgart's automotive cluster anchors robotic paint application and assembly line automation demand.
China
BYD's plants in Shenzhen and CATL's battery facilities in Ningde compress servo replacement cycles through software-defined upgrade paths rather than hardware refresh. GB/T 12668 efficiency standards shape electromagnetic compatibility benchmarks across East Asian supply chains. The Pearl River Delta electronics manufacturing corridor concentrates demand for high-speed pick-and-place robotics.
Japan
ASML and Nikon lithography systems in Kumagaya demand sub-nanometer positioning repeatability from ironless linear servo motors in wafer steppers. METI's industrial automation initiatives accelerate digital closed-loop adoption across precision manufacturing. The Nagoya-Tokyo manufacturing corridor hosts FANUC and Yaskawa production facilities serving global robotics demand.
Servo Motors and Drives Market Vendor Landscape
Channel-controlling players compete with product-specialist players for dominance in servo system procurement. The market structures around three tiers: diversified industrial conglomerates with integrated automation portfolios, precision motion specialists with deep robotics expertise, and component-focused suppliers serving retrofit applications. Strategic moves concentrate on firmware licensing transitions and safety certification pre-emption in European markets.
Among diversified industrial conglomerates, Siemens anchors European market presence through its integrated drive systems portfolio. Yaskawa Electric Corporation and Mitsubishi Electric Corporation represent the precision motion specialist archetype, with the former dominating robotics applications and the latter leveraging factory automation stacks across Asia-Pacific manufacturing corridors.
| Leading Market Players |
|---|
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Siemens |
| Rockwell Automation |
| ABB |
| Schneider Electric |
| FANUC Corporation |
| Delta Electronics |
| Bosch Rexroth |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet export quota volatility from China's Inner Mongolia and Jiangxi provinces compresses margin spreads between premium permanent-magnet servo systems and ferrite-based economy alternatives, while simultaneously forcing drive manufacturers toward dual-sourcing strategies that elongate qualification timelines and fragment procurement economics.
Pricing Analysis
The technology-generation pricing gap separates legacy analog servo drives from ARM Cortex-based digital platforms and emerging single-chip SoC architectures. Pricing stratifies across premium certified systems with IEC 61800-5-2 safe torque-off circuitry, standard closed-loop configurations for general automation, and economy open-loop drives for conveyor applications. Cost compression in the economy tier intensifies because AC induction motor variable frequency drives satisfy low-precision indexing at 40-60 percent lower installed cost. Automotive OEMs in Stuttgart and Shanghai exhibit the least price sensitivity, prioritizing regenerative energy recovery and predictive maintenance integration over upfront hardware cost.
Supply Chain Analysis
Export-control regimes on high-performance servo drive firmware and encoder signal processing IP limit technology flows between Japanese precision motion specialists and Chinese system integrators. Neodymium and dysprosium processing concentrates in China, with complementary winding equipment and power semiconductor fabrication anchored in Germany and Japan. Supply chain risk centers on single-source vulnerability for sintered rare earth magnets, where Inner Mongolia's Bayan Obo mine feeds 60 percent of global separated heavy rare earth output. Distribution runs through authorized distributor networks in European packaging machinery corridors and direct-to-machine-builder e-commerce platforms in North American mid-volume OEM segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo system procurement is shifting toward platform economics where firmware licensing and over-the-air update capabilities determine vendor lock-in, driven by Siemens and Rockwell automation platforms unbundling hardware from motion engineering services.
For Market Incumbents: Entrench position through backward integration into rare earth magnet recycling and secondary sourcing partnerships outside China's Jiangxi province, while accelerating IEC 61800-5-2 certification pre-emption to raise barriers against emerging digital-native competitors. Capture recurring revenue streams by embedding edge analytics for predictive maintenance subscriptions within drive firmware, displacing pure hardware replacement cycles. For New Entrants and Emerging Players: Establish a beachhead in India's Tamil Nadu and Gujarat electronics manufacturing corridors, where PLI scheme incentives attract servo system assembly capacity with reduced incumbent saturation. Target the linear servo motor segment for semiconductor lithography equipment, where ASML and Nikon lithography systems demand sub-nanometer positioning repeatability that rewards specialized engineering over integrated portfolio breadth. Deploy configurator platforms that bypass traditional distributor markup in mid-volume OEM segments. For Investors and Strategic Acquirers: The market sits at a firmware-transition phase that favors precision motion specialists with deep vector control algorithm expertise over diversified industrial conglomerates with hardware-centric margins. Five-to-ten year viability hinges on R&D allocation between embedded software development and hardware optimization. Target acquisition archetypes include single-chip motor control SoC developers and condition-monitoring analytics platforms. The signal to watch is the rate of unbundling between servo sizing services and hardware procurement in German packaging machinery sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Recycling | Reduces quota exposure from China's Inner Mongolia processing concentration while securing sustainable feedstock. |
| IEC 61800-5-2 Safety Certification Pre-emption | Accelerates European market access before EU Machinery Directive enforcement tightens compliance windows. |
| Single-Chip Motor Control SoC Development | Collapses gate driver and safety PLC functions onto unified silicon, digitizing margins toward firmware licensing. |
| Predictive Maintenance Platform Integration | Creates recurring revenue through vibration sensor edge analytics bundled with drive hardware. |
| Direct-to-Machine-Builder E-Commerce Launch | Bypasses distributor markup in mid-volume OEM segments where in-house automation competency exceeds North American benchmarks. |
Methodological Framework
A standing panel of motion control firmware engineers, automotive Tier 1 supplier procurement managers, packaging machinery OEM technical directors, and semiconductor equipment integration specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with plant engineers at Stuttgart and Shenzhen manufacturing clusters and aftermarket service heads at German distributor networks. Secondary validation drew from IEC 61800-5-2 certification registries, SEC 10-K filings of listed automation conglomerates, customs data on rare earth magnet trade flows, and METI industrial automation initiative disclosures. Bottom-up unit economics triangulated against top-down market sizing from factory automation capital expenditure tracking.
Scenario-bracketing anchored the analytical framework, with volume and value outputs stress-tested across conservative, baseline, and acceleration cases over the projection horizon. Segmentation modeling incorporated product type, control architecture maturity, end-user automation sophistication, and application motion complexity. CAGRs derived from replacement cycle compression analysis and software-defined upgrade path adoption curves. Industry-specific forecast inputs included rare earth magnet price volatility indices and cleanroom contamination protocol-driven replacement schedules for linear servo systems.
Sensitivities concentrate around export quota volatility for neodymium and dysprosium, cybersecurity mandate enforcement for industrial Ethernet-connected drives, and the pace of analog-to-digital retrofit economics in aging machine tool installed bases. Forecasts reflect documented assumptions on technology substitution rates and regional efficiency mandate implementation timelines. Material shifts in China's rare earth processing policy or IEC functional safety certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Global Sliding Vane Air Motor Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Gear Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
North America Hazardous Location Motors Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
United States DC Motor Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Europe Tank Insulation Market