
 Global Low Voltage Motors Market | 2026-2036
Global Low Voltage Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Voltage Motors Market Intelligence
The integration of on-board variable frequency drives (VFDs) directly into motor casings is tilting the market toward intelligent, networked motor systems. Siemens AG leads in developing integrated drive systems for industrial automation. ABB Ltd. leverages its extensive portfolio in robotics and process control to embed its motors in high-value applications. WEG S.A. competes on manufacturing scale and a strong presence in the Americas.
Low voltage motors are electric rotating machines designed to operate at voltages up to 1000V AC. These devices convert electrical energy into mechanical motion, serving as the primary movers in a vast array of industrial and commercial equipment. While traditional AC induction motors constitute the largest product segment by volume, brushless DC motors are gaining share due to superior efficiency and control. Within applications, demand from HVAC systems and pumps for water treatment facilities drives significant replacement and upgrade cycles.
Efficiency mandates like the EU's Ecodesign Regulation and US Department of Energy standards set stringent performance floors for motors sold in those markets. Similarly, China's GB standards for energy efficiency are pushing local and international manufacturers to upgrade their product lines. The critical decision for motor manufacturers now centers on balancing the higher cost of premium efficiency components against the market access granted by regulatory compliance.
Market Dynamics
The imperative to meet escalating energy efficiency standards, such as the EU's Ecodesign Directive and China's GB standards, is the central force shaping the low voltage motor market, compelling a shift toward more complex and costly designs.
Growth Catalysts
- Ecodesign Mandates:Regulations in the European Union and the United States set stringent minimum efficiency performance standards (MEPS), forcing the replacement of older, less efficient motors with premium efficiency models like IE3 and IE4 in industrial applications.
- Industrial Automation:Investment in automated material handling, robotics, and process control systems, especially within manufacturing facilities in China, directly increases the unit volume demand for precision low voltage motors.
- HVAC System Upgrades:The global expansion of commercial and residential building stock drives significant demand for low voltage motors used in fans, pumps, and compressors within modern heating, ventilation, and air conditioning systems.
Market Restraints
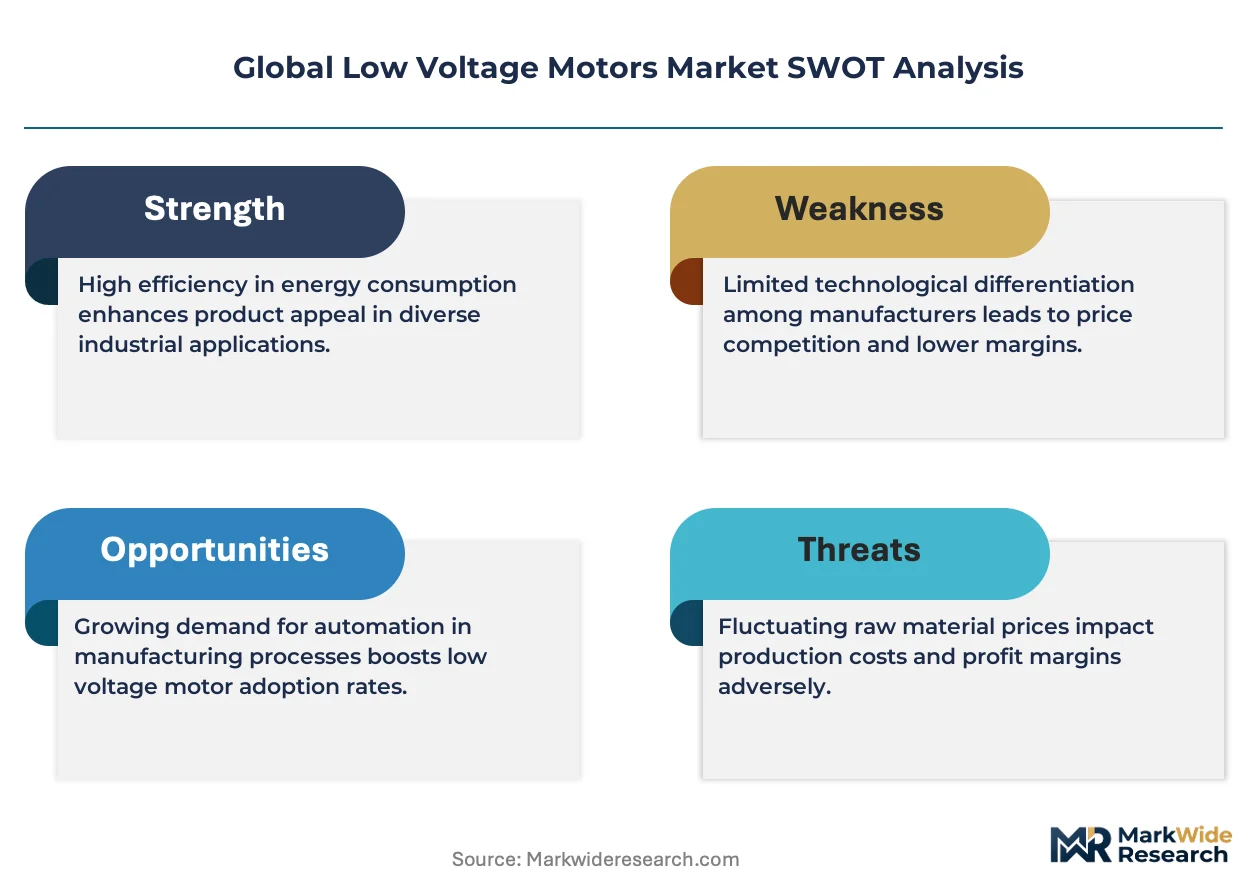
- Input Cost Volatility:The price of raw materials, particularly copper for windings and electrical steel for laminations, exposes motor manufacturers to significant margin pressure and complicates long-term pricing strategies.
- High Initial Investment:The premium cost of high-efficiency motors, such as brushless DC or permanent magnet types, acts as a barrier to adoption for small and medium-sized enterprises in price-sensitive emerging economies.
- Component Supply Concentration:A reliance on a limited number of suppliers in Asia for critical electronic components, including power semiconductors and microcontrollers for VFDs, creates potential supply chain vulnerabilities.
Strategic Opportunities
- Integrated Drive Systems:The development of motors with on-board variable frequency drives (VFDs) opens new applications in smart manufacturing and industrial IoT, where networked control and diagnostics are essential.
- Water Infrastructure Projects:Government-funded initiatives to upgrade and expand water and wastewater treatment facilities in countries like India and Brazil create sustained demand for motors to power pumps and aeration systems.
- Electrification of Off-Highway Vehicles:The transition toward electric and hybrid powertrains in agricultural, construction, and mining equipment presents a new market for ruggedized low voltage motors for auxiliary functions.
Industry Challenges
- Legacy System Integration:Integrating intelligent motors into existing factory floors with older, proprietary control systems creates significant technical complexity and implementation costs for end-users.
- Skilled Technician Scarcity:A shortage of maintenance personnel and engineers with the combined mechanical, electrical, and software expertise to service and troubleshoot integrated motor-drive systems hampers after-sales support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Voltage Motors Market |
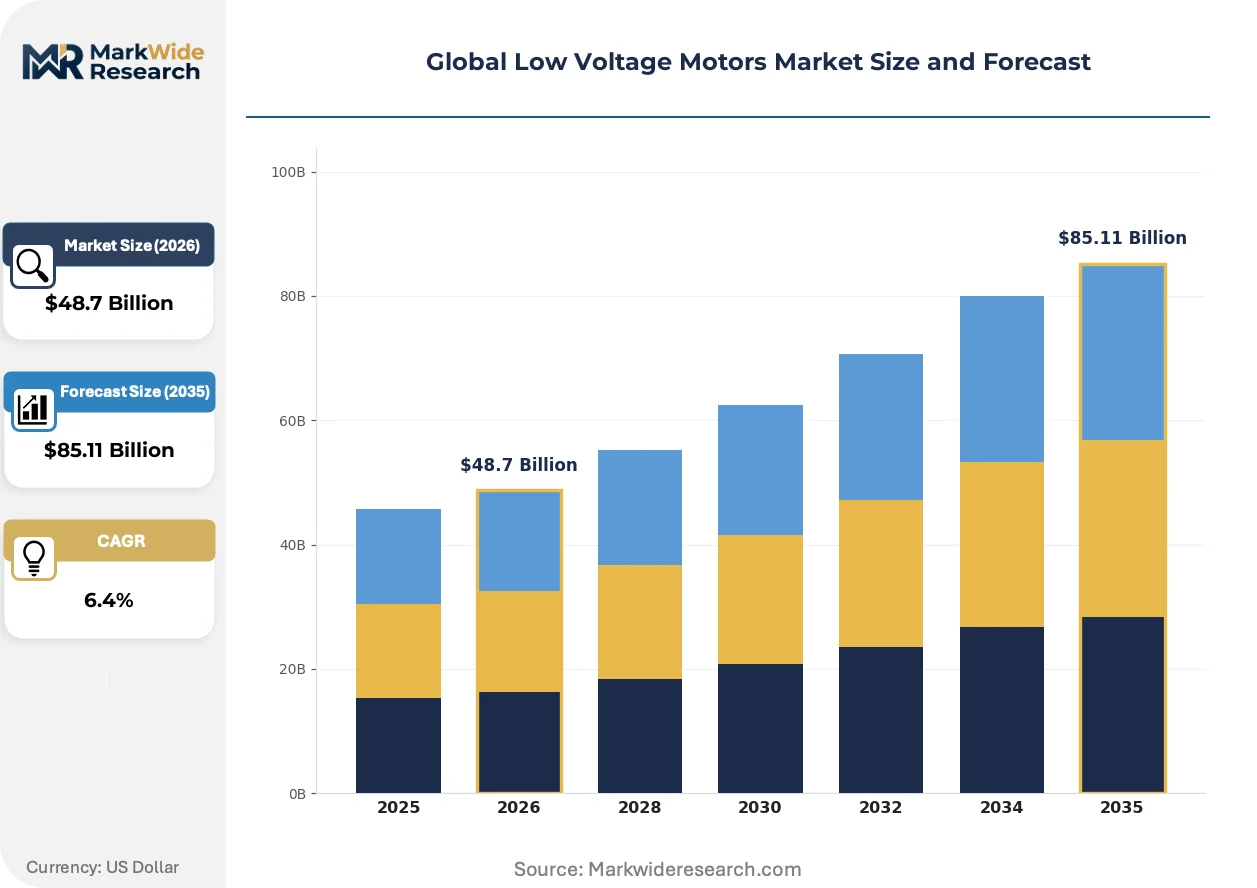
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
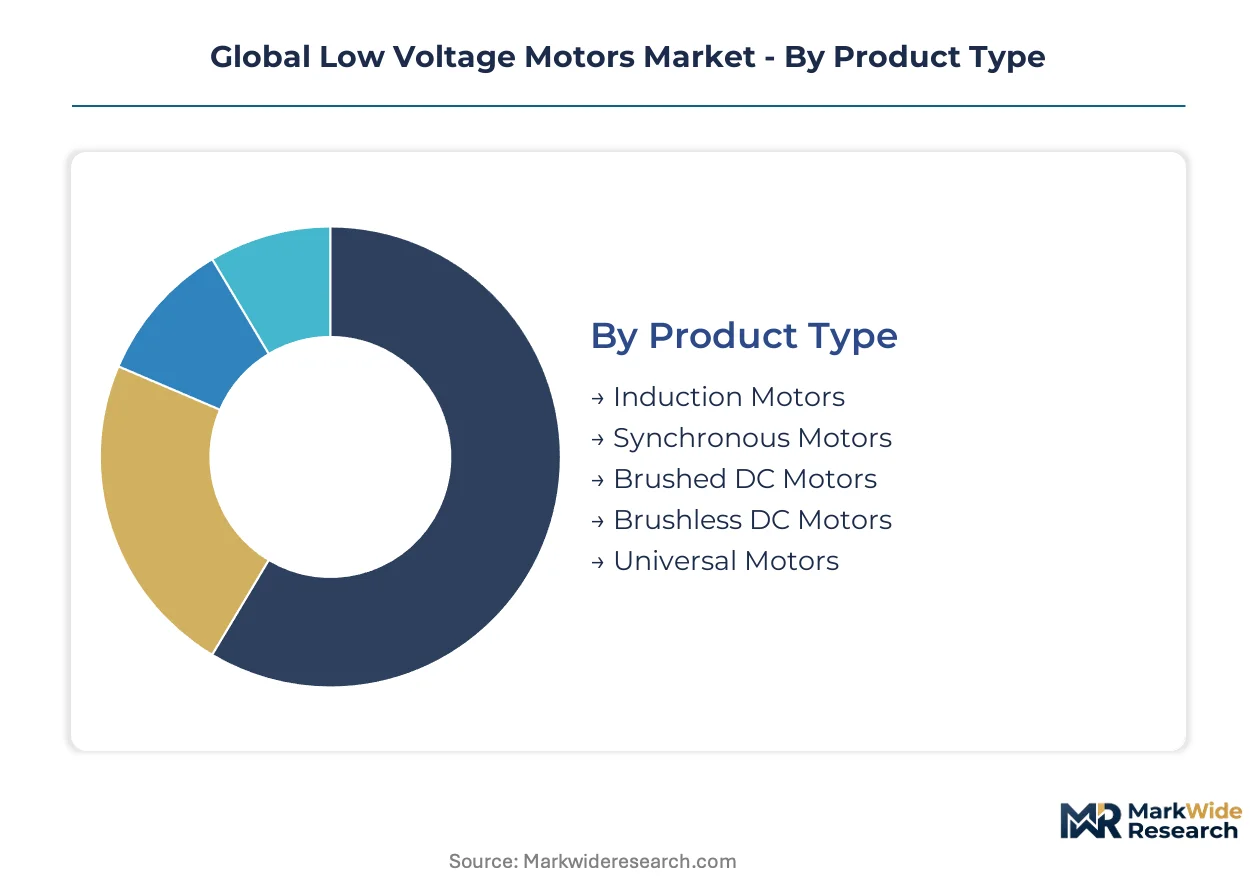
| Segmentation | Product Type: Induction Motors, Synchronous Motors, Brushed DC Motors, Brushless DC Motors, Universal Motors Technology: AC Motors, DC Motors, Servo Motors, Stepper Motors, Shaded Pole Motors, Hysteresis Motors Application: Pumps, Compressors, HVAC Systems, Material Handling, Machine Tools, Textile Equipment End User: Manufacturing Plants, Construction Firms, Agriculture Operators, Mining Companies, Water Treatment Facilities |
| Companies Covered | WEG S.A., Rockwell Automation, Inc., ABB Ltd., Toshiba Corporation, Mitsubishi Electric Corporation, Siemens AG, Schneider Electric SE, Regal Rexnord Corporation, Nidec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Voltage Motors Market Strategic Shifts & Innovations
The convergence of advanced power electronics and embedded software is transforming the low voltage motor from a simple electromechanical component into an intelligent, data-generating node within larger industrial systems. This evolution underpins a market-wide shift toward system-level efficiency and control.
Sensorless vector control technology uses sophisticated algorithms to calculate rotor speed and position without requiring a physical feedback device. This method is gaining widespread adoption in industrial applications like conveyors and fans, where precise speed regulation is necessary but cost is a primary concern. The software-based approach is hybridizing the simple AC induction motor with the high-performance dynamic response characteristics typically associated with more expensive servo motor systems.
The US Department of Energy's efficiency standards for electric motors create a mandatory performance floor for products sold in the United States. This regulation directly influences design choices, pushing manufacturers to adopt better materials and more advanced winding techniques to meet or exceed the specified efficiency levels. The commercial HVAC and industrial pump segments are most affected, as equipment OEMs must ensure their integrated products comply with the motor-specific rules.
Original equipment manufacturers (OEMs) are increasingly specifying motors based on total cost of ownership (TCO) rather than initial purchase price. This change in procurement behavior favors motors that feature integrated diagnostics and predictive maintenance capabilities, disrupting traditional distribution channels that compete primarily on unit cost. This trend is most visible in the European machine-building industry, where equipment uptime and serviceability are critical competitive differentiators.
Global Low Voltage Motors Market Segmentation
The low voltage motors market exhibits diverse segmentation reflecting varied performance needs, operational environments, and end-user requirements. Understanding these distinct segments is crucial for manufacturers to align product development with specific demand drivers. This analysis provides a structured overview of the market's key divisions.
Product Type:
The product type segmentation highlights the varying replacement cycles and technological lifespans across motor designs.
- Induction Motors:These rugged and cost-effective devices convert electrical energy into mechanical motion through electromagnetic induction, forming the backbone of industrial machinery. Demand for these motors is concentrating in heavy manufacturing sectors in China, driven by ongoing factory automation projects.
- Brushless DC Motors:Featuring permanent magnets and electronic commutation, these motors offer superior efficiency, precise speed control, and extended operational life compared to their brushed counterparts. Their demand is rising in HVAC systems across European commercial buildings, due to stringent energy efficiency mandates.
- Synchronous Motors:Operating at a constant speed synchronized with the AC supply frequency, these motors find use in applications requiring precise timing and power factor correction.
- Brushed DC Motors:These traditional motors utilize carbon brushes for commutation, offering simple control and cost-effectiveness for intermittent or low-power applications.
- Universal Motors:Capable of operating on both AC and DC power, these motors are characterized by their high starting torque and compact size, commonly found in portable power tools.
Induction Motors dominate the installed base. Brushless DC Motors is where expansion concentrates.
Technology:
The technology segmentation differentiates motors based on their underlying electrical principles and control mechanisms, influencing their suitability for various applications.
- AC Motors:These motors operate on alternating current, encompassing induction and synchronous types, and are widely deployed across industrial and commercial settings due to their robustness and availability. Demand for AC motors is concentrating in the upgrade of industrial infrastructure in India, driven by government-backed manufacturing initiatives.
- DC Motors:Utilizing direct current, these motors offer excellent speed control and high starting torque, making them suitable for applications requiring variable speed operation and battery power. Their demand is increasing in electrification projects for off-highway vehicles in North America, driven by emissions reduction targets.
- Servo Motors:Designed for precise position, velocity, and torque control, servo motors are critical components in robotics and automated manufacturing systems.
- Stepper Motors:These motors move in discrete steps, providing accurate positioning without feedback, commonly used in printing equipment and CNC machines.
- Shaded Pole Motors:Simple and inexpensive AC motors, often used in low-power, continuous-duty applications like small fans and pumps.
- Hysteresis Motors:Known for their smooth, quiet operation and constant speed, these motors are typically found in precision instruments and audio recording devices.
The shift towards DC Motors reflects the growing need for energy efficiency and precise control in modern systems.
Application:
The application segmentation categorizes motors by their primary function within different equipment and systems, reflecting diverse operational demands.
- HVAC Systems:Motors in heating, ventilation, and air conditioning systems power fans, blowers, and compressors in commercial and residential buildings. Demand for these motors is concentrating in new building construction in Southeast Asia, driven by rapid urbanization.
- Pumps:Low voltage motors are essential for various pumping applications, including water supply, wastewater treatment, and industrial fluid transfer. Their demand is increasing in government-funded water infrastructure projects in Brazil, driven by public health and environmental regulations.
- Material Handling:Motors are integrated into conveyors, hoists, and automated guided vehicles for efficient movement of goods in logistics and manufacturing.
- Compressors:These motors drive air and gas compressors used in industrial processes, refrigeration, and pneumatic systems.
- Machine Tools:Precision motors are vital for operating lathes, milling machines, and grinders in metalworking and fabrication industries.
- Textile Equipment:Motors power spinning, weaving, and knitting machinery, requiring reliable and often variable speed operation in textile manufacturing.
Specific regulatory mandates drive adoption in HVAC Systems and Pumps, promoting high-efficiency models.
End User:
The end user segmentation groups motor demand based on the primary industry or sector utilizing the equipment, revealing distinct purchasing patterns and scale requirements.
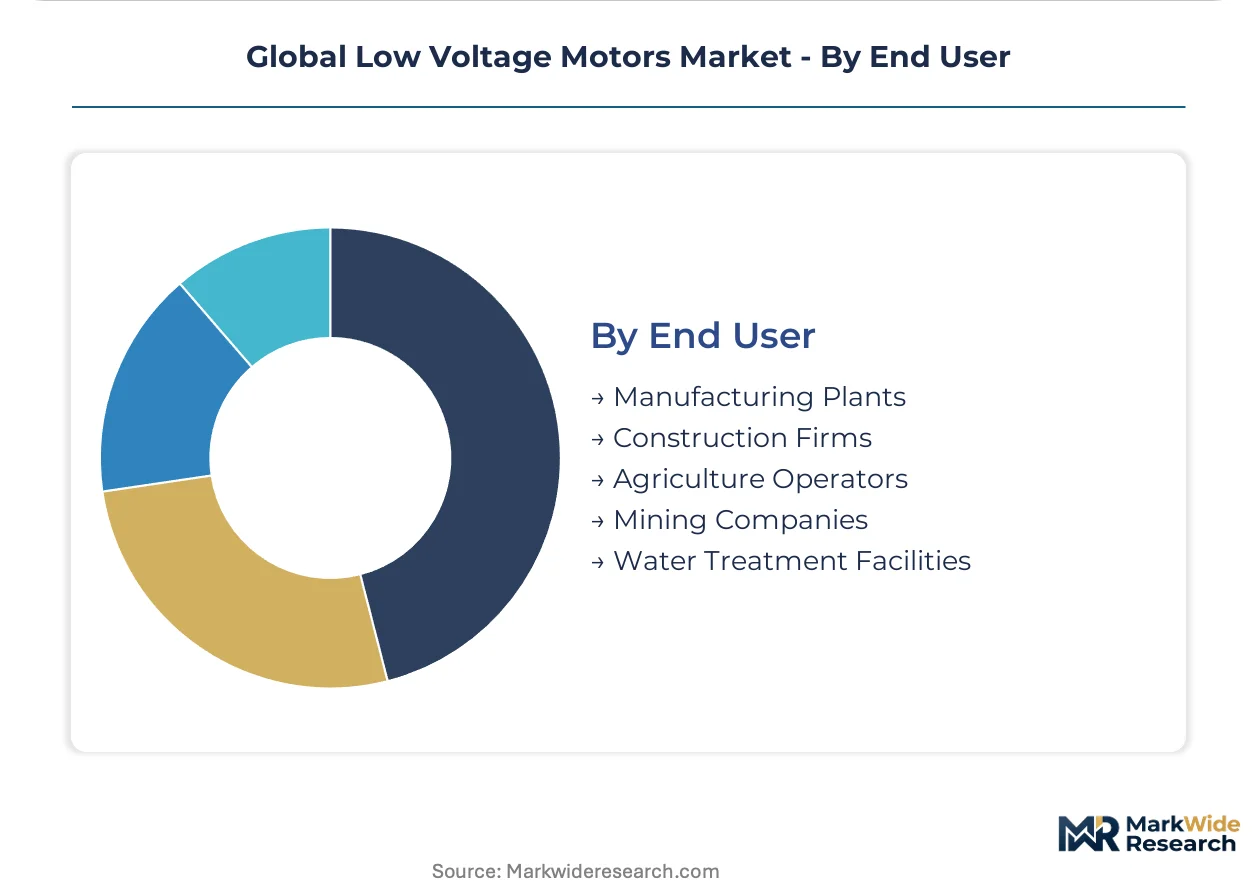
- Manufacturing Plants:These facilities integrate low voltage motors into production lines, robotics, and automation equipment for various industrial processes. Demand from manufacturing plants is concentrating in automotive and electronics production in Germany, driven by advanced automation investments.
- Water Treatment Facilities:Motors are critical for operating pumps, mixers, and aeration systems in municipal and industrial water and wastewater treatment processes. Their demand is increasing in public sector infrastructure upgrades across the United States, driven by environmental compliance requirements.
- Construction Firms:Motors power equipment such as concrete mixers, drills, and lifting machinery on construction sites.
- Agriculture Operators:Motors are used in irrigation systems, grain handling equipment, and ventilation for livestock facilities.
- Mining Companies:Motors drive conveyors, crushers, and ventilation systems in surface and underground mining operations, requiring robust designs.
Digital transformation initiatives are accelerating demand across Manufacturing Plants, particularly for intelligent motor systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers supply low voltage motors to global industrial markets, particularly those influenced by stringent European efficiency mandates. This market is expanding due to diverse regional demands and regulatory pressures. Significant investments in infrastructure and automation projects drive motor adoption across continents.
China
China's industrial automation initiatives drive significant demand for low voltage motors, especially in material handling solutions. The GB standards for energy efficiency compel local manufacturers to upgrade product lines and adopt more advanced designs. Advanced manufacturing clusters in the Yangtze River Delta concentrate demand for precision motors in robotics and automated production lines.
Germany
German automotive and electronics production facilities require advanced low voltage motors for automation and precision control. The EU's Ecodesign Directive mandates high efficiency standards, influencing motor design and procurement across industries. Bavaria's high-tech industrial equipment sector is a focal point for intelligent motor system integration within machinery building.
United States
United States public sector infrastructure upgrades create sustained demand for efficient low voltage motors, particularly in water treatment facilities. The US Department of Energy's efficiency standards set performance floors for industrial and commercial applications. Equipment OEMs in Midwestern industrial hubs integrate compliant motors into their HVAC and pump systems.
India
India's industrial infrastructure upgrades, supported by government-backed manufacturing initiatives, drive motor demand across various sectors. The PLI scheme encourages domestic production and technology adoption for components like electric motors. Industrial development zones in Gujarat are experiencing concentrated demand for robust low voltage motors in new factory setups.
Brazil
Brazil's government-funded water infrastructure projects create a strong demand for low voltage motors in pumps and aeration systems. Environmental regulations, alongside public health policies, prioritize efficient and reliable motor solutions for municipal utilities. São Paulo's industrial and water treatment facilities are key centers for motor deployment and replacement cycles.
Global Low Voltage Motors Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in the low voltage motors sector. The market structure exhibits a tiered consolidation, with large industrial conglomerates alongside niche technology providers. Strategic archetypes include integrated solution providers, mass-scale manufacturers, and regional specialists. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Global industrial conglomerates like Siemens AG and ABB Ltd. exemplify the integrated solution provider archetype, leveraging extensive portfolios in automation and process control. Siemens AG, a German industrial giant, anchors high-value industrial automation applications, emphasizing intelligent motor systems. ABB Ltd., a Swiss-Swedish multinational, occupies a position in robotics and advanced drive systems for high-value applications. Manufacturers with significant scale and diversified portfolios, such as WEG S.A., represent the mass-scale manufacturing archetype. This Brazilian company maintains a strong presence in the Americas, competing on manufacturing scale and broad product offerings across various industrial segments.
| Leading Market Players |
|---|
| WEG S.A. |
| Rockwell Automation, Inc. |
| ABB Ltd. |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Schneider Electric SE |
| Regal Rexnord Corporation |
| Nidec Corporation |
| Others |
Cost & Logistics Intelligence
Advanced manufacturing clusters in the Yangtze River Delta, with their concentrated production capacity, directly influence the global pricing power of standard low voltage motors. This regional supply dynamic creates a baseline for market competition across various product segments.
Pricing Analysis
The pricing gap between traditional AC induction motors and premium efficiency brushless DC models remains significant. Transactional per-unit pricing dominates, with differentiation stemming from efficiency certification levels like IE4 and integrated VFD capabilities. Pricing softness affects conventional models due to manufacturing scale, while input cost volatility from copper and electrical steel creates upward pressure. Small and medium-sized enterprises in emerging economies exhibit higher price sensitivity compared to European machine builders focused on total cost of ownership.
Supply Chain Analysis
Export controls on advanced semiconductor technologies could disrupt the intricate supply chains for integrated motor systems. Supply concentration for low voltage motors centers heavily in China and other Asian manufacturing hubs. Key dependencies include copper for windings, electrical steel for laminations, and power semiconductors for variable frequency drives. Single-source vulnerability for these critical electronic components poses a structural risk, while distribution predominantly occurs through direct sales to large OEMs and regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers a strong service-attach opportunity, as the monetization of integrated diagnostics and predictive maintenance solutions expands faster than hardware sales. This shift emphasizes recurring revenue streams over one-time product transactions.
For Market Incumbents: Build ecosystem control by expanding integrated motor-drive offerings with proprietary software and cloud connectivity. This strategy mitigates the threat from niche technology providers and reinforces market position against rising raw material costs. Investing in R&D for sensorless control algorithms and securing efficiency certifications like IE5 are critical levers. Expanding aftermarket service networks ensures long-term customer retention.
For New Entrants and Emerging Players: Pursue specialized applications within the electrification of off-highway vehicles and government-funded water infrastructure projects. The standard AC induction motor segment in basic industrial upgrades presents a penetrable entry point, particularly in regions with less stringent efficiency mandates. A go-to-market angle focusing on cost-effective, high-efficiency brushless DC motors bundled with basic digital monitoring services provides differentiation.
For Investors and Strategic Acquirers: Long-term, this sits as an industrial modernization and efficiency upgrade play because global regulatory mandates and automation trends drive sustained demand. Acquisition targets include specialized firms developing embedded VFDs or advanced motor control software, alongside regional service providers with strong customer relationships. The signal to watch is the accelerated adoption rate of integrated intelligent motor systems in new industrial builds.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Integrated Motor-Drive Solutions | Enhances system efficiency and enables advanced industrial IoT applications for end-users. |
| Expand Aftermarket Service Offerings | Creates recurring revenue streams and strengthens customer loyalty through predictive maintenance. |
| Invest in Advanced Material Science | Improves motor efficiency and reduces reliance on volatile raw material markets. |
| Target Water Infrastructure Projects | Captures sustained demand driven by public health and environmental compliance regulations. |
| Forge Software Partnership Ecosystems | Accelerates the integration of intelligent motors into broader industrial automation platforms. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive understanding of the market dynamics. Primary interviews with plant engineers, procurement managers, HVAC system integrators, and motor design engineers were triangulated with secondary research. Data sources included EU Ecodesign Directive documents, US Department of Energy reports, China GB standards, and industrial automation publications, ensuring a robust bottom-up and top-down validation.
Volume and value projections were calibrated against historical market performance and macroeconomic indicators across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from projected unit shipments and average selling prices throughout the forecast period, informed by industrial production indices and building construction starts.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or industrial CAPEX would shift the trajectory of motor demand. Forecasts reflect assumptions regarding geopolitical trade tensions and the stability of raw material supply chains. Material shifts in efficiency mandates or the cost of critical electronic components would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Crude Heater Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Asia-Pacific Induction Motor Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Power Scraper Market
Industrial Motors
Industrial Motor Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Seamless Steel Gas Cylinders Market