
 Europe Hazardous Location Motors Market | 2026-2036
Europe Hazardous Location Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hazardous Location Motors Market Foresight
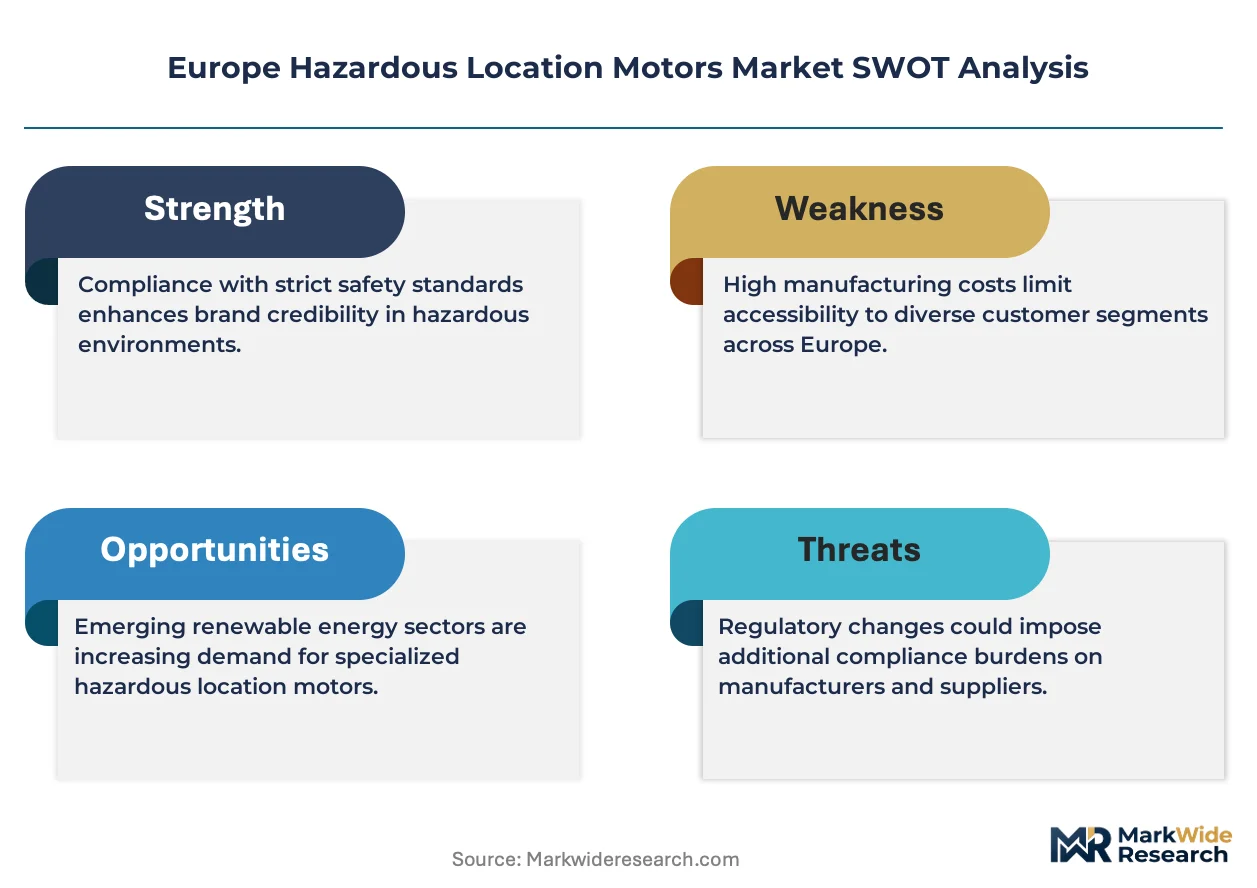
The gap between premium certified motors and basic commodity units is realigning procurement patterns across European industrial buyers. ABB Ltd leverages its ATEX-certified manufacturing footprint to anchor premium positioning in oil and gas applications. Siemens AG competes through integrated digital motor monitoring systems that extend service intervals in chemical plants. WEG Industries dominates mid-power ratings by controlling distribution channels across Southern Europe.
Hazardous location motors are enclosed electrical machines engineered to prevent ignition of flammable gases, vapors, or combustible dusts through flameproof enclosures, increased safety designs, or pressurized construction, typically operating in temperature classes T1 through T6 with ingress protection ratings from IP55 to IP66. These motors serve explosion-risk environments where standard industrial equipment would trigger catastrophic facility damage. Explosion-proof AC motors lead unit shipments across the European installed base, while synchronous motor variants represent the fastest-growing technology tier as refineries pursue energy efficiency targets. Oil and gas end users concentrate margin pools in above-200 HP power ratings where replacement cycles generate premium pricing.
The EU ATEX Directive 2014/34/EU mandates equipment conformity assessment for all motors deployed in Zone 0, 1, 2, 20, 21, and 22 hazardous areas, while IECEx certification provides mutual recognition across member states and reduces redundant testing burdens. ECHA's REACH restrictions on flame-retardant substances are forcing redesigns of motor insulation systems and enclosure coatings. Stakeholders must monitor how the EU Green Deal's industrial emissions benchmarks reshape motor efficiency minimums and retirement timelines for legacy installed equipment.
Market Dynamics
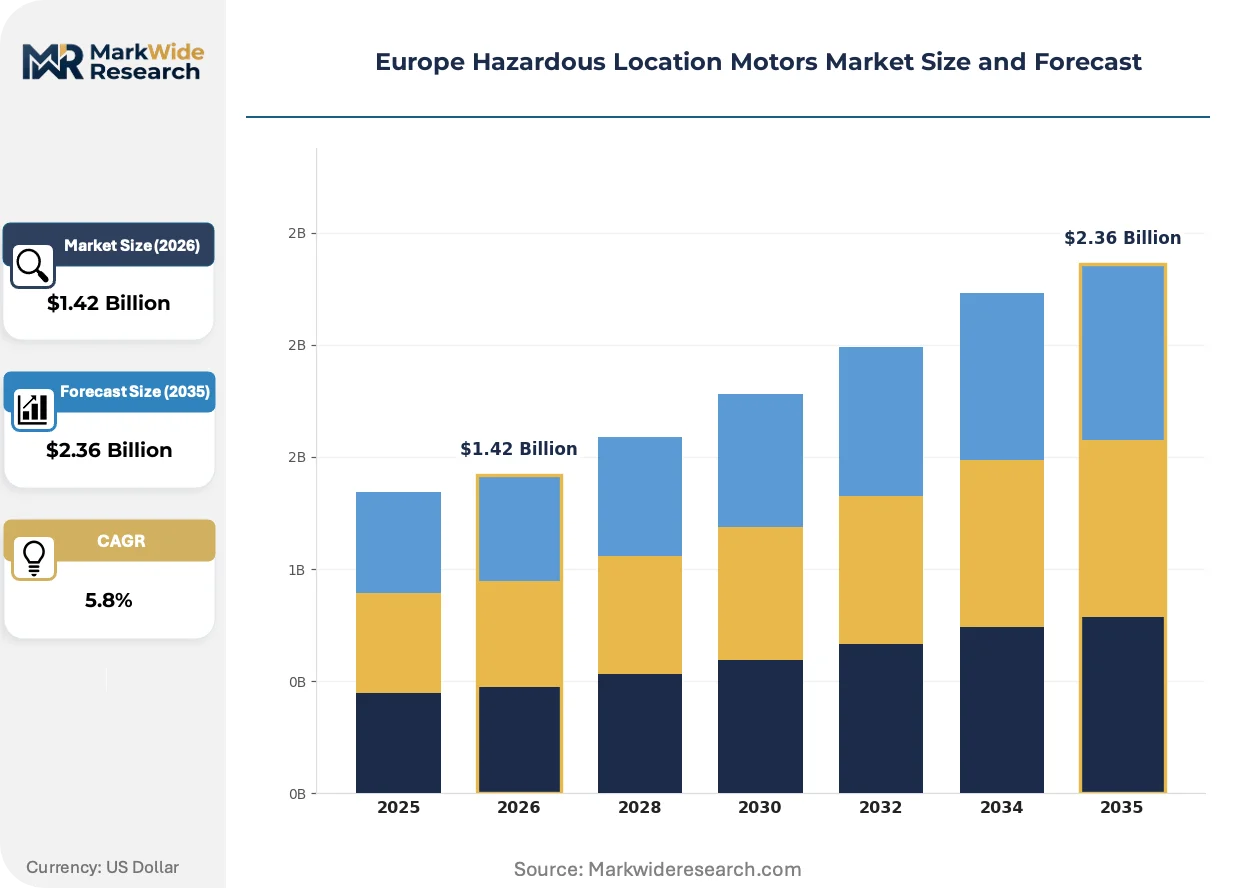
The replacement wave across aging chemical processing infrastructure is compressing procurement cycles, while ATEX Directive compliance costs widen the competitive moat between certified manufacturers and commodity suppliers. This structural tension is redistributing margin pools toward vertically integrated producers with captive testing facilities.
Growth Catalysts
- EU ATEX Directive enforcement:Mandatory conformity assessment for Zone 0-2 and Zone 20-22 equipment is disqualifying uncertified suppliers from refinery and petrochemical tenders.
- REACH substance restrictions:ECHA's flame-retardant limitations are accelerating redesign cycles for motor insulation systems, creating replacement demand for compliant next-generation units.
- Energy efficiency mandates:The EU Green Deal's industrial emissions benchmarks are forcing early retirement of legacy IE2-class motors in favor of IE4 and IE5 synchronous variants.
Market Restraints
- Copper and rare-earth magnet volatility:Permanent magnet supply concentration in China creates input cost instability for high-efficiency motor laminations.
- Testing infrastructure scarcity:ATEX and IECEx certification capacity concentrates in Germany and the United Kingdom, extending lead times for new market entrants.
- Extended asset lifecycles:Flameproof enclosures rated for 20-25 year service intervals delay replacement demand in mature oil and gas installations.
Strategic Opportunities
- Polish and Romanian chemical expansion:Greenfield petrochemical investments in Eastern Europe lack established supplier relationships, opening distribution channel contests.
- Digital motor monitoring convergence:Integration of vibration sensing and thermal imaging with ATEX-certified enclosures enables predictive maintenance service contracts.
- Net-zero industrial clusters:EU Innovation Fund financing for carbon-neutral refineries mandates highest-tier efficiency equipment, premiumizing synchronous motor specifications.
Industry Challenges
- ATEX Notified Body capacity constraints:Certification queue backlogs extend product launch timelines by 8-14 months for complex pressurized motor designs.
- Legacy system interoperability:Retrofitting digital monitoring onto existing flameproof installations requires custom engineering without standardized communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hazardous Location Motors Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: AC Motors, DC Motors, Explosion-Proof Motors, Synchronous Motors Power Rating: Up to 50 HP, 51-100 HP, 101-200 HP, Above 200 HP End User: Oil & Gas, Chemical Processing, Mining, Pharmaceutical Installation Type: Fixed Installation, Portable Installation, Mounting Solutions, Integrated Systems |
| Companies Covered | ABB Ltd, Rockwell Automation, Emerson Electric Co., WEG Industries, Siemens AG, Stainless Motors, Inc., Dietz Electric Co., Inc., Nidec Motor Corporation, Brook Crompton, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hazardous Location Motors Market Shifts & Advancements
Synchronous permanent magnet motors are displacing induction architectures across European hazardous location applications, while regulatory pressure on embodied carbon intensifies material selection scrutiny. Three developments are restructuring competitive positioning.
Permanent magnet synchronous technology is expanding into the 50-200 HP power band historically dominated by squirrel-cage induction designs. Chemical processors in the Netherlands and Belgium are specifying these units for continuous-duty pumps and compressors. The technology is compressing energy consumption benchmarks and shortening payback periods for efficiency-driven retrofits.
ECHA's REACH restrictions on halogenated flame retardants are compelling reformulation of motor winding varnishes and enclosure powder coatings. Manufacturers must resubmit technical files for existing ATEX certificates when altering insulation chemistry. German and French testing houses report surge in recertification applications for legacy product lines.
Refinery operators are consolidating vendor relationships around full-lifecycle service agreements that bundle motor supply with predictive maintenance analytics. Traditional equipment distributors face disintermediation as manufacturers establish direct monitoring service arms. The shift is most visible in North Sea oil and gas platforms where remote diagnostics reduce offshore maintenance crew deployments.
Europe Hazardous Location Motors Market Segmentation
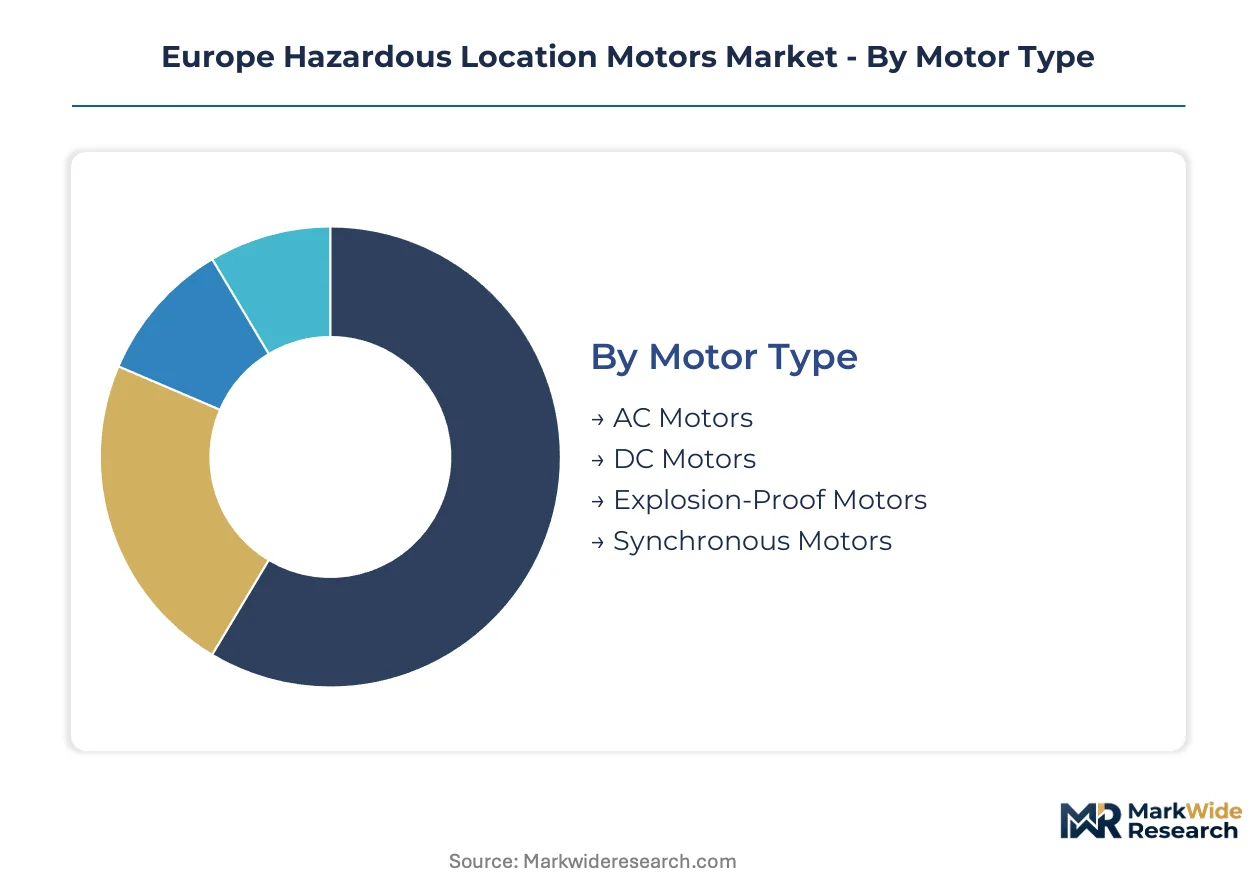
Segmentation in the Europe Hazardous Location Motors Market reveals how procurement priorities diverge across power ratings, installation constraints, and regulatory exposure zones. Buyers in German chemical clusters prioritize ATEX-certified synchronous units for energy efficiency compliance, while North Sea operators demand flameproof architectures in high-horsepower brackets.
Motor Type:
Certification tier and efficiency grade drive purchasing decisions across European industrial buyers, with ATEX Directive compliance costs widening the gap between premium synchronous architectures and commodity induction alternatives.
- AC Motors:Squirrel-cage induction designs dominate the installed base across European refineries and petrochemical plants. Demand concentrates in the 50-200 HP range where Dutch and Belgian chemical processors seek reliable continuous-duty operation for pumps and compressors under Zone 1 certification requirements.
- Synchronous Motors:Permanent magnet synchronous architectures are displacing induction designs in efficiency-sensitive applications. German and French refineries specify these units for above-200 HP compressors to meet EU Green Deal emissions benchmarks, with payback periods compressing as energy costs escalate.
- Explosion-Proof Motors:Flameproof enclosures with Ex d certification serve Zone 1 and Zone 2 environments across oil and gas platforms.
- DC Motors:Wound-field and permanent magnet DC variants retain niche demand in mining conveyors and drilling rigs requiring precise speed control.
Volume sits with AC Motors; growth tilts toward Synchronous Motors.
Power Rating:
Application scale and replacement cycle timing determine margin capture, with premium pricing concentrating where asset longevity and certification complexity intersect.
- Above 200 HP:Large-frame synchronous and induction motors serve main process compressors and critical pump trains in North Sea platforms and German refinery complexes. Oil and gas operators in the United Kingdom concentrate procurement here, accepting 20-25 year service intervals that delay replacement but generate substantial revenue per unit when retrofits occur.
- 101-200 HP:Mid-range explosion-proof units balance capital cost against efficiency gains in continuous chemical processing duty. French and Italian petrochemical sites specify these ratings for reactor agitators and extruder drives where ATEX Zone 1 certification is mandatory.
- 51-100 HP:Standardized flameproof motors serve secondary process equipment across Eastern European chemical expansion projects.
- Up to 50 HP:Compact increased-safety designs populate auxiliary systems and ventilation equipment in confined hazardous areas.
Margins concentrate in Above 200 HP; procurement velocity is accelerating fastest in 101-200 HP.
End User:
Regulatory exposure severity and asset replacement urgency shape demand patterns across European industrial verticals, with chemical processing leading current procurement cycles.
- Chemical Processing:Continuous-duty pump and compressor applications in ATEX Zone 1 environments drive specification of IE4 and IE5 synchronous motors. Demand is intensifying across German, Dutch, and Belgian clusters as operators retire aging IE2-class fleets ahead of EU Green Deal compliance deadlines.
- Oil & Gas:Offshore platforms and onshore terminals require flameproof and pressurized motor designs certified for explosive atmospheres. United Kingdom North Sea operators concentrate procurement in above-200 HP ratings where vendor consolidation around full-lifecycle service agreements is restructuring supplier relationships.
- Pharmaceutical:Cleanroom-compatible hazardous location motors serve solvent handling and API manufacturing in Ireland and Switzerland.
- Mining:Dust-ignition-proof motors for Zone 20-22 applications support extraction operations in Poland and Sweden.
Procurement volume favors Chemical Processing; contract value expansion is steepest in Oil & Gas.
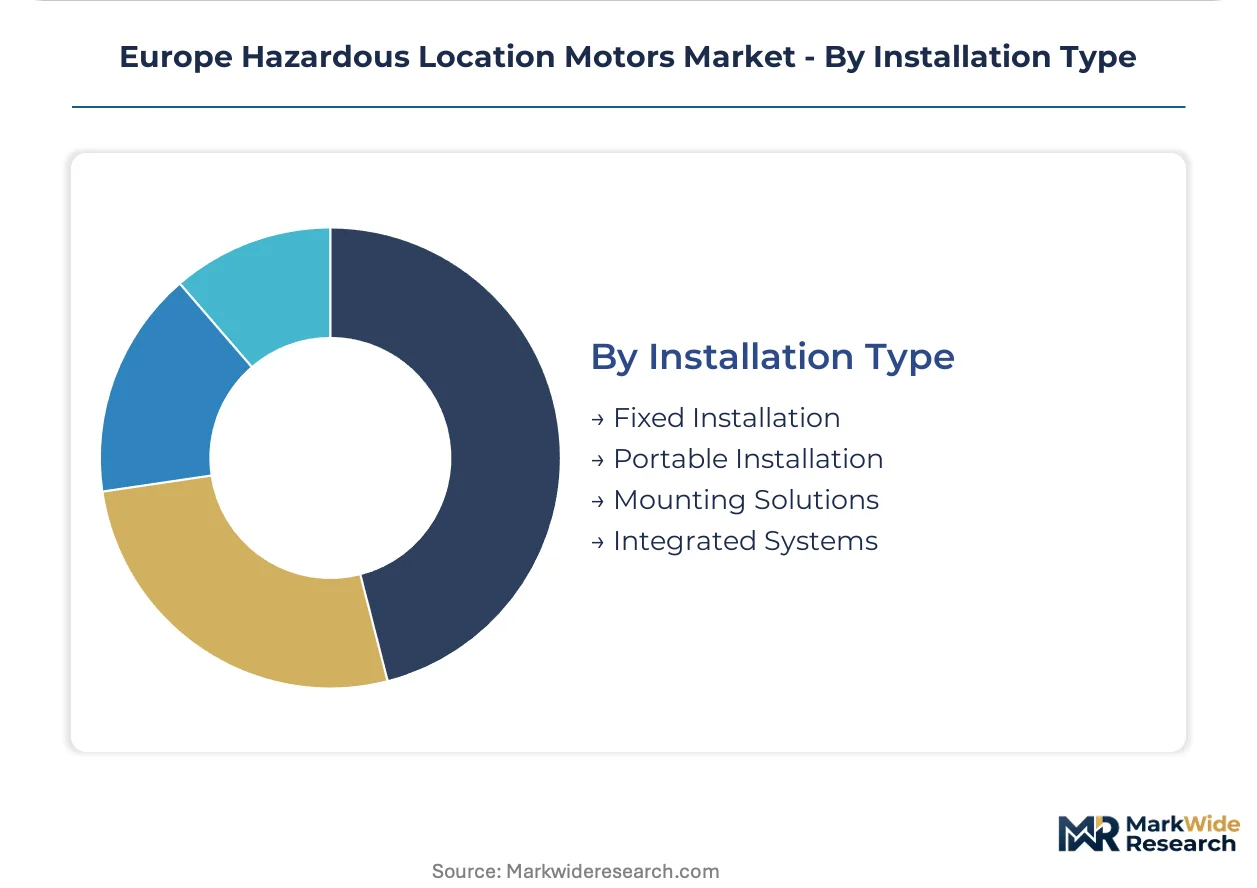
Installation Type:
Deployment flexibility and integration depth determine specification requirements, with fixed infrastructure dominating capital-intensive process industries while portable solutions serve maintenance and emergency applications.
- Fixed Installation:Permanently mounted flameproof and increased-safety motors anchor production lines in refineries and chemical plants. German and United Kingdom facilities standardize on these configurations for critical rotating equipment where ATEX certification continuity across 20-year asset lifecycles is non-negotiable.
- Integrated Systems:Motor-drive packages with embedded digital monitoring and ATEX-certified variable frequency drives are gaining specification in greenfield Dutch and Belgian chemical investments. These configurations compress commissioning timelines and simplify compliance documentation for ECHA REACH substance tracking.
- Portable Installation:Mobile explosion-proof units support turnaround maintenance and temporary process modifications.
- Mounting Solutions:Custom baseplate and coupling arrangements address legacy equipment retrofit requirements.
Fixed Installation commands current volume; Integrated Systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical cluster drives ATEX-certified motor demand across Northwest Europe, with replacement cycles accelerating as Dutch processors modernize aging pump infrastructure ahead of EU Green Deal deadlines.
Germany
Ruhr Valley refineries and Bavarian chemical parks specify IE5 synchronous motors for compressor retrofits. The Bundesministerium für Wirtschaft und Klimaschutz enforces industrial efficiency benchmarks that disqualify legacy IE2 equipment from tender eligibility. Ludwigshafen's BASF complex anchors procurement volume for above-200 HP flameproof units.
United Kingdom
North Sea platform operators concentrate demand in high-horsepower synchronous architectures for gas compression duty. The Health and Safety Executive mandates ATEX compliance verification through UKCA marking post-Brexit transition. Aberdeen's oilfield services corridor channels specification authority toward full-lifecycle service contracts bundling motor supply with remote diagnostics.
France
Normandy and Provence petrochemical sites drive specification of integrated motor-drive packages with embedded digital monitoring. The Autorité de Sûreté Nucléaire et de Radioprotection extends hazardous area oversight to adjacent chemical processing zones. Dunkirk's industrial port zone attracts greenfield investments specifying IE4-class synchronous units for extruder applications.
Netherlands
Antwerp-Rotterdam chemical corridor processors replace aging induction fleets with permanent magnet synchronous designs for continuous pump duty. The Dutch Emissions Authority enforces industrial CO2 benchmarks that compress payback calculations for efficiency upgrades. Moerdijk's chemical cluster standardizes on ATEX Zone 1 certified units with predictive maintenance integration.
Poland
Płock and Gdańsk petrochemical expansion projects create distribution channel contests among motor suppliers lacking established Eastern European relationships. The Polish Office of Technical Inspection implements EU ATEX Directive conformity assessment through notified bodies in Warsaw and Kraków. Pomeranian Special Economic Zone greenfield sites specify mid-power explosion-proof motors for reactor agitator applications.
Europe Hazardous Location Motors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European hazardous location motors landscape, with vertically integrated manufacturers commanding premium positioning through captive ATEX testing facilities. The vendor base stratifies around certification tier, efficiency grade, and service integration depth. Three archetypes dominate: full-lifecycle service providers, mid-power rating specialists, and digital monitoring integrators. Competitive moves concentrate on backward integration into permanent magnet supply chains and geographic expansion into Eastern European chemical growth corridors.
Among Germany-based industrial conglomerates, Siemens AG and ABB Ltd exemplify the integrated-service archetype, bundling motor supply with predictive maintenance platforms. WEG Industries represents the mid-power specialist position, while Rockwell Automation anchors the digital convergence tier.
| Leading Market Players |
|---|
| ABB Ltd |
| Rockwell Automation |
| Emerson Electric Co. |
| WEG Industries |
| Siemens AG |
| Stainless Motors, Inc. |
| Dietz Electric Co., Inc. |
| Nidec Motor Corporation |
| Brook Crompton |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ATEX-certified synchronous units and commodity induction motors manifests in pricing power concentration among German and UK testing houses, while supply chain configurations bifurcate around captive magnet sourcing versus spot-market lamination procurement. Premium pricing for Zone 1-rated permanent magnet architectures reflects both conformity assessment scarcity and rare-earth supply concentration, compressing margins for distributors lacking direct manufacturer relationships.
Pricing Analysis
Value-based pricing anchored to energy throughput savings dominates IE4 and IE5 synchronous motor specifications, with German chemical processors accepting 40-60% capital premiums against 3-year efficiency payback guarantees. Price differentiation rests on ATEX certification tier and integrated digital monitoring bundling, with Zone 0-rated pressurized designs commanding substantial premiums over Zone 2 increased-safety alternatives. Cost compression in mid-power induction ratings intensifies as Eastern European buyers prioritize first-cost minimization over lifecycle efficiency, rendering the 51-200 HP band most price-sensitive while above-200 HP synchronous architectures remain least elastic due to vendor consolidation around full-lifecycle service contracts.
Supply Chain Analysis
Refurbishment flows for flameproof enclosures and stator rewinding services concentrate in Germany, the United Kingdom, and the Netherlands, extending asset lifecycles and delaying new unit procurement. Manufacturing draws from Chinese rare-earth magnet supply, German copper winding facilities, and Italian foundry castings for explosion-proof housings. Single-source vulnerability in permanent magnet laminations creates structural risk given export restriction exposure, while distribution runs through authorized ATEX-certified distributors with mandatory technical training credentials rather than general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet synchronous technology is displacing induction architectures across European hazardous location applications, compressing replacement cycles for legacy IE2-class fleets ahead of EU Green Deal compliance deadlines.
For Market Incumbents: Deploy captive ATEX testing infrastructure to extend certification lead times for challengers, while accelerating backward integration into permanent magnet supply chains to offset Chinese export volatility. Siemens AG and ABB Ltd anchor defensive positioning through integrated digital monitoring platforms that embed switching costs, insulating against mid-power specialists encroaching from Southern European distribution channels. For New Entrants and Emerging Players: Direct-to-plant digital sales channels bypass established distributor relationships in Polish and Romanian greenfield chemical investments where incumbent presence remains underdeveloped. Target mid-power explosion-proof ratings for reactor agitator applications in Pomeranian Special Economic Zone projects, leveraging IECEx mutual recognition to compress conformity assessment timelines versus full ATEX notified body queues. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing ATEX-certified manufacturing footprints and established Eastern European distribution given EU Innovation Fund financing acceleration for carbon-neutral refinery clusters. Long-term viability hinges on synchronous motor technology transition completion and rare-earth supply diversification. Monitor ECHA REACH substance restriction expansion for halogenated flame retardants as inflection indicator for insulation system redesign cycles and associated recertification revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Supply | Captive rare-earth sourcing insulates German manufacturers from Chinese export quota volatility. |
| ATEX Notified Body Capacity Expansion | UK and German testing house additions compress 8-14 month certification queues for complex pressurized designs. |
| Digital Monitoring Platform Integration | Siemens AG and Rockwell Automation bundle predictive analytics with motor supply to disintermediate distributors. |
| Eastern European Distribution Channel Establishment | Greenfield Polish and Romanian petrochemical investments lack incumbent supplier relationships. |
| IE5 Synchronous Motor Portfolio Expansion | EU Green Deal emissions benchmarks disqualify legacy IE2 equipment from tender eligibility. |
Research Methodology
Document review covered ATEX Directive implementation guidelines, IECEx certification databases, and ECHA REACH substance restriction filings, complemented by interviews with plant maintenance directors at German chemical clusters, procurement leads at UK North Sea operators, aftermarket service heads at motor distributors, and technical directors at notified bodies in Germany and the United Kingdom. Secondary validation drew from EU industrial emissions benchmarking reports, customs trade data for motor imports, and SEC filings of listed electrical equipment manufacturers. Bottom-up unit demand estimates triangulated against top-down energy efficiency mandate compliance projections.
Historical replacement cycle patterns cross-referenced against stakeholder panel input on procurement timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include motor type, power rating bracket, end-use vertical, ATEX zone classification, and regional regulatory cluster. CAGRs derived from installed base aging curves, efficiency mandate phase-in schedules, and greenfield investment pipeline tracking. Industry-specific forecast inputs incorporated EU Innovation Fund disbursement trajectories and ECHA substance restriction implementation timelines.
The model holds under steady EU Green Deal enforcement and stable rare-earth supply conditions; deviation in Chinese export policy or accelerated REACH restriction expansion would shift replacement demand timing and technology mix. Forecasts reflect assumptions regarding certification body capacity constraints and industrial emissions benchmark adherence. Practitioners should monitor ECHA substance restriction consultation outcomes and Bundesministerium für Wirtschaft und Klimaschutz efficiency tier enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Power Stacker Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Germany AC Motor Market
Industrial Motors
Power Scraper Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Vertical Gear Motor Market