
 Norway Wind Energy Market | 2026-2036
Norway Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Wind Energy Market Analytics
Offshore utility procurement is consolidating as the dominant demand channel in Norway's wind energy sector. Equinor ASA leverages its floating platform expertise to anchor large-scale developments in deep-water zones. Statkraft sustains its position through hydro-wind hybrid integration, while Vestas competes on turbine supply contracts for coastal projects. Siemens Gamesa Renewable Energy specializes in offshore direct-drive technology tailored to North Sea conditions.
Norway wind energy encompasses the harnessing of kinetic airflow through horizontal-axis and vertical-axis turbines to generate grid-scale electricity, with offshore floating platforms operating at water depths exceeding 60 meters where fixed foundations prove uneconomical. The primary purpose centers on decarbonizing national power supply while exporting surplus to continental Europe via subsea interconnectors. Offshore technology leads capital deployment, driven by Norway's steep continental shelf and favorable wind resources. Floating installation types represent the fastest-growing structural category, attracting specialized vessel orders and port upgrades. Utility applications dominate offtake agreements, though industrial direct supply contracts are expanding for energy-intensive coastal manufacturing.
The Norwegian Water Resources and Energy Directorate governs concession awards and grid connection priorities, while the Ministry of Petroleum and Energy sets annual leasing round schedules that directly control project pipeline timing. NVE technical standards for grid code compliance and environmental impact thresholds shape turbine selection and layout design requirements. Stakeholders must monitor floating foundation certification progress and hydrogen-of-wind integration pilots to anticipate the next capacity allocation cycle.
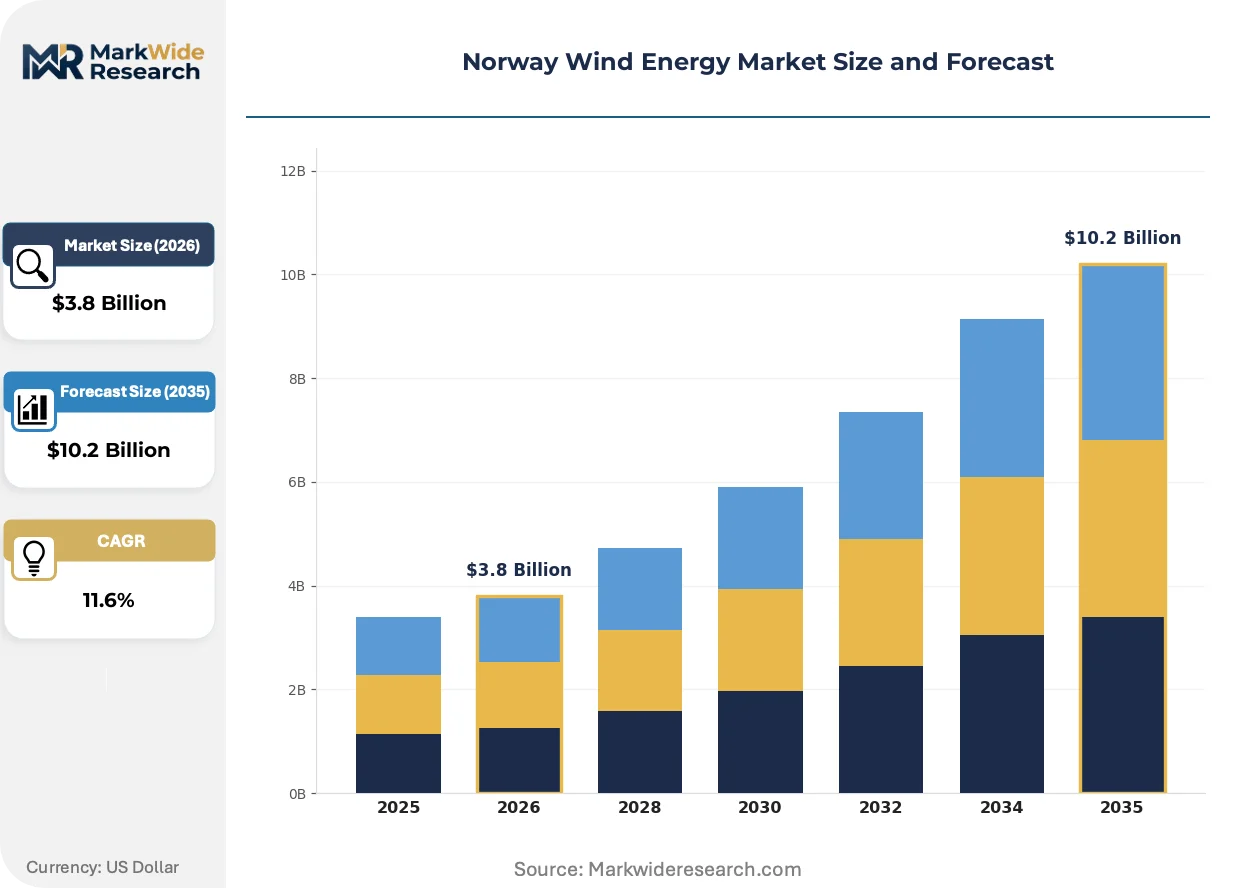
Market Dynamics
Floating foundation technology is electrifying capital deployment patterns across Norway's wind sector, compressing project timelines and rewriting seabed lease economics as developers race to secure deep-water concessions ahead of regulatory allocation cycles.
Growth Catalysts
- Offshore leasing acceleration:The Norwegian Water Resources and Energy Directorate's streamlined concession framework compresses approval timelines for floating installations, unlocking previously inaccessible North Sea zones.
- Subsea export infrastructure:Germany and the United Kingdom's interconnector demand pulls Norwegian surplus capacity, creating guaranteed offtake channels for utility-scale developments.
- Steel and composite manufacturing clusters:Port facilities at Stavanger and Bergen anchor specialized turbine component production, reducing logistics costs for floating foundation assembly.
Market Restraints
- Specialized vessel scarcity:Heavy-lift installation ships for floating platforms concentrate among a handful of North Sea contractors, creating bottlenecks during construction windows.
- Copper and rare earth price volatility:Direct-drive generator magnets and subsea cable sheathing expose project economics to commodity swings beyond developer control.
- Grid connection queuing:Statnett's transmission upgrade schedule creates mismatches between project completion and power evacuation capacity.
Strategic Opportunities
- Hydrogen-of-wind integration:Electrolyzer co-location at port clusters enables green hydrogen export, diversifying revenue beyond electrons.
- Arctic Barents Sea frontier:Ice-class floating platform designs open seasonal construction windows in northern waters currently excluded from leasing rounds.
- Industrial direct supply contracts:Energy-intensive coastal manufacturing—aluminum smelters, data centers, fertilizer plants—bypass utility intermediaries through bilateral power purchase agreements.
Industry Challenges
- Floating foundation certification gaps:DNV and Bureau Veritas standards for multi-turbine platforms remain in draft, freezing financing for novel designs awaiting formal classification.
- Marine electrical technician shortage:Subsea cable jointing and high-voltage offshore maintenance skills concentrate among aging North Sea oil workers with limited knowledge transfer pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Wind Energy Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Turbine Type, Hybrid Application: Utilities, Industrial Use, Commercial Installations, Residential Installation Type: Fixed, Floating, Grid-Connected, Standalone End User: Energy Companies, Government, Private Investors, Agricultural Sector |
| Companies Covered | Equinor ASA, Statkraft, Agder Energi, Magnora ASA, Vestas, Siemens Gamesa Renewable Energy, Norsk Hydro ASA, Scatec, Nel ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Wind Energy Market Evolving Landscape
Technology convergence and procurement model evolution are rewriting competitive rules across Norway's offshore wind value chain. Developers now prioritize integrated system architectures over component sourcing, while regulatory pressure accelerates environmental performance thresholds.
Semi-submersible floating platforms are electrifying project economics in water depths beyond 80 meters. Equinor's Hywind technology anchors commercial-scale deployments where fixed-bottom foundations prove structurally prohibitive. Offshore engineering firms now bid integrated platform-turbine packages rather than discrete components, compressing interface risk and warranty fragmentation.
Norway's Ministry of Petroleum and Energy mandates environmental impact thresholds for seabed leasing that exceed EU baseline requirements. NVE technical standards for marine mammal monitoring and fishing ground coexistence shape layout design and seasonal construction blackouts. Developers respond by clustering turbines in corridors that minimize cable crossings and benthic disturbance, accepting lower capacity density for permit certainty.
Long-term offtake contracting is displacing merchant risk exposure among Norwegian utilities. Statkraft and regional grid operators now seek 15-20 year power purchase agreements with industrial buyers before final investment decisions, transferring volume risk to energy-intensive manufacturers. Aluminum producers and green hydrogen developers in western Norway drive this shift, demanding price certainty for capital-intensive process investments.
Norway Wind Energy Market Segmentation
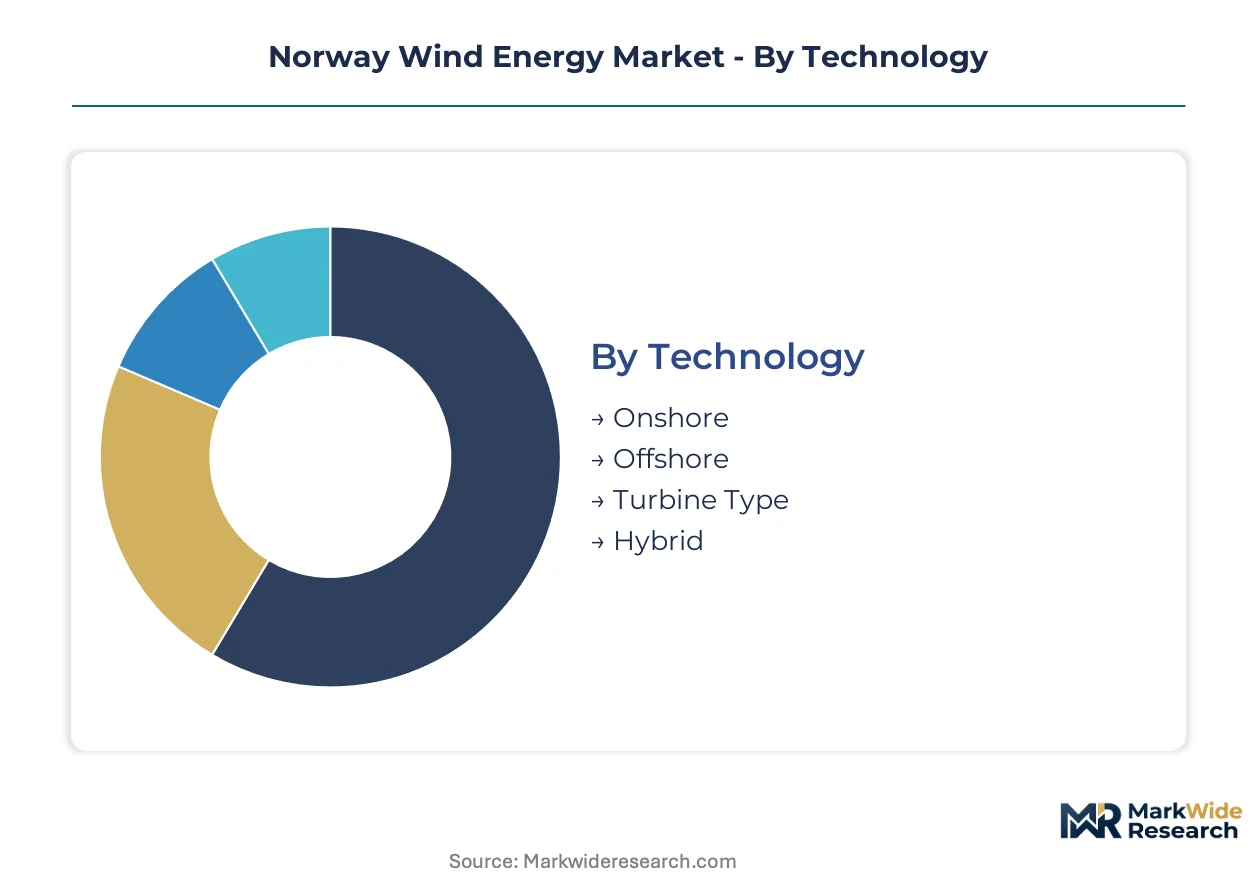
Segmentation in Norway's wind energy market reveals how capital allocation follows distinct procurement logics across technology maturity, buyer risk profiles, and seabed geography. Understanding these divides explains why floating offshore commands premium financing while onshore hybrid projects attract industrial direct investment.
Technology:
Capital intensity and water depth economics drive technology selection decisions for Norwegian developers.
- Offshore:Floating platform installations dominate capital deployment in water depths exceeding 60 meters along the North Sea continental shelf. Equinor's Hywind deployments anchor commercial-scale projects where fixed foundations prove structurally prohibitive, with subsea export cables feeding German and British interconnector demand.
- Onshore:Horizontal-axis turbines in mountainous corridors and coastal plains serve regional grid balancing needs. Statkraft's hydro-wind hybrid integration leverages existing transmission infrastructure in western Norway, compressing grid connection queuing delays that plague standalone developments.
- Turbine Type:Direct-drive generators from Siemens Gamesa eliminate gearbox maintenance in offshore salt-air environments.
- Hybrid:Co-located wind-hydro-battery configurations optimize Norway's reservoir dispatch flexibility against spot price volatility.
Volume sits with offshore; growth tilts toward hybrid.
Application:
Contract duration and counterparty credit quality separate application segments by financing access.
- Utilities:Statkraft and regional grid operators anchor 15-20 year power purchase agreements, transferring volume risk to energy-intensive manufacturers before final investment decisions. Long-term offtake contracting displaces merchant exposure for utility-scale developments.
- Industrial Use:Aluminum smelters, data centers, and fertilizer plants in western Norway bypass utility intermediaries through bilateral agreements. These direct supply contracts demand price certainty for capital-intensive process investments.
- Commercial Installations:Mid-scale developments serve coastal manufacturing clusters with shorter payback horizons.
- Residential:Distributed small-scale turbines concentrate in rural agricultural zones with favorable permitting.
Contracting volume concentrates in utilities; industrial direct procurement climbs fastest.
Installation Type:
Seabed lease allocation cycles and foundation certification status shape installation economics.
- Floating:Semi-submersible platforms unlock deep-water zones beyond 80 meters where the Norwegian Water Resources and Energy Directorate accelerates concession awards. DNV certification progress for multi-turbine designs remains in draft, freezing financing for novel configurations.
- Fixed:Monopile and jacket foundations dominate shallow-water developments with established supply chains.
- Grid-Connected:Statnett transmission upgrades create queuing mismatches between project completion and power evacuation capacity.
- Standalone:Islanded microgrids serve remote coastal facilities with limited interconnection access.
Fixed foundations retain installed base dominance; floating platforms gain share fastest.
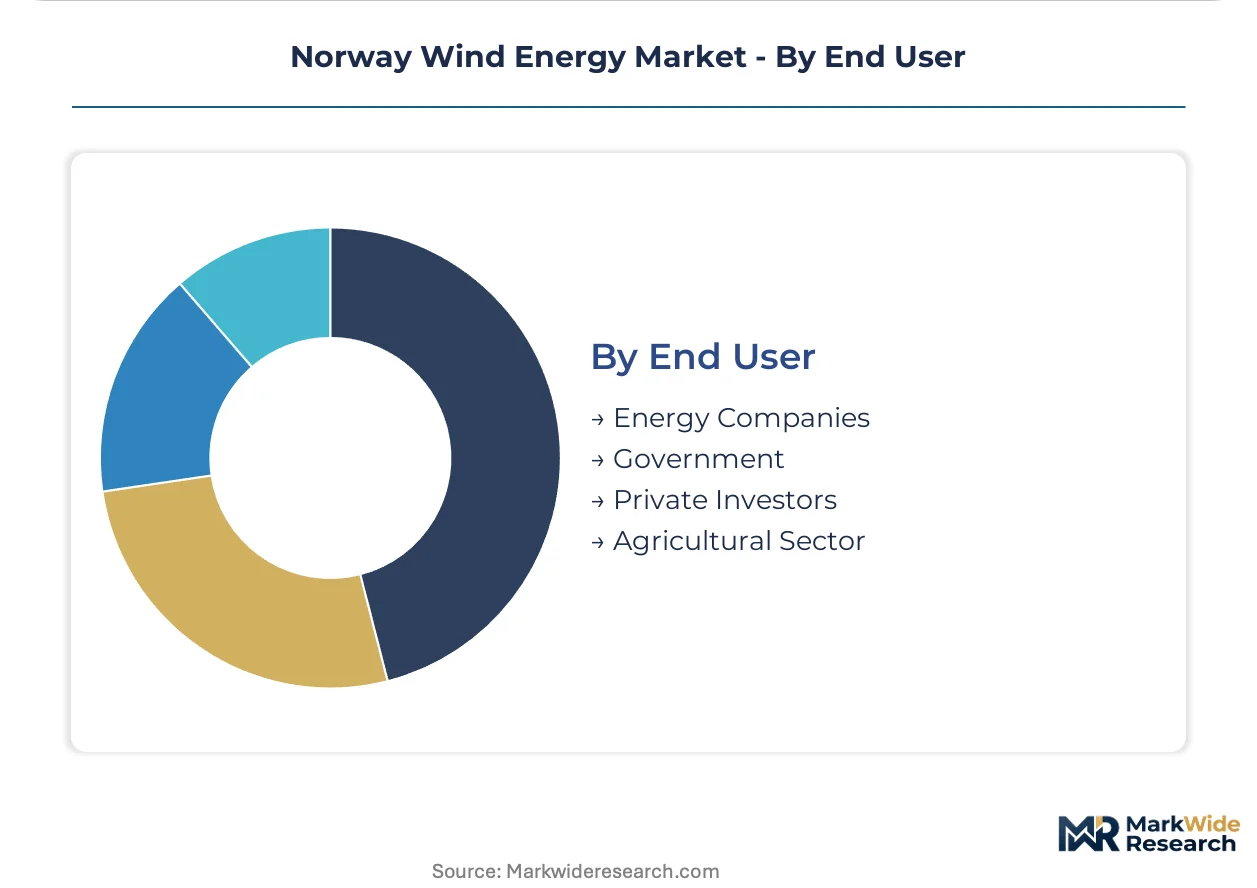
End User:
Risk tolerance and return horizon requirements segment end users by capital source.
- Energy Companies:Equinor and Statkraft deploy balance-sheet capacity for billion-kronor developments, absorbing construction risk and long-dated merchant exposure. Their floating platform expertise anchors integrated system architectures over component sourcing.
- Private Investors:Infrastructure funds and pension capital seek operational assets with contracted revenue streams.
- Government:Ministry of Petroleum and Energy leasing round schedules directly control project pipeline timing through annual allocation cycles.
- Agricultural Sector:Landowners in western Norway lease sites for small-scale onshore turbines with minimal grid upgrade requirements.
Energy companies deploy the most capital; private investors expand fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea port clusters concentrate Norway's wind energy infrastructure, with tax-advantaged development zones accelerating capital deployment along the western coastline from Stavanger to Bergen.
Stavanger Region
Offshore engineering expertise and deep-water port facilities anchor floating platform assembly operations. The Norwegian Water Resources and Energy Directorate prioritizes concession awards for semi-submersible installations in adjacent North Sea blocks. Equinor's Hywind technology development at Karmøy exemplifies integrated platform-turbine manufacturing.
Bergen Corridor
Subsea cable manufacturing and marine logistics clusters serve interconnector export routes to Germany and the United Kingdom. NVE grid code compliance requirements shape turbine selection for projects feeding Statnett's western transmission backbone. Port upgrades at Ågotnes support heavy-lift vessel mobilization for floating foundation deployment.
Trøndelag Coast
Industrial direct supply contracts from aluminum smelters and fertilizer plants drive onshore hybrid wind-hydro development. Ministry of Petroleum and Energy leasing schedules coordinate with reservoir dispatch patterns to optimize seasonal power balancing. Norsk Hydro's captive demand anchors bilateral power purchase agreements in this corridor.
Northern Norway
Arctic Barents Sea frontier zones await ice-class floating platform certification for seasonal construction windows. NVE environmental impact thresholds for marine mammal monitoring extend permitting timelines in these waters. Tromsø-based engineering consultancies prototype cold-climate turbine adaptations for future leasing rounds.
Norway Wind Energy Market Competitive Landscape
Top-tier vendors anchor integrated system architectures, while component specialists compete on discrete technology modules. The market exhibits concentrated leadership among energy majors with floating platform expertise, balanced by specialized turbine suppliers and emerging infrastructure developers. Strategic archetypes span balance-sheet deployers, technology licensors, and industrial offtake aggregators. Competitive moves center on seabed lease accumulation and long-term contracting with energy-intensive manufacturers.
Within the integrated developer tier, Equinor ASA and Statkraft occupy positions defined by floating platform commercialization and hydro-wind hybrid integration respectively. Vestas represents the turbine supply archetype, competing on coastal project equipment contracts. Siemens Gamesa Renewable Energy anchors the offshore direct-drive specialization segment. These three exemplify how technology positioning and capital scale separate competitive vectors in Norway's concession-driven market.
| Leading Market Players |
|---|
| Equinor ASA |
| Statkraft |
| Agder Energi |
| Magnora ASA |
| Vestas |
| Siemens Gamesa Renewable Energy |
| Norsk Hydro ASA |
| Scatec |
| Nel ASA |
| Others |
Value Network & Pricing Analysis
Marine electrical technician concentration in Stavanger and Bergen compresses labor-cost differentials across floating foundation installation tiers, with premium pricing for certified subsea cable jointing teams widening spreads against standard offshore maintenance rates.
Pricing Analysis
Short lead-time premiums for heavy-lift vessel charters compress project economics, while spot inventory discounts on monopile components attract shallow-water developers with flexible construction windows. Contract-based long-term offtake agreements dominate utility procurement, with price differentiation driven by DNV certification grade and volume scale in turbine supply contracts. Cost compression in fixed-bottom foundations intensifies as port infrastructure competition stiffens at Ågotnes and Karmøy. Aluminum smelters exhibit highest price sensitivity due to energy cost pass-through requirements, while Equinor's balance-sheet capacity absorbs premium floating platform pricing without volume risk transfer.
Supply Chain Analysis
Direct-drive generator magnets rest on Chinese rare earth processors and German precision engineering clusters, with subsea cable sheathing drawing from Norwegian and UK copper fabricators. Floating foundation steel and composite inputs hinge on specialized rolling mills in Sweden and Denmark. Single-source vulnerability concentrates in heavy-lift installation vessels operating across the North Sea. Distribution runs through Stavanger and Bergen port clusters with integrated turbine component staging and foundation assembly yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized vessel scarcity props pricing power across installation tiers, with heavy-lift ship availability acting as the binding capacity constraint compressing project timelines and sustaining contractor rate premiums.
For Market Incumbents: Deploy concession accumulation ahead of NVE allocation cycles to lock seabed lease positions before floating foundation certification finalizes. Anchor integrated platform-turbine packages to reduce interface risk exposure. Counter emerging pure-play floating specialists through captive vessel charter agreements and backward integration into port infrastructure control at Ågotnes. For New Entrants and Emerging Players: Capture industrial direct supply contract whitespace in Trøndelag's aluminum corridor, where Norsk Hydro's captive demand lacks bilateral competition. Target hydrogen-of-wind electrolyzer co-location at Bergen port clusters as the most penetrable application segment. Pursue go-to-market positioning as hybrid wind-hydro integrators leveraging Statnett's western transmission backbone access. For Investors and Strategic Acquirers: Re-rating potential sits with floating platform technology licensors given DNV certification finalization as catalyst. Long-term viability favors developers with contracted offtake coverage exceeding fifteen years and seabed lease tenures matching depreciation schedules. Monitor NVE annual allocation cycle announcements as the inflection signal for pipeline visibility and financing access.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Foundation Certification Investment | DNV classification progress unlocks financing for novel multi-turbine platform designs. |
| Heavy-Lift Vessel Charter Agreement | Long-term contractor relationships secure construction windows amid North Sea fleet scarcity. |
| Industrial Direct Supply Contract | Bilateral agreements with aluminum smelters transfer volume risk before final investment decisions. |
| Hydrogen-of-Wind Integration Pilot | Electrolyzer co-location at Bergen diversifies revenue beyond electron-only export models. |
| Port Infrastructure Backward Integration | Control over Ågotnes staging yards compresses logistics costs for floating foundation assembly. |
Research Methodology
Regulatory filings from the Norwegian Water Resources and Energy Directorate, Statnett transmission planning documents, and North Sea offshore project databases formed the secondary backbone for market sizing. Primary interviews with utility planning officers, floating platform EPC contractors, and marine logistics specialists at Stavanger port facilities combined with bottom-up project pipeline aggregation and top-down energy demand modeling. Cross-validation against IEA renewable deployment statistics and FERC interconnector filings anchored volume estimates.
Historical capacity addition trends across the analysis window established baseline growth patterns segmented by technology type, water depth category, and end-user risk profile. CAGRs derived from regression against seabed lease allocation cycles, interconnector commissioning schedules, and industrial power demand curves. Forecast inputs incorporated floating foundation learning curve effects and Statnett transmission upgrade queue progression without year-specific milestone assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to DNV certification timelines and rare earth supply chain disruptions. Assumptions reflect NVE regulatory continuity and German-UK interconnector demand persistence. Copper price volatility, vessel charter rate spikes, and Arctic Barents Sea ice-class platform approvals warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Italy Wind Energy Market