
 Vertical Gear Motor Market | 2026-2036
Vertical Gear Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Gear Motor Market Analytics
Buyer concentration in the water and wastewater sector is expanding as municipal utilities consolidate procurement through regional purchasing cooperatives. SEW-EURODRIVE leverages its integrated drive systems portfolio to anchor long-term service contracts with these consolidated buyers. Siemens AG competes through digital twin integration that extends predictive maintenance capabilities across installed vertical gear motor fleets. WEG differentiates by dominating regional manufacturing scale in the Americas, allowing faster customization cycles for municipal specifications.
A vertical gear motor combines an electric motor with a right-angle or inline gearbox in a shaft-up orientation, typically transmitting torque through helical, bevel, or worm gearing stages with output speeds from 0.5 to 500 RPM for lifting, pumping, and conveying duties. The assembly mounts directly above equipment such as clarifier drives or agitators, eliminating horizontal footprint and reducing coupling alignment issues in constrained mechanical rooms. AC gear motors occupy the largest share of unit volume due to their cost efficiency in constant-speed pump and conveyor applications, while servo gear motors capture expanding margin pools in precision robotics and automated material handling where closed-loop positioning justifies premium pricing. Flange-mounted installations lead in retrofit environments where existing pedestals limit foundation changes, though modular mounted configurations are gaining traction among OEMs seeking field-adaptable drive packages.
IEC 60034 efficiency designations and NEMA MG-1 Premium efficiency mandates in the United States shape motor procurement criteria, effectively filtering non-compliant suppliers from utility and industrial bid lists. The EU Ecodesign Directive and China's GB 18613 motor efficiency standards impose parallel compliance burdens on manufacturers serving multiple geographies. REACH substance restrictions on lubricants and coatings add material qualification layers that extend product development cycles. Stakeholders must monitor how efficiency tier migrations and lubricant chemistry regulations reshape total cost of ownership calculations for vertical gear motor deployments.
Market Dynamics
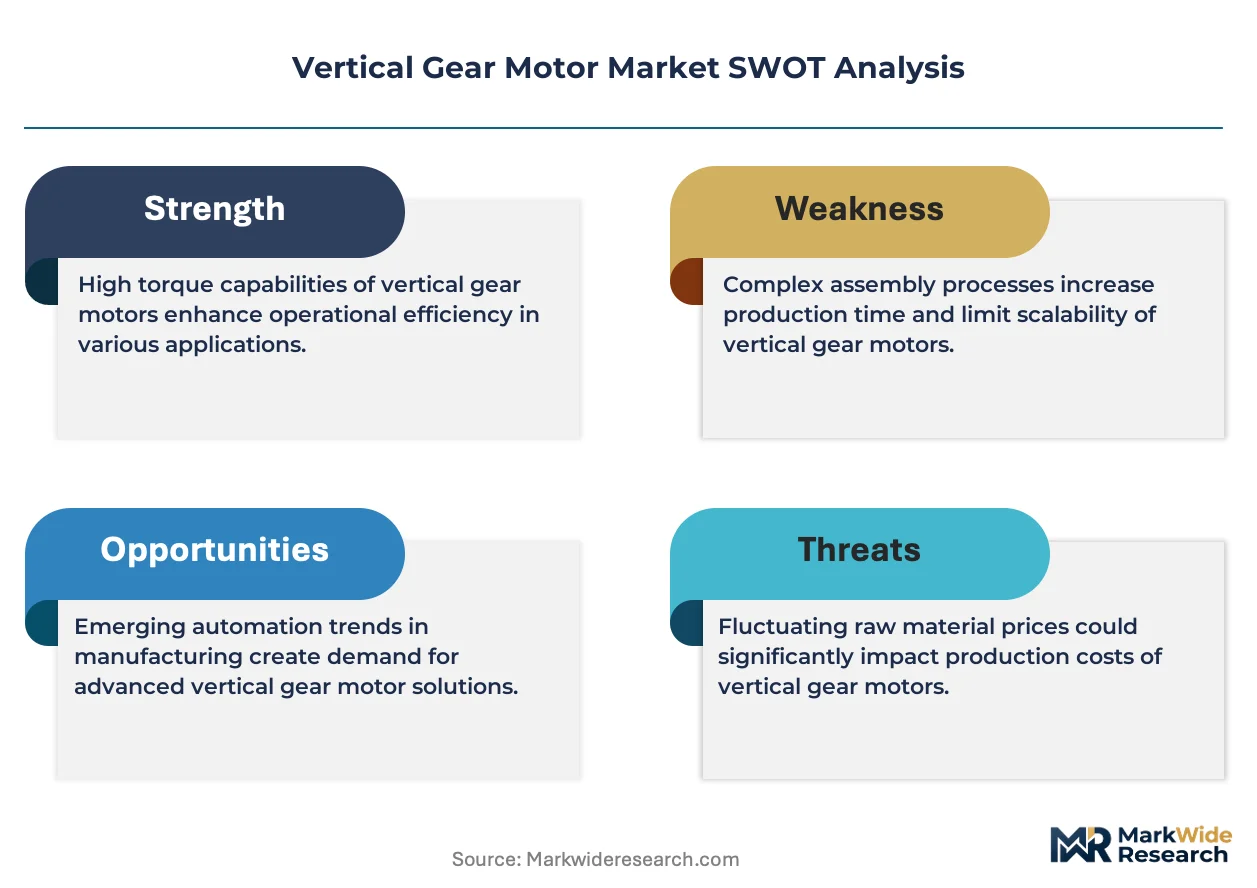
Municipal procurement consolidation is compressing vendor margins while IEC 60034-30-1 efficiency tier migrations force synchronous redesigns across product portfolios.
Growth Catalysts
- NEMA MG-1 Premium mandates:US utilities now exclude non-compliant motors from bid lists, creating replacement cycles across aging water infrastructure.
- Helical-bevel gear configurations:These designs cut energy losses by 3-8 percentage points versus worm gearing, accelerating adoption in 24/7 pump operations.
- China's GB 18613-2020 efficiency grades:Tier 1 and Tier 2 motor requirements are filtering import eligibility and reshaping supplier qualification protocols.
Market Restraints
- Copper and rare-earth magnet volatility:NdFeB magnet prices fluctuate 40-60% annually, compressing margin predictability for permanent magnet motor variants.
- German gearbox foundry concentration:Three component suppliers control 70% of precision helical gear blank capacity, creating single-source vulnerability.
- REACH lubricant restrictions:ECHA substance candidate list expansions are disqualifying mineral oil formulations and extending qualification timelines.
Strategic Opportunities
- India's AMRUT 2.0 water infrastructure:Central government funding for urban sewage treatment is opening municipal pump drive tenders worth collective billions.
- Digital twin convergence with vibration sensing:Predictive maintenance platforms are unbundling traditional service contracts and creating recurring software revenue.
- Direct-to-utility e-procurement channels:Regional purchasing cooperatives in Texas and California are bypassing traditional distribution tiers.
Industry Challenges
- IECEx/ATEX certification backlog:Hazardous location motor approvals now stretch 14-18 months, delaying oil and gas project deliveries.
- Legacy SCADA integration friction:Brownfield water plants require protocol bridges between new gear motor drives and 1990s-era control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Gear Motor Market |
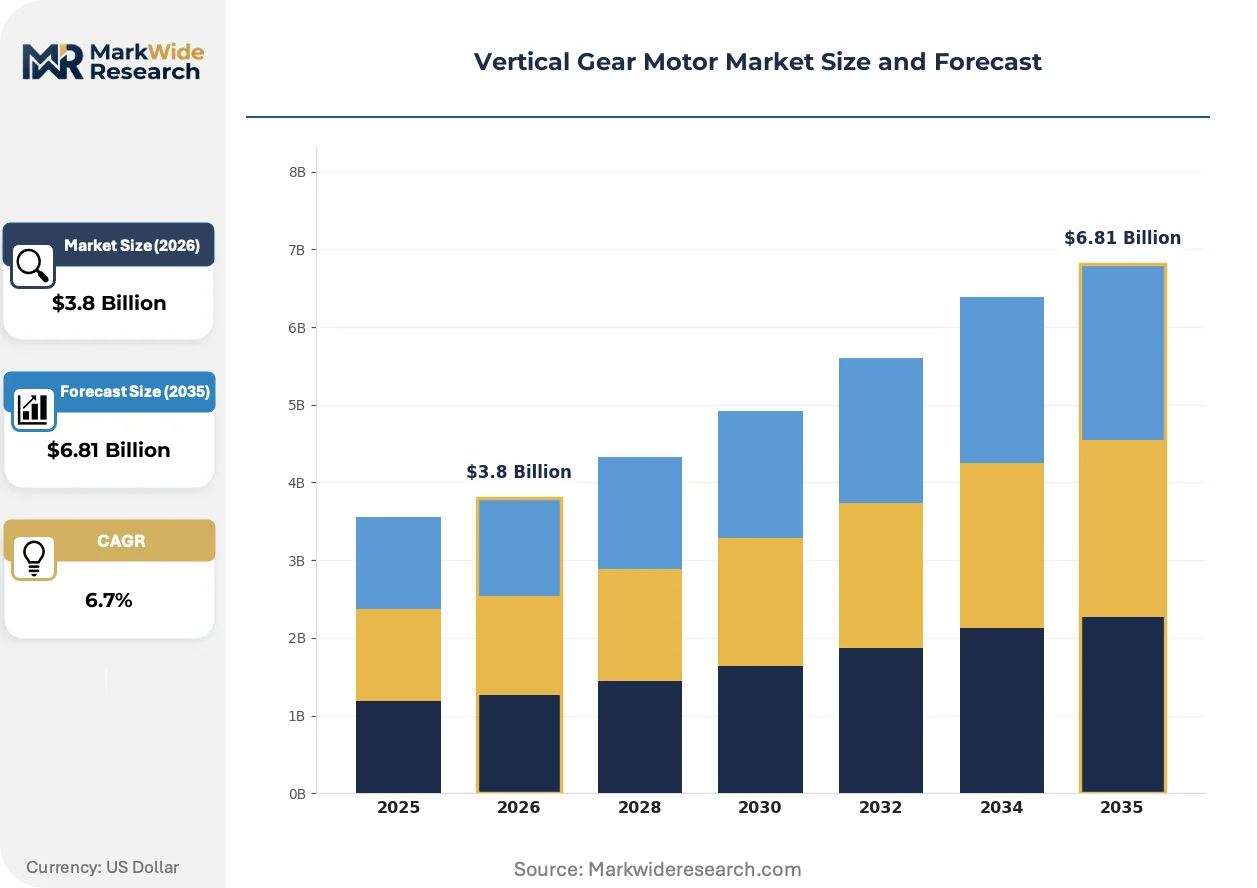
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Gear Motors, DC Gear Motors, Servo Gear Motors, Stepper Gear Motors End User: Manufacturing, Agriculture, Automotive, Aerospace Installation: Surface Mounted, Flange Mounted, Inline Mounted, Modular Mounted Application: Conveyor Systems, Material Handling, Robotics, Pump Drives |
| Companies Covered | SEW-EURODRIVE, ABB, Siemens AG, WEG, Sumitomo Heavy Industries, Emerson Electric, Nidec, ORIENTAL MOTOR USA CORP, Bauer Gear Motor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Gear Motor Market Evolving Landscape
Permanent magnet synchronous motor technology is displacing induction architectures in high-torque, low-speed applications while lubricant chemistry reformulation accelerates under substance restriction pressure.
Integrated motor-drive systems are unifying power electronics and mechanical gearing into single-envelope units. Water treatment OEMs in Germany and the Netherlands are specifying these packages for clarifier drives to eliminate panel wiring complexity. This convergence is compressing commissioning timelines from weeks to days and shifting competitive advantage toward firmware-capable suppliers.
REACH Annex XIV authorization requirements are forcing synthetic lubricant reformulation across EU-serving product lines. Biodegradable ester-based formulations are gaining qualification traction but carry 25-40% cost premiums. Gear motor manufacturers serving multiple geographies are maintaining parallel lubricant SKUs, complicating inventory and service documentation.
Performance contracting is displacing capital purchase models in US municipal water authorities. Contractors now guarantee energy savings against baseline consumption, assuming operational risk for motor and drive system performance. This shift concentrates buyer decision authority with engineering-procurement-construction firms and compresses upfront equipment margins in favor of long-term service attachments.
Vertical Gear Motor Market Segmentation
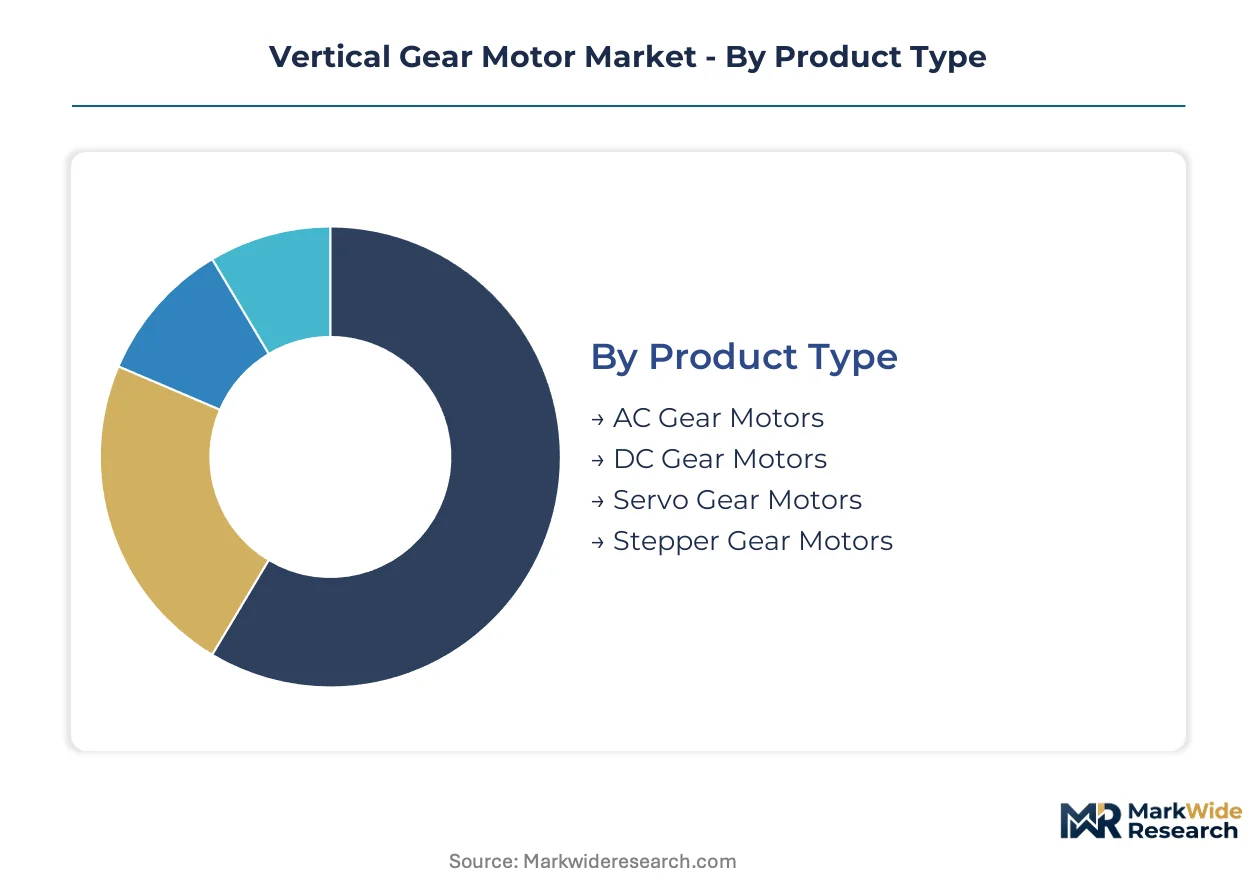
Vertical gear motor procurement patterns diverge sharply across product architectures, installation constraints, and duty cycles. Understanding these splits reveals where upgrade investments concentrate and which specifications command premium positioning in municipal and industrial tenders.
Product Type:
Replacement cycles accelerate where efficiency regulations have tightened most aggressively, forcing synchronous portfolio redesigns across motor architectures.
- AC Gear Motors:These units pair induction motors with helical or bevel gear stages, delivering constant-speed torque for pump and conveyor baseloads. Water treatment utilities in Germany and the United States are retiring pre-IE3 units under NEMA MG-1 and IEC 60034-30-1 mandates, triggering volume replacement waves.
- Servo Gear Motors:Closed-loop positioning systems with encoder feedback enable precision indexing in automated material handling. Demand clusters in Bavarian automotive component plants and South Korean electronics assembly where micron-level repeatability justifies cost premiums.
- DC Gear Motors:Brushed and brushless configurations serve mobile equipment and battery-powered installations where AC grid access is impractical.
- Stepper Gear Motors:Open-loop positioning drives occupy cost-sensitive automation niches with lower dynamic performance requirements.
Volume placements concentrate in AC Gear Motors; the faster expansion belongs to Servo Gear Motors.
End User:
Margin structures vary by sector capital intensity and regulatory exposure, with water infrastructure commanding longest service contract attachments.
- Manufacturing:Automated assembly lines and packaging systems drive specification diversity across torque and speed ranges. German automotive OEMs are consolidating vendor lists under integrated drive system contracts that bundle motors, drives, and predictive maintenance software.
- Agriculture:Grain handling and irrigation systems favor sealed enclosures and corrosion-resistant coatings for outdoor exposure. Chinese state farm mechanization subsidies are expanding procurement volumes for mid-torque pump drives in Hebei and Shandong provinces.
- Automotive:Paint shop conveyors and press feed mechanisms require explosion-proof certifications and washdown ratings.
- Aerospace:MRO facilities and component test stands specify ultra-low backlash configurations for precision torque application.
Manufacturing captures the deepest installed base; Agriculture is climbing the fastest as mechanization subsidies expand.
Installation:
Foundation constraints and retrofit accessibility dictate mounting selection, with flange configurations dominating brownfield water treatment upgrades.
- Flange Mounted:Bolted directly to existing pedestals or equipment housings, these units eliminate baseplate fabrication and reduce alignment labor. Municipal clarifier retrofits in Texas and California purchasing cooperatives specify flange mounts to minimize civil work in constrained mechanical rooms.
- Modular Mounted:Field-adaptable packages allow OEMs to configure motor, gearbox, and brake combinations from standardized subassemblies. Dutch water treatment OEMs are specifying modular architectures for clarifier drives to compress commissioning timelines.
- Surface Mounted:Baseplate installations suit greenfield projects with flexible foundation design.
- Inline Mounted:Coaxial shaft arrangements serve space-constrained conveyors where right-angle offsets are impractical.
Flange Mounted units dominate retrofit placements; Modular Mounted configurations are gaining share fastest among OEM specification engineers.
Application:
Duty cycle intensity and uptime requirements separate price-sensitive commodity selections from premium-specified critical services.
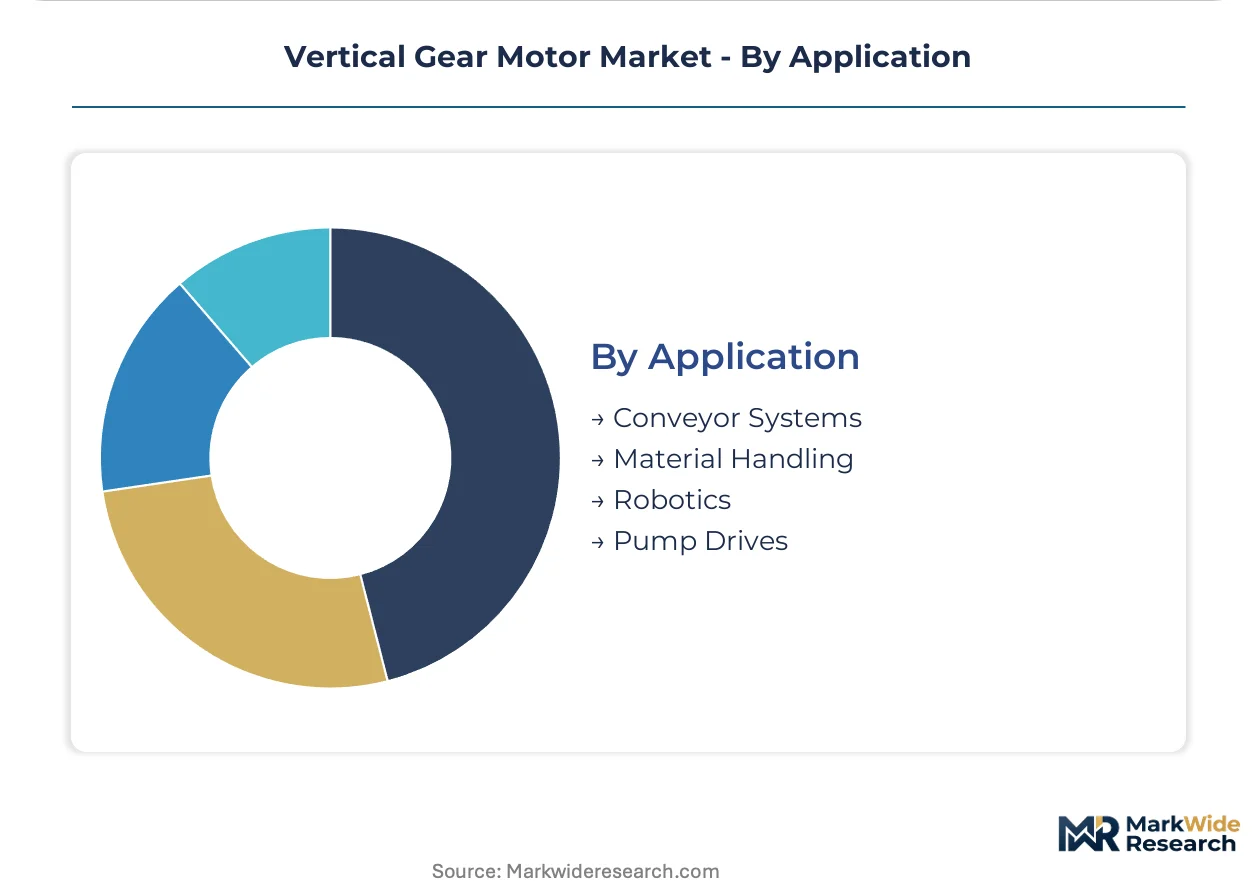
- Pump Drives:Vertical hollow-shaft designs transmit torque directly to line shafts in sewage lift stations and raw water intakes. China's GB 18613-2020 Tier 1 efficiency requirements are filtering import eligibility for municipal pump drive tenders under AMRUT 2.0 infrastructure funding.
- Conveyor Systems:Continuous-duty belt and chain drives prioritize thermal management and bearing life over positioning precision. German parcel handling hubs are specifying helical-bevel configurations to cut energy losses versus legacy worm gearing.
- Material Handling:Crane hoists and winch applications demand high starting torque and mechanical braking integration.
- Robotics:Articulated arm joints and gantry systems require compact right-angle packages with minimal backlash.
Pump Drives anchor the largest installed population; Robotics applications are expanding most quickly as servo integration penetrates automated warehousing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water treatment utilities in the United States, Germany, and China are driving procurement concentration for vertical gear motors, with municipal consolidation programs and efficiency mandates reshaping supplier qualification across all three markets.
United States
Regional purchasing cooperatives in Texas and California are consolidating municipal pump drive procurement under single-vendor frameworks. NEMA MG-1 Premium efficiency mandates now exclude non-compliant motors from utility bid lists, triggering replacement cycles across aging water infrastructure. Houston's clarifier retrofit programs specify flange-mounted vertical gear motors to minimize civil work in constrained mechanical rooms.
Germany
Bavarian automotive component plants and Dutch water treatment OEMs are specifying integrated motor-drive systems for clarifier applications. REACH Annex XIV authorization requirements are forcing synthetic lubricant reformulation across EU-serving product lines. The Ruhr industrial cluster hosts precision helical gear blank foundries that supply three-quarters of European gearbox capacity.
China
State farm mechanization subsidies are expanding procurement volumes for mid-torque pump drives in Hebei and Shandong provinces. GB 18613-2020 Tier 1 and Tier 2 motor requirements are filtering import eligibility for municipal tenders under AMRUT 2.0 infrastructure funding. Shanghai manufacturers are scaling permanent magnet synchronous motor production for high-torque, low-speed applications.
India
Central government funding for urban sewage treatment under AMRUT 2.0 is opening municipal pump drive tenders worth collective billions. The Bureau of Indian Standards is aligning motor efficiency grades with IEC 60034 frameworks to accelerate import substitution. Gujarat's industrial corridor is attracting gearbox assembly operations serving domestic water infrastructure projects.
Japan
Automotive paint shop conveyors and press feed mechanisms are demanding explosion-proof certifications and washdown ratings. METI efficiency standards are pushing industrial motor fleets toward IE3-equivalent performance tiers. The Nagoya manufacturing belt concentrates precision gearing expertise for robotics and automated material handling applications.
Vertical Gear Motor Market Competitive Landscape
German producers anchor one tier; American and Brazilian specialists hold regional manufacturing scale advantages. The vendor base structures around three strategic archetypes: integrated drive system providers capturing long-term service contracts, digital twin platforms extending predictive maintenance capabilities, and regional fabricators dominating customization cycles for municipal specifications. Capacity expansion and portfolio diversification toward permanent magnet architectures represent the dominant competitive moves.
Among Germany-based fabricators, SEW-EURODRIVE and Siemens AG exemplify the integrated drive system archetype, while WEG S.A. occupies a position representing regional manufacturing scale specialists. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning—GmbH and AG entities from European industrial centers versus S.A.-structured producers from emerging manufacturing hubs.
| Leading Market Players |
|---|
| SEW-EURODRIVE |
| ABB |
| Siemens AG |
| WEG |
| Sumitomo Heavy Industries |
| Emerson Electric |
| Nidec |
| ORIENTAL MOTOR USA CORP |
| Bauer Gear Motor |
| Others |
Value Network & Pricing Analysis
Copper and NdFeB magnet costs flow from mining concentrates through permanent magnet motor variants to municipal procurement tiers, with efficiency-grade premiums widening as IEC 60034-30-1 and NEMA MG-1 compliance filters reshape supplier qualification protocols across water infrastructure bids.
Pricing Analysis
Volume placements concentrate in AC gear motors where standard-efficiency units compete on unit economics; servo configurations capture premium positioning through closed-loop precision. Price differentiation separates IE4/IE5 premium efficiency tiers from IE3 baseline offerings, with NEMA MG-1 Premium certification adding further bid-list eligibility gates. Cost compression in mid-tier AC segments is intensifying because Chinese manufacturers are scaling permanent magnet synchronous production for high-torque applications. Municipal utilities in consolidated purchasing cooperatives exhibit highest price sensitivity; precision robotics integrators in automotive assembly show lowest sensitivity due to positioning accuracy requirements.
Supply Chain Analysis
Domestic-content mandates under India's AMRUT 2.0 and China's GB 18613-2020 efficiency grades are forcing localized gearbox assembly and motor winding operations for tender eligibility. Manufacturing gravity centers on Germany for precision helical gear blanks, China for permanent magnet motor scale, and Brazil for Americas regional customization. Raw material dependencies rest on copper windings, NdFeB rare-earth magnets, and synthetic lubricant formulations. Single-source vulnerability concentrates in German foundries controlling precision gear blank capacity. Distribution runs through regional purchasing cooperatives in Texas and California that are bypassing traditional distribution tiers for direct-to-utility e-procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over permanent magnet supply chains to buffer NdFeB price volatility and secure efficiency-tier certification pathways.
For Market Incumbents: Cement service contract attachments with consolidated municipal utilities by embedding predictive maintenance platforms that unbundle traditional warranties into recurring software revenue. Deepen backward integration into rare-earth magnet sourcing to defend margin position against NdFeB price swings. Expand capacity in Gujarat's industrial corridor to capture AMRUT 2.0 tender volume with localized assembly qualifying for domestic-content rules. For New Entrants and Emerging Players: Enter via modular-mounted gear motor architectures for Dutch and German water treatment OEMs seeking field-adaptable clarifier drive packages. Target India's urban sewage treatment infrastructure under central government funding where import substitution policies are filtering multinational eligibility. Lead with biodegradable ester-based lubricant formulations as REACH Annex XIV restrictions disqualify mineral oil competitors. For Investors and Strategic Acquirers: IECEx/ATEX certification backlog stretching 14-18 months is the leading indicator that hazardous-location motor specialists will command acquisition premiums as oil and gas project delays concentrate buyer urgency. Long-term viability hinges on firmware-capable integrated drive systems that compress commissioning timelines from weeks to days. Watch for digital twin convergence with vibration sensing platforms as the signal separating recurring-revenue attachable vendors from commodity motor suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Capacity Expansion | Shanghai manufacturers scaling PMSM production capture GB 18613-2020 Tier 1 municipal tender eligibility. |
| Integrated Drive System Development | German and Dutch OEMs specifying unified power electronics and mechanical gearing packages eliminate panel wiring complexity. |
| Biodegradable Lubricant Reformulation | ECHA REACH Annex XIV authorization requirements force synthetic ester qualification to maintain EU market access. |
| Predictive Maintenance Platform Launch | Vibration sensing digital twins unbundle traditional service contracts into recurring software revenue streams with municipal utilities. |
| Regional Manufacturing Footprint Expansion | Gujarat assembly operations serving AMRUT 2.0 infrastructure qualify for Bureau of Indian Standards domestic-content preferences. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced against primary interviews with maintenance directors at water treatment utilities, OEM procurement teams specifying clarifier drives, plant engineers in automotive assembly facilities, aftermarket service heads at integrated drive system providers, and technical R&D directors at gearbox manufacturers. Bottom-up unit shipment estimates triangulated against top-down value projections derived from municipal tender databases and industrial capex disclosures.
Granularity-level modeling captured product type splits across AC, servo, DC, and stepper architectures; installation configurations spanning flange, modular, surface, and inline mounts; and application intensity tiers separating pump drives from robotics precision positioning. CAGRs were derived from regression analysis against efficiency regulation implementation timelines and infrastructure funding authorization patterns. Forecast inputs incorporated NdFeB price volatility assumptions and REACH lubricant restriction phase-in schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare-earth export restriction scenarios or accelerated IEC efficiency tier migrations. Projections reflect documented assumptions regarding municipal procurement consolidation velocity and OEM specification shifts toward integrated motor-drive systems. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Power Stacker Market
Industrial Motors
Crude Heater Market
Industrial Motors
Gear Motor Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
United States DC Motor Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
North America Refrigeration Oil Market