
 Gear Motor Market | 2026-2036
Gear Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Motor Market Analysis
Robotics and automated machinery is realigning the gear motor demand profile toward precision servo and compact planetary configurations. SEW-EURODRIVE leverages its integrated drive systems portfolio to dominate material handling applications across European automotive plants. Siemens AG sustains technology leadership through digital twin-enabled gear motor diagnostics embedded in its industrial automation stack. Nidec Corporation anchors high-volume production of compact brushless DC gear motors for collaborative robot joints.
A gear motor combines an electric motor with a mechanical gearbox to reduce output speed while multiplying torque for controlled mechanical motion, typically specified by gear ratio, efficiency class, and output torque rating in Newton-meters. AC gear motors remain the volume backbone across conveyor and packaging lines where constant speed operation suffices, though servo gear motors are displacing them in indexing and pick-and-place roles demanding programmable positioning. Low and medium power ratings occupy the largest installed base, while ultra high power units command concentrated margin pools in heavy mining and steel mill applications.
Efficiency regulations including IEC 60034-30-1 efficiency classes and the US DOE integral horsepower motor rule shape product design mandates and淘汰 schedules for non-compliant induction motor-gearbox pairings. REACH substance restrictions and RoHS material limits constrain lubricant formulations and housing alloys, pushing manufacturers toward synthetic greases and aluminum die-casting substitutions. Stakeholders must monitor how regional carbon border adjustments and embodied energy disclosure requirements will reshape sourcing economics for cast iron housings and copper windings.
Market Dynamics
IEC 60034-30-1 efficiency class upgrades and regional motor efficiency mandates are compressing demand for lower-tier asynchronous units while accelerating replacement cycles across industrial installed bases.
Growth Catalysts
- Material handling automation:Automated conveyor systems in e-commerce fulfillment centers and automotive assembly plants are expanding gear motor deployment for precise torque control and synchronized motion.
- REACH substance restrictions:European chemical regulations are pushing manufacturers toward synthetic lubricants and aluminum die-cast housings, creating upgrade demand for compliant integrated drive systems.
- Servo motor displacement:Programmable positioning requirements in indexing and pick-and-place applications are pulling demand from fixed-speed AC gear motors toward precision servo configurations.
Market Restraints
- Copper and rare earth magnet volatility:Windings and permanent magnet materials face price swings that compress margins on compact brushless DC units for collaborative robotics.
- Cast iron supply concentration:Heavy mining and steel mill applications depend on specialized foundry capacity concentrated in select industrial clusters, creating lead time vulnerability for ultra high power housings.
- Induction motor-gearbox pairing obsolescence:Non-compliant legacy configurations face accelerated淘汰 schedules under US DOE integral horsepower motor rules, stranding installed base retrofit investments.
Strategic Opportunities
- Smart factory investments:Manufacturing reshoring initiatives in Germany and the United States are creating demand for digital twin-enabled gear motor diagnostics integrated into industrial automation stacks.
- Collaborative robot joints:Compact planetary configurations for human-robot interaction represent underpenetrated white space requiring specialized torque density and safety-rated feedback systems.
- Carbon border adjustment mechanisms:Embodied energy disclosure requirements will reshape sourcing economics for copper windings and cast iron components, favoring suppliers with verified low-carbon production pathways.
Industry Challenges
- Electromechanical integration expertise:Servo gear motor proliferation requires control systems engineering capabilities scarce in traditional gearbox-focused workforces.
- Multi-standard certification timelines:Simultaneous compliance with IEC efficiency classes, CE marking, and US DOE rules extends product launch cycles and fragments R&D allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Motor Market |
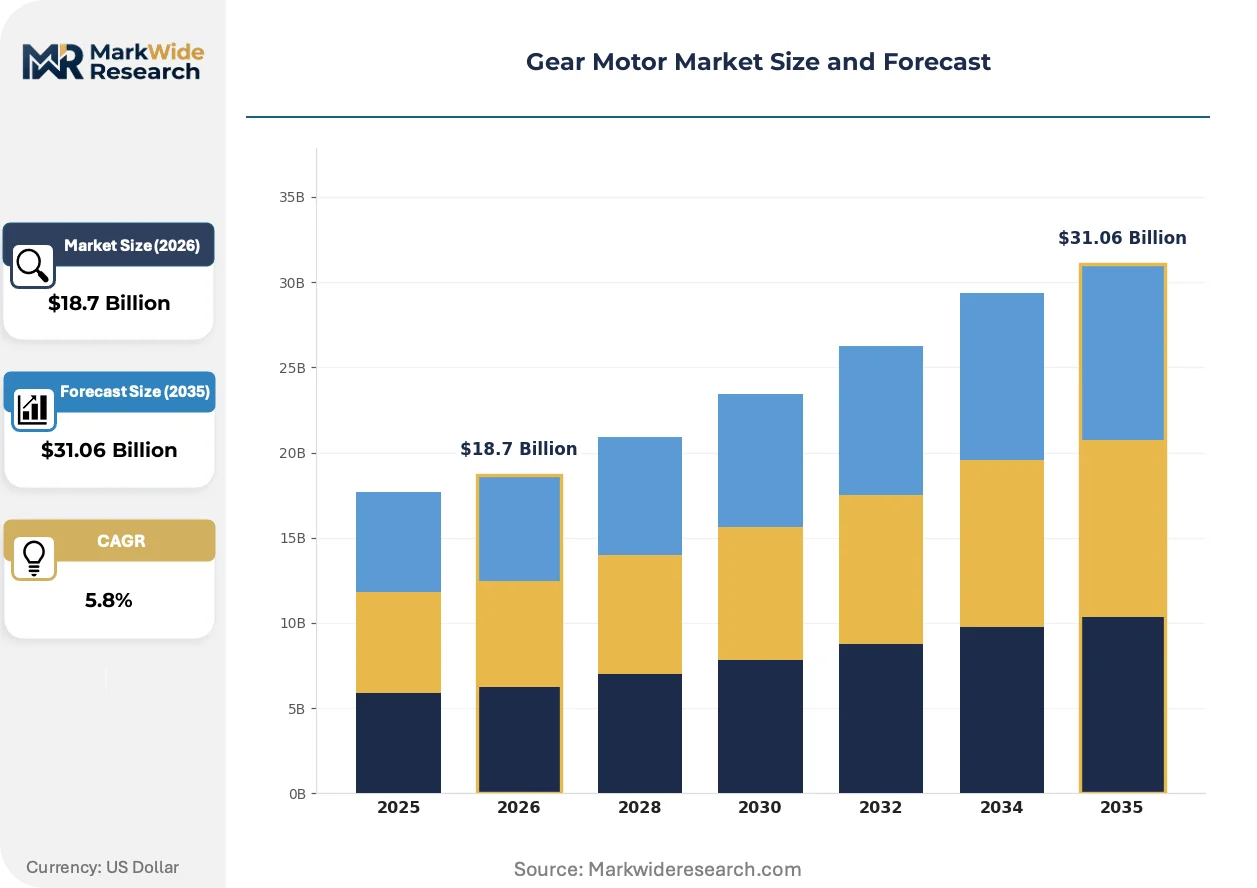
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Gear Motors, DC Gear Motors, Servo Gear Motors, Stepper Gear Motors Application: Automated Machinery, Conveyors, Robotics, Packaging Equipment End User: Manufacturing, Automotive, Food Processing, Aerospace Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | SEW-EURODRIVE, Siemens AG, ABB, Emerson Electric, Sumitomo Heavy Industries, Regal Rexnord Corporation, Nidec Corporation, Bonfiglioli, Bauer Gear Motor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Motor Market Emerging Trajectories
Precision motion requirements and connected diagnostics are restructuring how gear motors are specified, procured, and maintained across industrial verticals.
Integrated drive systems combining motor, gearbox, and variable frequency drive in a single mechanical envelope are modularizing how automotive OEMs specify material handling equipment. Tier-1 suppliers in European automotive plants now demand plug-and-play motion subsystems rather than discrete component sourcing. This consolidation is compressing the vendor base while elevating system-level accountability over individual component warranties.
EU Green Deal carbon intensity benchmarks and embodied energy disclosure mandates are reshaping supplier qualification protocols for cast iron housings and copper windings. Foundries in Germany and Italy must now document Scope 1-3 emissions to maintain preferred supplier status with industrial automation majors. Heavy mining and steel mill applications face the steepest compliance burdens given their reliance on high-material-content ultra high power units.
Buyer concentration among automotive and e-commerce fulfillment operators is compressing specification cycles and unbundling after-sales service contracts from initial equipment purchases. Large-scale conveyor operators in the United States now demand predictive maintenance data feeds as a condition of vendor selection, displacing traditional time-based service agreements. This behavioral shift is most visible in automated intralogistics deployments where uptime guarantees dominate total cost of ownership calculations.
Gear Motor Market Segmentation
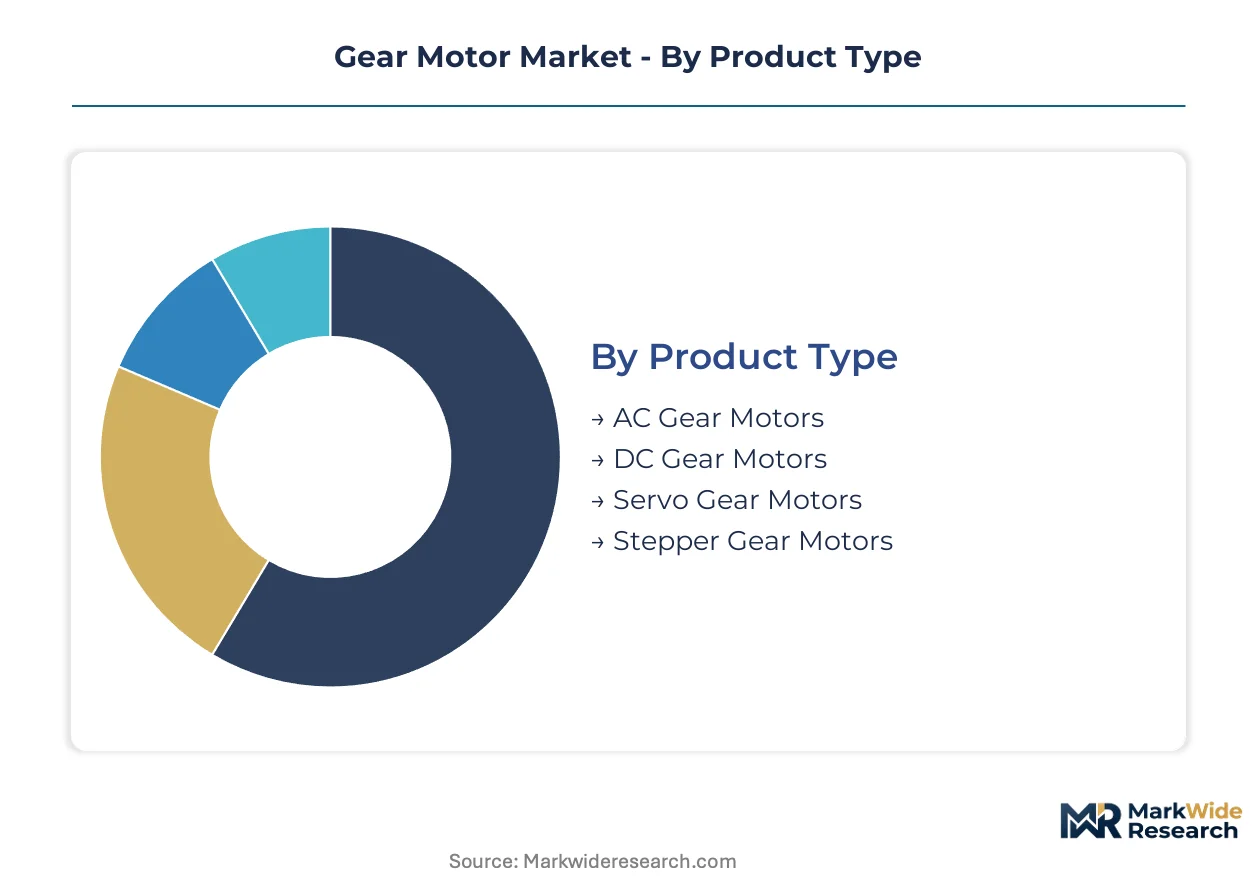
Gear motor specification patterns diverge sharply across power classes and motion control architectures. Understanding how IEC efficiency mandates and automation intensity reshape segment trajectories enables precise portfolio positioning.
Product Type:
Efficiency class upgrades and servo displacement dynamics are compressing replacement cycles across asynchronous configurations while accelerating precision motor adoption.
- AC Gear Motors:Induction motor-gearbox pairings dominate conveyor and packaging lines where constant speed operation suffices. IEC 60034-30-1 compliance deadlines in Germany and China are forcing accelerated淘汰 of IE1 and IE2 legacy units across material handling installed bases.
- Servo Gear Motors:Permanent magnet synchronous motors with integrated planetary or helical gearboxes deliver programmable positioning for indexing and pick-and-place roles. Demand concentrates in automotive assembly plants across the United States where digital twin-enabled diagnostics now determine vendor selection.
- DC Gear Motors:Brushed and brushless configurations serve battery-powered mobile equipment and low-voltage automation subsystems. REACH substance restrictions are pushing manufacturers toward synthetic lubricants and aluminum housing substitutions in European supply chains.
- Stepper Gear Motors:Open-loop position control suits low-cost precision applications in laboratory automation and small-format packaging. Cost-sensitive procurement in Asian manufacturing clusters sustains volume despite servo encroachment at higher performance tiers.
AC gear motors sit at the top of the volume ranking, with servo gear motors climbing the fastest.
Application:
Automation intensity varies dramatically by end-use, with uptime guarantees and predictive maintenance requirements reshaping procurement specifications.
- Automated Machinery:General-purpose motion subsystems for machine tools and processing equipment require configurable torque-speed profiles. Smart factory investments in Germany are elevating system-level accountability over discrete component warranties.
- Conveyors:Synchronized multi-motor arrays in e-commerce fulfillment centers demand precise torque control for package routing. Large-scale operators in the United States now mandate predictive maintenance data feeds as a condition of vendor selection.
- Robotics:Collaborative robot joints require compact planetary configurations with safety-rated feedback systems. Human-robot interaction applications represent underpenetrated white space requiring specialized torque density engineering.
- Packaging Equipment:Intermittent motion and continuous web handling applications span from low-cost indexing to high-speed servo coordination. Food processing hygiene requirements in Europe favor stainless steel housing variants with sealed lubrication systems.
Conveyors command the largest installed base, with robotics gaining share fastest.
End User:
Customer concentration among automotive and e-commerce operators is compressing specification cycles and unbundling service contracts from equipment purchases.
- Manufacturing:Diverse factory automation spanning metalworking, plastics, and assembly operations. Manufacturing reshoring initiatives in Germany and the United States are creating demand for integrated drive systems with embedded diagnostics.
- Automotive:Tier-1 suppliers demand plug-and-play motion subsystems rather than discrete component sourcing. European automotive plants now specify complete material handling modules from SEW-EURODRIVE and Siemens AG portfolios.
- Food Processing:Hygienic design requirements and washdown compatibility constrain housing materials and sealing architectures. EU Green Deal carbon intensity benchmarks are reshaping supplier qualification protocols for cast iron and aluminum components.
- Aerospace:Precision motion for assembly jigs and testing equipment with extreme reliability requirements. Low-volume, high-margin procurement tolerates extended lead times for specialized foundry capacity.
Manufacturing generates the broadest volume footprint, with automotive delivering the steepest margin expansion trajectory.
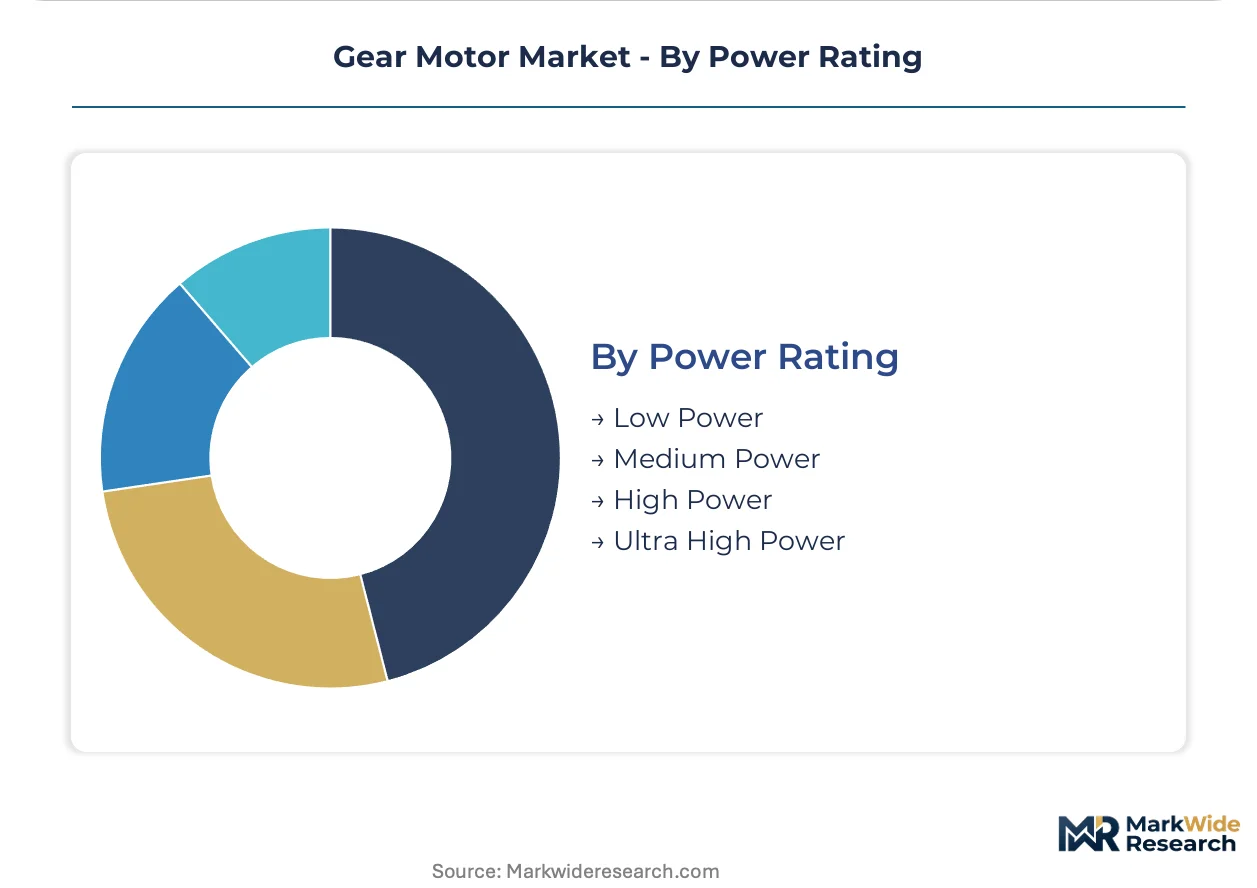
Power Rating:
Material intensity and embodied carbon scale non-linearly with power class, concentrating compliance burdens in heavy industrial applications.
- Low Power:Compact units below 750W serve collaborative robotics and small-format automation. Brushless DC configurations from Nidec Corporation anchor high-volume production for robot joint applications.
- Medium Power:The volume backbone across packaging lines and general machinery, typically 0.75-7.5kW. US DOE integral horsepower motor rules are accelerating replacement of non-compliant induction motor-gearbox pairings in this range.
- High Power:Mining conveyors and steel mill drives demand ruggedized housings and forced lubrication systems. Copper and rare earth magnet volatility compresses margins on permanent magnet configurations at this scale.
- Ultra High Power:Specialized foundry capacity for cast iron housings concentrates in select industrial clusters, creating lead time vulnerability. Carbon border adjustment mechanisms will reshape sourcing economics for these high-material-content units.
Medium power ratings occupy the largest installed base, with low power units expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting gear motor production toward jurisdictions with favorable efficiency compliance costs. Manufacturers are relocating final assembly to exploit gaps between IEC mandate enforcement timelines across industrial clusters.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive demand for integrated drive systems with embedded diagnostics. The EU Green Deal carbon intensity benchmarks force foundries in Bavaria to document Scope 1-3 emissions for preferred supplier status. Industrial automation majors in North Rhine-Westphalia now mandate predictive maintenance data feeds as standard procurement terms.
China
Dual carbon goals and MIIT efficiency standards are accelerating淘汰 of IE1 and IE2 legacy units across Yangtze River Delta manufacturing hubs. GB standards compliance deadlines compress replacement cycles for induction motor-gearbox pairings in Shanghai and Suzhou automation corridors. NMPA-aligned quality protocols reshape supplier qualification for food processing equipment exports.
United States
US DOE integral horsepower motor rules strand non-compliant installed bases across Midwest automotive plants. Manufacturing reshoring initiatives in Michigan and Ohio create demand for digital twin-enabled gear motor diagnostics. E-commerce fulfillment operators in California now require uptime guarantees with predictive maintenance data feeds as vendor selection criteria.
Japan
METI efficiency roadmaps push permanent magnet synchronous motor adoption in Nagoya automotive assembly clusters. JIS standards certification timelines extend product launch cycles for servo gear motor configurations. Collaborative robot joint manufacturers in Osaka demand compact planetary configurations with safety-rated feedback systems.
Italy
REACH substance restrictions drive synthetic lubricant transitions across Emilia-Romagna packaging machinery manufacturers. CE marking compliance for IEC 60034-30-1 efficiency classes elevates system-level accountability over discrete component warranties. Foundries in Lombardy face EU Green Deal embodied energy disclosure mandates for cast iron housing exports.
Gear Motor Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents expand beyond discrete components into integrated motion subsystems. The vendor base concentrates around three tiers: diversified industrial conglomerates with automation stacks, specialized drive system integrators, and regional component fabricators. Two strategic archetypes have emerged—full-stack platform providers bundling diagnostics with hardware, and precision specialists targeting collaborative robotics torque density requirements. M&A activity and vertical integration into foundry capacity represent the dominant competitive moves as material traceability requirements tighten.
Within the diversified conglomerate tier, SEW-EURODRIVE GmbH & Co KG, Siemens AG, and Nidec Corporation exemplify contrasting geographic and structural positioning. SEW-EURODRIVE represents the German GmbH & Co KG format with integrated drive systems specialization. Siemens AG anchors the AG-listed industrial automation archetype with digital twin-enabled portfolio breadth. Nidec Corporation occupies the Japanese corporate structure focused on compact brushless DC configurations for precision motion segments.
| Leading Market Players |
|---|
| SEW-EURODRIVE |
| Siemens AG |
| ABB |
| Emerson Electric |
| Sumitomo Heavy Industries |
| Regal Rexnord Corporation |
| Nidec Corporation |
| Bonfiglioli |
| Bauer Gear Motor |
| Others |
Supply Flow & Price Mechanics
Copper winding costs cascade through three distinct pricing tiers as they migrate from Chilean and Zambian mining operations through German and Chinese motor manufacturers to automotive OEM procurement desks. Raw material volatility in rare earth magnets and cast iron foundry capacity further stratifies final assembly pricing across efficiency classes and regional compliance tiers.
Pricing Analysis
Distributor margins compress standard AC gear motor pricing by 12-18 points before reaching mid-sized manufacturing accounts, while direct-to-OEM contracts for integrated drive systems command premium positioning through embedded diagnostics bundling. Pricing stratifies across IE4 premium efficiency, IE3 standard compliance, and legacy IE2 economy tiers, with carbon border adjustment exposure now widening spreads between European-sourced and Asian-manufactured units. Cost compression in brushless DC configurations intensifies as Nidec Corporation and Chinese competitors expand high-volume production for collaborative robotics. Tier-1 automotive suppliers exhibit lowest price sensitivity given uptime guarantee requirements, whereas small-format packaging machinery buyers in Asian manufacturing clusters drive aggressive procurement negotiation.
Supply Chain Analysis
CE marking and IEC 60034-30-1 efficiency certification gating restricts European market access to foundries with documented Scope 1-3 emissions protocols, favoring German, Italian, and select Czech suppliers over unverified Asian producers. Rare earth magnet processing concentrates in China, Japan, and Malaysia, while specialized cast iron housing production rests on German and Italian foundry clusters with automotive-qualified capacity. Single-source vulnerability in neodymium supply chains from Chinese refining operations creates exposure for permanent magnet synchronous motor configurations. Distribution runs through authorized drive system integrators in Europe, direct OEM relationships in automotive, and industrial distributors in general machinery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gear motor market functions as a stable compounder anchored by irreversible automation intensity across material handling and intralogistics infrastructure. Efficiency regulation mandates create predictable replacement cycles that sustain manufacturer order books regardless of macroeconomic volatility.
For Market Incumbents: Cement technology leadership in servo gear motor integration by acquiring control systems engineering capabilities scarce in traditional gearbox workforces. Deepen backward integration into copper winding and rare earth magnet supply chains to defend margin position against commodity volatility. Prioritize digital twin-enabled diagnostics development to meet predictive maintenance data feed requirements from large-scale conveyor operators in the United States and Germany.
For New Entrants and Emerging Players: Launch via collaborative robot joint specialization targeting underpenetrated torque density requirements in human-robot interaction applications. Target food processing equipment segments in Europe where REACH-compliant synthetic lubricant and stainless steel housing expertise creates qualification barriers for established competitors. Pursue white-space penetration in medium-power servo configurations for automotive assembly plants seeking alternatives to SEW-EURODRIVE and Siemens AG portfolios.
For Investors and Strategic Acquirers: Consolidation pressure builds where foundry capacity scarcity intersects with carbon border adjustment compliance requirements for cast iron housing exports to European markets. Five-to-ten year viability favors vertically integrated manufacturers with captive rare earth magnet sourcing and certified low-carbon production pathways. Watch for inflection in MIIT enforcement timelines across Yangtze River Delta manufacturing hubs as signal for Chinese replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures permanent magnet synchronous motor cost stability against Chinese refining concentration. |
| Digital Twin Diagnostics Platform Launch | Meets predictive maintenance mandates from US e-commerce fulfillment and German automotive operators. |
| IE4 Efficiency Class Product Line Expansion | Captures replacement demand from IEC 60034-30-1 compliance deadlines in Germany and China. |
| Collaborative Robot Joint Specialization | Addresses torque density white space in human-robot interaction safety-rated feedback systems. |
| Carbon-Verified Foundry Capacity Acquisition | Qualifies preferred supplier status under EU Green Deal embodied energy disclosure mandates. |
Methodological Framework
Bottom-up manufacturing automation modeling reconciled against top-down motor production tracking forms the analytical core of this study. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at automotive and e-commerce fulfillment facilities informed demand-side assumptions. Secondary validation drew from IEC efficiency standard filings, US DOE integral horsepower motor rule dockets, SEC 10-K disclosures from listed industrial conglomerates, and customs trade data for copper winding and cast iron housing imports. Triangulation between end-use deployment surveys and supplier shipment records verified segment-level volume allocations.
Input-output matrices mapped gear motor specification flows across power ratings, efficiency classes, and motion control architectures throughout the projection horizon. Segmentation dimensions modeled include product type, application intensity, end-user concentration, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis of installed base vintages against compliance deadline schedules. Industry-specific forecast inputs incorporated MIIT enforcement trajectory assumptions for Chinese manufacturing hubs and carbon border adjustment implementation timing for European imports.
Several conditions sit outside the modeled scope, including abrupt rare earth export restrictions, foundry capacity disruptions from energy price spikes, and unilateral tariff impositions on motor-gearbox assemblies. Forecasts reflect documented assumptions regarding efficiency mandate adherence rates and automation capital expenditure continuity. A model refresh is warranted upon material change in IEC 60034-30-1 enforcement stringency or substantive revision to US DOE integral horsepower motor rules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Germany AC Motor Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Smart Motors Market
Industrial Motors
Hydraulic Motors Market