
 Seamless Steel Gas Cylinders Market | 2026-2036
Seamless Steel Gas Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
Seamless Steel Gas Cylinders Market Insights
Indian seamless steel cylinder producers is pivoting toward higher-pressure specifications to serve compressed natural gas and hydrogen mobility clients. Rama Cylinders leverages backward integration into steel billet supply to control input costs. Beijing Tianhai Industry anchors its position through captive heat-treatment capacity and ISO 9809 certification dominance. Worthington Industries sustains North American share via automated ultrasonic testing lines and DOT-3AA compliance depth.
Seamless steel gas cylinders are single-piece, hot-drawn or cold-drawn pressure vessels manufactured from chromium-molybdenum or manganese steel billets without longitudinal welds, designed to contain compressed gases at working pressures exceeding 150 bar. Industrial gas applications occupy the largest volume share as packaged gas distributors standardize on Type 1 cylinders for argon, nitrogen, and oxygen delivery. Medical gas demand is accelerating fastest among application categories, driven by home oxygen therapy expansion and hospital bulk system backups. Machined cylinders dominate premium pricing tiers where dimensional tolerances below 0.5 millimeters enable precision valve integration.
The U.S. DOT's Hazardous Materials Regulations and ISO 9809-1 govern wall thickness, hydrostatic test pressure, and periodic requalification cycles, effectively filtering out uncertified producers. China's SAMR enforces GB 5099 and GB/T 28053 standards for domestic cylinder circulation, creating a dual-compliance burden for exporters. India's PESO mandates IS 7285 certification for industrial gas cylinders, adding another layer of market access control. Stakeholders must monitor hydrogen embrittlement testing protocols as 700-bar hydrogen storage cylinders enter qualification pipelines.
Market Dynamics
Hydrogen mobility infrastructure buildouts are compressing qualification timelines for 700-bar storage systems while tightening metallurgical requirements across the supply base. Cylinder producers face simultaneous pressure to certify new pressure ratings and secure backward integration into heat-treatment capacity.
Growth Catalysts
- DOT-3AA Requalification Mandates:The U.S. Department of Transportation's shortened requalification cycles for high-pressure cylinders are accelerating replacement demand among industrial gas distributors.
- Home Oxygen Therapy Expansion:Medical device suppliers are scaling cylinder fleets to serve COPD patient populations in residential settings, particularly in Medicare-reimbursed markets.
- China Hydrogen Fuel Cell Vehicle Deployment:Domestic fleet scaling under the national hydrogen energy roadmap is concentrating orders for 35 MPa and 70 MPa storage systems with SAMR-certified producers.
Market Restraints
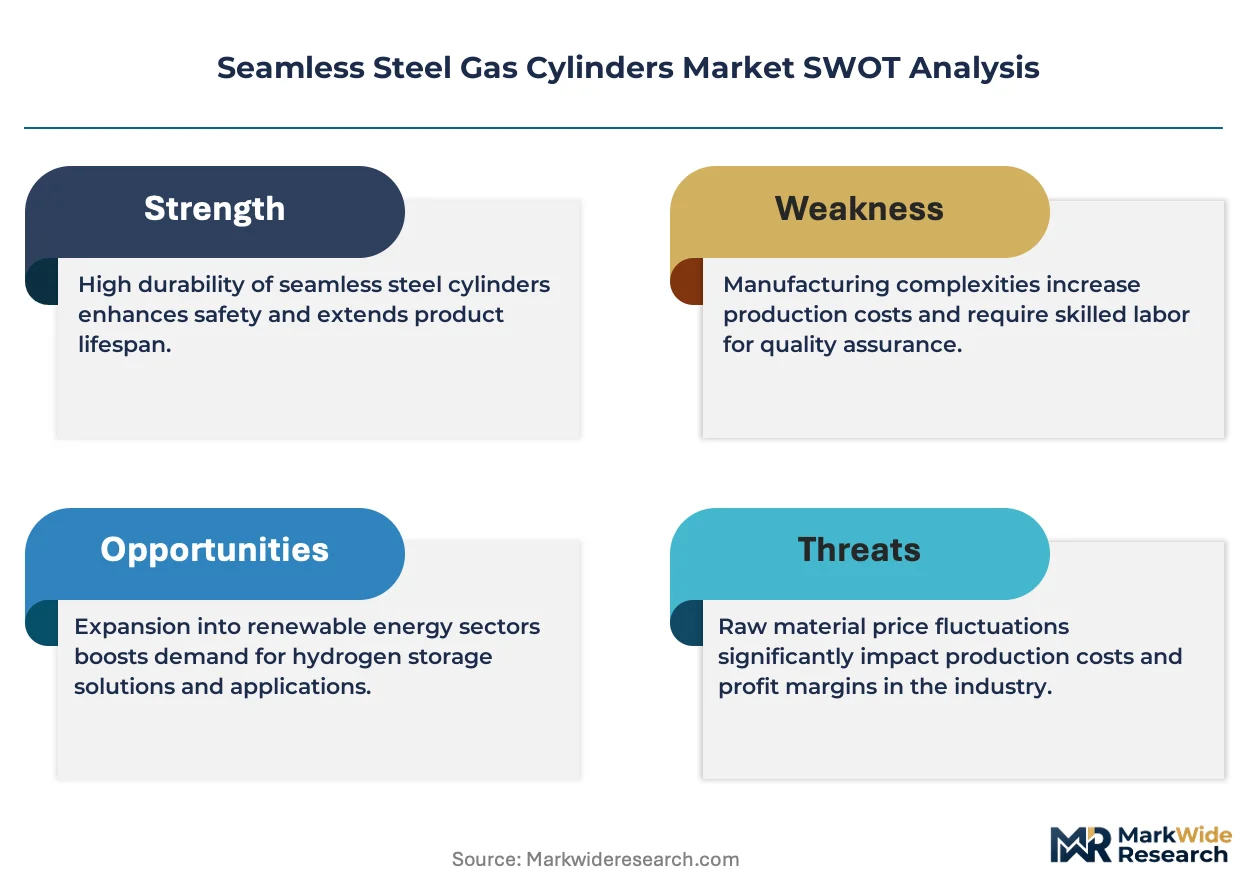
- Chromium-Molybdenum Steel Price Volatility:Alloy surcharges on billet inputs compress margin predictability for cylinder fabricators without captive steelmaking.
- Heat-Treatment Capacity Concentration:Quenching and tempering infrastructure clusters in select manufacturing basins, creating bottleneck risk during demand surges.
- Type 4 Composite Substitution:Carbon-fiber wrapped polymer liners are displacing steel in premium hydrogen storage applications above 500 bar working pressure.
Strategic Opportunities
- India CNG Mobility Infrastructure:City gas distribution expansion under the national CNG program creates cylinder demand from conversion workshops and fleet operators.
- ISO 19881 Hydrogen Testing Protocols:Early qualification to emerging hydrogen embrittlement standards positions producers for 700-bar automotive contracts.
- Telemedicine-Enabled Remote Patient Monitoring:Home healthcare platforms are bundling oxygen cylinder logistics with digital compliance tracking, opening channel partnerships.
Industry Challenges
- Ultrasonic Testing Technician Shortage:Automated NDT line operation requires specialized certification that outpaces vocational training program output.
- Multi-Jurisdiction Certification Stacking:Simultaneous pursuit of DOT, ISO 9809, and GB 5099 approvals extends product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seamless Steel Gas Cylinders Market |
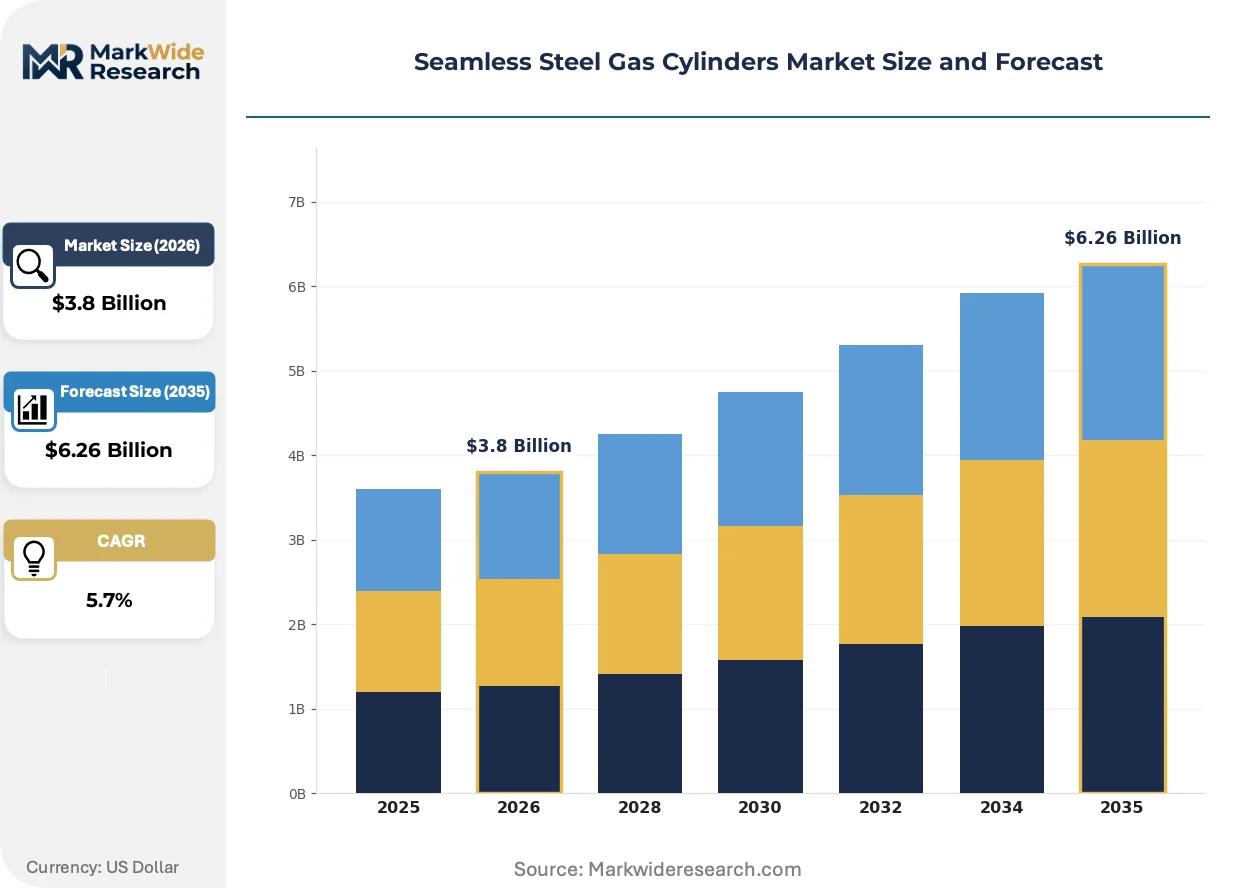
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Welded Cylinders, Machined Cylinders, Composite Cylinders, Standard Cylinders Application: Industrial Gas, Medical Gas, Firefighting, Beverage End User: Manufacturing, Healthcare, Hospitality, Automotive Size: Small, Medium, Large, Extra Large |
| Companies Covered | Rama Cylinders, Beijing Tianhai Industry, Worthington Industries, Faber Industrie, Shandong Huachen High Pressure Vessel Group, Everest Kanto Cylinder, Linde Group, NKTECH, Norris Cylinder Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seamless Steel Gas Cylinders Market Trends and Innovations
Metallurgical process control and inspection automation are converging to enable thinner-wall designs at equivalent safety margins. These advances are compressing material intensity per cylinder while expanding the addressable pressure range.
Quench-hardening simulation software is unifying thermal process design with predictive microstructure modeling. Tier-1 producers in Germany and Japan are deploying these digital twins to reduce physical prototype cycles for new alloy grades. This capability is compressing development timelines for 700-bar hydrogen-qualified steels from 36 months toward 18 months.
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is redirecting refrigerant cylinder demand toward natural refrigerant systems. Industrial gas distributors are retrofitting ammonia and CO2 recovery infrastructure, triggering cylinder fleet turnover for compatible pressure ratings. Food processing and cold chain logistics represent the most affected end-use verticals.
Hospital procurement departments are consolidating cylinder suppliers through multi-year managed service agreements. These contracts bundle equipment, maintenance, and telemetry-enabled inventory tracking, displacing transactional spot purchasing. The shift is most visible in U.S. health systems responding to CMS cost-containment mandates.
Seamless Steel Gas Cylinders Market Segmentation
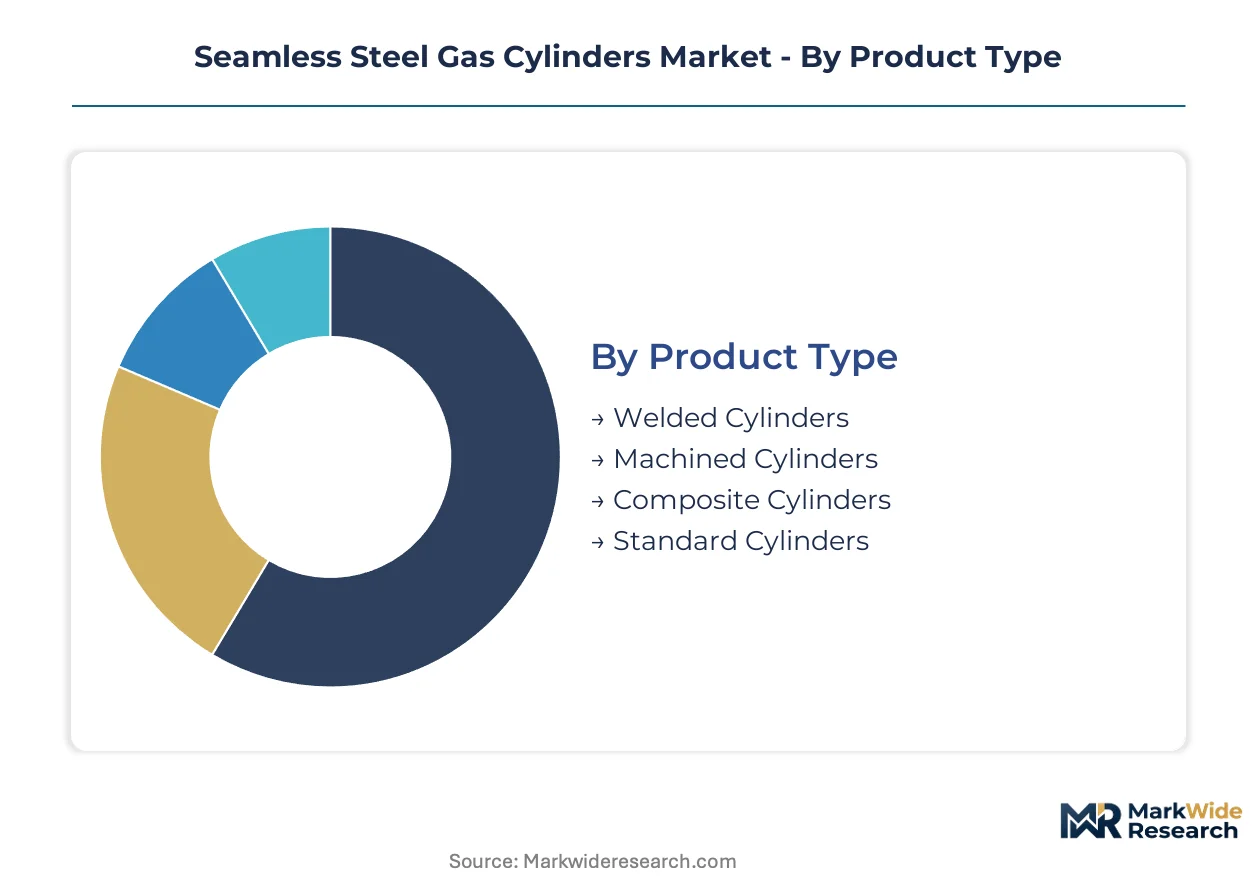
Seamless steel cylinder purchasing patterns diverge sharply between standalone equipment buyers and embedded system integrators. Equipment manufacturers prioritize dimensional precision for valve integration, while gas distributors optimize for fleet interchangeability. These integration-depth differences reshape how producers allocate heat-treatment capacity and certification investments.
Product Type:
Standalone cylinder deployments dominate industrial gas distribution, while embedded configurations concentrate in automotive hydrogen storage systems requiring frame-integrated mounting.
- Machined Cylinders:These hot-finished vessels undergo precision turning to achieve dimensional tolerances below 0.5 millimeters at neck and base interfaces. Demand clusters in medical oxygen systems where valve integration failures carry liability exposure, and in 700-bar hydrogen automotive applications where thread precision prevents seal degradation under thermal cycling.
- Standard Cylinders:Cold-drawn or hot-drawn vessels produced to ISO 9809-1 or DOT-3AA specifications without secondary machining operations. Industrial gas distributors in packaged argon and nitrogen applications standardize on this tier for fleet interchangeability, though margin compression from alloy steel volatility limits producer pricing power.
- Welded Cylinders:Longitudinally seam-welded pressure vessels serving lower-pressure industrial applications where seamless construction cost cannot be justified.
- Composite Cylinders:Type 4 carbon-fiber wrapped polymer liners displacing steel above 500 bar working pressure in premium hydrogen mobility segments.
Standard cylinders lead volumes today; machined cylinders are gaining share fastest.
Application:
Cost tier stratification separates commodity industrial gas handling from premium medical and safety-critical applications where certification depth determines supplier selection.
- Industrial Gas:Packaged distribution of argon, nitrogen, and oxygen to fabrication shops and chemical plants. Fleet turnover accelerates under DOT requalification mandates, with distributors consolidating suppliers to reduce compliance overhead.
- Medical Gas:Home oxygen therapy cylinders and hospital bulk system backups. COPD patient population expansion in Medicare-reimbursed markets drives cylinder fleet scaling, with procurement shifting toward managed service agreements bundling equipment and logistics.
- Firefighting:Self-contained breathing apparatus and suppression system cylinders. Regulatory requalification cycles match industrial pressure equipment standards.
- Beverage:Carbon dioxide cylinders for fountain dispensing and brewery service. Food-grade internal surface specifications add processing cost relative to industrial equivalents.
Industrial gas dominates volume concentration; medical gas shows steepest expansion trajectory.
End User:
Customer type fragmentation creates divergent procurement patterns between capital-equipment buyers and consumable-gas renters.
- Manufacturing:Metal fabrication, chemical processing, and electronics production facilities operating captive cylinder fleets or contracted gas supply. Demand correlates with industrial production indices and welding process automation adoption.
- Healthcare:Hospital systems and home medical equipment suppliers. CMS cost-containment mandates are consolidating supplier bases toward multi-year managed service agreements with telemetry-enabled inventory tracking.
- Hospitality:Restaurants, bars, and hotels operating beverage carbonation systems. Price sensitivity limits specification upgrading beyond minimum safety compliance.
- Automotive:Hydrogen fuel cell vehicle manufacturers and conversion workshops. China's national hydrogen energy roadmap concentrates orders with SAMR-certified domestic producers.
Manufacturing leads absolute consumption; automotive is climbing the fastest.
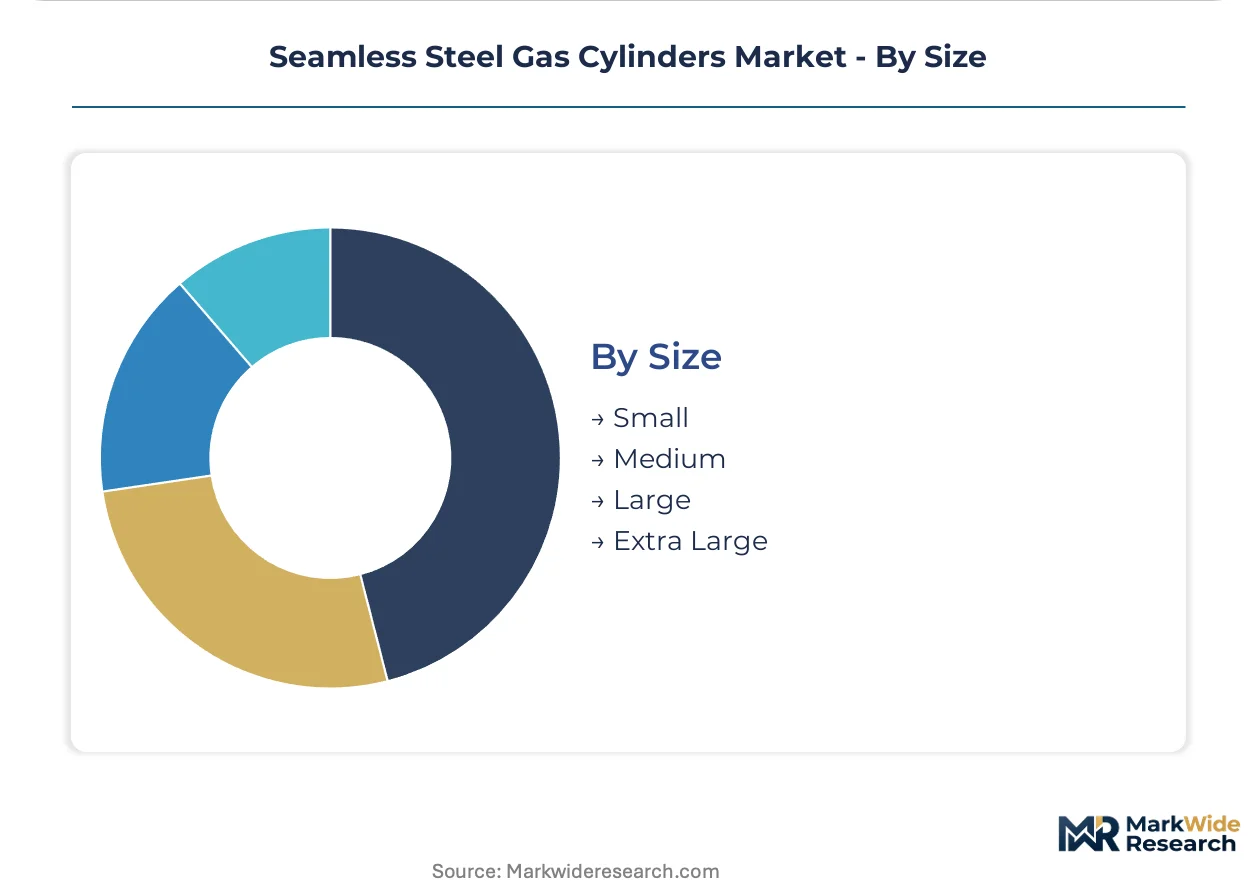
Size:
Volume-maturity dynamics separate established small-cylinder logistics networks from emerging large-format hydrogen storage systems.
- Medium:Cylinders in the 40-50 liter water capacity range standard for industrial gas distribution and medical oxygen service. Fleet interchangeability requirements lock in dimensional standards across regional markets.
- Large:High-pressure vessels exceeding 80 liters water capacity for stationary hydrogen storage and tube trailer applications. Metallurgical requirements intensify with wall thickness and heat-treatment uniformity demands.
- Small:Portable cylinders below 20 liters for emergency medical service and specialty gas sampling. Distribution runs through specialized medical equipment channels with higher service intensity.
- Extra Large:Jumbo cylinders and tube trailers for bulk gas distribution and hydrogen refueling station storage. Limited producer base with captive heat-treatment capacity requirements.
Medium cylinders anchor current volumes; large cylinders show strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as compliance cost differentials between jurisdictions widen. Cylinder fabricators migrate toward markets with streamlined certification pathways while maintaining export access through mutual recognition agreements.
United States
DOT-3AA requalification mandates are accelerating fleet turnover among industrial gas distributors. The Department of Transportation's Hazardous Materials Regulations enforce shortened inspection cycles for high-pressure cylinders. Manufacturing concentrates in Ohio and Pennsylvania, where automated ultrasonic testing infrastructure serves packaged gas distributors.
Germany
Quench-hardening simulation software adoption is compressing development timelines for 700-bar hydrogen-qualified steels. The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases redirects refrigerant cylinder demand toward ammonia-compatible pressure ratings. Industrial clusters in Bavaria and North Rhine-Westphalia anchor precision machining capacity for medical oxygen systems.
China
Hydrogen fuel cell vehicle deployment under the national hydrogen energy roadmap concentrates orders for 35 MPa and 70 MPa storage systems. SAMR enforces GB 5099 and GB/T 28053 standards, creating dual-compliance burdens for exporters. Beijing-Tianjin-Hebei and Yangtze River Delta manufacturing basins dominate captive heat-treatment capacity.
India
City gas distribution expansion under the national CNG program generates cylinder demand from conversion workshops and fleet operators. PESO mandates IS 7285 certification for industrial gas cylinders, controlling market access. Rama Cylinders leverages backward integration into steel billet supply in Maharashtra and Gujarat to control input costs.
Japan
Metallurgical process control advances enable thinner-wall designs at equivalent safety margins for precision valve integration. METI oversees alignment with ISO 9809-1 and emerging ISO 19881 hydrogen embrittlement protocols. Chubu and Kansai industrial corridors host Tier-1 producers deploying digital twins for alloy grade development.
Seamless Steel Gas Cylinders Market Competitive Landscape
Chinese producers anchor the scale-driven tier; European and North American specialists hold premium positioning through certification depth and precision machining. Market structure fragments across three strategic archetypes: integrated steel-to-cylinder fabricators with captive billet supply, precision machinists serving medical and hydrogen automotive specifications, and regional distributors with fleet management capabilities. Dominant competitive moves include backward integration into heat-treatment capacity and multi-jurisdiction certification stacking to compress product launch timelines.
Among Asia-Pacific fabricators, Beijing Tianhai Industry and Rama Cylinders exemplify the integrated archetype through steel billet control and captive heat-treatment infrastructure. Worthington Industries occupies a position within the North American precision tier, representing automated non-destructive testing deployment. Faber Industrie and Shandong Huachen High Pressure Vessel Group sit within the regional specialist category, serving distinct certification jurisdictions.
| Leading Market Players |
|---|
| Rama Cylinders |
| Beijing Tianhai Industry |
| Worthington Industries |
| Faber Industrie |
| Shandong Huachen High Pressure Vessel Group |
| Everest Kanto Cylinder |
| Linde Group |
| NKTECH |
| Norris Cylinder Company |
| Others |
Pricing and Supply Chain Analysis
Quench-hardening simulation software deployment across German and Japanese Tier-1 producers is compressing alloy development cycles from 36 months toward 18 months, simultaneously reducing prototype costs and concentrating metallurgical expertise in manufacturing basins with captive heat-treatment infrastructure. This technological shift feeds back into pricing power asymmetries between integrated fabricators and commodity cylinder assemblers.
Pricing Analysis
Distributor margins in packaged industrial gas applications absorb alloy surcharge volatility through fleet standardization on ISO 9809-1 standard cylinders, while direct-to-OEM contracts for 700-bar hydrogen systems command premium positioning through DOT-3AA and SAMR certification bundling. Price differentiation separates machined medical-grade cylinders with sub-0.5 millimeter tolerances from cold-drawn industrial equivalents. Cost compression in standard cylinder tiers intensifies as chromium-molybdenum billet prices fluctuate. Healthcare procurement committees show least price sensitivity due to liability exposure from valve integration failures.
Supply Chain Analysis
Ultrasonic testing technician shortages in Ohio, Pennsylvania, and Bavaria constrain automated NDT line expansion despite accelerating demand. Manufacturing concentrates in China, India, and Germany, with captive heat-treatment capacity anchoring production geography. Raw material flows draw from chromium-molybdenum steel billet suppliers in integrated steelmaking regions. Single-source vulnerability concentrates in quenching and tempering infrastructure clusters. Distribution runs through industrial gas distributors with fleet interchangeability requirements and hospital procurement departments consolidating toward managed service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where DOT requalification mandates and hydrogen embrittlement testing protocols under ISO 19881 generate replacement demand and certification barriers simultaneously.
For Market Incumbents: Hedge alloy cost exposure through backward integration into steel billet supply or long-term offtake agreements with manganese and chromium-molybdenum producers. Defend against Type 4 composite substitution above 500 bar by accelerating 700-bar hydrogen qualification pipelines and securing SAMR certification for Chinese automotive contracts. For New Entrants and Emerging Players: Capture white-space in India's city gas distribution expansion under the national CNG program, where IS 7285 certification requirements filter out uncertified competitors. Target precision machining capacity for medical oxygen systems in Medicare-reimbursed markets, deploying telemedicine-enabled remote patient monitoring partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with fleet management capabilities but limited heat-treatment integration. Long-term viability favors fabricators with multi-jurisdiction certification stacking and captive metallurgical process control. Monitor hydrogen fuel cell vehicle deployment rates in China's Beijing-Tianjin-Hebei corridor as the inflection signal for 70 MPa storage system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Billet Supply | Rama Cylinders controls input costs through captive manganese and chromium-molybdenum sourcing in Maharashtra. |
| Multi-Jurisdiction Certification Stacking | Simultaneous DOT-3AA, ISO 9809-1, and GB 5099 pursuit compresses product launch timelines for automotive hydrogen contracts. |
| Automated Ultrasonic Testing Deployment | Worthington Industries sustains North American share through NDT line investment serving industrial gas distributors. |
| ISO 19881 Hydrogen Embrittlement Qualification | Early adoption positions producers for 700-bar automotive storage systems ahead of SAMR enforcement timelines. |
| Managed Service Agreement Structuring | Hospital procurement consolidation under CMS cost-containment mandates favors telemetry-enabled inventory tracking bundling. |
Research Methodology
Direct dialogue with cylinder fabrication plant managers, industrial gas distributor procurement leads, hospital biomedical engineers, and automotive hydrogen storage system engineers grounded qualitative assessment. Secondary validation drew from DOT Hazardous Materials Regulations filings, SAMR GB standard enforcement notices, PESO certification databases, and SEC disclosures from packaged gas distributors. Bottom-up volume builds across product type, application, and size segments triangulated against top-down macroeconomic indicators.
Output projections across the analysis window reflect segment-level growth rate derivation from industrial production indices, hydrogen fuel cell vehicle deployment roadmaps, and medical oxygen therapy reimbursement trends. Modeled dimensions span machined versus standard cylinder construction, industrial gas versus medical gas application, and manufacturing versus healthcare end-use. CAGRs emerged from regression against historical fleet turnover patterns and regulatory requalification cycle compression.
Underlying measurement precision varies by segment; industrial gas applications carry tighter precision than emerging hydrogen automotive categories due to established DOT requalification data. Forecasts reflect assumptions around alloy price stability and certification timeline execution. Practitioners should monitor SAMR enforcement intensity for GB/T 28053 compliance and Type 4 composite cylinder cost curves for substitution acceleration signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
United States DC Motor Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Asia-Pacific Induction Motor Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
China AC Motor Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market