
 Latin America Electric Drives Market | 2026-2036
Latin America Electric Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Electric Drives Market Foresight
Modular drive packaging is realigning procurement patterns across Latin American industrial buyers. WEG SA anchors its competitive stance through deep manufacturing scale in Brazilian motor and drive production. Siemens AG leverages integrated automation portfolios to compete in Mexico's automotive supplier tier. Schneider Electric differentiates through energy management software bundled with hardware platforms.
Electric drives are electromechanical systems that regulate motor speed, torque, and rotational direction through power electronic converters, typically operating at voltage classes from 230V to 690V and frequency ranges up to several hundred hertz for industrial motor control. AC Drives dominate installed capacity across Latin American process industries due to their compatibility with existing induction motor fleets and lower maintenance profiles. Servo Drives command premium positioning in precision manufacturing applications where motion control accuracy dictates output quality. Variable Frequency Drive technology leads technology adoption as facilities retrofit fixed-speed pump and fan systems for demand-responsive operation.
Brazil's INMETRO certification requirements and Mexico's CFE energy efficiency standards shape product compliance pathways for equipment suppliers entering these markets. ANEEL grid codes in Brazil additionally influence regenerative drive specifications for power generation interconnection. Stakeholders must monitor evolving efficiency tier migrations and local content rules as governments tighten industrial electrification policies.
Market Dynamics
Modular drive packaging is restructuring Latin American industrial procurement by decoupling power modules from control electronics, enabling Brazilian and Mexican facilities to stage capital deployment across budget cycles rather than committing to monolithic systems upfront.
Growth Catalysts
- INMETRO certification mandates:Brazil's mandatory efficiency labeling for industrial motors is forcing manufacturing plants to replace fixed-speed equipment with variable frequency drives, creating replacement demand across São Paulo state's automotive supplier base.
- Mining motor system upgrades:Brazilian iron ore and copper extraction operations are retrofitting conveyor and pump systems with regenerative drives to recover braking energy and reduce grid consumption in remote locations.
- CFE efficiency standards:Mexico's Federal Electricity Commission tightened minimum performance requirements for industrial equipment, compelling manufacturers in Querétaro and Guanajuato to accelerate drive modernization timelines.
Market Restraints
- IGBT and silicon carbide supply concentration:Power semiconductor sourcing remains concentrated among Asian foundries, exposing Latin American drive assemblers to lead time volatility and currency-driven input cost swings.
- ANEEL grid code complexity:Brazil's national electric energy agency imposes stringent regenerative power quality requirements that extend engineering validation timelines and raise non-recurring engineering costs for drive suppliers.
- Electromechanical relay substitution:Basic motor starters retain cost advantage in low-duty-cycle applications across small-scale Mexican metalworking shops, limiting addressable market for sophisticated drive solutions.
Strategic Opportunities
- Colombian manufacturing expansion:Underpenetrated industrial corridors around Medellín and Bogotá present first-mover potential as the country's textile and food processing sectors automate legacy production lines.
- Edge analytics convergence:Integration of vibration monitoring algorithms with drive firmware creates predictive maintenance value propositions for Chilean mining operations seeking to reduce unplanned downtime.
- Argentina energy tariff restructuring:Subsidy reduction programs are improving payback calculations for efficiency investments, opening industrial drive demand in Buenos Aires province's chemical processing cluster.
Industry Challenges
- Power electronics engineering scarcity:Latin American technical universities produce insufficient graduates with embedded control and thermal management expertise to support drive OEM expansion plans.
- Legacy fieldbus integration:Decades-old PROFIBUS and DeviceNet installations in Brazilian process plants complicate retrofit projects, requiring protocol gateway engineering that extends commissioning schedules.
- Dual certification burden:Suppliers must simultaneously satisfy INMETRO efficiency testing and CFE electromagnetic compatibility validation, duplicating documentation and laboratory costs for pan-regional product strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Electric Drives Market |
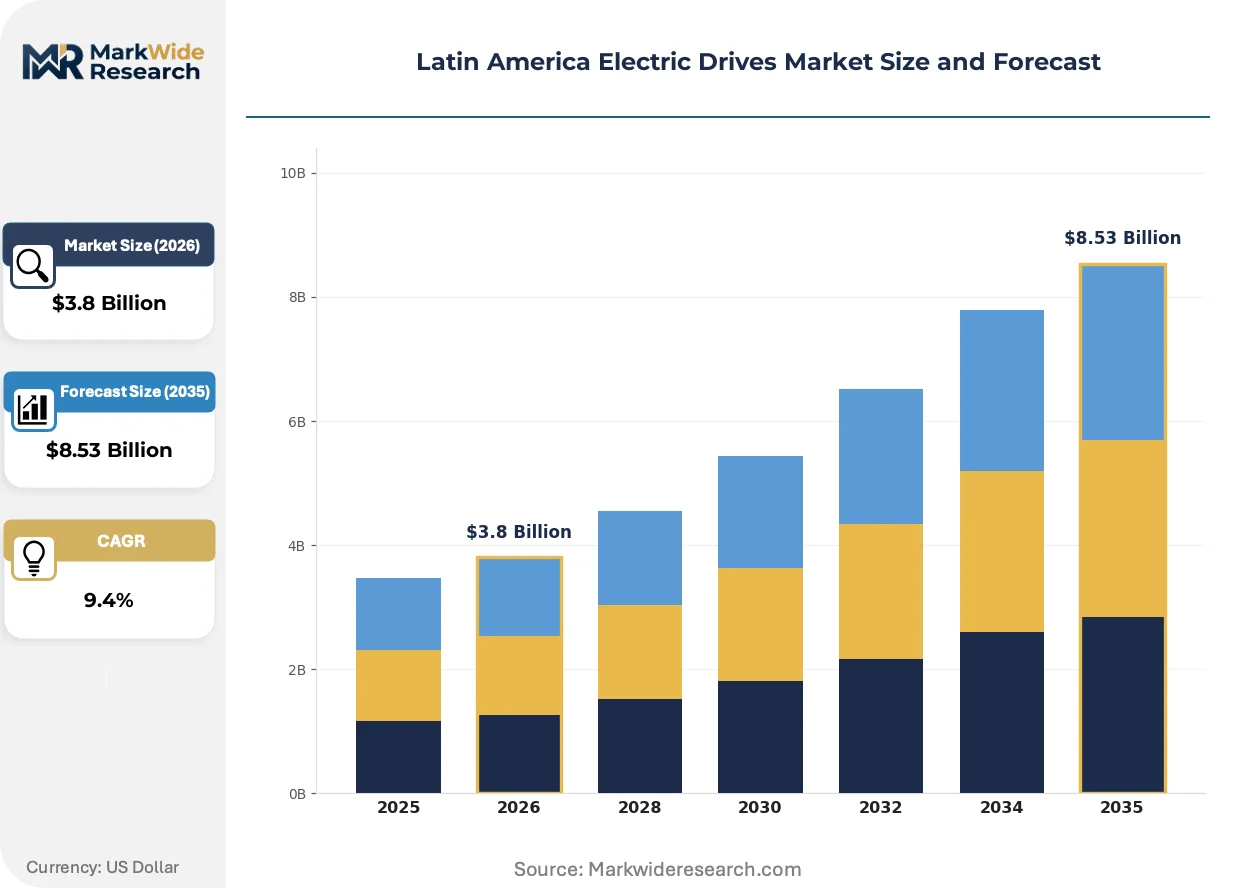
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, Soft Starters End User: Manufacturing, Oil & Gas, Transportation, Power Generation Technology: Variable Frequency Drive, Direct Online, Programmable Logic Control, Motion Control Application: Pumps, Fans, Conveyors, Compressors |
| Companies Covered | ABB Ltd., Rockwell Automation Inc., Siemens AG, Schneider Electric, Mitsubishi Electric Corporation, Danfoss, WEG SA, Emerson Electric, Nidec Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Electric Drives Market Shifts & Advancements
Silicon carbide power semiconductors and edge-native control architectures are compressing drive form factors while enabling new service revenue models. Equipment suppliers are repositioning hardware margins toward software-enabled performance guarantees.
Silicon carbide MOSFETs are replacing insulated-gate bipolar transistors in mid-voltage drive platforms, cutting switching losses by half and permitting passive cooling in harsh mining environments. Chilean copper concentrators and Brazilian pulp mills are piloting these systems for conveyor and refiner applications. The technology is consolidating supplier tiers by forcing legacy IGBT-focused drive houses to requalify thermal designs or cede premium efficiency segments.
CFE's 2024 update to NOM-001-SEDE electrical standards mandates harmonic distortion limits for industrial facilities above 500kW contracted demand. Mexican automotive stamping plants and appliance manufacturers must install active front-end drives or external filters to maintain grid connection permits. The regulation is accelerating adoption of regenerative drive architectures in Guanajuato's supplier parks where multiple plants share substation infrastructure.
Industrial buyers are unbundling hardware acquisition from commissioning and lifecycle service contracts, treating drive systems as operational expenditures rather than capital assets. Brazilian sugar-ethanol processors and Mexican cement producers now favor multi-year performance agreements with remote monitoring provisions over traditional equipment purchase. This pattern concentrates most visibly in São Paulo state's chemical sector, where facilities prioritize uptime guarantees over brand loyalty in supplier selection.
Latin America Electric Drives Market Segmentation
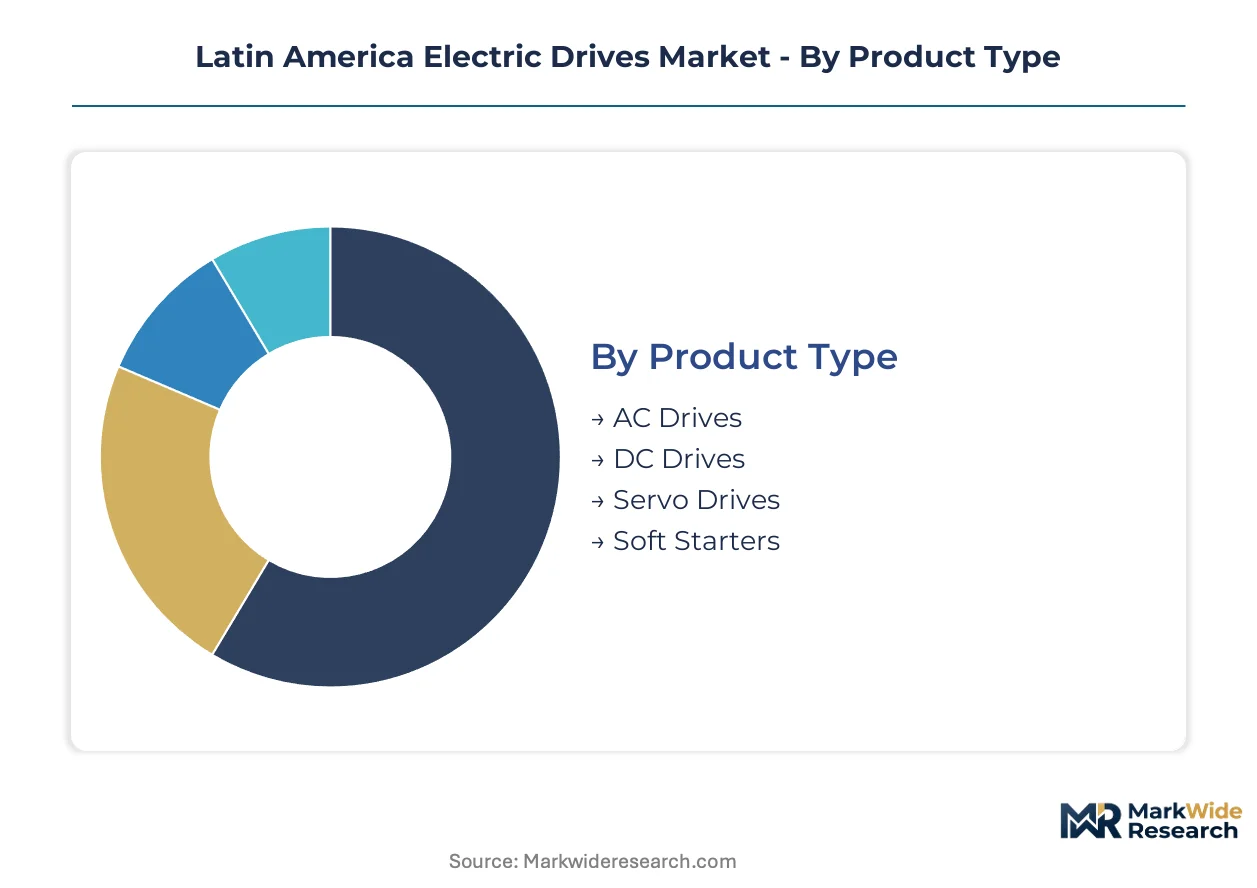
Electric drive segmentation in Latin America reflects divergent certification burdens across product architectures. INMETRO efficiency labeling applies differentially to AC versus DC platforms, while CFE harmonic standards constrain technology selection in Mexico's heavy industrial zones.
Product Type:
Certification pathways fragment sharply across voltage classes and switching technologies, with INMETRO's efficiency tiers and CFE's electromagnetic compatibility rules forcing distinct compliance investments per segment.
- AC Drives:Power electronic converters operating at 230V to 690V classes dominate Brazilian installed capacity through compatibility with existing induction motor fleets. Demand concentrates in São Paulo state's automotive supplier belt where INMETRO mandates are forcing fixed-speed replacements.
- Servo Drives:Precision motion control systems with closed-loop feedback command premium positioning in Mexican automotive stamping plants. Querétaro's supplier parks favor these for robotic welding lines where positional accuracy dictates output quality.
- DC Drives:Thyristor-based speed regulation retains niche presence in legacy Brazilian steel mill installations.
- Soft Starters:Reduced-voltage motor starting equipment serves cost-sensitive Mexican metalworking shops with low-duty-cycle requirements.
Leading the category by volume: AC Drives. Growing fastest: Servo Drives.
End User:
Customer procurement sophistication varies dramatically, with mining and automotive sectors demanding predictive maintenance integration while power generation prioritizes grid code compliance.
- Manufacturing:Automotive, appliance, and food processing facilities across Guanajuato and São Paulo states drive standardization around modular drive architectures. CFE's tightened efficiency mandates are compressing payback calculations for modernization investments.
- Oil & Gas:Upstream and midstream operations in Brazil's pre-salt basins specify explosion-proof enclosures and regenerative braking for offshore platform cranes. ANEEL grid code complexity extends engineering validation timelines for these installations.
- Transportation:Metro systems and port logistics in Buenos Aires and Valparaíso specify drives for traction and material handling.
- Power Generation:Hydroelectric and thermal plants in Minas Gerais state require ANEEL-compliant regenerative drives for turbine governor systems.
Manufacturing commands the largest share by unit volume. Oil & Gas exhibits the steepest expansion trajectory as pre-salt development accelerates.
Technology:
Adoption patterns track facility electrification maturity, with Variable Frequency Drive penetration highest where energy tariffs justify efficiency retrofits.
- Variable Frequency Drive:Demand-responsive pump and fan control through adjustable output frequency leads technology adoption across Latin American process industries. Brazilian sugar-ethanol processors favor these for irrigation and milling applications where seasonal load profiles vary.
- Motion Control:Multi-axis synchronization systems serve precision manufacturing in Mexico's aerospace supplier tier. Guanajuato's automation clusters specify these for CNC machining centers requiring coordinated spindle and axis positioning.
- Direct Online:Basic across-the-line starting persists in small-scale Argentine food processing where capital constraints limit sophistication.
- Programmable Logic Control:Integrated drive-PLC combinations simplify retrofit projects in Chilean mining conveyors with legacy fieldbus infrastructure.
Variable Frequency Drive holds the dominant position by installed base. Motion Control is climbing the fastest as precision manufacturing expands.
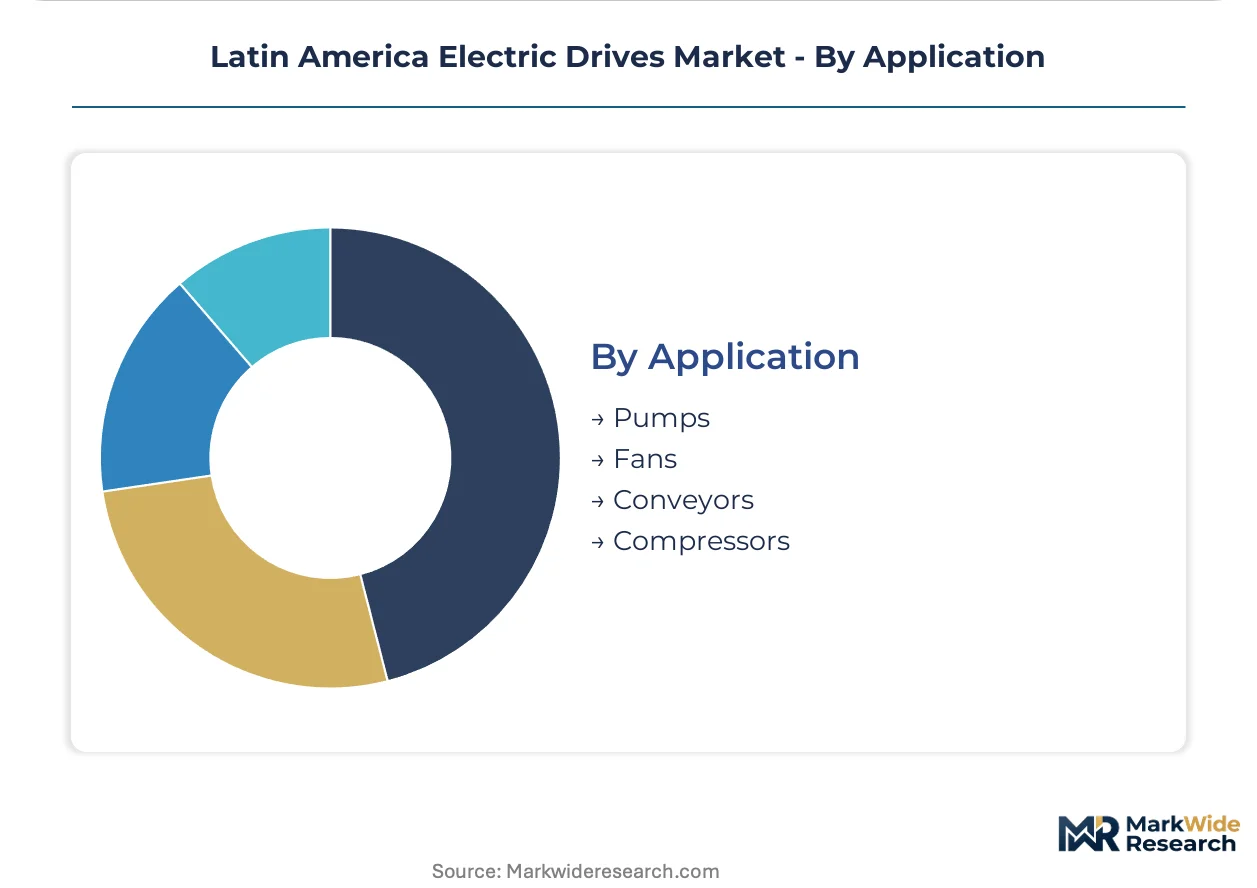
Application:
Load characteristics determine drive specification complexity, with centrifugal pumps and fans favoring standard VFD platforms while compressors demand torque-control variants.
- Pumps:Centrifugal and positive displacement configurations in Brazilian water treatment and mining slurry transport represent the largest addressable application. INMETRO-certified drives are displacing throttling valve control in São Paulo's municipal distribution networks.
- Fans:HVAC and process ventilation systems in Mexican cement plants specify drives for damper replacement. CFE's harmonic distortion limits for facilities above 500kW contracted demand are accelerating active front-end adoption in shared substation environments.
- Conveyors:Bulk material handling in Chilean copper concentrators and Brazilian iron ore operations requires regenerative braking for downhill sections.
- Compressors:Air and refrigeration compression in Buenos Aires province's chemical cluster demands constant torque control profiles.
Pumps lead by unit shipments. Fans are gaining share fastest on the back of CFE regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives concentrate drive assembly capacity in Brazil's northern Amazonas state, drawing component suppliers toward duty-advantaged manufacturing corridors.
Brazil
Mining conveyor retrofits and automotive supplier belt modernization dominate demand. ANEEL grid codes enforce regenerative power quality standards for industrial interconnection. São Paulo state's chemical processing cluster favors multi-year performance agreements with remote monitoring provisions over traditional equipment purchase.
Mexico
Automotive stamping plants and aerospace supplier tiers drive precision motion control procurement. CFE's 2024 NOM-001-SEDE update mandates harmonic distortion limits for facilities above 500kW contracted demand. Guanajuato's supplier parks accelerate active front-end drive adoption in shared substation environments.
Chile
Copper concentrator bulk material handling requires regenerative braking for downhill conveyor sections. The country's national mining regulator emphasizes energy recovery specifications for remote extraction sites. Valparaíso port logistics specify drives for material handling automation.
Colombia
Textile and food processing automation present first-mover potential in underpenetrated industrial corridors. The national standards body shapes efficiency labeling requirements for imported industrial equipment. Medellín's manufacturing belt automates legacy production lines with staged capital deployment.
Argentina
Energy tariff restructuring improves payback calculations for efficiency investments in chemical processing. Subsidy reduction programs alter industrial facility electrification economics. Buenos Aires province's processing cluster opens demand for variable frequency drive retrofits.
Latin America Electric Drives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin American procurement channels. The market structures around three tiers: integrated automation portfolios, regional manufacturing scale players, and component-focused technology licensors. Strategic moves concentrate on modular platform standardization and service contract bundling rather than pure hardware margin capture.
Within the integrated automation tier, ABB Ltd. and Siemens AG occupy positions spanning drive hardware through control software ecosystems. WEG SA anchors regional manufacturing scale from Brazilian production bases. Rockwell Automation Inc. exemplifies the portfolio diversification archetype, sitting within industrial automation systems rather than standalone drive supply. These three represent distinct competitive vectors: global technology integration, regional captive production, and automation-centric bundling.
| Leading Market Players |
|---|
| ABB Ltd. |
| Rockwell Automation Inc. |
| Siemens AG |
| Schneider Electric |
| Mitsubishi Electric Corporation |
| Danfoss |
| WEG SA |
| Emerson Electric |
| Nidec Corporation |
| Others |
Supply & Pricing Matrix
Brazilian automotive supplier procurement concentration around São Paulo state's manufacturing belt anchors the dominant contract-based pricing model for electric drives. CFE-mandated efficiency retrofits in Mexico's Guanajuato supplier parks amplify volume-scale negotiations, compressing hardware margins while elevating after-sales service premiums.
Pricing Analysis
Short lead-time premiums of 15-25 percent over standard delivery schedules separate urgent replacement demand from planned modernization budgets across Latin American industrial buyers. Three-tier pricing structure across premium silicon carbide platforms, standard IGBT-based systems, and economy soft starters reflects INMETRO certification grade and thermal performance tier. Cost compression in standard AC drive segments intensifies as Asian component assemblers expand direct distribution into Colombian and Argentine markets. Small-scale Mexican metalworking shops exhibit highest price sensitivity, while Brazilian mining operators prioritize regenerative braking efficiency over unit acquisition cost.
Supply Chain Analysis
Freight cost volatility from Asian semiconductor hubs through Pacific shipping lanes adds 8-12 percent landed cost variance for Brazilian drive assemblers sourcing IGBT and silicon carbide modules. Power electronics manufacturing concentrates in China, South Korea, and Japan, with Latin American facilities dependent on imported power modules, control boards, and thermal management components. Single-source vulnerability in silicon carbide substrate supply threatens production schedules for premium efficiency drive platforms. Distribution runs through authorized distributor networks serving industrial maintenance departments, with direct OEM relationships dominating mining and automotive tier-one procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power semiconductor foundry capacity constraints in East Asia prop pricing power for drive suppliers with secured component allocation. Equipment buyers face extended delivery horizons that favor incumbents with inventory buffers over spot-market dependent competitors.
For Market Incumbents: Anchor defensive positioning through backward integration into power module assembly in Brazil's Manaus Free Trade Zone, insulating against Asian foundry lead time volatility. Deepen captive service network density across Chilean mining corridors to lock out emerging predictive maintenance specialists. Certification investment in simultaneous INMETRO and CFE compliance documentation creates switching costs for pan-regional accounts. For New Entrants and Emerging Players: Silicon carbide thermal management algorithms offer entry wedge into premium efficiency segments where incumbent IGBT-focused houses lag requalification timelines. Colombian textile automation and Argentine chemical processing clusters present most penetrable white-space targets given underdeveloped distributor coverage. Edge-native vibration analytics bundled with hardware procurement contracts provides differentiated go-to-market angle against traditional capital-sale incumbents. For Investors and Strategic Acquirers: The window for entry favors mid-cap drive specialists with established INMETRO certification pathways and Brazilian manufacturing presence. Long-term viability hinges on software-enabled service revenue conversion rather than pure hardware margin capture. Watch ANEEL grid code amendments for regenerative drive specifications as inflection indicator for power generation interconnection demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Module Assembly | Manaus Free Trade Zone production reduces landed cost exposure to Asian semiconductor supply volatility. |
| Silicon Carbide Platform Requalification | Passive cooling capability opens premium efficiency segments in Chilean copper concentrator applications. |
| Multi-Year Performance Service Contracts | São Paulo chemical sector procurement patterns prioritize uptime guarantees over equipment brand loyalty. |
| Edge Analytics Firmware Integration | Vibration monitoring algorithms embedded in drive control boards create predictive maintenance revenue streams. |
| Dual Certification Documentation Investment | Simultaneous INMETRO efficiency and CFE electromagnetic compatibility validation reduces pan-regional sales friction. |
Research Methodology
Trade publications, customs import records, and national energy regulator filings formed the secondary backbone for demand quantification. Primary interviews with maintenance directors at Brazilian mining operations, procurement leads at Mexican automotive Tier 1 suppliers, plant engineers at Chilean copper concentrators, and aftermarket service heads at regional drive distributors informed operational assumptions. Bottom-up and top-down triangulation validated segment-level estimates against aggregate industrial electricity consumption patterns.
Bottom-up modeling tracked equipment replacement cycles, regulatory compliance deadlines, and facility electrification investments across the projection horizon. Segmentation dimensions included voltage class, switching technology, end-use industry, and regional regulatory cluster. CAGRs derived from fitted adoption curves for Variable Frequency Drive retrofits and silicon carbide technology substitution rates. Forecast inputs incorporated INMETRO efficiency tier migration schedules and CFE harmonic distortion enforcement timelines.
Several conditions sit outside the modeled scope, including unannounced subsidy restructuring in Argentina, abrupt ANEEL grid code amendments, and geopolitical disruption to Asian semiconductor supply chains. Forecasts reflect documented assumptions about industrial electricity tariff trajectories and mining capital expenditure continuity. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Power Scraper Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
HVAC Motors Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Smart Motors Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
United Kingdom DC Motor Market