
 Electric Vehicle Charging Management Software Market | 2026-2036
Electric Vehicle Charging Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charging Management Software Market Insights
Multi-source platform integration is expanding as fleet operators and charge point owners seek vendor-agnostic orchestration rather than single-stack dependency. ChargePoint Holdings, Inc. leverages its hardware-software coupling to sustain network density advantages across North American deployments. Driivz Ltd. anchors large-scale utility integrations in Europe with utility-grade billing and grid-balancing modules. AMPECO Ltd. differentiates through white-label flexibility that lets energy retailers and mobility providers control branded customer experiences.
Electric vehicle charging management software comprises middleware and application layers that govern session authentication, load balancing, tariff optimization, and grid interconnection across heterogeneous charger fleets. The stack typically exposes REST APIs for third-party integration while embedding OCPP protocol handlers to normalize communication across hardware vendors. Cloud-based deployment leads among operators managing geographically distributed assets, though edge computing segments are gaining traction where millisecond-level load response matters for grid stability. Fleet operators represent the fastest-growing end user category as logistics electrification intensifies charging complexity at depots. Smart grid integration technology commands premium positioning as utilities impose demand charges and time-of-use structures that reward predictive load shaping.
The US Federal Energy Regulatory Commission and state public utility commissions shape market access through interconnection standards and demand response program eligibility. Europe's ECHA and national regulators enforce cybersecurity and data portability mandates under the EU AI Act and GDPR that complicate cross-border platform architectures. Stakeholders must monitor how ISO 15118 plug-and-charge standards and evolving NERC reliability criteria redefine interoperability requirements before committing to long-term platform contracts.
Market Dynamics
Fleet electrification mandates and ISO 15118 plug-and-charge standardization are compressing procurement cycles, forcing charge point operators to abandon single-vendor stacks for interoperable middleware architectures that normalize across heterogeneous hardware fleets.
Growth Catalysts
- California Title 24 Building Standards:Commercial developers must pre-wire parking infrastructure for EV readiness, creating embedded software demand before charger deployment.
- Logistics depot electrification:Last-mile delivery operators require orchestration platforms that balance overnight charging loads against utility demand charges.
- Cloud-native architectures:Containerized deployment models reduce operator capex and accelerate feature velocity for geographically distributed assets.
Market Restraints
- Cybersecurity certification costs:EU AI Act and GDPR compliance for cross-border data flows inflate platform development timelines.
- Protocol fragmentation:OCPP 1.6, 2.0.1, and proprietary variants force middleware vendors to maintain multiple handler stacks.
- Utility interconnection queues:Distribution system upgrade delays in Germany and the US stall software deployment at scale.
Strategic Opportunities
- V2G bidirectional integration:FERC Order 2222 eligibility creates new revenue streams for fleet operators with grid-responsive charging.
- White-label platform licensing:Energy retailers in deregulated European markets seek branded control over customer touchpoints.
- Edge computing modules:Millisecond load response requirements at high-utilization depots favor localized processing over pure cloud architectures.
Industry Challenges
- Embedded systems talent scarcity:Shortage of engineers with combined OCPP protocol and utility SCADA experience slows product iteration.
- Legacy ERP integration:Fleet management software from incumbent telematics vendors resists API-based interoperability with charging platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charging Management Software Market |
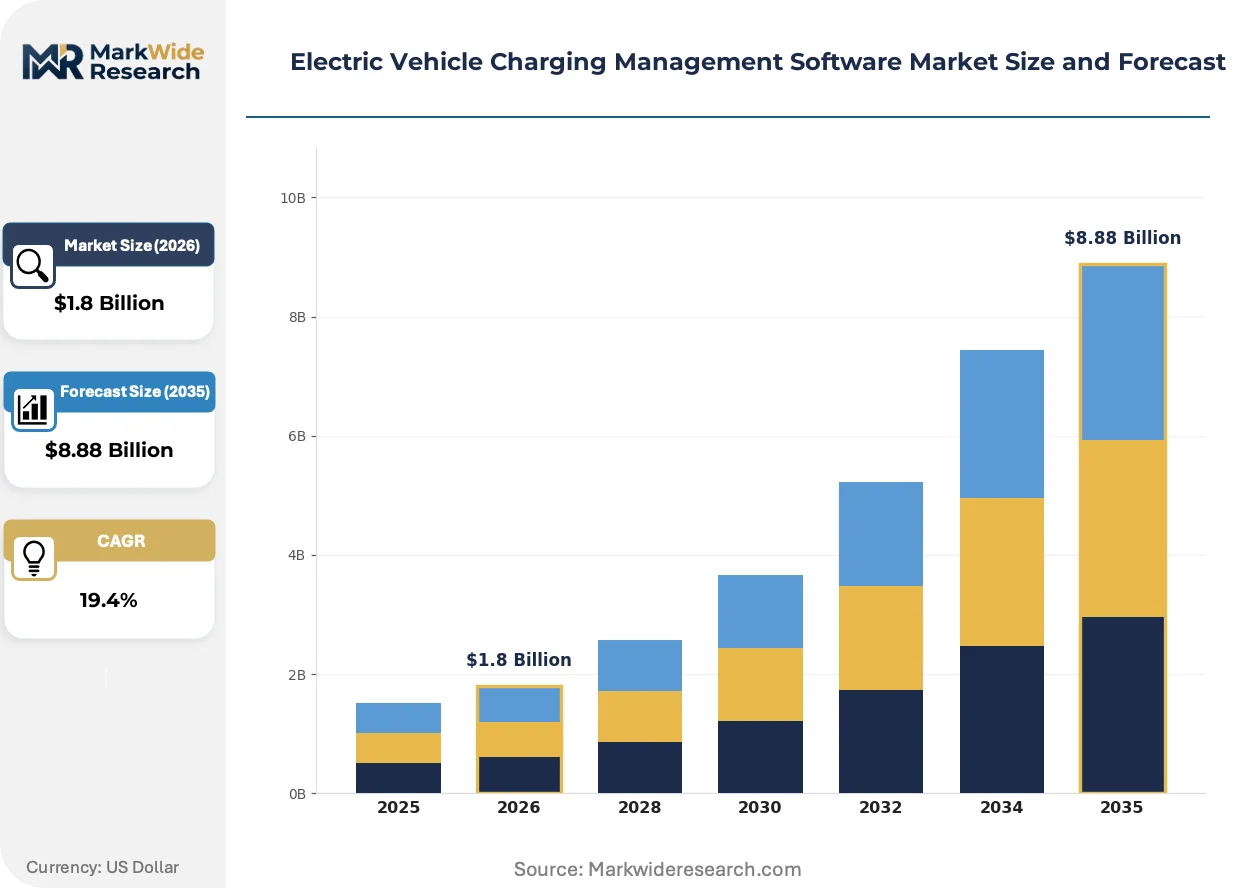
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Smart Chargers, Wireless Chargers End User: Fleet Operators, Residential Users, Commercial Operators, Public Charging Stations Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Technology: Plug and Charge, Smart Grid Integration, Demand Response, Renewable Energy Integration |
| Companies Covered | ChargePoint Holdings, Inc., Driivz Ltd., AMPECO Ltd., EV Connect, Inc., EVBox, ChargeLab Inc., Shell plc, Ampcontrol, ETREL d.o.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charging Management Software Market Trends and Innovations
Software-defined charging infrastructure is dissolving the boundary between hardware and application layers, enabling operators to reconfigure tariff logic and load algorithms without physical site visits.
Plug-and-charge authentication via ISO 15118 is overtaking RFID card and mobile app workflows. Large fleet operators in Germany and California are mandating this capability in new procurement specifications. The technology is compressing session initiation times and eliminating credential management overhead that previously fragmented user experience across roaming networks.
The EU AI Act's risk classification framework for automated decision-making systems now governs predictive load-balancing algorithms. Platform vendors must document training data provenance and implement human oversight mechanisms for tariff optimization models. European operators are responding by segregating AI inference pipelines from core billing systems to isolate compliance scope.
Subscription-based platform access is displacing perpetual license models among mid-sized charge point operators. Monthly fees tied to active port counts align vendor incentives with operator utilization growth. This shift is most pronounced in the UK and Netherlands where capital-constrained CPOs prioritize opex flexibility over upfront software investment.
Electric Vehicle Charging Management Software Market Segmentation
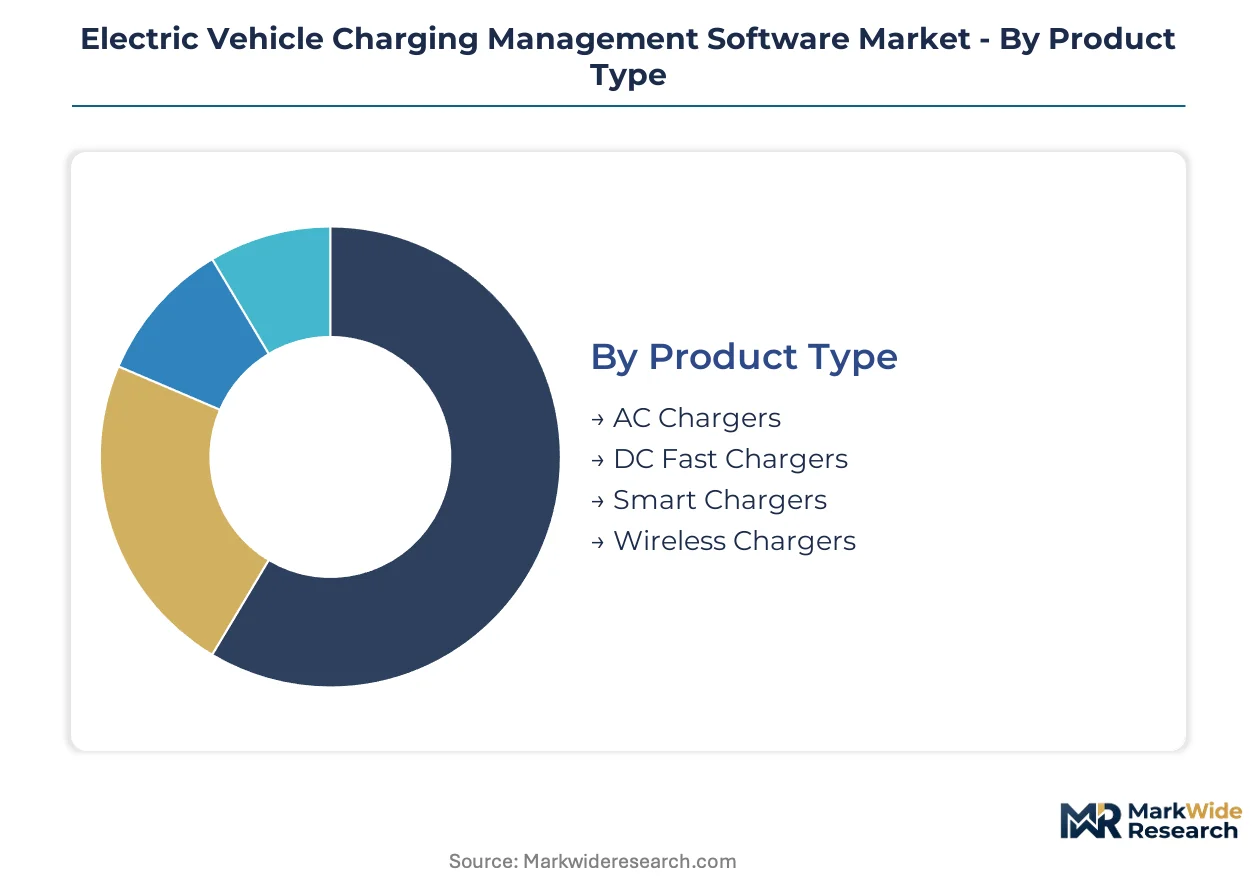
Segmentation in EV charging management software reveals how procurement priorities diverge across hardware types, user sophistication, and infrastructure maturity. Buyers select platforms based on whether they prioritize rapid deployment flexibility, deep utility integration, or white-label customer control.
Product Type:
Cost tier separates buyers in this category, with capital intensity and utilization patterns driving software feature requirements.
- DC Fast Chargers:High-power hardware demands sophisticated load-balancing algorithms and predictive maintenance modules to manage thermal cycling and grid interconnection complexity. Fleet operators in Germany and California concentrate procurement here, driven by depot electrification mandates that require sub-30-minute turnaround times for commercial vehicles.
- Smart Chargers:Bidirectional communication capabilities enable dynamic tariff optimization and V2G revenue stacking through ISO 15118 protocol compliance. European utilities prioritize these deployments where demand response program eligibility creates measurable bill savings.
- AC Chargers:Lower hardware cost supports residential and workplace installations with basic authentication and session management.
- Wireless Chargers:Inductive power transfer systems require specialized alignment detection and foreign object recognition software layers.
AC chargers lead volumes today; DC fast chargers are gaining share fastest.
End User:
Application context determines whether buyers need single-site simplicity or multi-asset orchestration across dispersed geographies.
- Fleet Operators:Depot-centric charging requires integration with route planning systems, driver scheduling platforms, and utility demand charge optimization. Last-mile delivery electrification in California and Germany is compressing procurement cycles as logistics operators abandon fragmented point solutions for unified orchestration platforms.
- Commercial Operators:Retail and workplace installations prioritize customer authentication simplicity and roaming network interoperability to maximize port utilization.
- Public Charging Stations:Highway corridor deployments emphasize 99.9% uptime guarantees and rapid fault escalation protocols.
- Residential Users:Single-point home charging demands basic scheduling and time-of-use rate optimization with minimal configuration overhead.
Fleet operators lead volumes today; commercial operators are expanding most quickly.
Deployment:
Volume scale and latency tolerance separate cloud-native buyers from those requiring localized processing.
- Cloud-Based:Centralized infrastructure reduces capital expenditure and enables rapid feature deployment across geographically distributed charger fleets. Mid-sized charge point operators in the UK and Netherlands favor subscription models that align vendor incentives with port utilization growth.
- Edge Computing:Millisecond-level load response requirements at high-utilization depots favor localized processing for grid stability applications.
- Hybrid:Split architectures keep sensitive billing data on-premises while offloading analytics to cloud environments.
- On-Premises:Air-gapped installations serve defense, critical infrastructure, and jurisdictions with strict data sovereignty requirements.
Cloud-based deployments lead volumes today; edge computing is climbing the fastest.
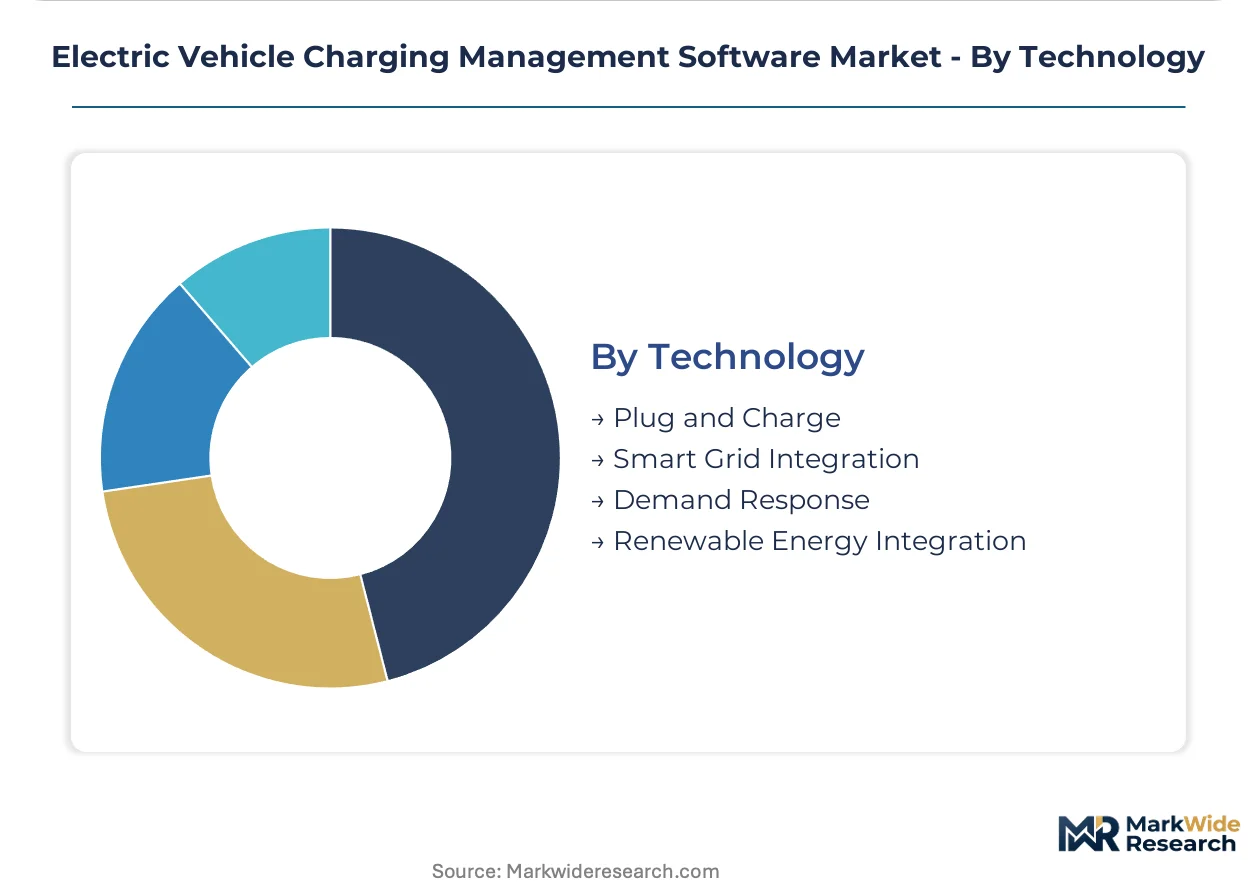
Technology:
Maturity of grid interconnection standards determines which capabilities buyers can actually deploy versus merely evaluate.
- Smart Grid Integration:Utility SCADA interoperability and automated demand response enrollment enable revenue stacking beyond simple energy sales. Germany's distribution system operators mandate these capabilities for new commercial installations.
- Plug and Charge:ISO 15118 authentication eliminates credential management overhead and compresses session initiation times. California fleet procurement specifications increasingly mandate this capability.
- Demand Response:FERC Order 2222 eligibility creates grid-responsive revenue streams for aggregated charging assets.
- Renewable Energy Integration:Solar and storage coupling requires forecast-based charging schedules and islanding detection algorithms.
Smart grid integration leads volumes today; plug and charge is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor from Stuttgart to Munich anchors software demand as fleet operators electrify logistics depots under federal commercial vehicle mandates. California's Title 24 building standards and FERC interconnection rules shape North American procurement specifications. China's dual carbon targets and MIIT smart grid directives compress deployment timelines across the Yangtze Delta manufacturing belt.
United States
Fleet depot electrification in California and Texas drives cloud-platform procurement as logistics operators consolidate fragmented point solutions. FERC Order 2222 eligibility requirements shape demand response software specifications for grid-interconnected assets. The Los Angeles-Inland Empire freight corridor concentrates pilot deployments of V2G-capable charging orchestration systems.
Germany
Distribution system operators mandate utility-grade SCADA interoperability for new commercial installations under federal grid modernization programs. ECHA cybersecurity frameworks and GDPR cross-border data rules inflate compliance costs for platform vendors serving multi-national fleets. The Rhine-Ruhr industrial belt hosts concentrated deployments of predictive load-balancing systems at heavy-duty logistics hubs.
China
MIIT smart grid directives and provincial dual carbon targets accelerate procurement of grid-responsive charging management platforms. GB standards for EV interconnection create domestic protocol requirements that diverge from OCPP implementations elsewhere. The Yangtze River Delta manufacturing cluster concentrates software development talent and pilot deployments of edge-computing charging modules.
United Kingdom
Capital-constrained charge point operators favor subscription-based platform access over perpetual licenses, prioritizing opex flexibility. Ofgem regulatory frameworks for demand response program eligibility shape software procurement specifications for commercial fleet operators. The Midlands logistics corridor hosts concentrated deployments of depot-centric charging orchestration systems integrated with route planning platforms.
Netherlands
Roaming network interoperability requirements drive vendor-agnostic middleware adoption among multi-network charge point operators. The national charging infrastructure scaling program creates embedded software demand across workplace and retail installations. The Randstad urban corridor concentrates deployments of ISO 15118 plug-and-charge authentication systems at high-utilization public charging hubs.
Electric Vehicle Charging Management Software Market Competitive Landscape
Global majors compete with regional champions across integration depth and regulatory compliance specialization. The vendor landscape fragments across three tiers: hardware-coupled platform providers, pure-play software middleware vendors, and utility-grade system integrators. Two strategic archetypes dominate: vendors embedding charging management within broader energy service portfolios, and specialists offering white-label flexibility to branded mobility providers. Competitive positioning hardens through strategic partnerships with distribution system operators and technology licensing arrangements that accelerate protocol compliance.
Within the hardware-coupled tier, ChargePoint Holdings, Inc. and EVBox occupy positions that exemplify network density advantages across North American and European deployments respectively. Among pure-play middleware specialists, Driivz Ltd. and AMPECO Ltd. represent contrasting approaches to utility integration and white-label customer experience control. These four anchors illustrate how competitive differentiation concentrates around either deep grid interconnection capabilities or flexible deployment architectures that accommodate heterogeneous hardware fleets.
| Leading Market Players |
|---|
| ChargePoint Holdings, Inc. |
| Driivz Ltd. |
| AMPECO Ltd. |
| EV Connect, Inc. |
| EVBox |
| ChargeLab Inc. |
| Shell plc |
| Ampcontrol |
| ETREL d.o.o. |
| Others |
Pricing and Supply Chain Analysis
Fleet operators in California and Germany concentrate procurement volume, anchoring subscription-based SaaS pricing as the dominant commercial model across cloud-native charging management platforms.
Pricing Analysis
Input-cost pass-through from cloud infrastructure and cybersecurity compliance investments shapes vendor pricing structures. Three-tier pricing stratifies across enterprise, mid-market, and entry-level deployments, with differentiation resting on API integration depth and grid-interconnection certification grade. Cost compression in the entry tier intensifies as open-source middleware alternatives proliferate. Fleet operators exhibit highest price sensitivity due to thin logistics margins, while utility-grade system integrators absorb premium pricing for SCADA interoperability.
Supply Chain Analysis
Freight and logistics costs for edge-computing hardware modules concentrate supply risk in Taiwan, South Korea, and China, where semiconductor fabrication and embedded systems assembly anchor component sourcing. The software stack draws from cloud hyperscaler infrastructure, OCPP protocol licensing frameworks, and utility SCADA integration libraries. Single-source vulnerability in specialized OCPP firmware development creates chokepoint exposure. Distribution runs through direct vendor-to-operator sales with systems integrator intermediation for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as fleet electrification mandates create embedded, recurring demand for orchestration platforms across logistics and commercial vehicle segments.
For Market Incumbents: Lock in utility-grade certification moats by deepening ISO 15118 and FERC Order 2222 compliance investments before emerging cloud-native entrants achieve feature parity. Prioritize backward integration into edge-computing hardware to capture margin from millisecond load-response deployments at high-utilization depots. For New Entrants and Emerging Players: API-first marketplace positioning opens white-space in white-label platform licensing for European energy retailers seeking branded customer control without captive software development. Target capital-constrained charge point operators in the UK and Netherlands with usage-based subscription tiers that displace perpetual license incumbents. For Investors and Strategic Acquirers: Utility affiliates and energy majors are the most active acquirer in this space, consolidating middleware capabilities to bundle charging management within broader energy service portfolios. Mid-stage pure-play vendors with proven utility integrations represent the most defensible acquisition profile. Monitor California Title 24 enforcement velocity as an inflection signal for embedded infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Partnership | Charge point operators normalize heterogeneous hardware fleets through vendor-agnostic middleware architectures. |
| Utility-Grade Certification Investment | FERC and ECHA compliance creates defensible positioning for grid-interconnected deployments. |
| Edge Computing Module Development | Millisecond load-response requirements at depots favor localized processing over pure cloud. |
| White-Label Licensing Expansion | Energy retailers in deregulated markets control branded customer touchpoints without captive development. |
| Acquisition of Specialist Firm | Strategic buyers consolidate OCPP protocol expertise and utility SCADA integration capabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged charge point operators, fleet logistics directors, utility demand response program managers, and software platform engineering leads. Secondary validation drew from FERC interconnection filings, ECHA cybersecurity guidance, state public utility commission dockets, and hyperscaler infrastructure capex disclosures. Bottom-up port-count modeling and top-down market sizing triangulated volume estimates.
Comparable-period anchoring linked projection assumptions to historical deployment trajectories across the analysis window. Segmentation dimensions spanned deployment architecture, charger hardware type, end-user vertical, grid-interconnection technology tier, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to fleet electrification mandate timelines, with sensitivity testing around utility interconnection queue delays and protocol standardization velocity.
The model assumes a particular technology adoption path; alternative pathways for ISO 15118 plug-and-charge deployment would alter the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and cloud infrastructure cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging System Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market