
 US Electric Motor Market | 2026-2036
US Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric Motor Market Insights
Software-defined motor control and predictive maintenance subscriptions is recalibrating how OEMs monetize electric motor assets over equipment lifecycles. ABB Ltd leverages its digital platform architecture to anchor long-term service contracts with industrial buyers. Nidec Motor Corporation specializes in fractional horsepower precision motors, dominating niche applications in medical devices and robotics. General Electric sustains its position in heavy-duty industrial segments through deep channel relationships with utilities and process industries.
An electric motor is an electromechanical device that converts electrical energy into mechanical torque through electromagnetic induction, with core specifications including efficiency class (IE1 through IE5), power factor, and thermal insulation rating. AC motors lead installed base volume across US manufacturing and HVAC applications, while servo motors represent the fastest-expanding category as factory automation demands precise position control. The below 1 HP segment remains mature with intense price competition, whereas above 20 HP units command premium margins due to custom engineering requirements and longer replacement cycles.
DOE minimum efficiency standards and NHTSA corporate average fuel economy rules are forcing motor manufacturers to redesign core architectures and validate new material systems. EPA industrial emissions guidelines further shape demand by penalizing inefficient drive systems in heavy process applications. Stakeholders must monitor how proposed SEC climate disclosure rules will alter capital allocation toward high-efficiency motor upgrades across publicly held manufacturing operations.
Market Dynamics
DOE efficiency mandates and NHTSA fuel economy standards are forcing motor manufacturers to redesign core architectures and validate new material systems across the US Midwest manufacturing belt.
Growth Catalysts
- Industrial Automation Surge:Factory reshoring to Michigan, Ohio, and Illinois is driving servo motor demand for precision position control in automated assembly lines.
- NHTSA CAFE Standards:Corporate average fuel economy rules compel automotive OEMs to electrify powertrains, expanding high-efficiency motor procurement.
- DOE Minimum Efficiency Regulations:Federal efficiency mandates accelerate replacement cycles for legacy IE1 and IE2 motors in HVAC and process industries.
Market Restraints
- Rare Earth Supply Concentration:Permanent magnet motor production depends on concentrated rare earth processing capacity outside North America, creating input cost volatility.
- Copper Price Volatility:Winding material costs fluctuate with commodity markets, compressing margins for below 1 HP motor manufacturers locked in price competition.
- Technical Thermal Limitations:High-efficiency IE5 designs face heat dissipation constraints that limit power density in compact industrial installations.
Strategic Opportunities
- Servitization Models:Software-defined motor control platforms enable predictive maintenance subscriptions, recalibrating OEM monetization from equipment sales to lifecycle contracts.
- SEC Climate Disclosure Rules:Proposed requirements for publicly held manufacturers will redirect capital toward high-efficiency motor upgrades and retrofits.
- Medical Robotics Expansion:Fractional horsepower precision motors face rising demand from surgical robotics and diagnostic equipment manufacturers.
Industry Challenges
- Electromagnetic Compatibility Certification:FCC Part 15 compliance timelines for variable frequency drives delay product launches and increase validation costs.
- Legacy System Integration:Retrofitting IE4 and IE5 motors into existing mechanical infrastructure requires custom coupling and control architecture redesign.
- Power Electronics Talent Scarcity:Motor control firmware development and thermal management engineering skills concentrate among a limited pool of specialized engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric Motor Market |
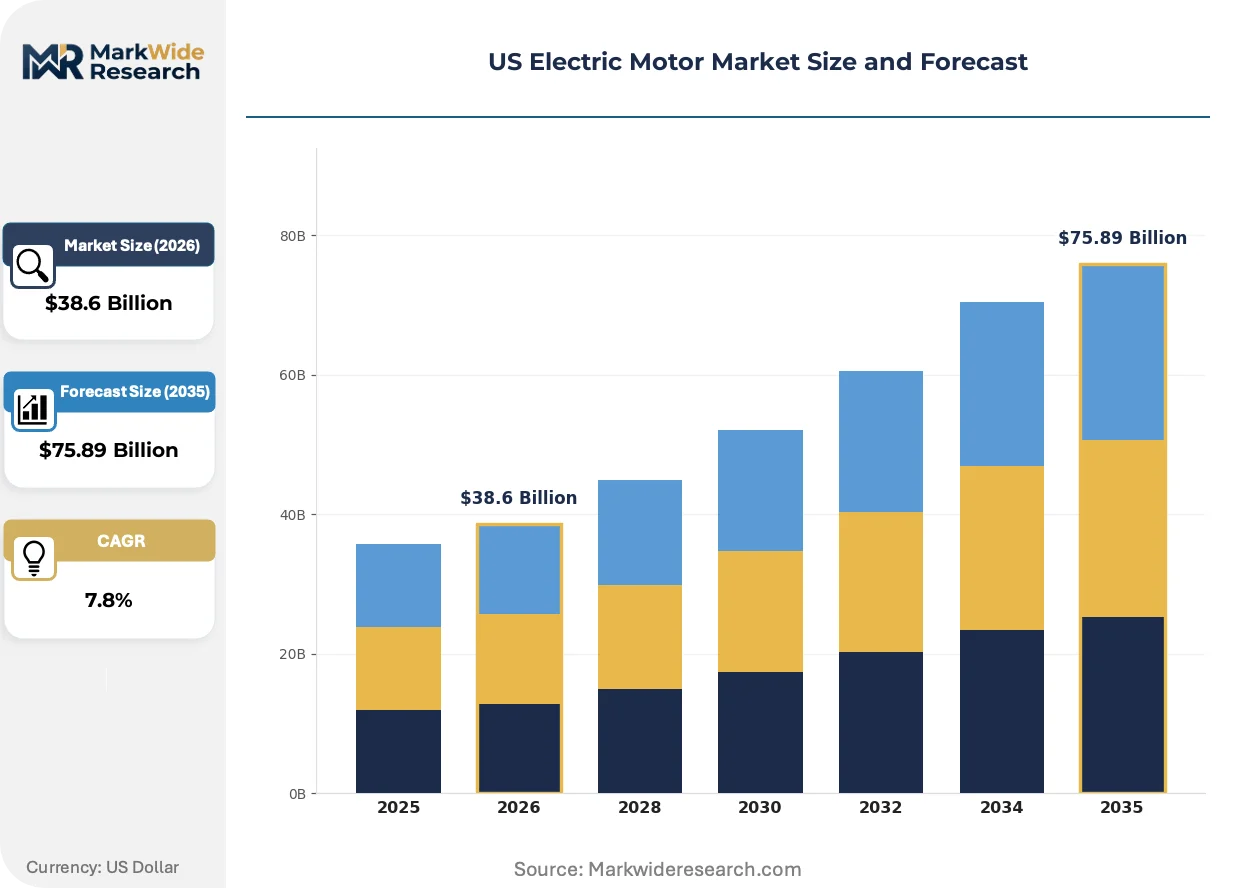
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: AC Motors, DC Motors, Servo Motors, Stepper Motors End User: Manufacturing, Automotive, HVAC, Consumer Electronics Power Rating: Below 1 HP, 1-5 HP, 5-20 HP, Above 20 HP Installation: In-place, Portable, Mounted, Stationary |
| Companies Covered | ABB Ltd, Nidec Motor Corporation, General Electric, Regal Rexnord Corporation, Ametek Inc, Siemens, WorldWide Electric Corporation, Franklin Electric Co., Inc., Allied Motion Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric Motor Market Trends and Innovations
Digitalization is rewiring how electric motor value is captured, with hardware margins compressing while software and service layers expand. Three forces are actively restructuring competitive positioning.
Silicon carbide (SiC) power semiconductors enable higher switching frequencies and reduced thermal losses in variable frequency drives. Industrial buyers in automotive test cells and semiconductor fabrication are adopting SiC-based drives at accelerating pace. This technology is decentralizing motor control intelligence from centralized panels to edge-mounted drive modules, compressing installation footprints and cable runs.
NHTSA fuel economy standards and EPA industrial emissions guidelines are tightening in parallel, forcing simultaneous compliance across automotive and process industry motor applications. Manufacturers must validate architectures against both efficiency and emissions benchmarks. Heavy-duty industrial segments face the steepest redesign requirements as dual regulatory pressure compounds.
Buyers are unbundling after-sales service from initial equipment procurement, contracting predictive maintenance separately through digital platform subscriptions. Industrial distributors are responding by building service capabilities or partnering with control system vendors. This shift is most visible across Great Lakes manufacturing operations where uptime guarantees dominate procurement criteria.
US Electric Motor Market Segmentation
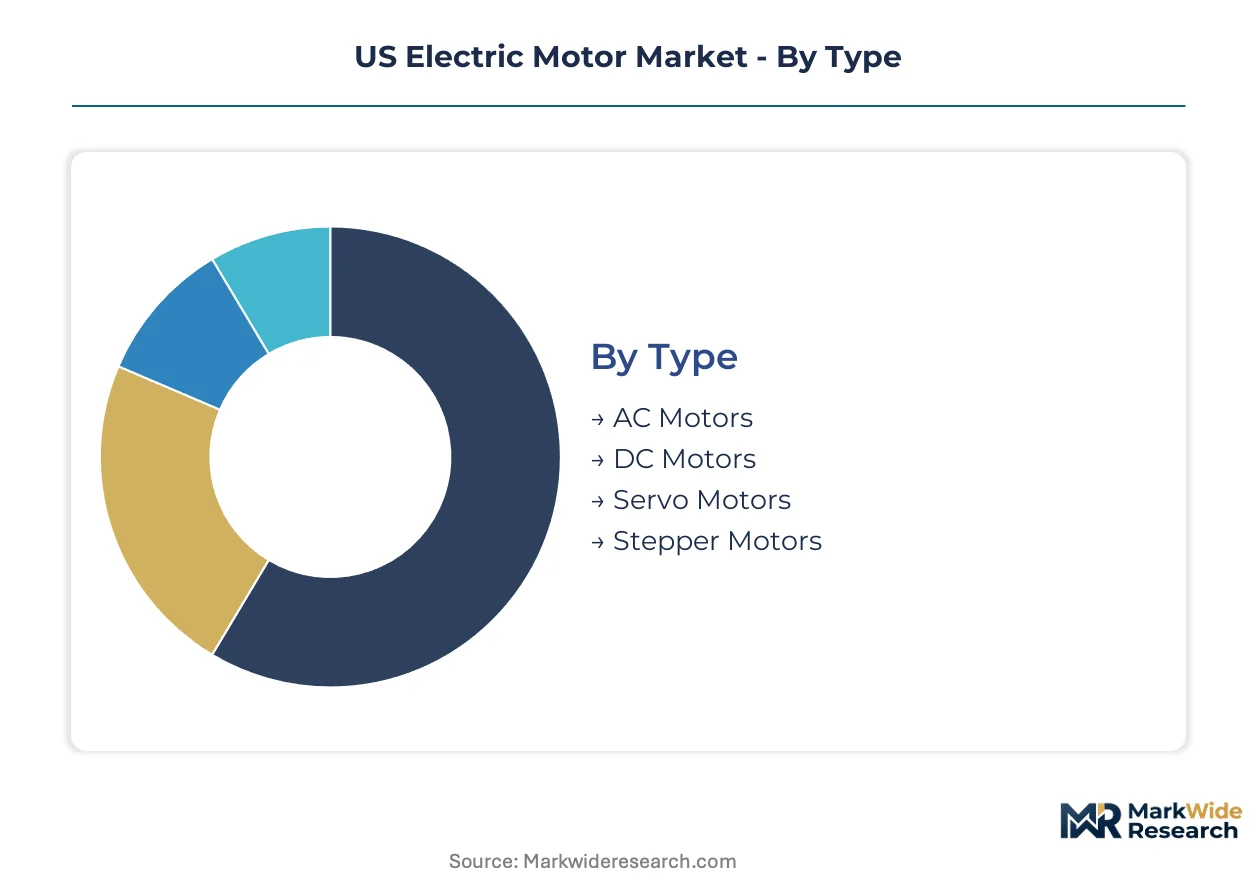
Motor architecture choices cascade through procurement economics, regulatory compliance pathways, and aftermarket service models. Segment boundaries in this market reflect technical trade-offs between efficiency mandates, power density requirements, and integration complexity across US industrial infrastructure.
Type:
Standardized AC induction platforms dominate volume procurement, while precision motion categories command customization premiums and longer sales cycles.
- AC Motors:Induction and synchronous architectures convert alternating current to rotational torque through electromagnetic stator-rotor coupling. DOE efficiency regulations are forcing IE3 and IE4 upgrades across Midwest manufacturing facilities in Michigan, Ohio, and Illinois, where HVAC and pump applications concentrate installed base.
- Servo Motors:Closed-loop feedback systems with encoder resolution below 1 arc-minute enable precise position, velocity, and torque control. Factory automation reshoring to the Great Lakes corridor is accelerating demand for multi-axis servo arrays in robotic assembly and semiconductor test equipment.
- DC Motors:Brushed and brushless permanent magnet designs deliver high starting torque for battery-powered mobility and material handling equipment.
- Stepper Motors:Open-loop incremental positioning systems with fixed step angles serve cost-sensitive applications in 3D printing, medical dispensers, and textile machinery.
Most installed capacity flows through AC Motors. Expansion is steepest in Servo Motors.
End User:
Customer procurement sophistication varies sharply, with automotive and semiconductor buyers demanding predictive maintenance integration while HVAC contractors prioritize first-cost minimization.
- Manufacturing:Discrete and process industries deploy motors across material handling, machining centers, and pumping systems. The US Midwest manufacturing belt—spanning Detroit automotive clusters, Cleveland metalworking, and Chicago food processing—generates concentrated demand for IE4 and IE5 efficiency classes under tightening EPA industrial emissions guidelines.
- Automotive:OEM powertrain electrification and tier-1 supplier automation drive specialized motor procurement for electric vehicle traction, thermal management, and battery assembly. NHTSA CAFE standards compel high-efficiency motor integration across vehicle subsystems.
- HVAC:Commercial and residential climate systems specify fractional to medium horsepower motors for compressors, fans, and pumps, with replacement cycles accelerated by DOE minimum efficiency mandates.
- Consumer Electronics:Miniature brushless DC motors power hard disk drives, cooling fans, and appliance actuators in cost-optimized, high-volume procurement.
Manufacturing channels the largest revenue pool. Automotive applications are climbing the fastest as electrification penetrates vehicle platforms.
Power Rating:
Margin structures invert across the power spectrum, with commodity competition below 1 HP and engineered-to-order premiums above 20 HP.
- Above 20 HP:Custom-wound heavy-duty motors serve mining, oil and gas, and primary metals processing with cast iron frames and Class H insulation. Extended replacement cycles and application-specific engineering create pricing power for manufacturers with deep channel relationships in US process industries.
- Below 1 HP:Fractional horsepower units power appliances, office equipment, and small pumps in intense price competition. Copper price volatility compresses margins for manufacturers lacking backward integration into lamination stamping or die-casting operations.
- 1-5 HP:General-purpose industrial motors bridge commercial HVAC and light manufacturing applications with standardized NEMA frame dimensions.
- 5-20 HP:Mid-range units serve conveyor systems, machine tools, and commercial refrigeration with balanced customization and standardization economics.
Below 1 HP motors constitute the broadest installed base. Above 20 HP units deliver the steepest margin expansion trajectory.
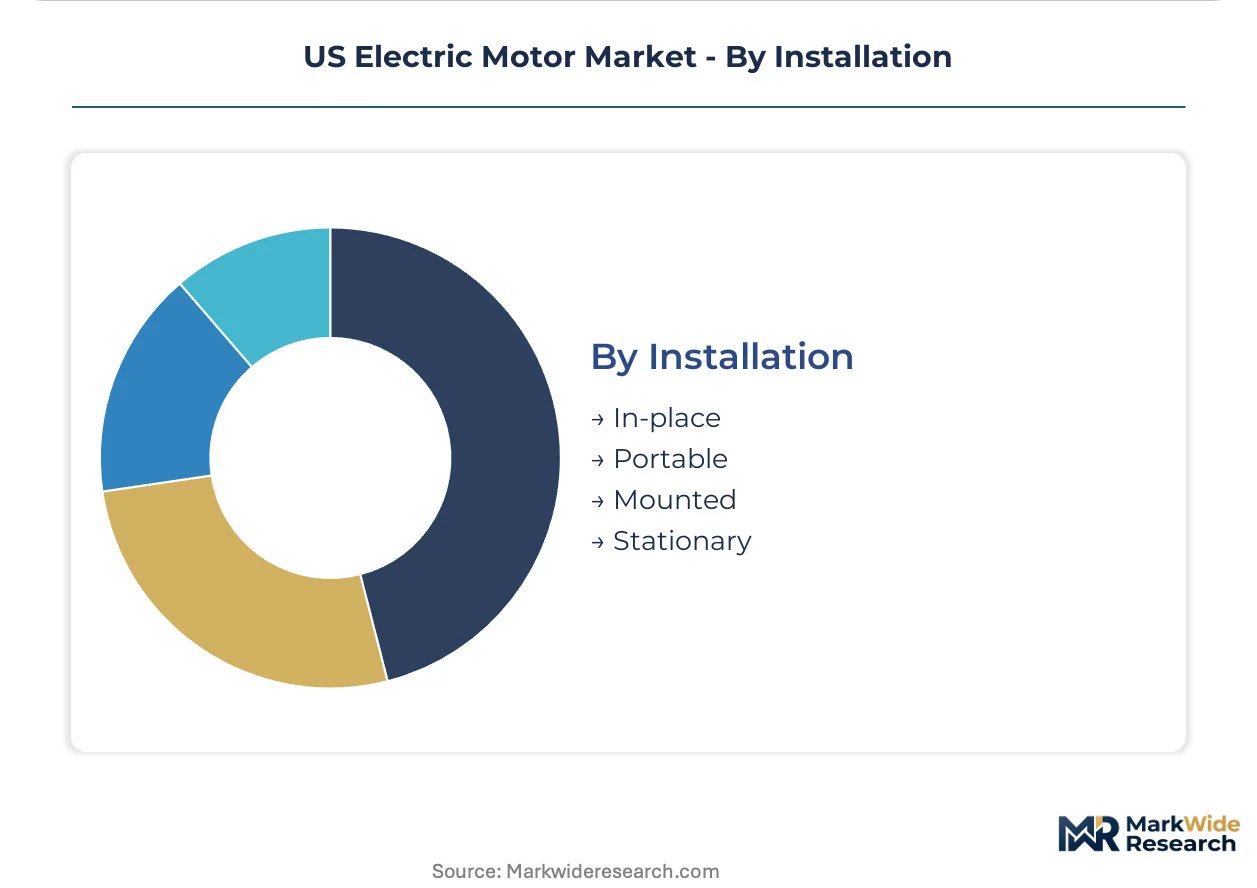
Installation:
Physical mounting configuration determines thermal management design, cabling architecture, and maintenance accessibility in field deployment.
- Stationary:Fixed-base industrial motors with rigid foot mounting dominate permanent infrastructure in process plants and manufacturing facilities.
- In-place:Direct-coupled pump and compressor motors with C-face or D-flange mounting simplify alignment and reduce bearing loads in fluid handling applications.
- Mounted:Bracket or pedestal configurations enable flexible positioning in OEM equipment integration.
- Portable:Lightweight framed or cart-mounted motors serve construction, agriculture, and temporary power applications with plug-and-cord connectivity.
Stationary configurations anchor permanent industrial capacity. Portable installations are expanding most quickly in construction and agricultural equipment electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters concentrate servo motor demand for automotive automation, while China's manufacturing scale absorbs fractional horsepower units for appliance and consumer electronics production at unmatched procurement volumes.
Midwest Manufacturing Belt
Automotive electrification and industrial reshoring concentrate motor demand across Michigan, Ohio, and Illinois. DOE efficiency mandates accelerate IE3 and IE4 motor replacements in Detroit-area stamping plants and Cleveland metalworking facilities. Chicago food processing and logistics hubs generate sustained procurement for mid-range industrial motors.
Southeast Growth Corridor
Battery gigafactories and EV assembly plants in Georgia, Tennessee, and South Carolina drive specialized motor procurement for traction systems and thermal management. NHTSA CAFE compliance pressures automotive OEMs to electrify powertrains. Charleston and Savannah port automation projects absorb servo motors for container handling systems.
Texas Energy and Petrochemical Hub
Upstream oilfield electrification and downstream petrochemical processing sustain demand for above 20 HP explosion-proof motors. EPA industrial emissions guidelines penalize inefficient drive systems in Gulf Coast refineries. Houston engineering centers specify custom-wound motors for compression and pumping applications.
California Technology and Clean Energy
Semiconductor fabrication and solar manufacturing equipment demand precision motion control systems. California Air Resources Board industrial emissions rules shape motor efficiency specifications. Bay Area robotics startups and medical device manufacturers procure fractional horsepower servo motors for surgical and diagnostic platforms.
Northeast Industrial Legacy
HVAC modernization in commercial buildings across New York, Pennsylvania, and Massachusetts replaces legacy IE1 and IE2 motors under state-level efficiency incentives. DOE regional efficiency partnerships accelerate retrofit cycles. Boston-area biotech and pharmaceutical manufacturing deploys cleanroom-rated motors for sterile processing environments.
US Electric Motor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in heavy-duty industrial motors above 20 HP and fragmented competition below 1 HP where price pressure dominates. Three archetypes occupy distinct competitive terrain: diversified industrial conglomerates with integrated digital platforms, fractional horsepower precision specialists serving medical and robotics niches, and regional contract manufacturers competing on cost for standardized AC induction platforms. M&A activity concentrates among mid-tier players seeking scale, while technology licensing agreements proliferate around silicon carbide drive architectures.
Within the diversified industrial tier, ABB Ltd and Siemens exemplify platform-centric competitors anchoring long-term service contracts through predictive maintenance capabilities. Nidec Motor Corporation occupies a position among fractional horsepower specialists, representing precision motor archetypes that dominate medical device and robotics applications. These three companies illustrate how competitive positioning diverges between lifecycle monetization models and component specialization strategies.
| Leading Market Players |
|---|
| ABB Ltd |
| Nidec Motor Corporation |
| General Electric |
| Regal Rexnord Corporation |
| Ametek Inc |
| Siemens |
| WorldWide Electric Corporation |
| Franklin Electric Co., Inc. |
| Allied Motion Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement teams concentrate purchasing power for traction motors and thermal management systems, enforcing contract-based long-term offtake agreements that lock in volume commitments and compress spot-market premiums for below 1 HP suppliers.
Pricing Analysis
Capacity additions in Mexico and Southeast Asia are reshaping price floors for fractional horsepower motors, intensifying cost compression across standardized AC induction platforms. Three-tier pricing structure across premium IE5, standard IE3-IE4, and economy IE1-IE2 efficiency levels segments buyer segments by regulatory exposure and replacement urgency. Pricing pressure stems from copper lamination cost volatility and rare earth magnet input swings. HVAC contractors and appliance OEMs exhibit acute price sensitivity, while process industry buyers absorb premiums for above 20 HP custom engineering.
Supply Chain Analysis
Dual-sourcing requirements mandated by automotive OEMs and defense contractors force qualification of second-source suppliers for silicon steel laminations and permanent magnet assemblies. Manufacturing draws from China for rare earth processing, Japan for precision magnet alloys, and Germany for high-efficiency winding equipment. Critical dependencies include copper rod, electrical steel, and neodymium-iron-boron magnets. Single-source vulnerability concentrates in rare earth separation capacity outside North America. Distribution runs through industrial distributors, OEM direct procurement, and MRO channel partners serving Midwest manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Midwest reshoring incentives create cost arbitrage against Asian manufacturing for heavy-duty industrial motors, as DOE efficiency mandates and IRA domestic content rules widen the total-cost-of-ownership gap between US-assembled and imported platforms.
For Market Incumbents: Cement platform stickiness through predictive maintenance subscription bundling and backward integration into silicon carbide drive module production. Defend against Nidec's fractional horsepower precision encroachment by locking medical device OEMs into multi-year lifecycle contracts. Prioritize certification investment for IE5 thermal management architectures ahead of anticipated SEC climate disclosure rule acceleration. For New Entrants and Emerging Players: Enter via surgical robotics and semiconductor test equipment servo motor niches where encoder resolution specifications exceed incumbent mass-market capabilities. Target Georgia and Tennessee battery gigafactory corridors for traction motor thermal management subsystems. Pursue joint development agreements with EV platform engineering teams rather than component catalog positioning. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, consolidating mid-tier servo motor specialists to fill precision motion portfolio gaps. Five-to-ten-year viability hinges on software-defined motor control platform penetration rates. Monitor NHTSA CAFE standard stringency announcements as inflection signals for high-efficiency motor procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive rare earth sourcing insulates margin from Chinese export quota volatility. |
| Servitization Platform Launch | Predictive maintenance subscriptions recalibrate OEM monetization toward recurring revenue. |
| IE5 Efficiency Certification | DOE regulatory escalation positions certified suppliers for accelerated replacement cycles. |
| Midwest Manufacturing Footprint Expansion | Proximity to Michigan and Ohio automotive clusters reduces logistics cost and lead time. |
| Surgical Robotics Partnership | Fractional horsepower precision demand from medical device OEMs commands premium pricing. |
Research Methodology
Coverage spans the US Midwest manufacturing belt, Southeast battery corridor, and Texas petrochemical hub, with primary inputs from each region combining interviews with plant engineers, OEM procurement directors, aftermarket service heads, and industrial distributor account managers. Secondary validation draws from DOE efficiency standard filings, NHTSA CAFE regulatory dockets, SEC climate disclosure proposals, and customs trade data for motor and drive imports. Bottom-up installation base estimates triangulate against top-down OEM production forecasts.
Rate-of-change decomposition separates volume growth from efficiency tier mix shift and average selling price evolution across the projection horizon. Segmentation dimensions modeled include motor architecture type, power rating tier, end-use industry vertical, and regional manufacturing cluster. CAGRs derive from regression against industrial production indices, reshoring announcement tracking, and regulatory compliance timeline analysis. Forecast inputs incorporate silicon carbide adoption curves and rare earth price scenario modeling.
Inputs from DOE regulatory filings and OEM procurement surveys were available through the study window; gaps in privately held motor distributor transaction data introduce uncertainty bands around replacement cycle timing assumptions. Forecasts reflect documented assumptions regarding NHTSA rule finalization and IRA credit extension. Deviation in rare earth export policy or copper price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Germany AC Motor Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
United States DC Motor Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Power Stacker Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Gear Motor Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
Crude Heater Market
Industrial Motors
Europe Tank Insulation Market