
 Global Brushed DC Motor Market | 2026-2036
Global Brushed DC Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brushed DC Motor Market Foresight
REACH compliance is rebalancing the cost-of-entry calculus for brushed DC motor manufacturers serving European automotive and medical device clients. Johnson Electric Holdings Limited leverages its vertically integrated manufacturing footprint across China and Switzerland to sustain cost competitiveness under evolving substance restrictions. Nidec Corporation anchors its position through dominant scale in precision motor production for hard disk drives and industrial automation. Mabuchi Motor Co., Ltd. specializes in high-volume, low-cost iron core motors for consumer applications, competing primarily on manufacturing efficiency and Asian supply chain density.
A brushed DC motor converts direct current electrical energy into mechanical rotation through commutator-mediated switching of wound armature coils, typically achieving torque outputs from millinewton-meters to several hundred newton-meters depending on frame size and magnet configuration. Iron core variants retain cost leadership in high-torque industrial and agricultural machinery applications where weight tolerance permits laminated steel construction, while coreless designs command premium positioning in medical device producers' portable diagnostic equipment due to superior acceleration response and minimal cogging torque. Digital control technology represents the fastest-expanding segment as automotive Tier-1 Suppliers integrate encoder feedback and PWM drive electronics for precision positioning in electric throttle and HVAC flap actuation systems.
The EPA regulates brushed DC motor efficiency under electric motor minimum performance standards, while China's MIIT enforces GB standards for motor energy consumption in industrial equipment. ECHA's SCIP database requirements for product-level substance disclosure are reshaping how medical device producers and automotive Tier-1 Suppliers qualify suppliers across extended supply chains. Stakeholders must monitor the divergence between regional efficiency mandates and material compliance frameworks when configuring multi-source manufacturing strategies.
Market Dynamics
Automotive electrification is compressing design cycles for brushed DC motors as Tier-1 Suppliers demand integrated motor-drive systems with embedded position sensing. The shift from standalone motors to mechatronic subsystems is forcing manufacturers to reconfigure R&D priorities and supplier qualification protocols.
Growth Catalysts
- EU F-Gas Regulation:Energy-efficiency mandates for HVAC systems in commercial vehicles are accelerating procurement of high-efficiency coreless motors with reduced electromagnetic losses.
- Electric power steering modules:German and Japanese automotive suppliers are expanding specifications for compact brushed DC actuators with integrated thermal management.
- Shenzhen-Nagoya manufacturing clusters:Precision motor assembly co-location with regional electronics supply chains is shortening prototype-to-production timelines for medical device producers.
Market Restraints
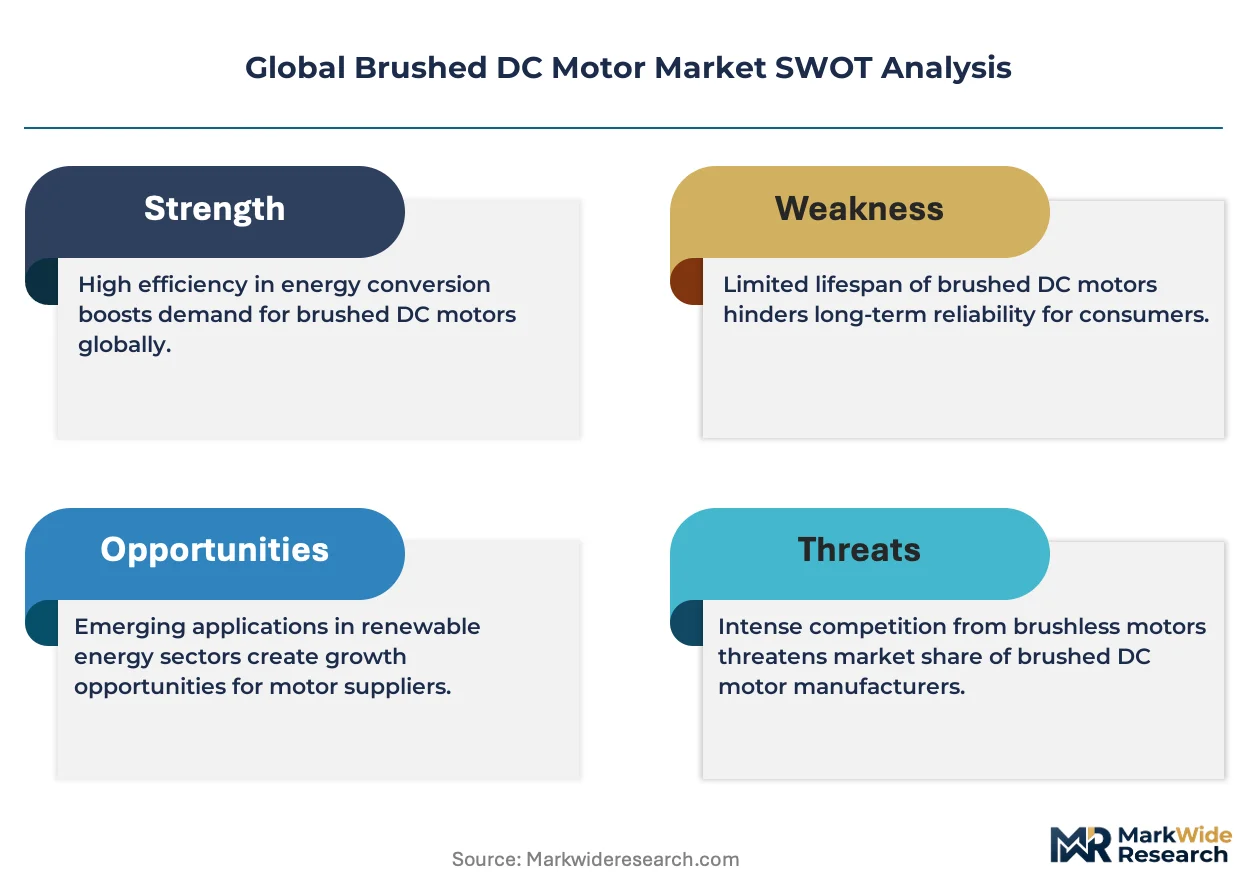
- Rare earth magnet cost volatility:Neodymium and samarium-cobalt price swings compress margins for high-performance motor variants dependent on permanent magnet construction.
- REACH substance disclosure:ECHA's SCIP database requirements impose documentation burdens that extend supplier qualification timelines for European medical device and automotive clients.
- Brushless DC motor substitution:Advances in sensorless control algorithms and declining power electronics costs enable brushless alternatives to capture positioning applications requiring extended operational life.
Strategic Opportunities
- Portable diagnostic equipment:Coreless motor architectures with minimal cogging torque are penetrating point-of-care medical devices where rapid acceleration response differentiates product performance.
- India's PLI scheme for automotive components:Production-linked incentives for electric vehicle subsystems create localized manufacturing incentives for motor suppliers establishing assembly operations.
- Encoder-PWM convergence:Integration of magnetic encoders with pulse-width modulation drives is expanding into agricultural machinery automation where precision valve control commands premium positioning.
Industry Challenges
- Commutation expertise scarcity:Specialized knowledge in brush material selection and commutator surface engineering is concentrating among retiring technician cohorts, constraining quality assurance capacity.
- Multi-standard certification complexity:Simultaneous compliance with EPA electric motor efficiency standards, China's GB energy consumption benchmarks, and EU CE marking requirements fragments testing budgets and extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brushed DC Motor Market |
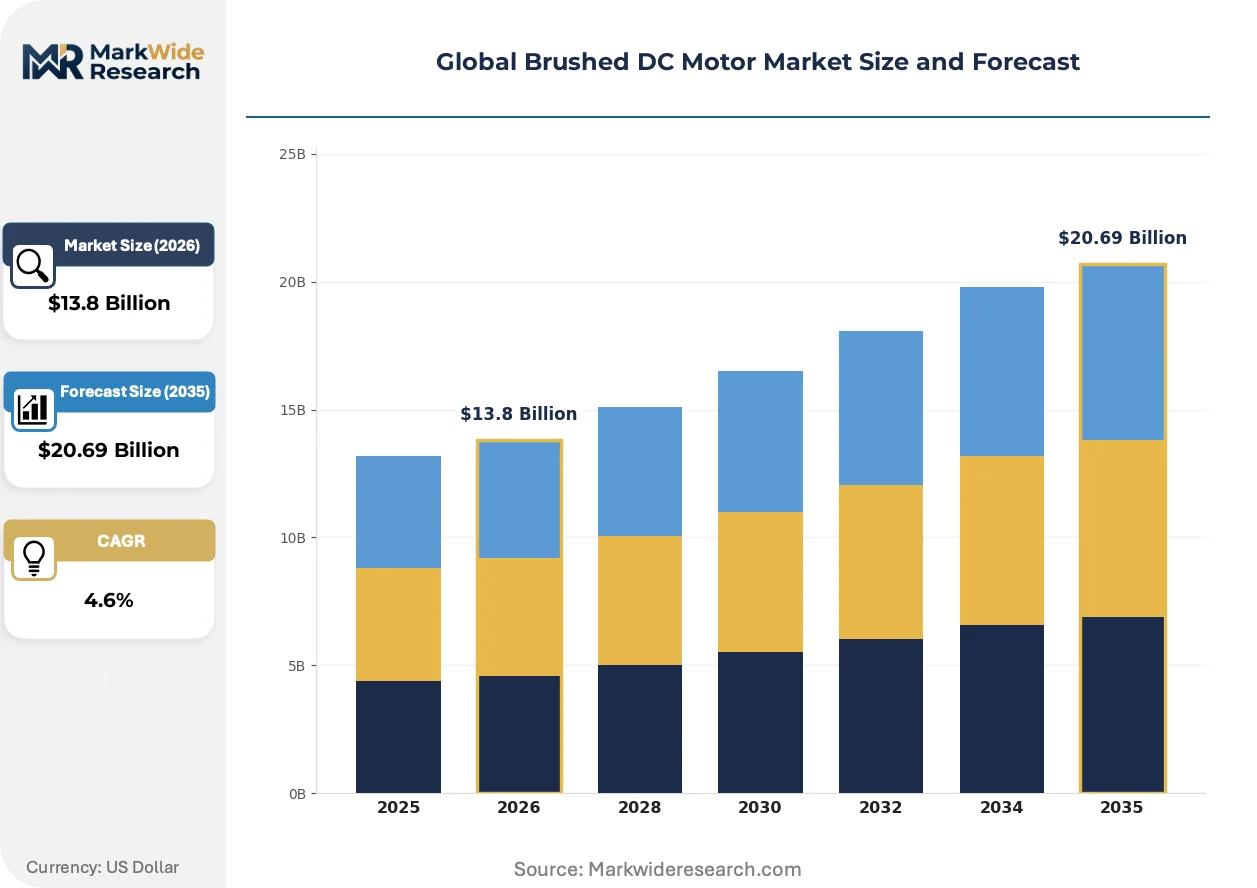
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Core, Coreless, Plastic Core, Slotless Technology: Electromagnetic, Brushless Hybrid, Analog Control, Digital Control Application: Home Appliances, Power Tools, HVAC Equipment, Agricultural Machinery End User: Consumer Electronics Manufacturers, Industrial Equipment Makers, Medical Device Producers, Automotive Tier-1 Suppliers |
| Companies Covered | AMETEK, Inc., Johnson Electric Holdings Limited, Nidec Corporation, Mabuchi Motor Co., Ltd., Siemens AG, Maxon Motor AG, Toshiba Corp., ABB Ltd., FAULHABER Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brushed DC Motor Market Shifts & Advancements
Digital control integration is displacing analog drive architectures across precision positioning applications. Three convergent developments are reshaping how brushed DC motors are specified, procured, and deployed in end-use equipment.
Integrated encoder-feedback systems are expanding into electric throttle and HVAC flap actuation modules. Automotive Tier-1 Suppliers in Germany and Japan are specifying magnetic or optical encoders with 12-bit resolution as standard requirements. This technology convergence is compressing the addressable market for standalone motor suppliers lacking in-house drive electronics capability.
China's MIIT enforcement of GB motor energy consumption standards is tightening efficiency benchmarks for industrial equipment deployed in manufacturing facilities. Domestic motor producers are reconfiguring lamination designs and magnet grades to maintain market access. The regulatory pressure is most acute in East Asian manufacturing clusters where export-oriented equipment must satisfy dual compliance with Chinese and European efficiency frameworks.
Direct procurement relationships between automotive Tier-1 Suppliers and motor manufacturers are displacing traditional distributor channels for specification-grade products. Buyers are consolidating supplier panels and demanding application engineering support earlier in design cycles. This channel compression is most visible in Nagoya and Stuttgart where just-in-time assembly requirements favor geographically proximate motor engineering teams.
Global Brushed DC Motor Market Segmentation
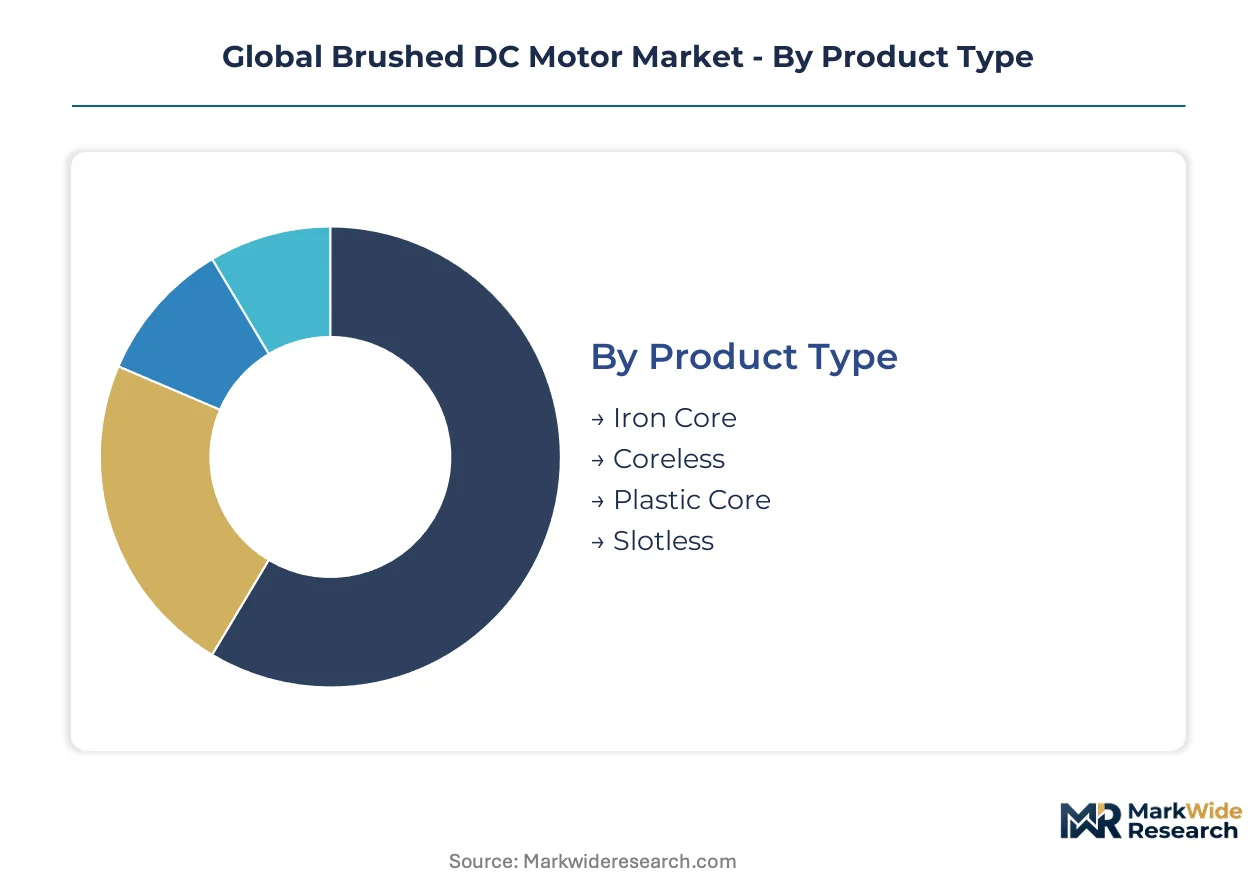
Segmentation in the brushed DC motor market reveals how capital deployment, technical specialization, and regulatory exposure concentrate value capture. Manufacturers configure product portfolios around magnet material costs, precision requirements, and end-user qualification protocols.
Product Type:
Capital intensity varies sharply across construction methods, with permanent magnet configurations and lamination tooling driving upfront investment thresholds.
- Iron Core:Laminated steel armatures with wound copper coils deliver high torque density for agricultural machinery and industrial power transmission. Chinese producers dominate volume manufacturing, though German and Japanese suppliers command premium positioning in precision-machined variants for automotive actuation modules.
- Coreless:Self-supporting copper windings eliminate cogging torque, enabling rapid acceleration response in portable diagnostic equipment and electric power steering systems. Medical device producers in Switzerland and automotive Tier-1 Suppliers in Stuttgart specify these for applications where minimal electromagnetic interference and precise positioning justify material costs.
- Plastic Core:Injection-molded polymer armatures reduce unit weight for consumer electronics manufacturers in Shenzhen producing handheld devices and small appliances.
- Slotless:Cylindrical windings without stator teeth optimize smooth torque output for precision instrumentation and laboratory automation equipment.
Most installed capacity flows through Iron Core. Expansion is steepest in Coreless.
Technology:
Control architecture determines which suppliers capture value from system integration versus component sales.
- Digital Control:Embedded PWM drives with magnetic encoder feedback enable closed-loop positioning in electric throttle and HVAC flap actuation. Automotive Tier-1 Suppliers in Nagoya and Stuttgart require 12-bit resolution as standard, compressing margins for standalone motor suppliers lacking drive electronics capability.
- Electromagnetic:Conventional wound-field construction persists in high-torque agricultural machinery where cost minimization outweighs efficiency optimization.
- Brushless Hybrid:Commutator-based designs incorporating sensorless control elements bridge reliability and cost requirements in power tools and home appliances.
- Analog Control:Simplified voltage regulation maintains presence in price-sensitive consumer electronics where precision positioning is unnecessary.
Digital Control is gaining share fastest in specification-grade applications. Electromagnetic retains volume leadership in emerging markets.
Application:
End-use diversification spreads regulatory and demand risk across cyclical and defensive sectors.
- HVAC Equipment:EU F-Gas Regulation efficiency mandates are accelerating procurement of high-efficiency coreless motors for commercial vehicle climate systems. Manufacturers serving European automotive clients must demonstrate compliance with ECHA substance disclosure requirements.
- Power Tools:Brushless hybrid architectures are displacing pure brushed designs in professional-grade equipment, though brushed motors retain cost advantage in consumer cordless tools.
- Home Appliances:China's MIIT enforcement of GB energy consumption standards is tightening efficiency benchmarks for motors in washing machines and refrigeration compressors.
- Agricultural Machinery:Encoder-PWM convergence is expanding into precision valve control for automated irrigation and planting equipment.
HVAC Equipment commands the highest specification premiums. Agricultural Machinery is climbing the fastest as automation penetrates farm operations.
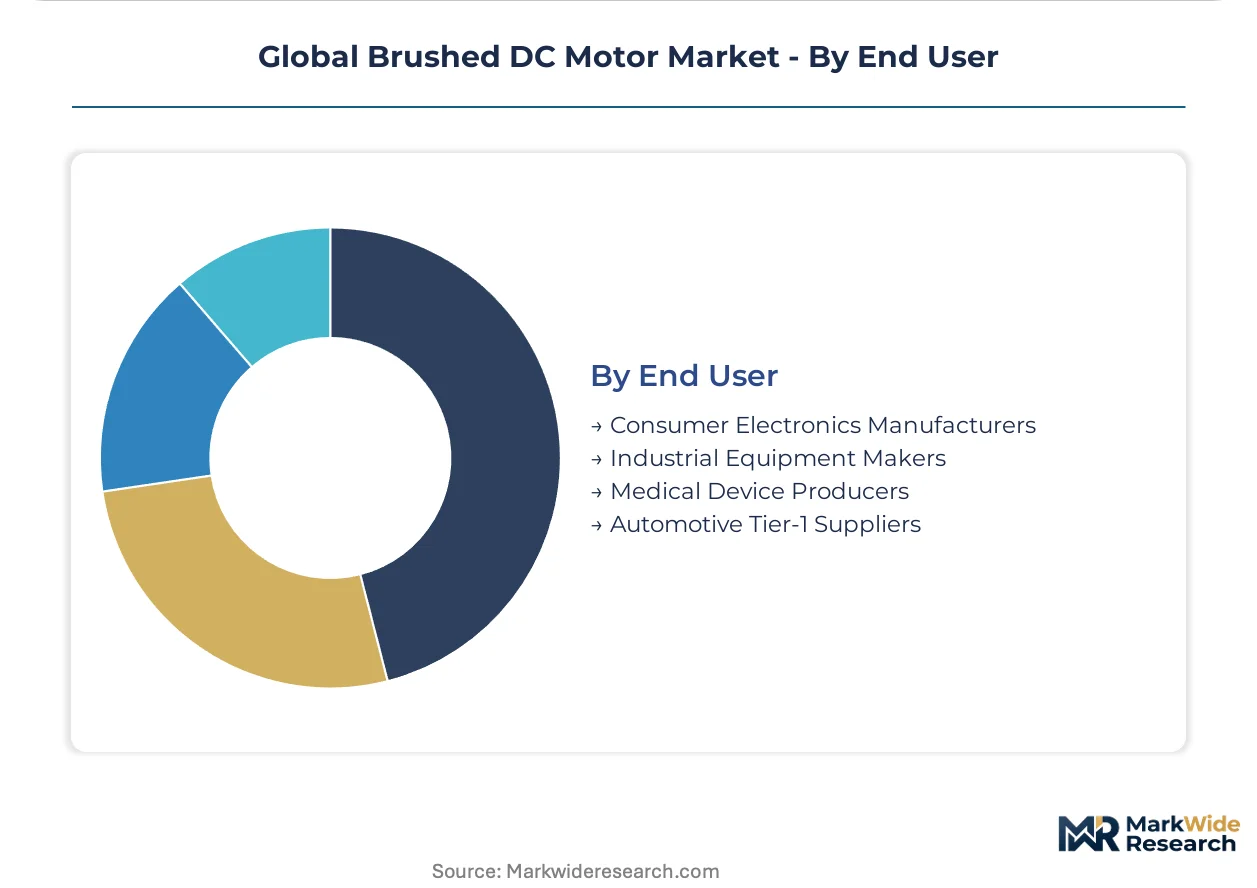
End User:
Customer concentration and qualification intensity segment the market between high-volume commoditized supply and engineered solutions.
- Automotive Tier-1 Suppliers:Direct procurement relationships are displacing distributor channels, with buyers consolidating supplier panels and demanding application engineering support earlier in design cycles. Just-in-time assembly requirements in Nagoya and Stuttgart favor geographically proximate motor engineering teams.
- Medical Device Producers:REACH compliance and ECHA SCIP database requirements extend supplier qualification timelines, favoring vertically integrated manufacturers with documented substance chains.
- Consumer Electronics Manufacturers:Shenzhen-based assemblers prioritize supply chain density and rapid prototype-to-production turnaround over technical differentiation.
- Industrial Equipment Makers:Dual compliance with Chinese GB standards and European efficiency frameworks shapes sourcing strategies for export-oriented machinery.
Automotive Tier-1 Suppliers absorb the most engineering resources per contract. Medical Device Producers are expanding procurement most quickly as point-of-care diagnostics proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized commutation engineering talent concentrates in Stuttgart, Nagoya, and Shenzhen, anchoring design-to-production workflows for precision motor applications across automotive, medical, and industrial sectors.
Germany
Automotive Tier-1 Suppliers in Stuttgart and Munich drive specification-grade procurement for electric power steering and HVAC flap actuation modules. The KBA enforces type-approval standards for vehicle-integrated motor systems. Manufacturing clusters in Baden-Württemberg co-locate precision machining with Tier-1 assembly operations to compress prototype-to-production timelines.
Japan
METI's industrial efficiency directives accelerate adoption of high-performance coreless architectures in factory automation and medical device applications. Nagoya-based engineering teams specialize in magnetic encoder integration for closed-loop positioning systems. The Chubu region maintains concentrated expertise in commutator surface engineering and brush material selection.
China
MIIT enforcement of GB motor energy consumption standards tightens efficiency benchmarks for industrial equipment and home appliance manufacturers. Shenzhen assemblers leverage regional electronics supply chain density to shorten procurement cycles for consumer electronics motor modules. The Pearl River Delta hosts the world's largest installed base of iron core motor stamping capacity.
Switzerland
Swissmedic regulatory frameworks for active implantable medical devices shape qualification protocols for coreless motor suppliers serving portable diagnostic equipment producers. Precision manufacturers in the Swiss Mittelland region specialize in minimal-cogging torque architectures for point-of-care instrumentation. Vertically integrated producers document substance chains to satisfy ECHA SCIP database requirements for European medical device clients.
United States
EPA electric motor minimum performance standards govern efficiency thresholds for industrial power transmission applications. Midwest manufacturing corridors in Michigan and Ohio retain specialized winding and lamination capabilities for agricultural machinery automation. Encoder-PWM convergence for precision valve control commands premium positioning in automated irrigation systems deployed across the Corn Belt.
Global Brushed DC Motor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across specification tiers, creating a tiered structure where scale-driven producers serve high-volume consumer applications while engineering-intensive firms capture premium positioning in medical and automotive segments. Three archetypes dominate: vertically integrated Asian manufacturers with captive magnet supply, European precision engineering houses with documented REACH compliance, and diversified industrial conglomerates leveraging cross-divisional technology transfer. Competitive moves concentrate on backward integration into rare earth magnet sourcing and geographic expansion into India's PLI-subsidized automotive component zones.
Among precision motor specialists, Maxon Motor AG and FAULHABER Group exemplify the European engineering-house archetype with established medical device qualification protocols, while Nidec Corporation anchors the scale-driven tier through dominant production volumes in hard disk drive and industrial automation applications. Johnson Electric Holdings Limited occupies a position spanning both consumer electronics density and automotive specification-grade supply, reflecting the competitive pressure to bridge volume manufacturing with embedded control integration.
| Leading Market Players |
|---|
| AMETEK, Inc. |
| Johnson Electric Holdings Limited |
| Nidec Corporation |
| Mabuchi Motor Co., Ltd. |
| Siemens AG |
| Maxon Motor AG |
| Toshiba Corp. |
| ABB Ltd. |
| FAULHABER Group |
| Others |
Supply & Pricing Matrix
Automotive Tier-1 Supplier consolidation of supplier panels is forcing brushed DC motor manufacturers to absorb application engineering costs earlier in design cycles, compressing margins for standalone component vendors while rewarding integrated mechatronic subsystem providers with pricing power.
Pricing Analysis
Bundled mechatronic subsystems command premium positioning against unbundled motor-only supply as German and Japanese automotive buyers mandate embedded encoder feedback and PWM drive integration. Price differentiation separates specification-grade coreless architectures with REACH-compliant substance chains from commodity iron core variants serving Chinese consumer electronics manufacturers. Cost compression in the iron core tier intensifies because Shenzhen-based assemblers prioritize supply chain density over technical differentiation. Medical device producers in Switzerland exhibit the lowest price sensitivity due to Swissmandated qualification protocols, while consumer electronics manufacturers in Shenzhen show the highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth magnet processors that feed lamination and winding operations across German, Japanese, and Swiss precision motor facilities. Geographic supply concentration centers on China for neodymium magnet raw material, Japan for commutator surface engineering expertise, and Germany for precision-machined lamination tooling. Raw material dependencies draw from copper winding wire, laminated silicon steel, and sintered permanent magnet grades. Tariff exposure on magnet materials fragments multi-source manufacturing strategies for European automotive clients. Distribution runs through direct procurement relationships displacing traditional distributor channels for specification-grade products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Brushed DC Motor Market represents a late-cycle quality story as automotive electrification and medical device miniaturization shift procurement toward premium coreless architectures with documented compliance chains.
For Market Incumbents: Extend backward integration into rare earth magnet sourcing to defend margin position against neodymium price volatility. Anchor capacity expansion in India's PLI-subsidized automotive zones to capture localized electric vehicle subsystem demand. Certification investment in ECHA SCIP database documentation preserves European medical device and automotive Tier-1 access. For New Entrants and Emerging Players: The price-point gap between premium Swiss-engineered coreless motors and Chinese iron core commodities creates entry space for mid-tier digital control specialists. Agricultural machinery automation in the US Midwest offers the most penetrable white-space as encoder-PWM convergence penetrates precision valve control. A go-to-market angle targeting aftermarket service contracts for existing installed base equipment bypasses entrenched OEM supply relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with European precision engineering houses possessing established medical device qualification protocols and REACH-compliant substance documentation. Long-term viability over a multi-year horizon favors acquisition targets with captive magnet supply and embedded control integration capability. The signal to watch is brushless DC motor substitution rates in positioning applications requiring extended operational life.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Neodymium cost volatility protection secures margin stability for permanent magnet motor variants. |
| Encoder-PWM Drive Integration | Automotive Tier-1 Suppliers in Stuttgart and Nagoya mandate 12-bit resolution as standard specification. |
| India PLI Zone Manufacturing Footprint | Production-linked incentives for electric vehicle subsystems create localized assembly advantages. |
| ECHA SCIP Database Compliance Investment | European medical device producers extend supplier qualification timelines for documented substance chains. |
| Coreless Architecture R&D Expansion | Point-of-care diagnostic equipment penetration accelerates demand for minimal cogging torque motors. |
Research Methodology
Multiple input streams — primary interviews with automotive Tier-1 procurement officers, medical device engineering directors, and motor manufacturing plant managers; secondary validation through MIIT GB standard filings, ECHA SCIP database disclosures, and EPA electric motor efficiency regulations; plus customs trade data on magnet material flows — were reconciled through bottom-up and top-down triangulation.
Historical shipment data cross-referenced against panel input from precision motor specialists anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product construction type, control architecture technology, end-use application, and customer qualification intensity. CAGRs were derived from installed base replacement cycles and penetration rates for digital control integration. Industry-specific forecast inputs incorporated EU F-Gas Regulation compliance timelines and China's dual carbon goal enforcement trajectories.
Caveats apply where rare earth magnet price volatility, REACH substance restriction expansion, or brushless DC motor substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology transition speeds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Power Stacker Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Global Low Voltage Motors Market