
 Solar Drying System Market | 2026-2036
Solar Drying System Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Drying System Market Insights
Pay-as-you-go solar dryer leasing is reconfiguring competitive entry barriers across emerging markets. Ecozen Solutions leverages its thermal engineering expertise to dominate high-value horticulture corridors in South Asia. Suncue Company Ltd. anchors its position through proprietary heat-recapture technology that extends operational hours beyond peak sunlight. Rudra Solar Energy competes on modular system architecture that reduces installation labor for smallholder cooperatives.
A solar drying system harnesses radiant energy to reduce moisture content in organic materials through controlled thermal convection, typically operating between 40°C and 70°C with integrated humidity management to preserve product integrity. Direct solar dryers expose crops to incident radiation in transparent enclosures, while mixed-mode dryers supplement natural convection with forced airflow to achieve faster throughput and more uniform drying profiles. The agriculture end-user segment commands the largest installed base due to post-harvest loss reduction mandates, whereas hybrid photovoltaic-thermal systems represent the fastest-expanding technology category as stakeholders pursue round-the-clock operational capability.
India's Ministry of New and Renewable Energy, the Bureau of Indian Standards, and the Food Safety and Standards Authority of India collectively shape equipment certification pathways and food-contact material standards that determine market access for domestic and imported systems. The EU Green Deal and F-Gas Regulation indirectly redirect European agricultural investment toward solar thermal alternatives by constraining conventional refrigerant-based dehydration methods. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their potential to reprice solar-dried commodity exports from developing producer nations.
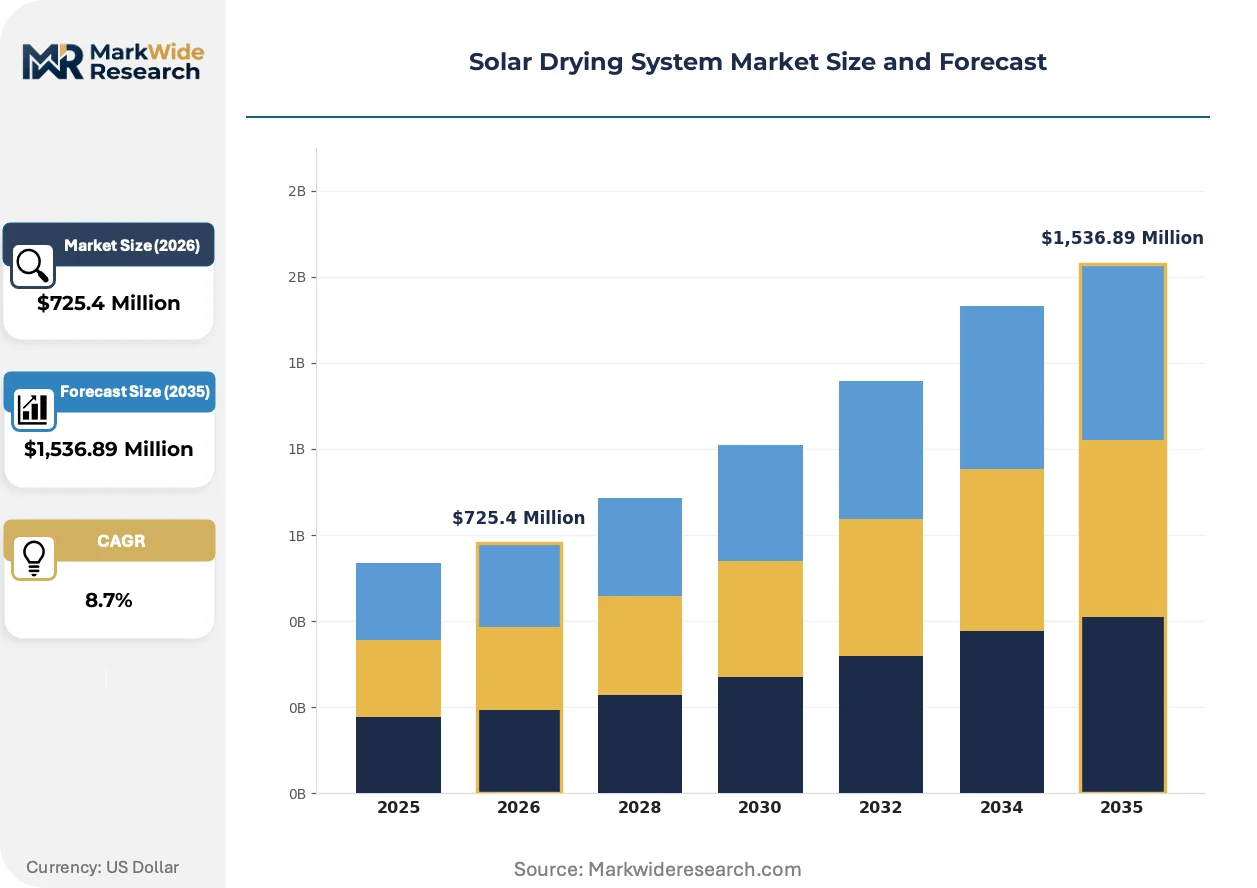
Market Dynamics
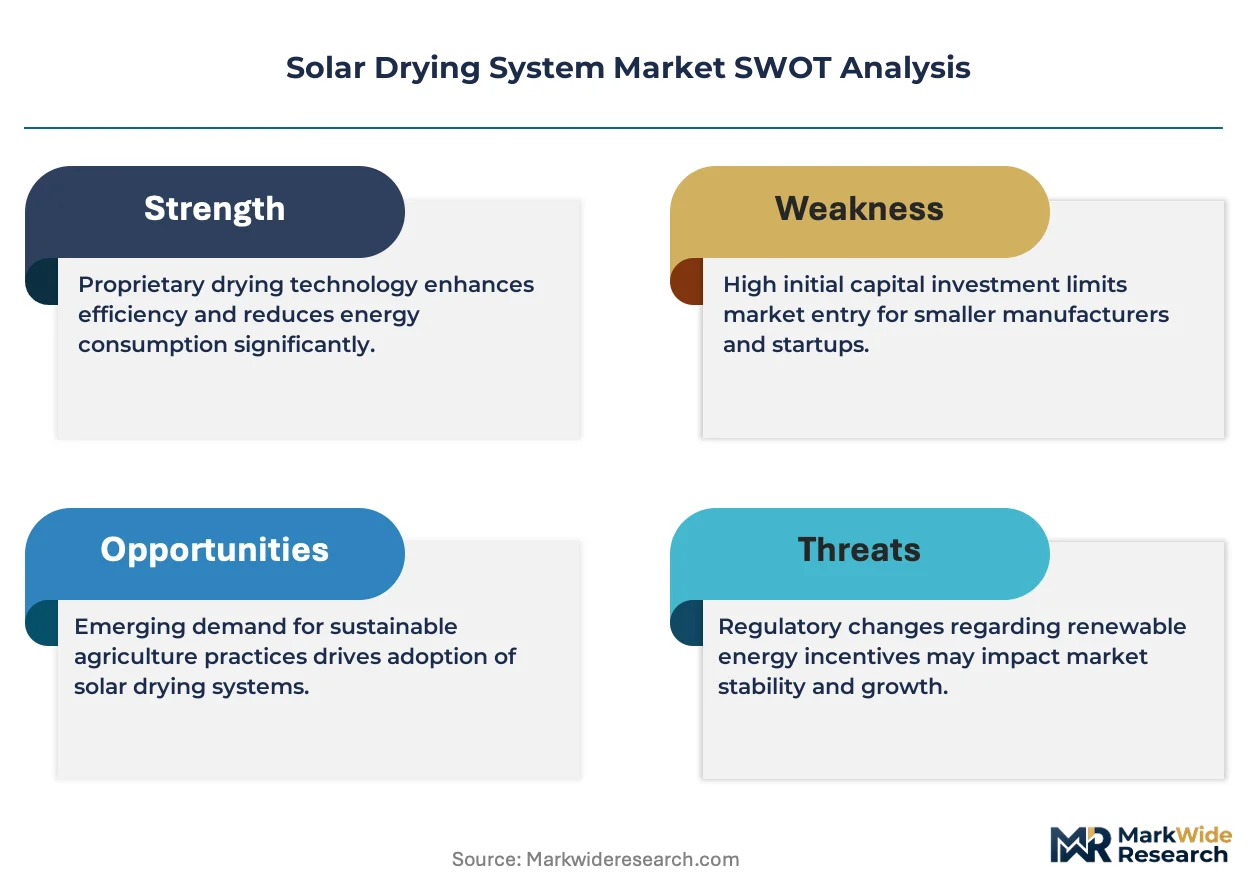
Hybrid photovoltaic-thermal architectures are compressing operational downtime for solar drying systems, forcing incumbents to reengineer thermal storage subsystems or cede horticulture contracts to integrated competitors.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic module cost reductions are accelerating equipment localization for Maharashtra and Gujarat dryer producers.
- Post-harvest loss reduction mandates:Agricultural cooperatives in sub-Saharan Africa are expanding procurement of decentralized drying infrastructure.
- Heat-recapture technology:Extended operational hours beyond peak sunlight are improving throughput economics for high-value crop processors.
Market Restraints
- Aluminum and tempered glass price volatility:Enclosure material cost swings compress margins for batch-type dryer manufacturers.
- Supply concentration in Chinese PV cell production:Import dependency creates tariff exposure for non-integrated system assemblers.
- Limited thermal storage density:Current phase-change materials cannot sustain overnight operations without auxiliary biomass heating.
Strategic Opportunities
- Kenya and Ethiopia horticulture corridors:Underpenetrated smallholder cooperatives present first-mover leasing opportunities for pay-as-you-go models.
- EU F-Gas Regulation constraints:Refrigerant-based dehydration restrictions are redirecting investment toward solar thermal alternatives in Mediterranean processing zones.
- IoT-enabled humidity management:Sensor-to-cloud integration is opening premium service tiers for traceability-conscious exporters.
Industry Challenges
- Thermal engineering talent scarcity:System integrators face recruitment bottlenecks for convection modeling specialists.
- Bureau of Indian Standards certification timelines:Food-contact material testing delays extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Drying System Market |
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,536.89 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indirect Solar Dryers, Direct Solar Dryers, Mixed-Mode Dryers, Solar Tunnel Dryers End User: Agriculture, Food Processing, Pharmaceuticals, Textile Manufacturing Technology: Thermal Solar, Photovoltaic, Hybrid Systems, Evaporative Cooling Application: Fruits, Grains, Vegetables, Herbs |
| Companies Covered | Ecozen Solutions, Suncue Company Ltd., Solar Dryers Australia, Agro Solar Europe GmbH, SunBest Solutions, Solar Constructions, Vikram Solar, SunPower Corporation, Rudra Solar Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Drying System Market Trends and Innovations
Digital twin platforms are compressing design-to-deployment cycles for solar dryer configurations, while regulatory carbon-accounting requirements reshape specification priorities across export-oriented agricultural clusters.
Computational fluid dynamics software is virtualizing thermal chamber design validation before physical prototyping. Horticulture processing cooperatives in Gujarat and Maharashtra are adopting these simulation tools to customize airflow patterns for specific crop moisture profiles. The technology is virtualizing traditional empirical testing methods, reducing engineering iteration costs by eliminating multiple prototype builds.
The EU Green Deal's carbon-border adjustment mechanism is repositioning solar-dried commodity competitiveness for developing nation exporters. Agricultural processors in Kenya and Ethiopia must now document renewable thermal input shares to maintain EU market access. Dried fruit and spice exporters are responding by retrofitting hybrid systems with certified renewable thermal monitoring.
Cooperative procurement consortia are aggregating smallholder demand into volume-based equipment tenders. Maharashtra grape-drying associations are displacing individual farmer purchases with collective leasing arrangements that include maintenance and yield guarantees. This aggregation model concentrates buyer power and shifts vendor relationships toward long-term service contracts rather than transactional equipment sales.
Solar Drying System Market Segmentation
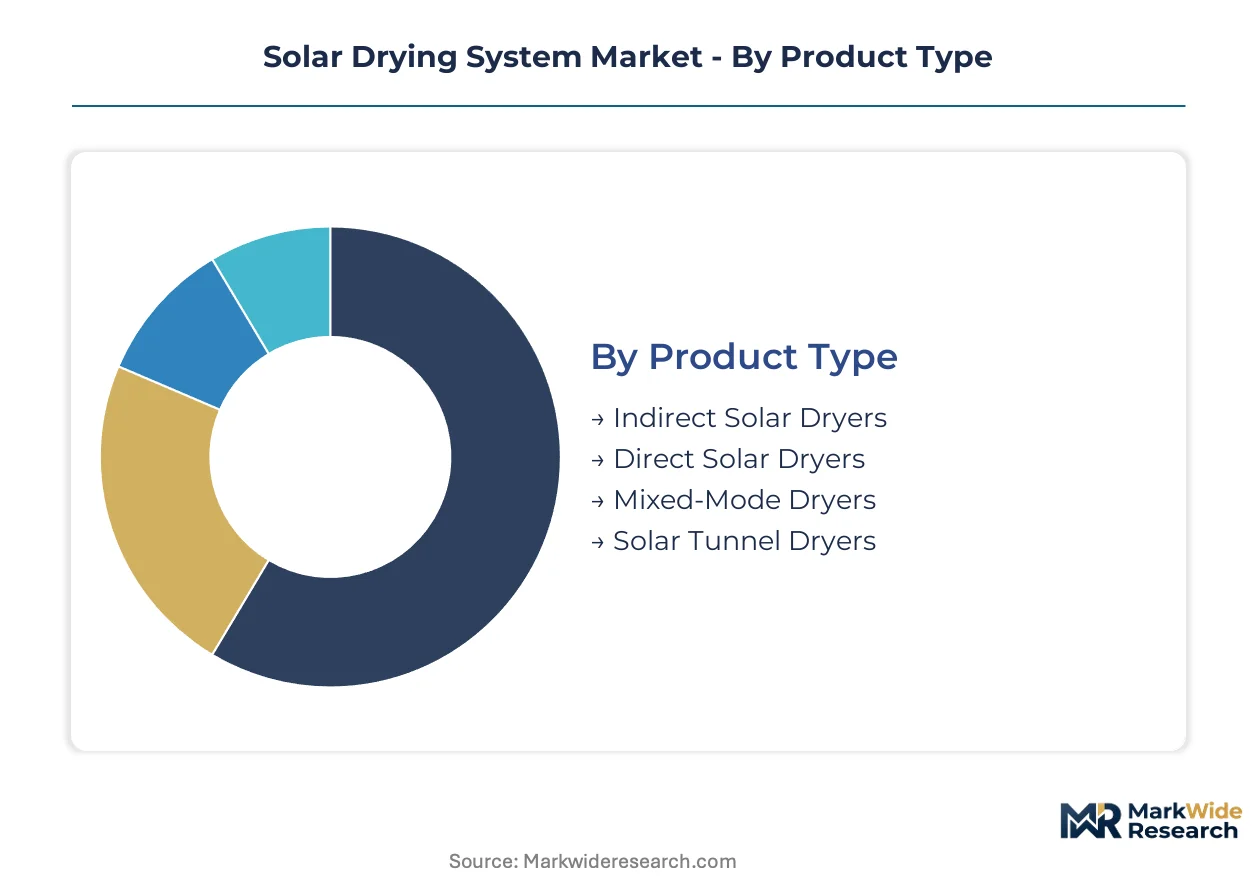
Solar drying system configurations diverge sharply across thermal architectures, end-use moisture requirements, and energy hybridization strategies. Equipment specification choices cascade into operational economics, installation complexity, and regulatory compliance pathways.
Product Type:
Cost tier differentiation separates enclosed thermal chambers from open-air exposure designs, with capital intensity tracking enclosure sophistication and airflow control mechanisms.
- Indirect Solar Dryers:These systems separate the solar collector from the drying chamber using heat exchangers, protecting sensitive crops from direct UV degradation. Demand concentrates in pharmaceutical herb processing across Maharashtra and Gujarat, where FSSAI contact-material standards mandate enclosed thermal pathways.
- Direct Solar Dryers:Transparent enclosures expose crops directly to incident radiation, minimizing component count and capital outlay. Smallholder cooperatives in sub-Saharan Africa prioritize these units for grains and pulses where color retention is secondary to throughput economics.
- Mixed-Mode Dryers:Forced airflow supplementation accelerates moisture removal beyond natural convection limits.
- Solar Tunnel Dryers:Continuous-flow designs suit high-volume commodity processors with steady feedstock supply.
Direct solar dryers hold installed capacity. Mixed-mode dryers are rotating up the share rankings.
End User:
Application-specific moisture precision requirements determine equipment specification tiers, with pharmaceutical and food-contact segments commanding premium thermal control architectures.
- Agriculture:Post-harvest loss reduction mandates drive procurement across cooperative networks, with Maharashtra grape-drying associations and Ethiopian coffee cooperatives deploying decentralized units to replace open-air sun drying.
- Food Processing:Export-oriented spice and dried fruit processors require humidity traceability documentation for EU carbon-border compliance, pushing adoption of IoT-enabled hybrid systems in Kenya and Ethiopia horticulture corridors.
- Pharmaceuticals:Active ingredient stability demands precise temperature band maintenance.
- Textile Manufacturing:Low-temperature fabric conditioning applications favor simple thermal collector designs.
Agriculture dominates procurement volumes. Food processing is climbing the fastest as export certification requirements tighten.
Technology:
Energy capture modality selection shapes operational autonomy, with hybrid architectures compressing downtime through photovoltaic-electrical backup integration.
- Thermal Solar:Absorber plate and glazing assemblies convert radiation to convective heat without electrical conversion losses. Batch processors in Gujarat horticulture clusters favor these for daytime-only operations with minimal maintenance requirements.
- Photovoltaic:Solar-electric conversion powers forced ventilation and control systems, enabling precise humidity management.
- Hybrid Systems:Combined thermal collection and electrical generation sustain overnight operations through battery storage, representing the steepest expansion trajectory as EU importers demand renewable thermal input documentation.
- Evaporative Cooling:Pre-drying humidity reduction extends effective drying windows in high-humidity climates.
Thermal solar retains the largest installed base. Hybrid systems are gaining share fastest on export compliance requirements.
Application:
Moisture content targets and product fragility dictate chamber design specifications, with high-value perishables justifying sophisticated thermal control investments.
- Fruits:Sugar-rich matrices require gentle temperature ramps to prevent case hardening and preserve rehydration capacity. Maharashtra grape and mango processors deploy indirect dryers with phase-change thermal storage for uniform drying profiles.
- Grains:Robust seed structures tolerate direct solar exposure and higher temperature bands. Smallholder cooperatives across Ethiopia and Kenya prioritize simple tunnel designs for maize and sorghum with minimal capital recovery periods.
- Vegetables:Enzymatic browning sensitivity drives demand for rapid moisture removal.
- Herbs:Volatile oil preservation mandates low-temperature indirect drying.
Grains command the largest installed capacity. Fruits are rotating up the share rankings on export value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for solar manufacturing is accelerating equipment localization for domestic dryer producers. Agricultural cooperatives in sub-Saharan Africa are expanding procurement of decentralized drying infrastructure. Export-oriented processors in Kenya and Ethiopia face tightening EU carbon-border compliance requirements.
India
Maharashtra grape-drying associations and Gujarat horticulture clusters drive concentrated demand for hybrid photovoltaic-thermal systems. The Ministry of New and Renewable Energy shapes equipment certification pathways through BIS standards and FSSAI food-contact material regulations. Nashik and Solapur districts host cooperative procurement consortia that aggregate smallholder demand into volume-based equipment tenders with maintenance guarantees.
Kenya
Smallholder cooperatives in coffee and dried fruit corridors seek pay-as-you-go leasing models to bypass capital constraints. The national agricultural regulator enforces post-harvest loss reduction mandates that redirect investment from open-air drying. Nakuru and Meru counties concentrate deployment of tunnel dryers for maize and sorghum with minimal capital recovery periods.
Ethiopia
Horticulture exporters require renewable thermal input documentation to maintain EU market access under carbon-border adjustment mechanisms. The country's investment commission facilitates foreign equipment partnerships for spice and dried fruit processors. Sidama and Yirgacheffe coffee-growing zones deploy decentralized units to replace traditional sun-drying methods.
Germany
EU F-Gas Regulation constraints redirect Mediterranean agricultural investment toward solar thermal alternatives. ECHA and EFSA standards govern food-contact materials and active ingredient stability for pharmaceutical herb processors. Bavaria and Baden-Württemberg host precision engineering firms supplying thermal storage subsystems to system integrators.
United States
USDA conservation programs incentivize on-farm renewable energy installations for post-harvest operations. FDA food safety standards determine equipment specifications for domestic dried fruit and nut processors. California Central Valley nut growers and Arizona date producers pilot hybrid systems with battery-backed overnight operations.
Solar Drying System Market Competitive Landscape
On the supply side, the industry is fragmented across thermal engineering specialists, photovoltaic module assemblers, and agricultural equipment fabricators. Tiered competitive positioning separates integrated system providers from component suppliers and regional installation contractors. Three archetypes dominate: thermal engineering specialists with heat-recapture IP, modular architecture providers targeting smallholder cooperatives, and PV-integrated hybrid system developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as stakeholders pursue round-the-clock operational capability.
Among Asia-Pacific thermal engineering specialists, Ecozen Solutions and Suncue Company Ltd. exemplify the integrated system archetype through proprietary convection management. Rudra Solar Energy occupies a position within the modular architecture tier serving cooperative networks. These three anchors illustrate how competitive differentiation clusters around thermal storage density, installation labor reduction, and export compliance documentation capabilities rather than pure equipment cost.
| Leading Market Players |
|---|
| Ecozen Solutions |
| Suncue Company Ltd. |
| Solar Dryers Australia |
| Agro Solar Europe GmbH |
| SunBest Solutions |
| Solar Constructions |
| Vikram Solar |
| SunPower Corporation |
| Rudra Solar Energy |
| Others |
Pricing and Supply Chain Analysis
The Mundra Port logistics corridor compresses landed costs for tempered glass and aluminum enclosures while amplifying price differentiation between BIS-certified and uncertified equipment tiers across Maharashtra and Gujarat procurement clusters.
Pricing Analysis
Certification level (BIS/FSSAI-grade) creates the primary spread between premium and economy tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers bundling IoT-enabled humidity management and export compliance documentation. Cost compression in standard tiers is intensifying because aluminum price volatility erodes assembler margins. Smallholder cooperatives in sub-Saharan Africa exhibit highest price sensitivity, while EU-facing export processors in Kenya and Ethiopia prioritize certification-grade equipment regardless of premium positioning.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for photovoltaic cell sourcing. Manufacturing concentrates in China, India, and Germany, with Chinese PV cells feeding modular assembly operations in Gujarat and Maharashtra. Raw material dependencies center on aluminum sheeting, tempered glass, and phase-change thermal storage media. Single-source vulnerability in Chinese PV cell production creates procurement fragility for non-integrated system assemblers. Distribution runs through cooperative procurement consortia and agricultural equipment dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive dynamics as pay-as-you-go leasing ecosystems aggregate smallholder demand and lock in long-term service relationships across sub-Saharan Africa and South Asia.
For Market Incumbents: Insulate core horticulture contracts in Maharashtra and Gujarat through captive thermal storage subsystem production and accelerated BIS certification timelines. Hybrid photovoltaic-thermal entrants threaten integrated providers by offering round-the-clock operational guarantees. Backward integration into phase-change material sourcing secures margin control against commodity volatility. For New Entrants and Emerging Players: Establish a beachhead in Kenyan and Ethiopian smallholder cooperative networks through pay-as-you-go leasing models with embedded maintenance guarantees. Underpenetrated coffee and dried fruit corridors present lowest competitive density. Partner with local agricultural regulators to align equipment specifications with post-harvest loss reduction mandates. For Investors and Strategic Acquirers: Thermal engineering specialists with proprietary heat-recapture IP represent the most defensible acquisition archetype for long-term positioning across the 5-10 year window. These firms command pricing power through extended operational hour guarantees that hybrid competitors struggle to replicate. Monitor EU carbon-border adjustment mechanism enforcement intensity as the critical inflection signal for renewable thermal input documentation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Capacity Expansion | Round-the-clock operational capability captures EU export compliance contracts from thermal-only competitors. |
| Backward Integration into Thermal Storage | In-house phase-change material production insulates margins from commodity price swings in aluminum and glass. |
| IoT-Enabled Service Tier Launch | Sensor-to-cloud humidity traceability opens premium pricing for carbon-border documentation requirements. |
| Cooperative Procurement Partnership | Long-term leasing arrangements with Maharashtra grape-drying associations displace transactional equipment sales. |
| BIS Certification Fast-Track Investment | Accelerated food-contact material approval compresses product launch cycles against 8-14 month standard timelines. |
Research Methodology
Initial hypotheses were tested against primary input from thermal engineering directors, agricultural cooperative procurement managers, and MNRE policy officers and refined through secondary validation. Stakeholder interviews combined with customs trade data, BIS certification registries, FSSAI food-contact material filings, and EU carbon-border adjustment mechanism documentation. Bottom-up equipment deployment estimates and top-down renewable energy investment flows were triangulated for consistency.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include thermal architecture type, end-use moisture precision tier, energy hybridization strategy, and regional regulatory cluster. CAGRs were derived from installed base growth trajectories and replacement cycle analysis. Phase-change material cost curves and photovoltaic module localization rates under India's PLI scheme served as industry-specific forecast inputs.
Stress conditions across aluminum price volatility, Chinese PV cell tariff exposure, and EU carbon-border enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cooperative procurement aggregation rates and thermal storage technology maturation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Solar Boat Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
China Renewable Energy Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Poland Renewable Energy Market