
 Flatwire & HAIR-PIN Motor Market | 2026-2036
Flatwire & HAIR-PIN Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Flatwire & HAIR-PIN Motor Market Insights
Copper winding technician availability is collapsing across established motor manufacturing hubs, forcing tier-one suppliers to automate hair-pin forming and laser-welding lines faster than workforce pipelines can refill. BorgWarner leverages its integrated powertrain division to capture flatwire stator contracts from premium EV platforms. Denso sustains Japanese OEM relationships through proprietary rectangular wire insulation systems. Bosch dominates European demand with scalable hair-pin architectures that accommodate 800-volt architectures.
Flatwire and hair-pin motors employ rectangular copper conductors arranged in precise slot configurations, typically achieving slot fill factors of 60-70% compared to 40-50% for conventional round-wire windings, with continuous laser welding replacing traditional splice connections to reduce ohmic losses and improve thermal dissipation. These motors primarily serve traction applications where power density and continuous duty cycles determine vehicle range and acceleration performance. AC Motors occupy the largest revenue share due to their prevalence in EV traction systems, while Servo Motors represent the fastest-expanding category as robotics and precision automation demand higher torque-per-unit-volume ratios. Automotive OEMs command the deepest margin pools among end users, though Industrial Automation is gaining share as servo-grade flatwire designs penetrate semiconductor fabrication equipment.
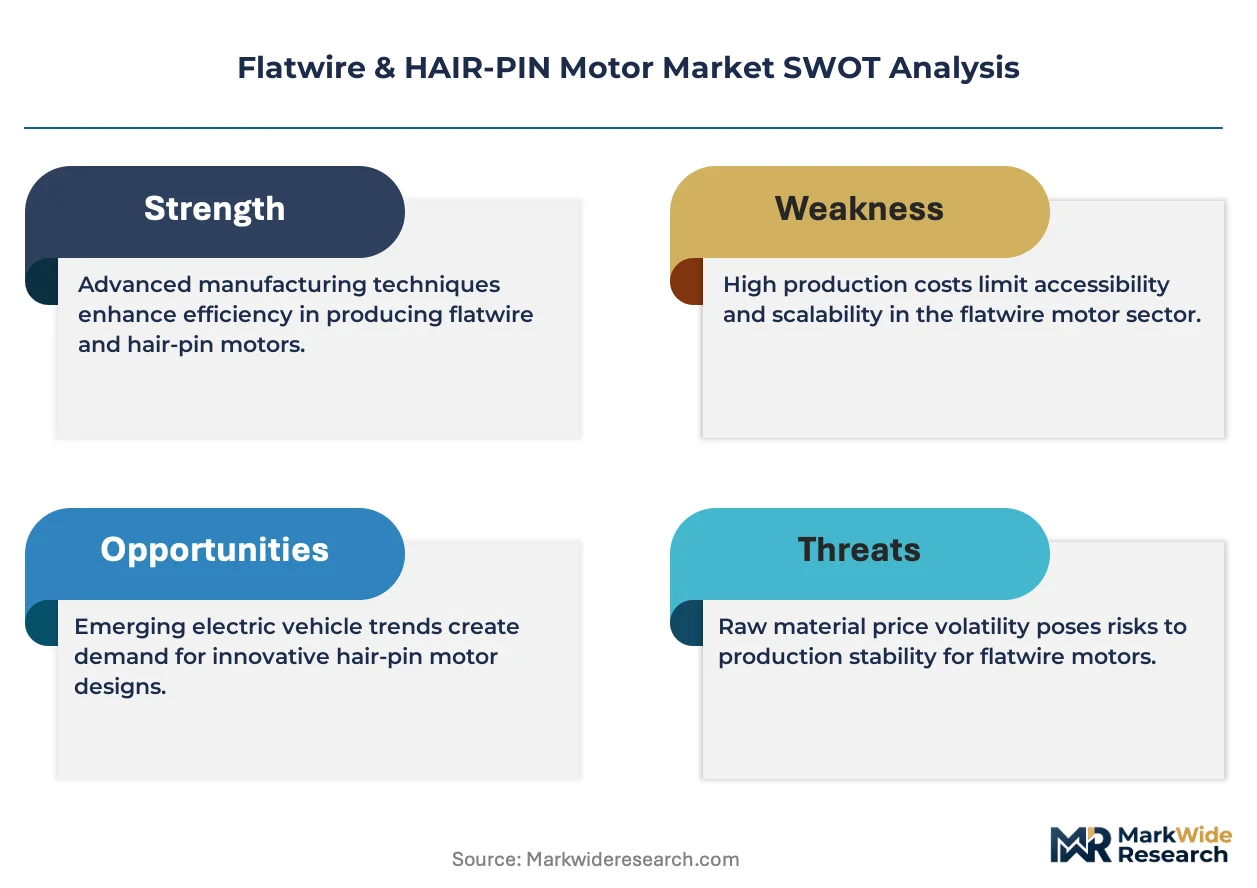
EPA tailpipe regulations and the EU Green Deal's CO2 fleet mandates are forcing powertrain electrification timelines that outpace round-wire motor refresh cycles, directly accelerating hair-pin platform commitments. China's MIIT dual carbon goals and NEV credit mandates favor domestic suppliers like BYD Company with captive flatwire winding capacity. NHTSA fuel economy standards in the United States are tightening concurrently, creating a three-jurisdiction regulatory squeeze that standardizes hair-pin architectures as the default high-efficiency pathway. Stakeholders must monitor copper price volatility and winding equipment lead times as the binding constraints on capacity expansion rather than end-market demand alone.
Market Dynamics
The transition from round-wire to flatwire stator architectures is compressing motor refresh cycles across automotive powertrain programs, forcing winding equipment investments ahead of confirmed platform volumes.
Growth Catalysts
- EU Green Deal CO2 Fleet Mandates:The tightened emissions framework is eliminating ICE powertrain development budgets, redirecting R&D toward hair-pin motor architectures that maximize slot fill and thermal performance.
- 800-volt EV architectures:Premium electric vehicle platforms are specifying continuous laser-welded hair-pin windings to handle higher current densities and reduce ohmic losses at elevated voltages.
- Germany's automotive supplier corridor:Concentrated winding equipment capacity and technician training infrastructure around Stuttgart and Munich are accelerating prototype-to-production timelines for flatwire stators.
Market Restraints
- Copper price volatility:Rectangular conductor raw material exposure creates margin compression that round-wire competitors can hedge more effectively through established commodity contracts.
- Winding equipment lead times:German and Japanese hair-pin forming machine builders carry order backlogs exceeding eighteen months, capping capacity expansion regardless of end-market demand.
- Rectangular wire insulation systems:Proprietary enamel formulations from Japanese suppliers create single-source dependencies that limit second-sourcing flexibility for tier-one motor manufacturers.
Strategic Opportunities
- Industrial automation servo motors:Semiconductor fabrication equipment and precision robotics are specifying flatwire designs for torque density advantages in confined motion envelopes.
- China's MIIT dual carbon goals:Domestic NEV credit mandates favor suppliers with captive flatwire winding capacity, creating procurement preference for vertically integrated motor producers.
- Laser welding convergence with machine vision:Real-time quality inspection during stator assembly is reducing rework rates and enabling traceability for automotive safety-critical applications.
Industry Challenges
- Copper winding technician scarcity:Skilled labor pipelines in established motor manufacturing hubs cannot refill positions lost to retirement, forcing premature automation of hair-pin forming lines.
- Stator-rotor thermal matching:Higher slot fill factors generate heat flux densities that exceed legacy cooling system specifications, requiring concurrent redesign of thermal management subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flatwire & HAIR-PIN Motor Market |
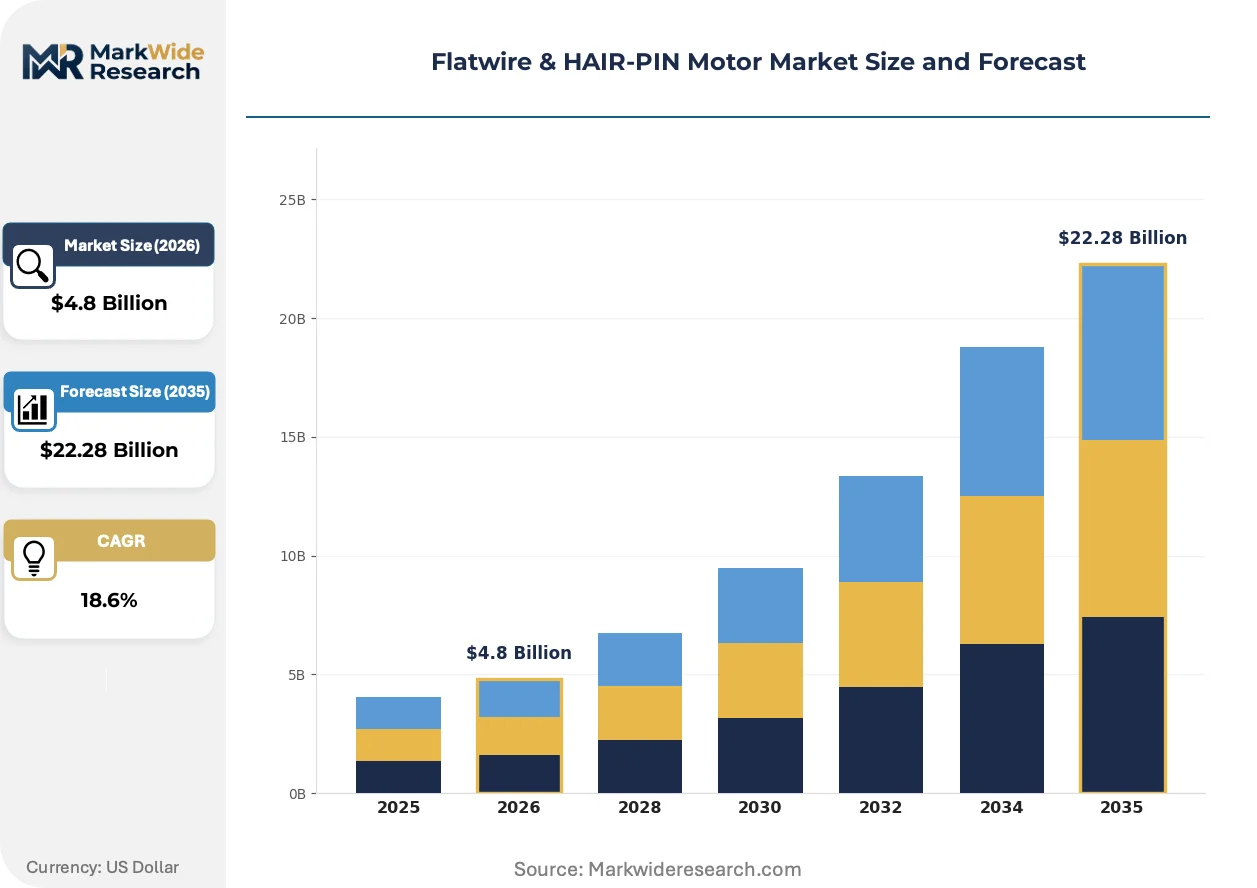
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Stepper Motors, Servo Motors End User: Aerospace, Automotive OEMs, Consumer Electronics, Industrial Automation Therapy Area: Power Tools, Home Appliances, HVAC Systems, Robotics Technology: Brushless, Synchronous, Asynchronous, Linear |
| Companies Covered | BorgWarner, Denso, Huayu Automotive Systems, Hitachi, Schaeffler Group, Magna International, BYD Company, Bosch, Nidec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flatwire & HAIR-PIN Motor Market Trends and Innovations
Hair-pin motor architectures are fragmenting into specialized variants optimized for distinct thermal and electrical duty cycles, diverging from the early standardization around single form-factor designs.
Continuous laser welding of hair-pin joints is decomposing the traditional splice connection paradigm in high-performance traction motors. Automotive OEMs are specifying welded architectures for 800-volt platforms to minimize contact resistance and enable higher continuous current ratings. This shift is compressing the market position of mechanical crimping equipment suppliers while elevating fiber laser system vendors into critical tier-one status.
The EU's F-Gas Regulation is restricting fluorinated greenhouse gases used in certain motor cooling systems, forcing manufacturers toward dielectric oil or water-glycol alternatives. Industrial motor producers serving European export markets are reformulating thermal management strategies to maintain efficiency certifications. HVAC and compressor applications face the most immediate compliance pressure, with redesign cycles accelerating to meet 2027 phase-down targets.
Buyer concentration among automotive OEMs is consolidating flatwire stator procurement into single-source framework agreements with multi-year volume commitments. Tier-one suppliers are accepting penalty clauses for capacity shortfalls in exchange for guaranteed minimum offtake. Germany and China's NEV corridors exhibit this pattern most visibly, with industrial automation buyers beginning to emulate similar security-of-supply contracting.
Flatwire & HAIR-PIN Motor Market Segmentation
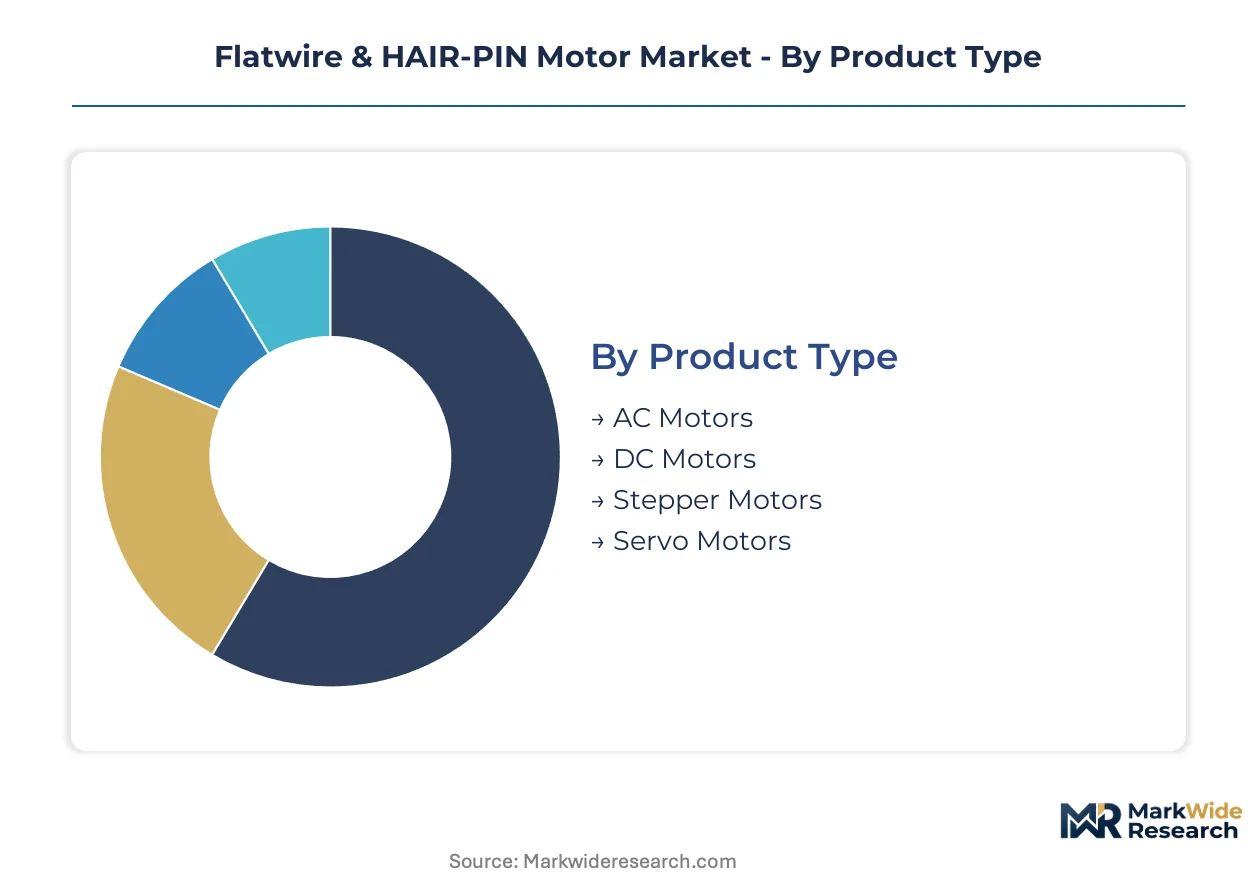
Rectangular conductor architectures demand precise segmentation to capture how slot fill factors and thermal performance vary across duty cycles. Regulatory pressure on powertrain efficiency is fragmenting procurement patterns by voltage class and end-use certification requirements.
Product Type:
EU Green Deal CO2 mandates and NHTSA fuel economy standards are segmenting motor procurement by continuous duty ratings and thermal envelope specifications.
- AC Motors:Synchronous and asynchronous alternating current designs dominate traction applications where variable frequency drives manage torque delivery. Automotive OEMs in Germany's supplier corridor specify these for 800-volt EV platforms requiring continuous laser-welded joints. Established volume favors AC Motors; emerging adoption favors Servo Motors.
- DC Motors:Direct current configurations with commutator mechanisms persist in cost-sensitive auxiliary systems where simple speed control suffices. Power tool manufacturers and aftermarket automotive suppliers source these from Chinese winding facilities with shorter equipment lead times.
- Stepper Motors:Discrete angular positioning drives with rectangular windings enable precise motion control in semiconductor fabrication equipment. Japanese automation integrators specify these for cleanroom robotics where step accuracy determines yield rates.
- Servo Motors:Closed-loop feedback systems with hair-pin windings achieve torque densities exceeding 5 kW per liter in confined motion envelopes. Industrial automation buyers in precision robotics and CNC machining centers are driving fastest category expansion.
AC Motors retain the deepest revenue base from EV traction commitments; servo-grade designs are climbing fastest as factory automation density increases.
End User:
Customer procurement power concentrates among buyers with multi-year platform volumes and penalty-backed framework agreements.
- Automotive OEMs:Tier-one powertrain divisions command dedicated flatwire winding capacity through captive supplier relationships. 800-volt platform specifications from premium European and Chinese manufacturers are standardizing hair-pin architectures across model ranges. These buyers extract steepest pricing leverage through volume guarantees.
- Industrial Automation:Semiconductor equipment builders and precision robotics OEMs specify servo-grade flatwire motors for torque-per-unit-volume advantages. German and Japanese machine tool manufacturers are consolidating procurement into single-source agreements mirroring automotive contracting patterns.
- Aerospace:Aircraft actuation and auxiliary power systems require certified rectangular wire insulation systems meeting AS9100 quality standards. Dual-source mandates from FAA-regulated programs limit supplier concentration despite technical performance advantages.
- Consumer Electronics:High-volume appliance and personal device manufacturers prioritize round-wire alternatives where slot fill optimization does not justify hair-pin equipment capital expenditure.
Automotive OEMs dominate committed capacity; industrial automation buyers are gaining procurement sophistication fastest.
Application Area:
Thermal duty cycles and continuous operation requirements segment demand by cooling system complexity and insulation class.
- HVAC Systems:Compressor motors in heat pumps and climate control equipment face EU F-Gas Regulation compliance pressure. Manufacturers are reformulating thermal management toward dielectric oil alternatives as fluorinated greenhouse gas restrictions tighten.
- Robotics:Articulated arm joints and gantry systems specify flatwire servo motors for acceleration bandwidth in confined envelopes. Chinese MIIT dual carbon goals favor domestic suppliers with captive winding capacity for factory automation deployments.
- Power Tools:Cordless and corded handheld equipment uses hair-pin designs where power-to-weight ratios determine professional user adoption. Brushless DC variants with rectangular windings are displacing brushed architectures in premium product tiers.
- Home Appliances:Washing machine drums and refrigerator compressors represent volume applications where round-wire motors retain cost advantages. Hair-pin penetration concentrates in energy efficiency premium tiers subject to EU Ecodesign regulations.
HVAC applications face regulatory redesign pressure; robotics is expanding most quickly on factory automation investment cycles.
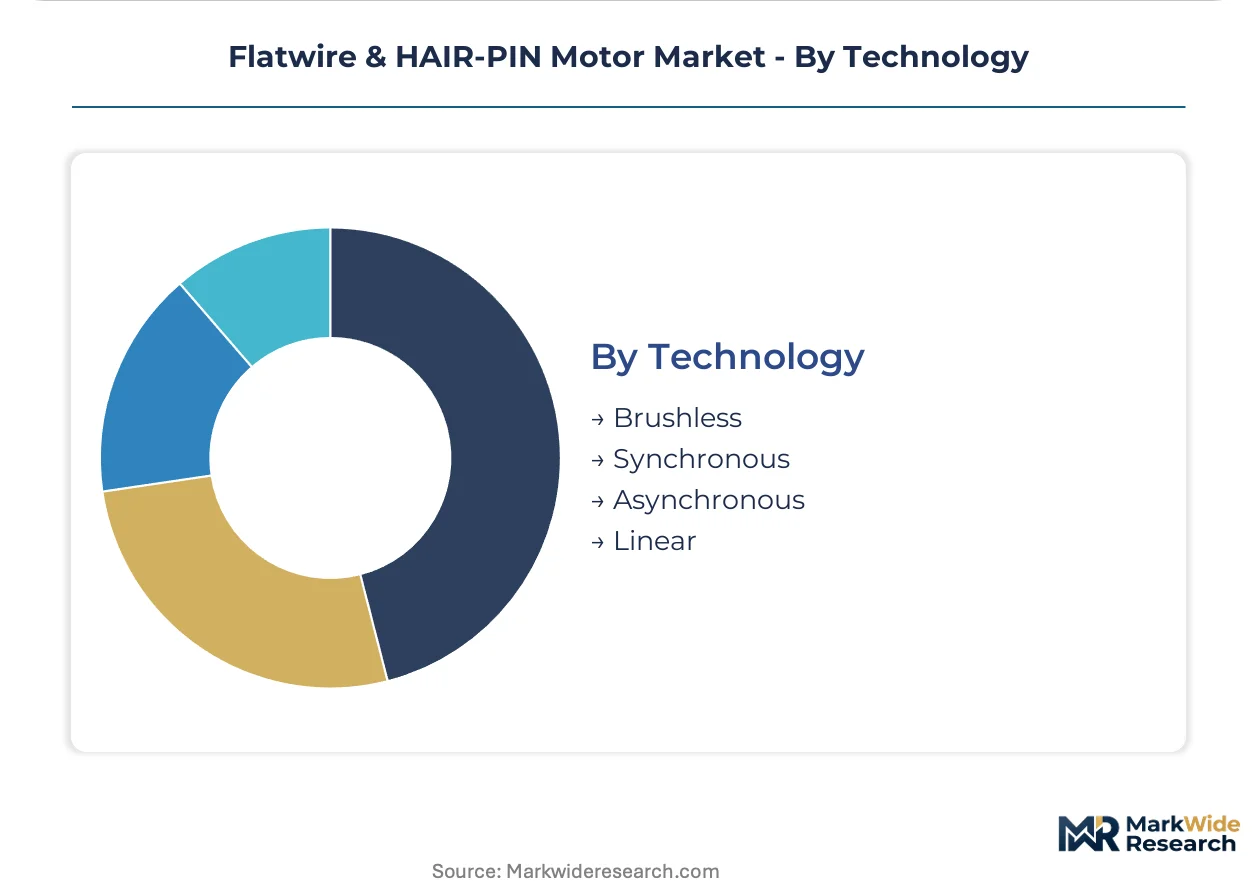
Technology:
Commutation and field excitation methods determine winding complexity and controller integration requirements.
- Brushless:Electronic commutation eliminates mechanical wear in high-speed traction and servo applications. Permanent magnet rotor designs with hair-pin stators achieve peak efficiencies exceeding 97% in 800-volt EV powertrains.
- Synchronous:Field-excited or permanent magnet configurations maintain constant speed under load variations. Grid-tied industrial drives and generator applications specify these for power factor correction capabilities.
- Asynchronous:Induction rotor designs without permanent magnets reduce raw material exposure to rare earth price volatility. Cost-optimized HVAC and pump applications favor these for supply security.
- Linear:Direct force generation without rotary-to-linear conversion enables precision positioning in maglev transport and semiconductor wafer handling. Specialized winding geometries require custom hair-pin forming equipment with extended lead times.
Brushless architectures command premium positioning; linear motor technology represents narrowest but highest-margin specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon goals and NEV credit mandates anchor China's procurement dominance, while Germany's supplier corridor and the United States' NHTSA standards create parallel demand poles for hair-pin motor architectures.
Germany
Stuttgart and Munich host concentrated winding equipment capacity serving premium EV platform specifications. The EU Green Deal CO2 fleet mandates eliminate ICE development budgets, redirecting R&D toward scalable hair-pin architectures. Bosch dominates European demand with 800-volt compatible designs from Baden-Württemberg facilities.
China
Domestic NEV subsidy restructuring favors vertically integrated motor producers with captive flatwire winding capacity. MIIT dual carbon goals and NEV credit mandates accelerate procurement from suppliers like BYD Company with in-house production capabilities. Yangtze River Delta manufacturing clusters concentrate prototype-to-production timelines for automotive OEMs.
United States
NHTSA fuel economy standards tighten concurrently with European and Chinese regulations, creating a three-jurisdiction squeeze on powertrain electrification. EPA tailpipe regulations force hair-pin platform commitments ahead of round-wire refresh cycles. Michigan and Ohio automotive corridors attract dedicated winding capacity from tier-one suppliers.
Japan
METI industrial policy supports rectangular wire insulation system development through proprietary enamel formulations. Denso sustains domestic OEM relationships with specialized thermal management designs. Nagoya and Tokyo metropolitan areas concentrate servo-grade motor production for precision automation export markets.
South Korea
Seoul Capital Area battery and motor manufacturing clusters serve Hyundai-Kia EV platform specifications. Government EV transition targets accelerate hair-pin stator adoption across 800-volt architectures. Busan-Ulsan industrial zones host winding equipment investments from automotive tier-one suppliers.
Flatwire & HAIR-PIN Motor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated powertrain divisions commanding premium platform access while specialized winding houses capture industrial automation niches. The market structure tiers into three strategic archetypes: diversified automotive suppliers with captive motor divisions, pure-play motor specialists with proprietary insulation systems, and vertically integrated Chinese producers with domestic NEV procurement preference. Dominant competitive moves include capacity expansion in Germany's supplier corridor and strategic partnerships securing laser welding equipment allocation.
Among diversified automotive suppliers, BorgWarner, Denso, and Bosch occupy positions exemplifying integrated powertrain strategies. BorgWarner represents the archetype leveraging divisional integration for premium EV platform contracts. Denso anchors Japanese OEM relationship maintenance through specialized thermal and insulation capabilities. Bosch exemplifies European scalability with hair-pin architectures accommodating high-voltage traction requirements. These three entities sit within the tier commanding deepest automotive OEM procurement leverage through multi-year framework agreements.
| Leading Market Players |
|---|
| BorgWarner |
| Denso |
| Huayu Automotive Systems |
| Hitachi |
| Schaeffler Group |
| Magna International |
| BYD Company |
| Bosch |
| Nidec Corporation |
| Others |
Pricing and Supply Chain Analysis
Multi-year framework agreements with penalty-backed volume commitments lock in both supply access and price visibility for automotive OEMs, compressing margin flexibility for tier-one suppliers while insulating end-users from copper volatility exposure.
Pricing Analysis
German automotive OEMs pay premiums of 15-20% above Chinese contract rates for identical slot-fill specifications, reflecting EU Green Deal compliance costs and localized winding capacity scarcity. Three-tier pricing structure across premium, standard, and economy levels separates 800-volt laser-welded architectures from 400-volt crimped joints and round-wire legacy designs. Pricing pressure stems from Chinese vertically integrated producers capturing domestic NEV procurement preference through MIIT credit-mandated sourcing. Industrial automation buyers exhibit highest price sensitivity due to fragmented procurement volumes, while premium EV platform engineers accept cost premiums for thermal performance guarantees.
Supply Chain Analysis
German and Japanese hair-pin forming machine builders constitute a chokepoint that caps global capacity expansion regardless of end-market demand. Raw material flows draw from Chilean copper cathode, Chinese rare earth processing, and Japanese enamel insulation formulations. Single-source vulnerability concentrates in proprietary rectangular wire coating systems from Nagoya-area chemical specialists. Distribution runs through tier-one powertrain divisions with captive supplier relationships rather than open merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among automotive OEMs with multi-year platform volumes, fragmenting tier-one supplier margins through penalty-backed framework agreements that extract guaranteed minimum offtake.
For Market Incumbents: Secure laser welding equipment allocation through strategic partnerships with fiber laser system vendors before order backlogs extend beyond equipment lead time horizons. Lock in copper cathode offtake through backward integration into scrap recycling or long-term smelter contracts to hedge against commodity volatility that round-wire competitors manage more effectively. Capacity addition in China's Yangtze River Delta manufacturing clusters addresses MIIT dual carbon procurement preference before domestic vertically integrated producers capture incremental NEV platform share. For New Entrants and Emerging Players: Aftermarket remanufacturing services for traction motor stator rewinding represents a service-layer gap where incumbents under-serve fleet operators seeking cost-optimized life extension. Target semiconductor fabrication equipment servo motor retrofits as the most penetrable segment, where torque density requirements outpace incumbent round-wire refresh cycles. Pursue laser welding-as-a-service go-to-market angles that bypass capital-intensive forming equipment ownership barriers. For Investors and Strategic Acquirers: Capital is best deployed toward winding equipment specialists with proprietary hair-pin forming intellectual property and established technician training pipelines. Long-term viability favors suppliers with demonstrated 800-volt platform qualification and automotive OEM safety-critical traceability certifications. Monitor copper price volatility inflections and German equipment builder order intake as early signals of margin compression versus capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Welding Equipment Partnership | Fiber laser system vendors achieve tier-one status as continuous welding replaces mechanical crimping in 800-volt architectures. |
| Copper Scrap Recycling Integration | Backward integration into cathode production hedges raw material exposure that rectangular conductor designs amplify. |
| 800-Volt Platform Qualification | Automotive OEM safety-critical traceability requirements elevate qualified suppliers into multi-year framework agreements. |
| Servo Motor Servicing Capability | Industrial automation buyers consolidate procurement into single-source agreements mirroring automotive contracting patterns. |
| Dielectric Oil Thermal Management | EU F-Gas Regulation compliance pressure forces HVAC and compressor redesign toward fluorinated gas alternatives. |
Research Methodology
Operator-level perspectives from winding equipment technicians, tier-one supplier procurement managers, OEM platform engineers, and laser welding system integrators anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings of listed automotive suppliers, MIIT NEV production databases, and EU Green Deal regulatory impact assessments. Customs data on copper rectangular conductor trade flows, equipment builder order backlogs, and automotive platform specification sheets furnished quantitative cross-checks. Bottom-up segment sizing triangulated against top-down powertrain electrification spend forecasts.
Sensitivity analysis tested forecast robustness across copper price scenarios, equipment lead time variations, and NEV subsidy policy discontinuities. Segmentation dimensions modeled include motor type, end-user procurement power, voltage class architecture, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, platform volume commitments, and technology transition elasticity parameters. Analysis window spans powertrain electrification timelines that outpace round-wire motor refresh cycles.
Underlying assumptions cover sustained EU CO2 fleet mandate enforcement, Chinese NEV credit scheme continuity, and copper price band stability, with deviation risk concentrated in winding equipment delivery delays and rare earth supply disruptions. Practitioners should keep alternative scenarios live as MIIT policy restructuring and EPA tailpipe regulation tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
United States DC Motor Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Air Heater Tubes Market
Industrial Motors
US Electric Motor Market
Industrial Motors
Power Scraper Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Power Stacker Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market