
 Gear Reduction Motors Market | 2026-2036
Gear Reduction Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Reduction Motors Market Insights
Chinese gearmotor foundries and machining clusters is realigning capacity toward high-precision helical and planetary configurations for export markets. SEW-EURODRIVE leverages its integrated drive manufacturing footprint across Europe and Asia to sustain premium positioning in modular gearmotor systems. Siemens AG anchors demand through its digital twin-enabled motor-gearbox platforms that merge predictive maintenance with powertrain optimization. Bonfiglioli competes aggressively in agricultural and renewable energy applications with specialized planetary drives engineered for high-torque, low-speed environments.
Gear reduction motors integrate a prime mover with a mechanical speed reducer—typically employing helical, bevel, worm, or planetary gear stages—to deliver controlled torque multiplication at reduced output speeds, with ratios commonly spanning 5:1 to 1000:1 and efficiency ratings governed by IEC 60034 designations. These electromechanical systems serve as the foundational motion elements in conveyor lines, robotic joints, packaging lines, and material handling equipment where precise speed control determines throughput consistency. AC motors dominate installed base volume across heavy manufacturing and process industries due to their durability and straightforward maintenance profiles, while servo motors capture the fastest expansion trajectory in robotics and CNC applications where closed-loop positioning accuracy commands priority. The brushless technology segment commands margin concentration as permanent magnet synchronous designs displace brushed alternatives in cleanroom electronics assembly and aerospace actuation systems.
ISO machinery safety standards, IEC motor efficiency frameworks, and OSHA mechanical power transmission regulations collectively dictate enclosure ratings, thermal performance benchmarks, and lockout-tagout integration requirements that determine market access for gearmotor suppliers. REACH substance restrictions and RoHS material compliance in Europe, alongside China's GB motor efficiency mandates, are forcing redesigns of winding insulation, lubricant formulations, and housing alloys across multinational product portfolios. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional content thresholds that threaten to fragment supply chain economics for globally sourced gearmotor components.
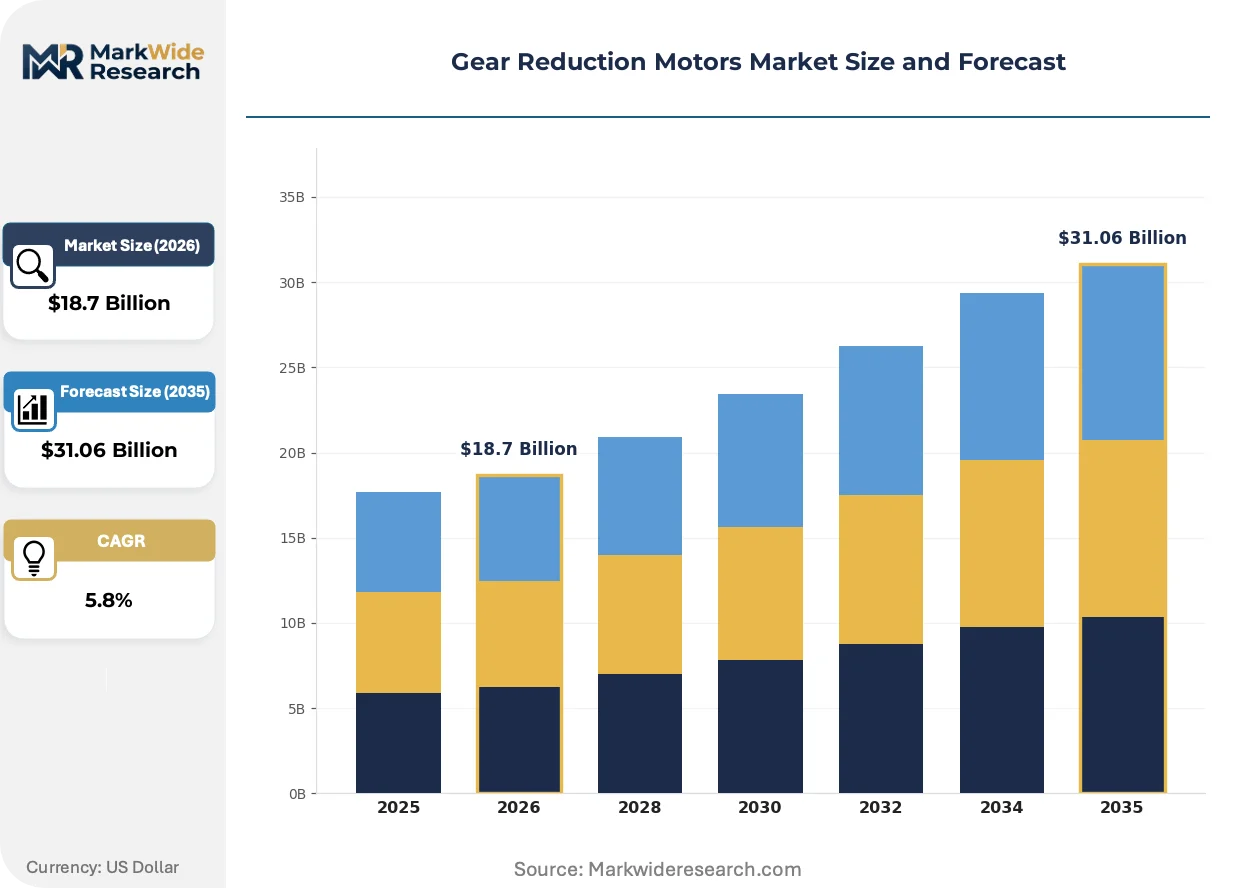
Market Dynamics
Factory automation intensity is compressing gearmotor procurement cycles as OEMs consolidate supplier bases around integrated motion platforms that bundle motors, drives, and precision gearing into single-source contracts.
Growth Catalysts
- Industrial energy efficiency mandates:China's GB 18613-2020 motor efficiency standards and the EU Ecodesign Directive are forcing replacement of legacy IE1 and IE2 gearmotors with IE4-rated permanent magnet systems in process industries.
- Robotics joint density expansion:Collaborative robot manufacturers in Germany and Japan are specifying compact planetary gearheads with sub-arcminute backlash for pick-and-place repeatability in electronics assembly cells.
- Material handling throughput pressure:E-commerce fulfillment centers across the United States are installing high-torque helical-bevel gearmotors on sortation conveyors to sustain parcel velocity during peak seasonal volume surges.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in China's Inner Mongolia and Jiangxi provinces, exposing permanent magnet motor supply chains to export quota volatility and geopolitical friction.
- Specialized machining equipment scarcity:Five-axis CNC gear grinding machines from European and Japanese builders carry 18-24 month lead times, capping expansion capacity for high-precision planetary gearbox manufacturers.
- Copper and steel input cost volatility:Winding copper and housing alloy prices fluctuate with commodity exchange movements, compressing margins on standardized AC gearmotor product lines where pricing is indexed to raw material benchmarks.
Strategic Opportunities
- Renewable energy drivetrain retrofit:Aging wind turbine pitch and yaw systems in Spain and Denmark present replacement demand for corrosion-resistant planetary gearmotors rated for offshore salt spray environments.
- Digital twin integration services:Condition monitoring algorithms fused with vibration sensors on gearmotor bearings enable predictive maintenance contracts that extend equipment life and create recurring revenue streams for motion system integrators.
- Agricultural mechanization acceleration:India's tractor and combine harvester OEMs are localizing planetary final drive production to meet PLI scheme localization thresholds and avoid import duties on fully assembled gearboxes.
Industry Challenges
- Electromechanical systems integration complexity:Servo gearmotor commissioning requires synchronized tuning of encoder feedback loops, drive parameters, and mechanical compliance that exceeds the skill base of traditional maintenance technicians in legacy manufacturing facilities.
- Multi-jurisdictional certification timelines:Simultaneous UL 1004-1, CE marking, and CCC approval processes for new gearmotor platforms extend product launch windows by 8-14 months and fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Reduction Motors Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors Application: Automated Machinery, Robotics, Conveyors, Packing Equipment Technology: Brushless, Brushed, Gearless, Hybrid End User: Manufacturing, Automotive, Aerospace, Electronics |
| Companies Covered | SEW-EURODRIVE, Siemens AG, ABB, Nidec Corporation, Sumitomo Heavy Industries, Regal Rexnord Corporation, Eaton, Bonfiglioli, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Reduction Motors Market Trends and Innovations
Motion control architectures are converging around intelligent edge nodes where gearmotors embed local processing capability, shifting value capture from hardware margins toward software-enabled performance optimization.
Integrated servo-gearbox units with hollow-shaft planetary stages are modularizing machine builder design workflows. Packaging machinery OEMs in Italy and the Netherlands are specifying these plug-and-play assemblies to reduce engineering hours on custom conveyor layouts. This modularization is compressing the traditional three-tier supply chain of motor vendor, gearbox specialist, and system integrator into bilateral direct procurement relationships.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of gear lubricants used in food-grade and cleanroom applications. European gearmotor suppliers are qualifying synthetic ester and polyalphaolefin alternatives to maintain NSF H1 certification for poultry processing and pharmaceutical packaging equipment. The transition is most acute in Germany's dairy machinery sector, where equipment washdown protocols previously relied on PFAS-containing lubricant chemistries.
Aftermarket service unbundling is fragmenting traditional distributor relationships. End-users in Japan's automotive stamping plants are contracting directly with gearmotor manufacturers for spare parts and refurbishment rather than channeling through regional industrial distributors. This disintermediation is most visible in high-volume press line applications where downtime costs exceed $50,000 per hour and response speed trumps distributor relationship continuity.
Gear Reduction Motors Market Segmentation
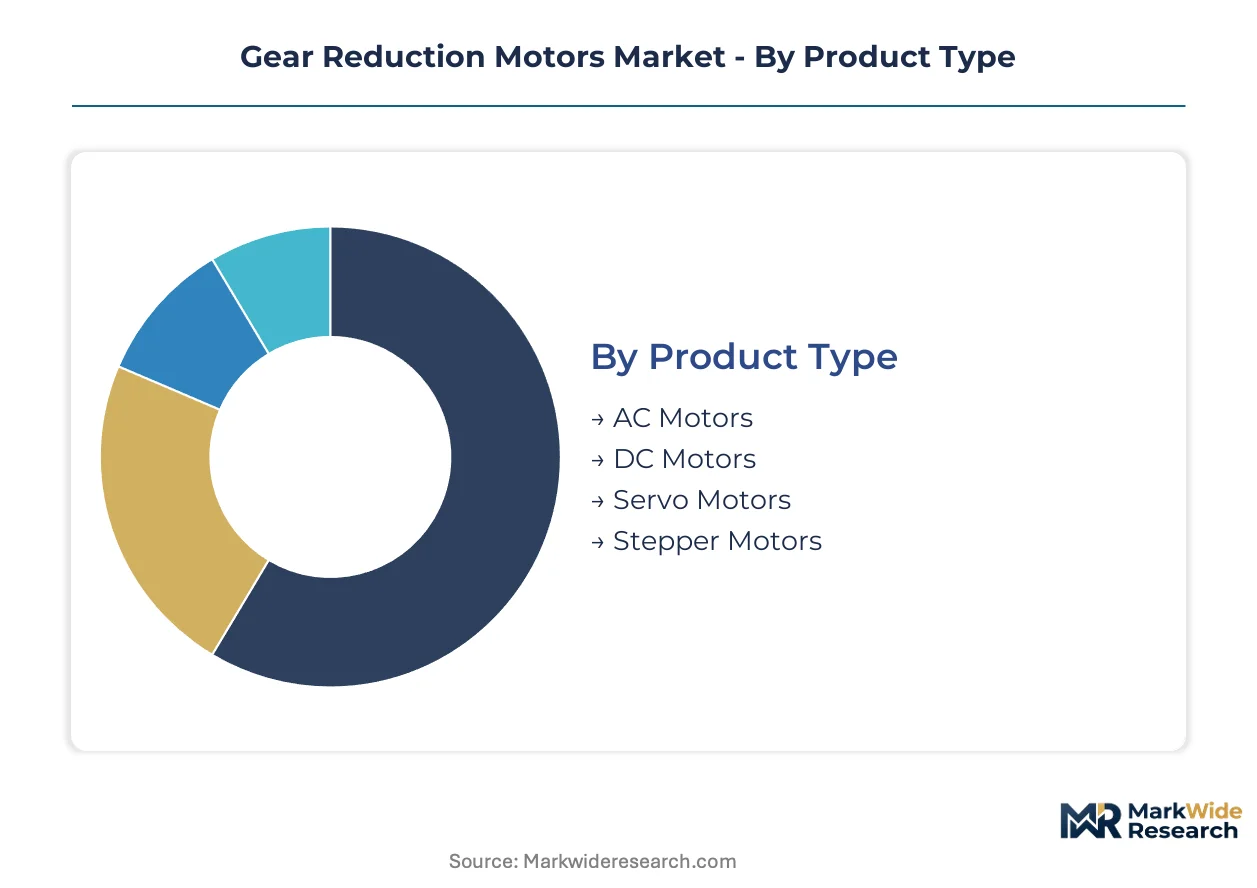
Gear reduction motors serve heterogeneous buyer requirements across precision levels, duty cycles, and integration complexity. Segmentation reveals how procurement specifications diverge between cost-sensitive volume buyers and performance-driven precision engineers.
Product Type:
Buyers differentiate primarily by control architecture needs and maintenance infrastructure maturity.
- AC Motors:Induction-based designs with squirrel-cage rotors deliver rugged torque multiplication across continuous-duty conveyor applications. Foundries in Germany's Ruhr region specify these for blast furnace material handling where ambient contamination tolerances exceed servo-grade sensitivity.
- Servo Motors:Closed-loop permanent magnet synchronous systems achieve sub-arcminute positioning accuracy through encoder feedback integration. Collaborative robot manufacturers in Japan's Kansai industrial corridor demand compact frame sizes with integrated planetary gearheads for electronics assembly repeatability.
- DC Motors:Brushed and brushless variants persist in battery-powered mobile equipment and legacy traction applications where AC infrastructure is absent.
- Stepper Motors:Open-loop positioning systems with detent torque characteristics suit low-cost indexing tables and laboratory automation where absolute accuracy is secondary to cost minimization.
AC motors lead volumes today; servo motors are gaining share fastest.
Application:
Motion control requirements vary sharply by throughput velocity and positioning precision demands.
- Automated Machinery:General-purpose gearmotors power indexing tables, rotary actuators, and linear positioning stages across discrete manufacturing. Machine tool builders in Italy's Emilia-Romagna cluster specify helical-bevel configurations for chip conveyor reliability under coolant exposure.
- Robotics:Articulated joint drives require zero-backlash harmonic or planetary gearheads with hollow-shaft architectures for cable routing. Six-axis robot OEMs in Shanghai's Songjiang district source compact integrated units to minimize arm inertia.
- Conveyors:Bulk material handling and parcel sortation systems prioritize torque density and thermal reserve over positional accuracy.
- Packing Equipment:Intermittent-motion machinery demands rapid acceleration profiles with controlled stopping precision for product registration.
Conveyors anchor installed base volume; robotics exhibits the steepest expansion trajectory.
Technology:
Commutation method and mechanical integration level determine lifecycle cost and application suitability.
- Brushless:Electronic commutation eliminates brush wear and sparking, enabling sealed enclosures for food-grade and explosive atmosphere certifications. Dairy processing equipment manufacturers in Denmark specify IP69K-rated washdown variants for CIP/SIP compliance.
- Brushed:Mechanical commutation persists in cost-constrained applications and legacy maintenance environments where controller simplicity outweighs efficiency penalties.
- Gearless:Direct-drive torque motors eliminate backlash and mechanical wear for semiconductor wafer handling and telescope azimuth positioning.
- Hybrid:Combined stepper-servo architectures merge open-loop economy with closed-loop reliability for mid-precision automation.
Brushless configurations dominate new specification activity; gearless designs expand most quickly in precision segments.
End User:
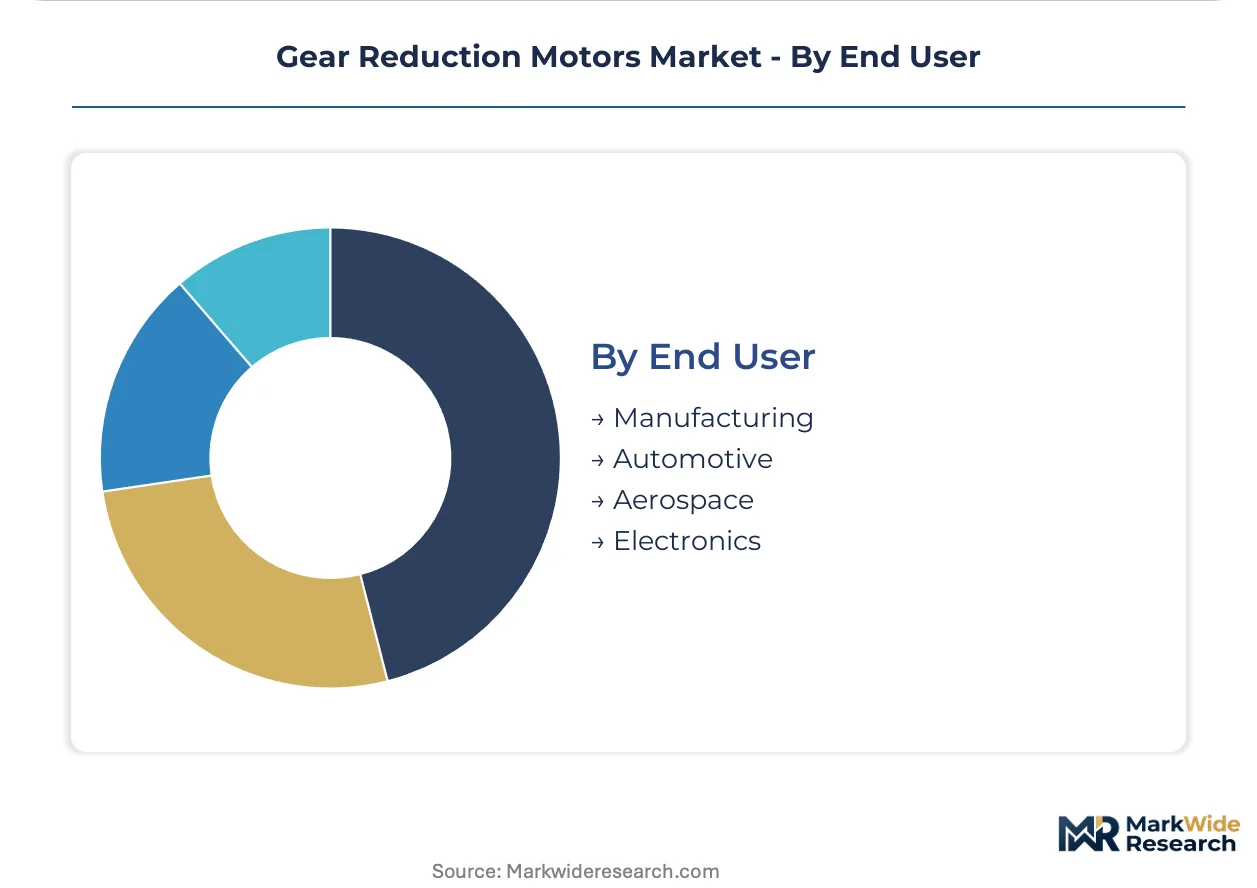
Industry-specific certification requirements and duty cycle profiles shape procurement priorities.
- Manufacturing:General industrial automation spans metal forming, plastics processing, and assembly systems with broad efficiency and reliability requirements. Automotive stamping plants in Michigan's Detroit-Warren corridor specify high-torque helical units for press feed mechanisms.
- Automotive:Powertrain assembly and body-in-white applications demand synchronized multi-axis motion with safety-rated torque limiting.
- Aerospace:Flight control actuation and fuel system positioning require DO-160 environmental qualification and extended temperature operation.
- Electronics:Cleanroom-compatible designs with low particulate generation serve semiconductor wafer transport and display panel assembly.
Manufacturing absorbs the highest absolute volumes; aerospace commands the strongest pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering heritage contrasts with China's scale-driven manufacturing expansion in gear reduction motor deployment. Both markets command substantial order volumes, yet procurement specifications diverge sharply between European efficiency mandates and Asian cost-optimization priorities.
China
GB 18613-2020 motor efficiency standards are accelerating IE4-rated permanent magnet system adoption across Jiangsu and Zhejiang province foundries. MIIT industrial upgrading programs subsidize high-precision helical and planetary gearmotor retooling for export markets. Suzhou's machining clusters are expanding five-axis gear grinding capacity to serve German and Japanese OEM supply chains.
Germany
EU Ecodesign Directive enforcement is phasing out IE1 and IE2 gearmotors in Ruhr region process industries by 2027. REACH substance restrictions are forcing lubricant reformulation for food-grade applications in Bavaria's dairy machinery sector. Stuttgart's automotive stamping plants are specifying safety-rated torque-limiting helical units for press feed mechanisms.
United States
OSHA mechanical power transmission regulations are tightening lockout-tagout integration requirements for conveyor installations in Michigan's Detroit-Warren automotive corridor. IRA clean energy manufacturing credits are incentivizing domestic gearmotor assembly for wind turbine drivetrain retrofits. E-commerce fulfillment centers across Ohio and Pennsylvania are deploying high-torque helical-bevel configurations for parcel sortation velocity.
Japan
METI energy efficiency roadmaps are targeting IE5 motor penetration in Kansai industrial corridor collaborative robot manufacturing. JIS standards for zero-backlash planetary gearheads are shaping electronics assembly cell specifications. Osaka's robot OEMs are sourcing compact integrated servo-gearbox units to minimize six-axis arm inertia.
India
PLI scheme localization thresholds are driving planetary final drive production shifts to Maharashtra and Gujarat tractor OEMs. BIS motor efficiency mandates are tightening procurement specifications for combine harvester drivetrains. Pune's agricultural machinery clusters are qualifying domestic suppliers to avoid import duties on fully assembled gearboxes.
Gear Reduction Motors Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold precision positioning segments. The vendor base stratifies across three tiers: integrated motion platform suppliers bundling motors, drives, and gearing; standalone gearbox specialists serving retrofit markets; and regional fabricators competing on delivery speed for standardized AC configurations. Strategic archetypes include efficiency-certification leaders, hollow-shaft modularization specialists, and rare-earth magnet supply chain integrators. Dominant competitive moves center on digital twin service unbundling and five-axis machining capacity expansion.
Within the integrated platform tier, SEW-EURODRIVE and Siemens AG exemplify full-stack motion system providers. SEW-EURODRIVE represents the modular gearmotor archetype with European-Asian manufacturing footprints, while Siemens AG anchors digital twin-enabled motor-gearbox platform development. Sumitomo Heavy Industries occupies a position among precision planetary specialists serving robotics and CNC applications. These three names illustrate how competitive positioning splits between bundled system integration and component-level precision engineering.
| Leading Market Players |
|---|
| SEW-EURODRIVE |
| Siemens AG |
| ABB |
| Nidec Corporation |
| Sumitomo Heavy Industries |
| Regal Rexnord Corporation |
| Eaton |
| Bonfiglioli |
| Emerson Electric |
| Others |
Pricing and Supply Chain Analysis
Copper futures on the London Metal Exchange cascade through gearmotor bill-of-materials into three distinct pricing tiers that separate IE4 permanent magnet systems from legacy IE2 induction units and economy-grade brushed DC alternatives. This commodity transmission mechanism concentrates margin pressure on standardized AC configurations where OEM procurement teams index contract pricing to raw material benchmarks.
Pricing Analysis
Distributor markups of 18-25% separate regional industrial supply houses from direct-to-OEM volume contracts that bypass channel intermediaries entirely. Three-tier pricing structure across premium, standard, and economy levels reflects IEC efficiency certification tiers, with IE4-rated permanent magnet systems commanding 40-60% premiums over IE2 induction alternatives. Pricing pressure stems from rare earth magnet cost volatility and five-axis machining capacity scarcity that extends precision planetary gearbox lead times. Cost-sensitive volume buyers in India's agricultural machinery sector exhibit highest price elasticity, while German automotive stamping plants prioritize torque density and safety certification over unit economics.
Supply Chain Analysis
Skilled gear grinding technician shortages in Germany's Baden-Württemberg region and Suzhou's machining clusters constrain expansion capacity for sub-arcminute backlash planetary systems. Manufacturing gravity centers on China for winding copper and housing castings, Germany for precision-cut helical gears, and Japan for compact servo-gearbox integration. Neodymium and dysprosium processing draws from China's Inner Mongolia and Jiangxi provinces, creating single-source vulnerability for permanent magnet motor supply chains. Distribution runs through authorized distributor networks for aftermarket service, with direct OEM procurement gaining share in high-volume automated machinery installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as factory automation intensity shifts procurement specifications toward IE4 efficiency tiers and predictive maintenance integration. The demand pivot toward premium specifications rewards suppliers with digital twin capabilities and five-axis machining assets.
For Market Incumbents: Deepen backward integration into rare earth magnet supply chains through offtake agreements with Chinese processors to mitigate export quota volatility. Expand five-axis CNC gear grinding capacity in European manufacturing footprints to capture premium positioning in robotics joint density expansion. Certification investment in IEC 60034 IE5 pre-standards development represents the priority lever against emerging servo-motor specialists from Japan's Kansai corridor. For New Entrants and Emerging Players: System integrators serving India's PLI scheme agricultural machinery localization present the most penetrable channel partner type for planetary final drive market entry. Target Maharashtra and Gujarat tractor OEM clusters with domestically assembled helical-bevel configurations that qualify for import duty avoidance. White-space exists in corrosion-resistant offshore wind turbine retrofit applications where incumbent lead times exceed 18 months. For Investors and Strategic Acquirers: Consolidation pressure builds where five-axis machining capacity scarcity intersects with digital twin software competency gaps among mid-tier gearbox specialists. Long-term viability over the coming decade favors platform suppliers bundling motion control hardware with predictive maintenance service contracts. Acquisition target archetype: precision planetary specialists with JIS-certified zero-backlash designs and established relationships with collaborative robot OEMs. Watch rare earth export license issuance patterns from China's Ministry of Commerce as inflection indicator for permanent magnet motor supply chain economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures neodymium processing capacity against Chinese export quota volatility. |
| Five-Axis CNC Gear Grinding Capacity Expansion | Captures premium positioning in robotics sub-arcminute backlash specifications. |
| Digital Twin Platform Development | Enables predictive maintenance contracts extending equipment lifecycle revenue. |
| IE5 Efficiency Pre-Standard Certification Investment | Establishes technical leadership ahead of EU Ecodesign Directive phase-outs. |
| Regional Manufacturing Footprint Localization | Qualifies for India's PLI scheme thresholds and avoids import duty exposure. |
Research Methodology
Bottom-up automated machinery and robotics demand modeling reconciled against top-down motor-gearbox production capacity tracking forms the analytical core of this study. Primary interviews with maintenance directors at automotive stamping plants, OEM procurement teams in packaging machinery, aftermarket service heads at industrial distributors, and plant engineers in e-commerce fulfillment centers combined with secondary validation from IEC 60034 efficiency filings, EU Ecodesign Directive implementation reports, SEC 10-K disclosures from listed motion control suppliers, and customs trade data on gearmotor component flows. Triangulation across these sources ensures demand-side consumption patterns align with supply-side manufacturing output.
Input-output matrices map copper and steel commodity price movements through winding and housing cost structures into finished gearmotor pricing tiers across the projection horizon. Segmentation dimensions modeled include motor control architecture, mechanical gear stage configuration, efficiency certification tier, end-use application intensity, and regional regulatory framework. CAGRs derive from installed base replacement cycles, automation capital expenditure trajectories, and efficiency mandate compliance deadlines. Industry-specific forecast inputs incorporate five-axis machining capacity expansion timelines and rare earth magnet supply quota allocations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical friction in rare earth supply chains, carbon border adjustment mechanism implementation timing, and robotics joint density expansion rates in electronics assembly. Forecasts reflect assumptions regarding GB 18613-2020 enforcement consistency, REACH substance restriction phase-in schedules, and IRA clean energy manufacturing credit durability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
US Electric Motor Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Smart Motors Market
Industrial Motors
Power Stacker Market
Industrial Motors
Europe Induction Motor Market