
 Global Sliding Vane Air Motor Market | 2026-2036
Global Sliding Vane Air Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sliding Vane Air Motor Market Intelligence
Buyer concentration across European automotive OEMs and North American food processing units is rebalancing toward mid-sized engineering workshops seeking standardized pneumatic solutions. Ingersoll Rand leverages its channel density across industrial distribution to sustain replacement part revenue. Atlas Copco AB anchors its position through captive compressor-to-motor system integration. Parker Hannifin Corporation competes on hydraulic-pneumatic crossover expertise in material handling applications.
Sliding vane air motors convert compressed air energy into rotary mechanical motion through eccentrically mounted rotors with sliding vanes that seal against a cylindrical chamber wall, achieving torque outputs from fractional horsepower to several kilowatts with inherent overload protection and spark-free operation. High torque motor variants dominate installed base value given their replacement frequency in heavy-duty material handling and packaging equipment cycles. Compact motor demand is accelerating fastest among aerospace assemblers where space-constrained tooling requires reduced envelope dimensions without sacrificing stall torque characteristics.
OSHA ventilation standards and EPA compressed air efficiency guidelines in the United States shape product certification requirements, while REACH and CE marking obligations in Europe govern material composition of vane seal compounds. China's GB standards for pneumatic machinery and MIIT energy efficiency classifications for factory air systems create divergent compliance pathways for multinational suppliers. Stakeholders must monitor evolving national energy intensity benchmarks that increasingly embed pneumatic system performance into facility-wide carbon accounting frameworks.
Market Dynamics
EU F-Gas Regulation phase-down schedules and industrial decarbonization mandates in Germany and France are compressing substitution timelines toward compressed air systems with lower lifecycle emissions, forcing incumbent suppliers to recertify product portfolios.
Growth Catalysts
- Food Processing Hygiene Requirements:Washdown-rated pneumatic drive systems replace sealed electric motors in meatpacking and dairy facilities where moisture ingress destroys conventional motor windings.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants and blowing agents accelerates factory-level audits of compressed air leakage, creating replacement demand for efficient vane motor architectures.
- Aerospace Tooling Miniaturization:Space-constrained assembly jigs in Wichita and Toulouse require compact motor variants delivering stall torque without envelope expansion.
Market Restraints
- Compressed Air Energy Penalty:Pneumatic system efficiency losses of 80-90% from compressor to point-of-use create lifecycle cost disadvantages versus direct-drive electric alternatives in continuous-duty applications.
- Vane Seal Material Concentration:Fluoropolymer and advanced composite seal production concentrates among German and Japanese specialty chemical suppliers, exposing motor assemblers to input cost volatility.
- Electric Servo Encroachment:Brushless DC motors with integrated drives displace air motors in precision indexing applications where positional accuracy requirements exceed pneumatic capabilities.
Strategic Opportunities
- India Manufacturing Expansion:PLI scheme incentives for food processing and packaging machinery create first-mover positioning for pneumatic system suppliers establishing local assembly.
- Carbon Accounting Integration:EU CSRD disclosure requirements embed pneumatic system efficiency into facility-wide Scope 1 and 2 reporting, favoring suppliers with verified lifecycle data.
- IIoT Convergence:Embedded pressure and vibration sensors combined with edge analytics enable predictive vane wear monitoring, opening subscription-based maintenance revenue streams.
Industry Challenges
- Pneumatic System Sizing Expertise:Declining in-house compressed air engineering capability among mid-sized OEMs extends sales cycles and increases specification error rates.
- Multi-Jurisdictional Certification:Simultaneous OSHA, CE marking, and China GB standard compliance extends product development timelines and fragments testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sliding Vane Air Motor Market |
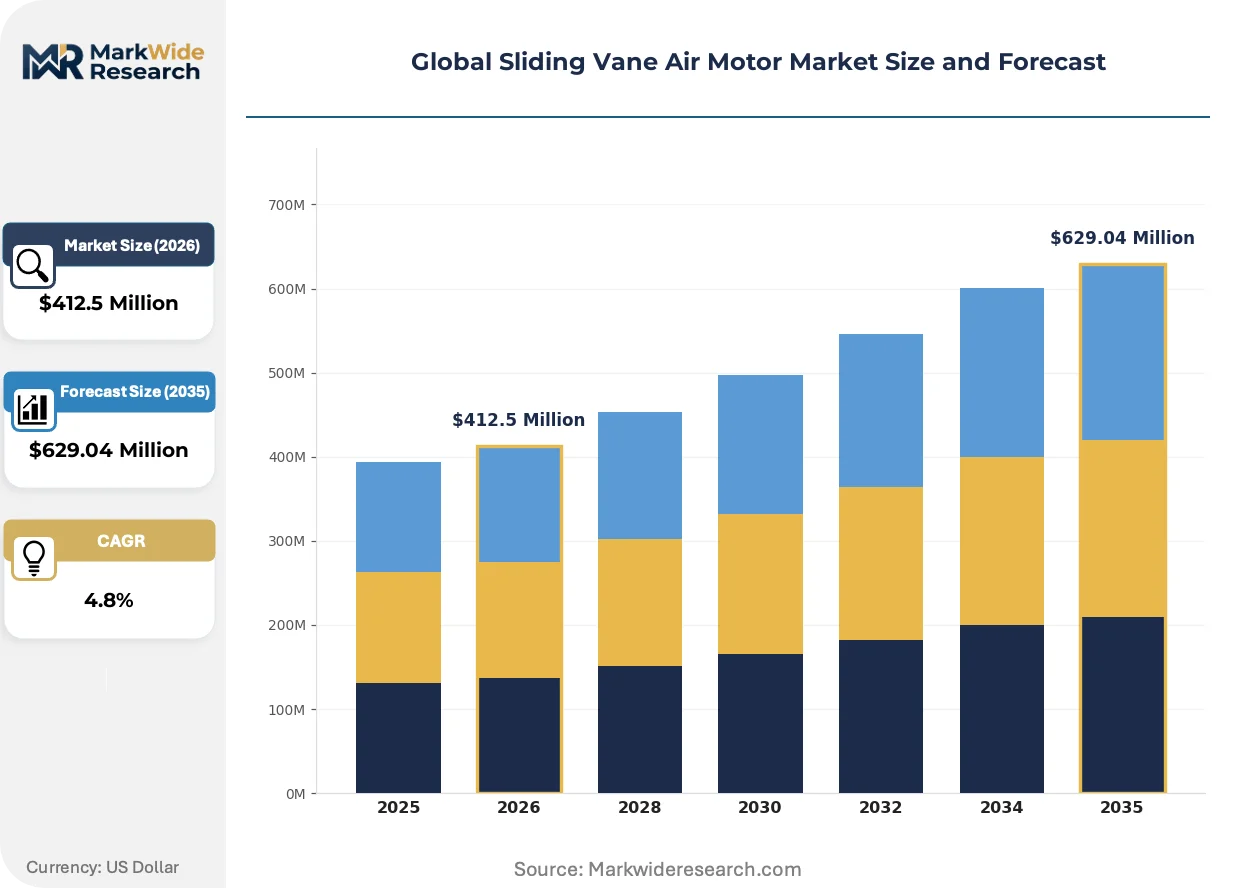
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Vane Motor, High Torque Motor, Low Speed Motor, Compact Motor, Variable Speed Motor Technology: Rotary Vane, Dual Vane, Multi-Vane, Balanced Vane, Unbalanced Vane Application: Material Handling, Packaging Equipment, Textile Machinery, Printing Machines, Pneumatic Tools End User: Manufacturing Plants, Engineering Workshops, Automotive OEMs, Aerospace Assemblers, Food Processing Units |
| Companies Covered | Ingersoll Rand, Globe Airmotors, Atlas Copco AB, Ferry Produits, Sommer-Technik GmbH, Parker Hannifin Corporation, Bibus AG, Sanei Co. Ltd., Deprag Schulz GmbH u. Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sliding Vane Air Motor Market Strategic Shifts & Innovations
Sliding vane air motor architectures are undergoing material and intelligence upgrades that compress maintenance intervals while expanding addressable applications beyond traditional pneumatic strongholds.
Carbon-fiber-reinforced vane composites are electrifying torque-to-weight ratios in portable assembly tools. Aerospace maintenance crews in Hamburg and Seattle adopt these variants for wing fastener installation where tool mass directly constrains operator fatigue. The technology is electrifying competitive positioning in ergonomic tooling segments previously ceded to electric alternatives.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of vane seal compounds across European supply chains. Compounders in the Netherlands and Belgium accelerate bio-based elastomer development to maintain CE marking eligibility. Food packaging OEMs in Italy and Spain face the steepest compliance timelines given direct food contact proximity.
Compressed air-as-a-utility contracting models are displacing capital purchase patterns among North American automotive tier suppliers. Tier 2 stamping and subassembly plants in Michigan and Ohio lease pneumatic capacity by the cubic meter rather than owning compressor assets. This shift concentrates specification authority with energy service companies and compresses motor replacement decisions into bundled maintenance schedules.
Global Sliding Vane Air Motor Market Segmentation
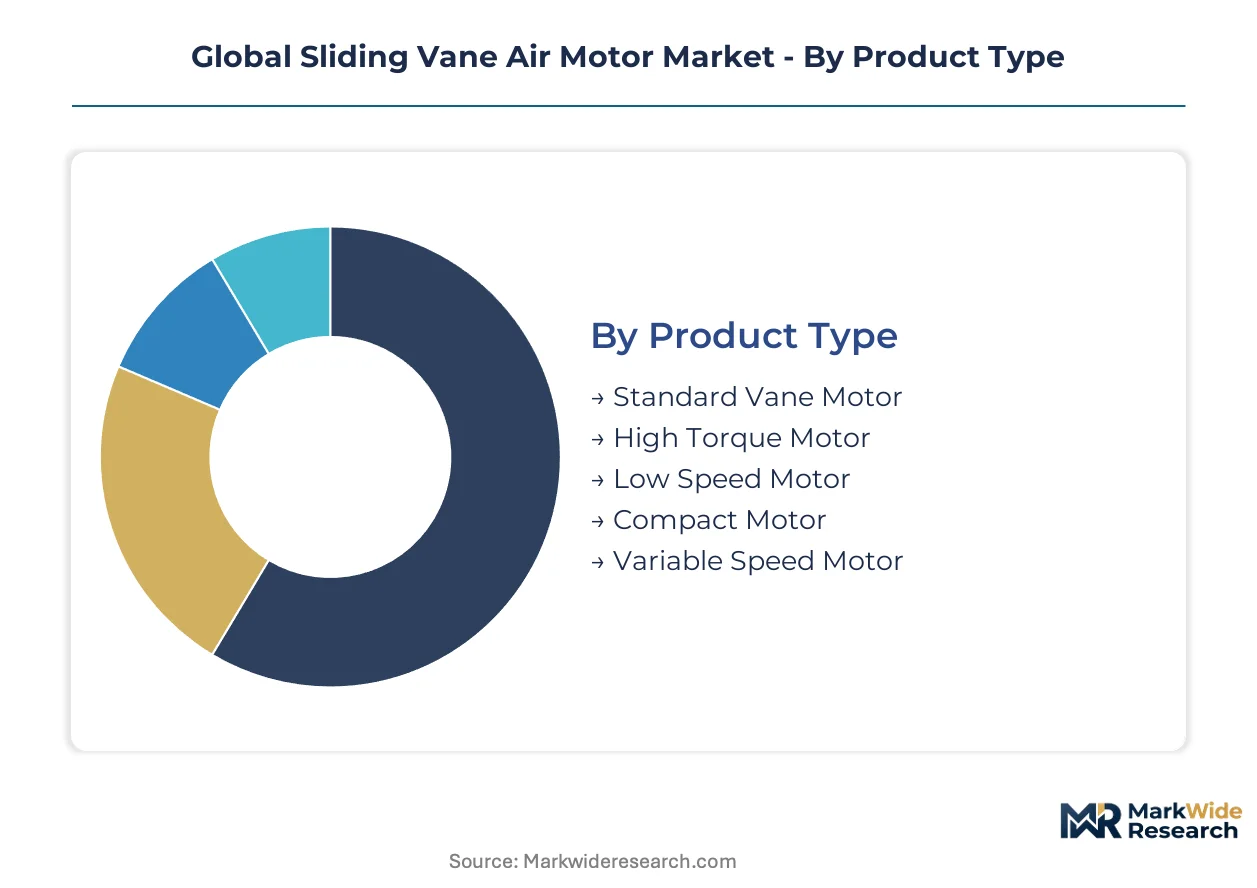
Segmentation in sliding vane air motors reveals how capital allocation, torque requirements, and regulatory exposure fragment demand across equipment classes. Understanding these divisions exposes where specification authority concentrates and where supplier margins diverge.
Product Type:
Capital intensity varies sharply across motor architectures, with high-torque variants demanding precision machining and specialized alloy castings that compress supplier working capital cycles.
- High Torque Motor:These units deploy eccentric rotors with enlarged vane contact surfaces to deliver stall torque exceeding 50 Nm without gearbox augmentation. Demand clusters in German automotive stamping plants and heavy packaging lines where overload protection eliminates mechanical clutching. Replacement cycles run shorter than compact alternatives due to continuous-duty wear patterns.
- Compact Motor:Reduced envelope dimensions sacrifice peak torque for space-constrained integration, achieving power densities above 0.5 kW/kg through aluminum housing extrusions and carbon-fiber vane composites. Wichita and Toulouse aerospace assemblers specify these for wing fastener tooling where operator fatigue limits tool mass.
- Standard Vane Motor:General-purpose architectures dominate replacement part revenue across mid-sized engineering workshops in the United States and China.
- Low Speed Motor:Direct-drive configurations eliminate gearbox maintenance in textile winding applications across Italian and Spanish mills.
- Variable Speed Motor:Integrated flow regulators enable torque modulation for precision indexing in printing press registration systems.
Most installed capacity flows through Standard Vane Motor architectures. Expansion is steepest in Compact Motor configurations.
Technology:
Technical differentiation centers on vane quantity and rotor balance geometry, with multi-vane architectures commanding premium positioning in continuous-duty applications.
- Rotary Vane:The foundational single-rotor design with 3-6 sliding vanes maintains lowest unit cost through standardized casting patterns and universal seal kits. Chinese packaging OEMs in Zhejiang and Guangdong provinces default to this architecture for cost-sensitive export equipment.
- Multi-Vane:Eight or more vanes distribute sealing contact across narrower arc segments, reducing individual vane loading and extending maintenance intervals by 40-60% in 24-hour textile operations. The added precision machining of rotor slots elevates capital requirements for motor assemblers.
- Dual Vane:Tandem rotor arrangements isolate exhaust stages for cleaner operation in food contact zones.
- Balanced Vane:Symmetrical pressure loading eliminates bearing side-thrust in high-speed printing applications.
- Unbalanced Vane:Simplified geometry accepts higher vibration levels in portable pneumatic tools.
Volume concentrates in Rotary Vane systems. Technology premiums are climbing fastest in Multi-Vane configurations.
Application:
Application segmentation tracks torque precision requirements against contamination exposure, with material handling tolerating wider performance variance than packaging registration systems.
- Material Handling:Conveyor drives and hoist mechanisms prioritize stall torque reliability over positional accuracy, accepting pneumatic inefficiency in exchange for spark-free operation in explosive atmospheres. German chemical processors and US grain elevator operators specify these for ATEX Zone 22 compliance.
- Packaging Equipment:Cartoning and capping stations demand repeatable indexing within ±0.5 degrees, driving specification of low-backlash vane motors with hardened steel rotors. Italian and Spanish food packaging OEMs face compressed timelines for REACH-compliant seal conversion.
- Textile Machinery:Yarn tensioning and winding applications favor low-speed direct drive to eliminate gearbox maintenance.
- Printing Machines:Registration control requires minimal hysteresis between pressure signal and shaft response.
- Pneumatic Tools:Handheld assembly tools prioritize power-to-weight ratios in ergonomic specifications.
Specification authority in Material Handling rests with facility maintenance departments. Packaging Equipment applications are gaining specification influence fastest as OEMs consolidate pneumatic system design.
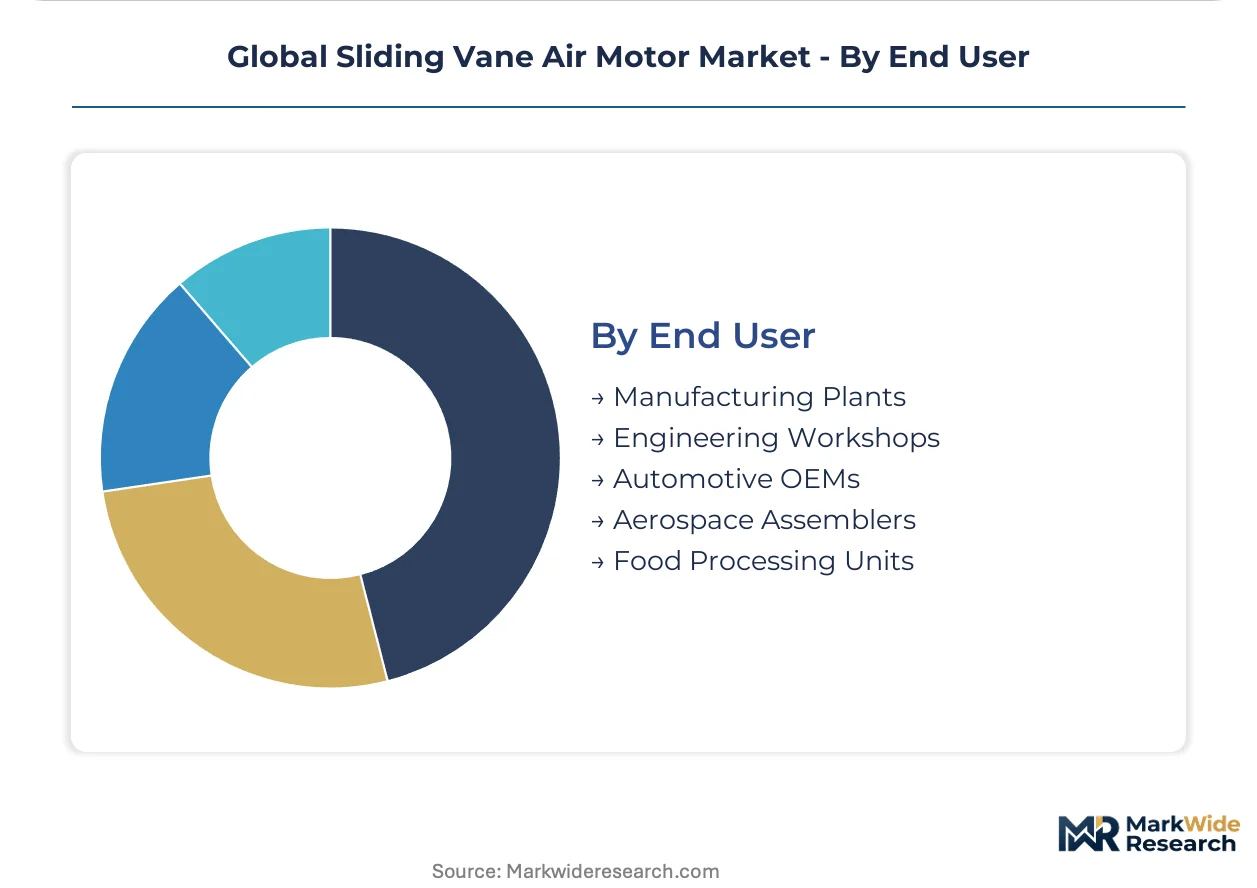
End User:
End user segmentation exposes divergent procurement sophistication, with automotive OEMs demanding lifecycle cost documentation against engineering workshops prioritizing immediate availability.
- Automotive OEMs:Stamping and body-in-white operations specify motors with verified MTBF data and predictive maintenance compatibility, bundling procurement into multi-year compressor service contracts. Michigan and Ohio tier suppliers increasingly lease pneumatic capacity rather than owning assets.
- Food Processing Units:USDA and FDA washdown requirements mandate 316 stainless housings and FDA-compliant vane materials, with replacement decisions triggered by seal degradation rather than mechanical failure. Meatpacking facilities in Nebraska and dairy processors in Wisconsin drive specification of IP69K-rated architectures.
- Manufacturing Plants:General industrial users balance first cost against local distributor stocking levels.
- Engineering Workshops:Job shops prioritize universal motor interchangeability across mixed equipment fleets.
- Aerospace Assemblers:FAA-traceable material certification elevates procurement documentation requirements.
Procurement consolidation is most advanced among Automotive OEMs. Food Processing Units are expanding specification fastest as hygiene regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compressed air engineering expertise anchors European demand, while Chinese manufacturing scale and US automation density shape volume distribution across three distinct regulatory environments.
United States
Automotive tier suppliers in Michigan and Ohio drive specification of washdown-rated pneumatic systems for stamping operations. OSHA ventilation standards and EPA compressed air efficiency guidelines govern product certification requirements for motor assemblers. Wichita aerospace clusters demand compact motor variants for wing fastener tooling where operator fatigue constrains equipment mass.
Germany
Automotive stamping plants and chemical processors prioritize high-torque architectures with ATEX compliance for explosive atmospheres. EU F-Gas Regulation phase-down schedules compress substitution timelines toward compressed air systems with lower lifecycle emissions. Hamburg maintenance crews adopt carbon-fiber vane composites for portable assembly tools in aerospace applications.
China
Packaging OEMs in Zhejiang and Guangdong provinces default to cost-sensitive rotary vane architectures for export equipment. MIIT energy efficiency classifications for factory air systems create compliance pathways distinct from Western standards. Yangtze River Delta manufacturing hubs concentrate demand for standardized pneumatic solutions amid automation upgrade cycles.
France
Industrial decarbonization mandates accelerate factory-level audits of compressed air leakage and system efficiency. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of vane seal compounds across domestic supply chains. Toulouse aerospace assemblers specify compact motors for space-constrained assembly jigs on narrow-body production lines.
India
PLI scheme incentives for food processing and packaging machinery create positioning opportunities for pneumatic system suppliers establishing local assembly. BIS standards for pneumatic machinery govern product compliance alongside state-level industrial policies. Maharashtra and Gujarat industrial corridors concentrate procurement from engineering workshops upgrading mixed equipment fleets.
Global Sliding Vane Air Motor Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a moderately consolidated structure where specification authority increasingly concentrates with energy service companies and compressed air system integrators. Tiered competition separates full-line pneumatic houses with captive compressor portfolios from component specialists serving replacement part channels. Two strategic archetypes dominate: integrated system suppliers bundling motor-to-compressor solutions, and precision machining houses optimizing vane-to-chamber tolerances for continuous-duty applications. Geographic expansion through distribution partnerships and portfolio diversification into condition-monitoring hardware represent the dominant competitive moves.
Among diversified industrial conglomerates, Ingersoll Rand and Atlas Copco AB occupy positions anchored by channel density and system integration capabilities respectively. Parker Hannifin Corporation exemplifies the hydraulic-pneumatic crossover specialist archetype. These three names represent the competitive core against which mid-sized European fabricators and emerging Asian suppliers position differentiated vane materials or regional service density.
| Leading Market Players |
|---|
| Ingersoll Rand |
| Globe Airmotors |
| Atlas Copco AB |
| Ferry Produits |
| Sommer-Technik GmbH |
| Parker Hannifin Corporation |
| Bibus AG |
| Sanei Co. Ltd. |
| Deprag Schulz GmbH u. Co. |
| Others |
Cost & Logistics Intelligence
Carbon-fiber vane composite adoption in aerospace tooling simultaneously elevates material costs and concentrates precision machining capacity among German and Japanese specialty suppliers, compressing margin structures for mid-tier motor assemblers while rewarding integrated players with captive compound development.
Pricing Analysis
Bundled compressor-to-motor service contracts dominate enterprise procurement, while unbundled component sales persist in aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified high-torque units from general-purpose rotary vane architectures. Pricing pressure stems from electric servo encroachment in precision indexing applications. Engineering workshops exhibit highest price sensitivity, while automotive OEMs prioritize lifecycle cost documentation over unit economics.
Supply Chain Analysis
Workforce availability constraints in precision grinding and rotor slot machining concentrate production capacity in Germany, Japan, and China. Fluoropolymer seal compounds and carbon-fiber vane prepregs draw from German and Japanese specialty chemical suppliers. Single-source vulnerability in REACH-compliant bio-based elastomer development elevates reformulation risk. Distribution runs through industrial distribution networks anchored by captive compressor portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU F-Gas Regulation compliance costs in Germany and France exceed India's PLI scheme incentive offsets, creating margin expansion opportunities for suppliers establishing local assembly in Maharashtra and Gujarat industrial corridors.
For Market Incumbents: Deploy predictive maintenance platform integration to counter electric servo displacement in precision indexing applications. Backward integration into carbon-fiber vane composite production secures supply continuity against Japanese specialty chemical concentration. Channel density reinforcement in North American food processing corridors sustains replacement part revenue against emerging Asian competitors.
For New Entrants and Emerging Players: Mid-sized engineering workshops in India's BIS compliance transition represent the most penetrable buyer archetype. White-space exists in REACH-compliant seal compound supply to Italian and Spanish food packaging OEMs facing compressed compliance timelines. Local assembly partnerships with Maharashtra industrial corridor distributors accelerate market entry without capital-intensive machining capacity.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision machining houses with multi-vane rotor expertise but limited aftermarket service infrastructure. Long-term viability hinges on IIoT convergence capabilities across the projection horizon. Acquisition targets should demonstrate verified lifecycle emissions data for EU CSRD disclosure alignment. Monitor MIIT energy efficiency classification updates as inflection indicators for Chinese manufacturing automation upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vane Composite Production | German and Japanese chemical supplier concentration creates input cost volatility for motor assemblers without captive material sources. |
| IIoT Predictive Maintenance Platform Launch | Embedded pressure and vibration sensors enable subscription revenue streams from aerospace maintenance crews in Hamburg and Seattle. |
| Local Assembly Establishment in India | PLI scheme incentives for food processing machinery create first-mover positioning in Maharashtra and Gujarat industrial corridors. |
| REACH-Compliant Seal Compound Reformulation | Netherlands and Belgium compounders accelerate bio-based elastomer development to maintain CE marking eligibility for European supply chains. |
| Compressed Air-as-a-Utility Partnership | Michigan and Ohio tier suppliers increasingly lease pneumatic capacity, concentrating specification authority with energy service companies. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with maintenance directors at automotive stamping plants, OEM procurement teams in packaging equipment, and aftermarket service heads with secondary validation against customs data, SEC filings from diversified industrial conglomerates, and MIIT energy efficiency classifications. Plant engineers in Wichita and Toulouse aerospace clusters provided application-specific demand parameters.
Historical trendline analysis of installed base replacement cycles and automation upgrade expenditures informed projection frameworks across motor architecture, vane technology, application torque requirements, and end-user procurement sophistication dimensions. CAGRs derive from segmented demand elasticity modeling and regulatory phase-down schedule impacts. Forecast inputs incorporate EU F-Gas Regulation substitution timelines and PLI scheme incentive disbursement patterns.
Underlying measurement precision varies by segment; high-torque motor replacement frequency data carries tighter precision than emerging compact aerospace applications. Forecasts embed assumptions regarding REACH Annex XVII enforcement consistency and carbon accounting integration velocity. Practitioners should monitor EPA compressed air efficiency guideline updates and China GB standard harmonization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Industrial Motor Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Power Stacker Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Germany AC Motor Market
Industrial Motors
Air Heater Tubes Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Europe Induction Motor Market