
 North America Hazardous Location Motors Market | 2026-2036
North America Hazardous Location Motors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hazardous Location Motors Market Analytics
UL 674 certification for explosion-proof electric motors is collapsing the supplier base as retesting costs and documentation burdens eliminate smaller manufacturers. Rockwell Automation sustains market presence through integrated safety architectures that bundle motors with variable frequency drives. ABB Ltd dominates medium-voltage hazardous duty designs through captive manufacturing in North Carolina and Mexico. Nidec Motor Corporation leverages fractional horsepower specialization to anchor aftermarket channels across Texas and Oklahoma petrochemical corridors.
Hazardous location motors are purpose-built rotating electrical machines engineered with sealed enclosures, flame paths, and temperature-limiting designs to prevent ignition of flammable gases, vapors, or combustible dusts in classified environments; they typically operate within Class I Division 1 or Class II Division 1 ratings with T-code temperature classifications from T2A to T6. Explosion-proof motors occupy the largest revenue pool due to oil and gas infrastructure age, while dust-ignition proof designs represent the fastest structural expansion as grain handling and wood processing facilities face NFPA 654 compliance deadlines. Mining applications remain mature with predictable replacement cadences, whereas pharmaceutical manufacturing commands premium pricing through stainless steel washdown requirements and FDA-validated documentation.
OSHA's enforcement of 29 CFR 1910.307 for hazardous classified locations and EPA methane emissions rules under the Clean Air Act shape product specifications and procurement timelines across upstream and midstream operations. CSA C22.2 No. 145 certification in Canada creates a dual-compliance burden for manufacturers serving cross-border energy corridors. Stakeholders must monitor NEMA's ongoing harmonization with IECEx standards and decide whether to absorb redundant certification costs or cede share to regionally focused competitors.
Market Dynamics
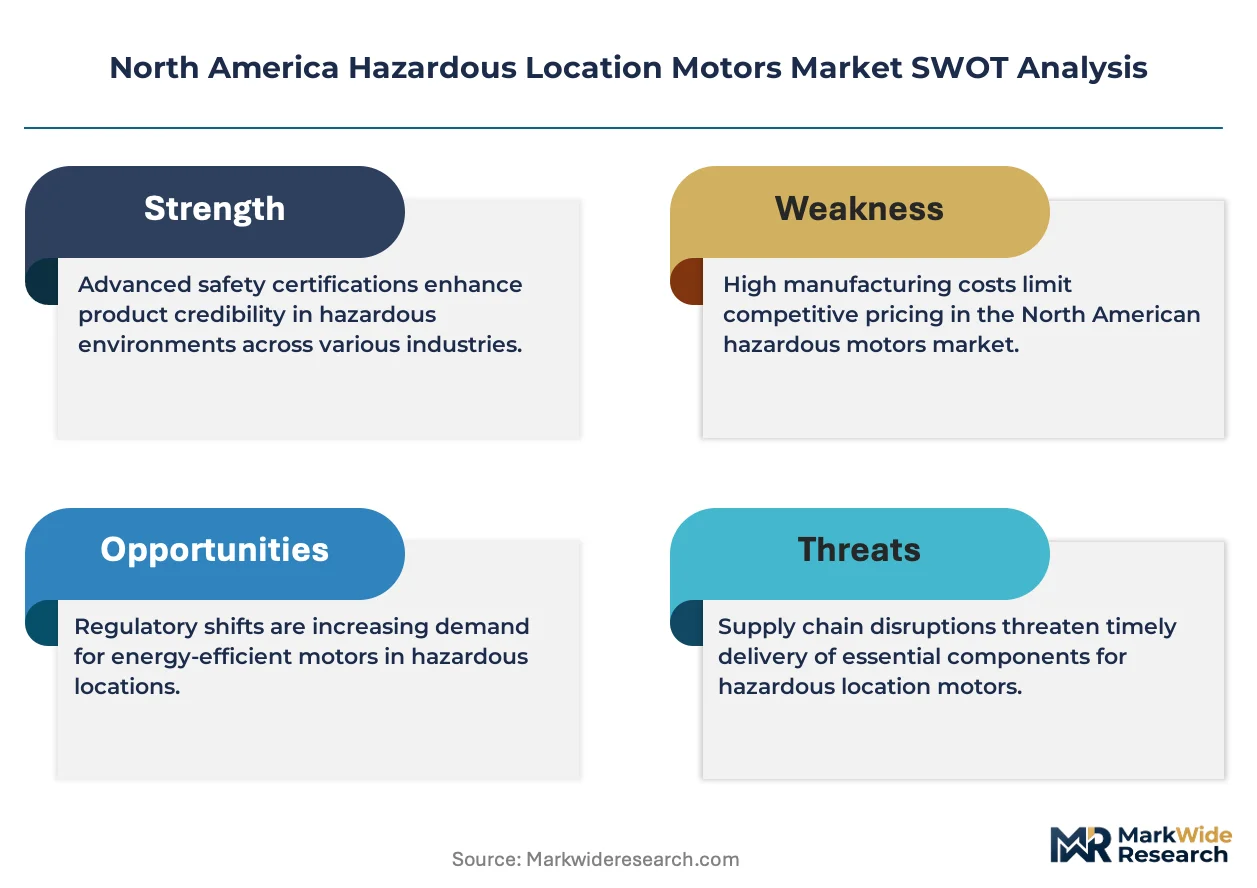
UL 674 certification retesting and NEMA MG 1 harmonization pressures are compressing the supplier base while oil and gas operators accelerate replacement cycles across the Permian Basin and Alberta oil sands. This regulatory-cost squeeze favors capital-rich manufacturers with captive testing infrastructure.
Growth Catalysts
- OSHA 29 CFR 1910.307 enforcement:Upgraded inspection protocols across Texas and Louisiana petrochemical corridors are forcing facility-wide motor audits and wholesale replacements.
- Alberta oil sands expansion:Steam-assisted gravity drainage projects in the Athabasca region require medium-voltage explosion-proof motors for artificial lift systems.
- NFPA 654 compliance deadlines:Grain elevators and wood processing facilities across the US Midwest are retrofitting dust-ignition proof motor installations.
Market Restraints
- Copper and rare earth magnet volatility:Neodymium price swings from Chinese export controls compress margins on high-efficiency permanent magnet designs.
- Dual-certification burden:CSA C22.2 No. 145 requirements in Canada force redundant testing for cross-border suppliers serving Alberta-Saskatchewan energy corridors.
- Extended lead times for cast iron enclosures:Foundry capacity concentration in Mexico creates bottlenecks for Class I Division 1 motor housings.
Strategic Opportunities
- Pharmaceutical stainless steel washdown motors:FDA-validated documentation requirements create pricing premiums for motors serving aseptic processing in Puerto Rico and Massachusetts biotech clusters.
- Variable frequency drive integration:Bundled motor-drive safety architectures open service revenue streams beyond hardware margins.
- Texas-Louisiana aftermarket channel consolidation:Independent distributors in the Gulf Coast petrochemical belt face succession gaps, creating acquisition targets for integrated suppliers.
Industry Challenges
- IECEx-NEMA harmonization timeline uncertainty:Stalled standard convergence forces manufacturers to maintain parallel design teams and documentation systems.
- Specialized winding technician scarcity:Vacuum pressure impregnation expertise for hazardous duty insulation systems concentrates among retiring practitioners in the US Southeast.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hazardous Location Motors Market |
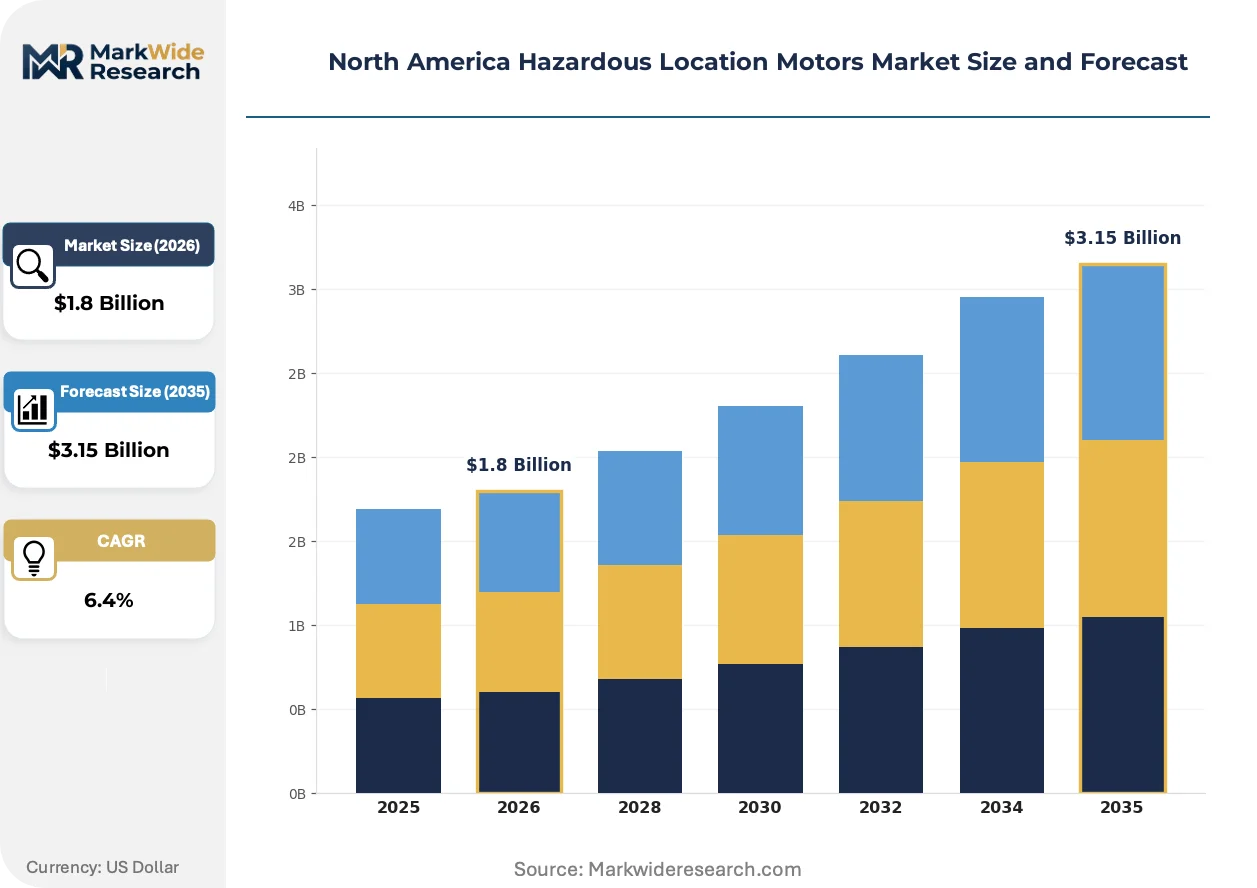
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Explosion-Proof Motors, Dust-Ignition Proof Motors, Corrosive Environment Motors, Sealed Motors Application: Mining, Chemical Processing, Oil & Gas, Pharmaceutical Manufacturing Fuel Type: Electric, Diesel, Gasoline, Dual Fuel End User: Utilities, Manufacturing, Transportation, Oil Refining |
| Companies Covered | Stainless Motors, Inc., Dietz Electric Co., Inc., Rockwell Automation, Inc., Nidec Motor Corporation, ABB Ltd, Brook Crompton, WEG Industries, Emerson Electric Co., General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hazardous Location Motors Market Evolving Landscape
Permanent magnet synchronous motor technology is fragmenting traditional induction motor dominance across North American hazardous locations. Three convergent developments are reshaping product architecture and procurement patterns.
Permanent magnet rotor designs are fragmenting market share previously held by squirrel-cage induction motors in medium-voltage applications. Oil and gas operators in the Permian Basin are adopting these designs for artificial lift systems where efficiency gains justify premium pricing. The technology is fragmenting supplier tiers by requiring rare earth magnet supply agreements and advanced rotor assembly capabilities that smaller manufacturers cannot replicate.
EPA methane emissions rules under the Clean Air Act are tightening motor efficiency and sealing requirements for upstream and midstream equipment. Compressor stations across Texas and New Mexico must now specify motors with enhanced bearing seals and lower windage losses to meet venting thresholds. The regulation is compressing procurement timelines as operators race to qualify equipment before enforcement deadlines.
Integrated safety architectures are displacing standalone motor purchases across Gulf Coast petrochemical complexes. Engineering-procurement-construction firms are specifying motor-variable frequency drive packages with SIL-rated safety functions rather than discrete components. This bundling concentrates purchasing authority with automation specialists and compresses margins for pure-play motor manufacturers serving Louisiana and Texas refineries.
North America Hazardous Location Motors Market Segmentation
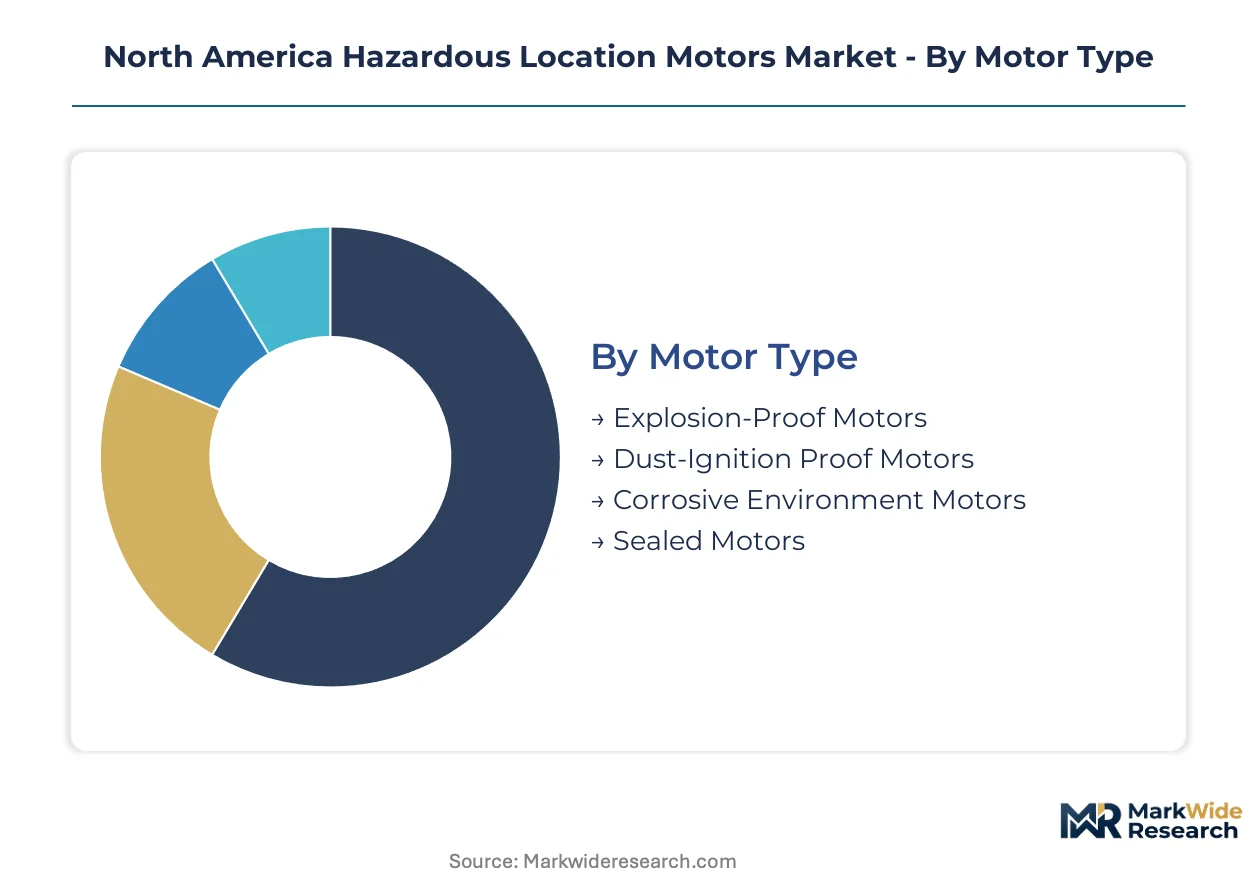
Hazardous location motor procurement patterns diverge sharply across protection methodologies and end-use environments. Segmentation reveals where certification premiums concentrate and which application verticals drive replacement velocity.
Motor Type:
Margin pools concentrate in designs requiring UL 674 certification and specialized enclosure engineering, with premium capture strongest in explosion-rated and corrosion-resistant categories.
- Explosion-Proof Motors:Sealed cast iron enclosures with machined flame paths contain internal explosions without igniting surrounding atmospheres. Demand concentrates across Texas and Louisiana petrochemical corridors where OSHA 29 CFR 1910.307 enforcement accelerates facility-wide replacement programs.
- Dust-Ignition Proof Motors:Tight-fitting enclosures and non-sparking fan designs prevent ignition of combustible dust suspensions. Grain elevators and wood processing facilities across the US Midwest are retrofitting installations ahead of NFPA 654 compliance deadlines.
- Corrosive Environment Motors:Stainless steel or epoxy-coated housings resist chemical attack in coastal and chemical processing settings.
- Sealed Motors:Hermetic designs exclude moisture and contaminants for washdown environments in food and pharmaceutical plants.
The dominant share belongs to Explosion-Proof Motors, while Dust-Ignition Proof Motors are expanding most quickly as NFPA enforcement tightens.
Application:
Application segmentation tracks directly to regulatory enforcement intensity and infrastructure age profiles across North American industrial clusters.
- Oil & Gas:Artificial lift systems and compressor stations in the Permian Basin and Alberta oil sands require medium-voltage explosion-proof designs with enhanced bearing seals for EPA methane compliance.
- Chemical Processing:Continuous-duty motors in chlor-alkali and petrochemical plants face aggressive chemical exposure and temperature cycling.
- Mining:Underground coal and hard rock operations maintain predictable replacement cadences tied to MSHA inspection schedules.
- Pharmaceutical Manufacturing:FDA-validated stainless steel washdown motors command pricing premiums in Puerto Rico and Massachusetts biotech corridors.
Oil & Gas retains the largest revenue pool, though Pharmaceutical Manufacturing delivers the steepest margin expansion.
Fuel Type:
Electrification mandates and emissions rules are compressing fossil-fuel motor demand while expanding specification complexity for electric alternatives.
- Electric:AC induction and permanent magnet synchronous designs dominate new installations across all classified environments.
- Diesel:Remains entrenched in remote mining and upstream oil sites lacking grid infrastructure.
- Gasoline:Limited to portable equipment and temporary installations in non-continuous duty cycles.
- Dual Fuel:Flexibility for grid-connected sites with backup generation requirements.
Electric motors hold commanding share, with Diesel retreating fastest under emissions pressure.
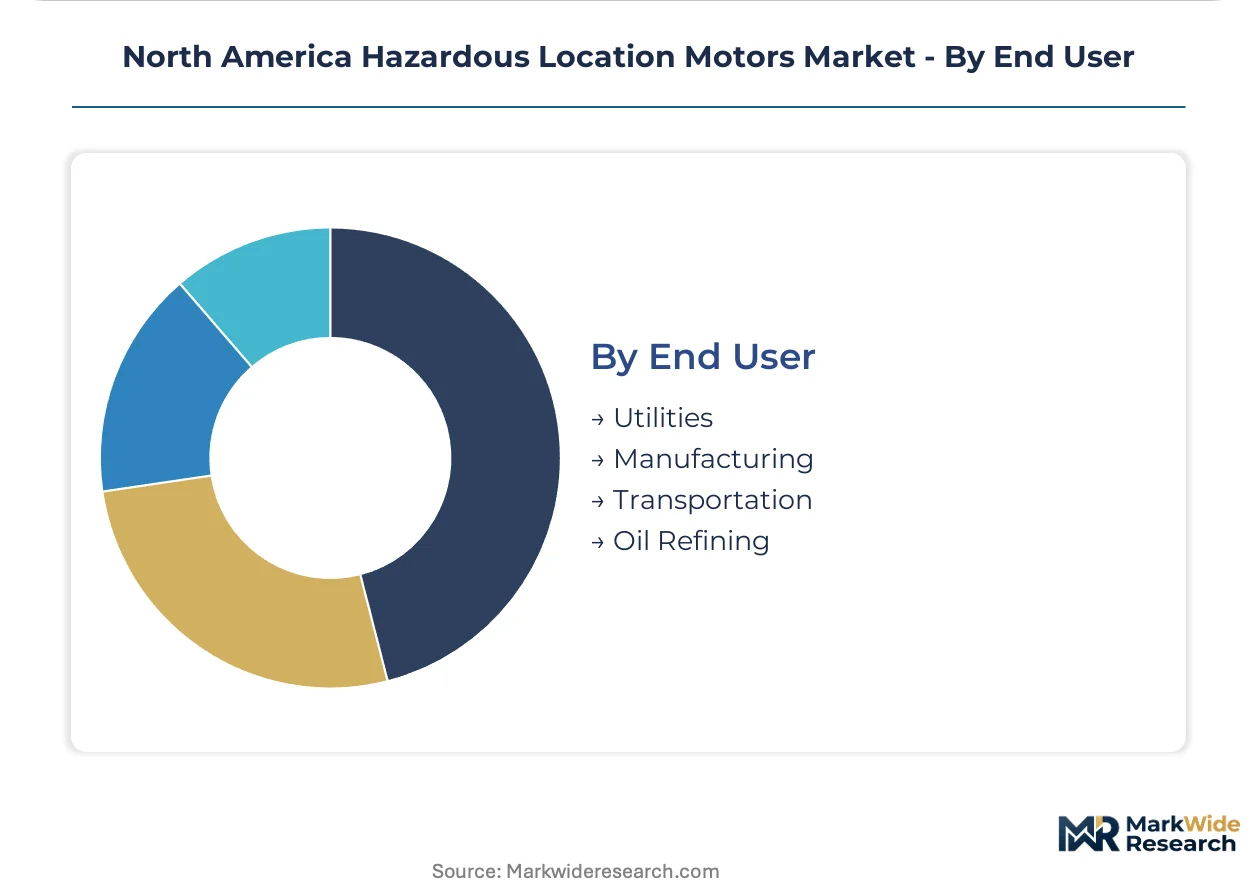
End User:
End user segmentation maps to capital expenditure cycles and regulatory exposure across North American industrial infrastructure.
- Oil Refining:Gulf Coast refineries in Texas and Louisiana drive bulk replacement demand through integrated turnaround schedules.
- Utilities:Natural gas compression and power generation facilities specify medium-voltage hazardous duty designs.
- Manufacturing:Chemical, food, and pharmaceutical plants balance uptime requirements against washdown and corrosion specifications.
- Transportation:Pipeline compressor stations and rail loading terminals require specialized sealing for volatile product handling.
Oil Refining anchors volume demand, while Manufacturing segments are diversifying fastest across application types.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA 29 CFR 1910.307 enforcement and EPA methane emissions rules are reshaping motor procurement patterns across North American industrial corridors. Federal and provincial regulators are tightening compliance windows while energy infrastructure age accelerates replacement cycles.
United States
Texas and Louisiana petrochemical clusters drive bulk demand as Gulf Coast refineries execute integrated turnaround schedules. OSHA inspection protocols across Houston and Lake Charles corridors are forcing facility-wide motor audits and wholesale replacements. The Permian Basin artificial lift expansion requires medium-voltage explosion-proof designs with enhanced bearing seals.
Canada
Alberta oil sands steam-assisted gravity drainage projects anchor medium-voltage motor demand for artificial lift systems. CSA C22.2 No. 145 certification creates dual-compliance burdens for cross-border suppliers serving Alberta-Saskatchewan energy corridors. Athabasca region operators are accelerating equipment qualification timelines ahead of provincial emissions deadlines.
Mexico
Foundry capacity concentration in northern Mexico creates bottlenecks for Class I Division 1 motor housings serving US cross-border demand. The country's manufacturing integration into North American petrochemical supply chains expands specification requirements for UL 674-certified designs. Monterrey and Tamaulipas industrial zones are absorbing overflow casting orders from US motor assemblers.
North America Hazardous Location Motors Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive hazardous duty certification infrastructure. Market structure concentrates around capital-rich manufacturers capable of absorbing UL 674 retesting costs and maintaining parallel NEMA-IECEx documentation systems. Three archetypes dominate: integrated automation suppliers bundling motors with drives, pure-play motor specialists with fractional horsepower depth, and diversified electrotechnical conglomerates with medium-voltage scale. Competitive moves center on aftermarket channel consolidation in Texas-Louisiana corridors and integrated safety architecture partnerships with engineering-procurement-construction firms.
Within the integrated automation tier, Rockwell Automation exemplifies bundled motor-drive safety architectures that concentrate purchasing authority with automation specialists. ABB Ltd and Nidec Motor Corporation anchor the electrotechnical conglomerate and pure-play specialist positions respectively, with the former representing medium-voltage hazardous duty scale and the latter occupying fractional horsepower aftermarket density across Oklahoma and Texas petrochemical corridors.
| Leading Market Players |
|---|
| Stainless Motors, Inc. |
| Dietz Electric Co., Inc. |
| Rockwell Automation, Inc. |
| Nidec Motor Corporation |
| ABB Ltd |
| Brook Crompton |
| WEG Industries |
| Emerson Electric Co. |
| General Electric |
| Others |
Value Network & Pricing Analysis
Foundry capacity utilization in northern Mexico and the US Southeast shapes price floors for Class I Division 1 motor housings while compressing margins for smaller assemblers lacking captive casting agreements. UL 674 certification costs and NEMA MG 1 harmonization expenses concentrate pricing power with capital-rich manufacturers who absorb retesting burdens without tier erosion.
Pricing Analysis
Certification level creates the primary spread across the motor market, with UL 674-validated designs commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects enclosure material grade, efficiency tier, and after-sales service bundling. Cost compression in medium-voltage segments is intensifying because rare earth magnet volatility from Chinese export controls squeezes permanent magnet synchronous designs. Independent distributors in the Gulf Coast corridor exhibit highest price sensitivity, while integrated EPC firms purchasing bundled motor-drive architectures show lowest elasticity.
Supply Chain Analysis
Extended lead times for cast iron enclosures now stretch eighteen to twenty-four months as foundry capacity concentrates in Mexico, China, and India. Raw material dependencies center on copper windings, neodymium permanent magnets, and epoxy resin insulation systems. Single-source vulnerability in Chinese rare earth processing creates supply chain risk for high-efficiency motor designs. Distribution runs through authorized industrial distributors in Texas and Louisiana petrochemical corridors, with direct OEM relationships gaining share among large refinery operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against integrated motor-drive architectures that displace standalone motor purchases across Gulf Coast petrochemical complexes. Permanent magnet synchronous technology and variable frequency drive bundling threaten pure-play motor manufacturers who fail to adapt their value proposition.
For Market Incumbents: Shield core aftermarket positions in Texas-Louisiana corridors by acquiring independent distributors facing succession gaps. Captive testing infrastructure investment defends against UL 674 retesting cost pressures while backward integration into foundry partnerships secures Class I Division 1 housing supply. Vertical integration into variable frequency drive engineering counters Rockwell Automation's bundled safety architecture threat. For New Entrants and Emerging Players: Differentiate on pharmaceutical stainless steel washdown specialization where FDA-validated documentation requirements create pricing premiums. Target Puerto Rico and Massachusetts biotech clusters where aseptic processing demand outstrips certified supplier capacity. Pursue fractional horsepower dust-ignition proof designs for Midwest grain elevator retrofits ahead of NFPA 654 enforcement deadlines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated automation suppliers bundling motors with service contracts and drive maintenance agreements. Five-to-ten year viability favors manufacturers with captive UL 674 testing infrastructure and parallel NEMA-IECEx documentation capabilities. Watch for IECEx-NEMA harmonization breakthrough as inflection indicator that would collapse redundant certification costs and reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive casting supply in Mexico insulates against Class I Division 1 housing bottlenecks. |
| Variable Frequency Drive Engineering Investment | Motor-drive bundling captures EPC procurement authority across Texas and Louisiana refineries. |
| Pharmaceutical Certification Expansion | FDA-validated stainless steel washdown capability unlocks Puerto Rico biotech pricing premiums. |
| Aftermarket Channel Consolidation | Acquisition of Gulf Coast distributors deepens replacement part penetration in petrochemical corridors. |
| Permanent Magnet Supply Agreements | Long-term neodymium contracts hedge Chinese export control volatility for synchronous motor lines. |
Research Methodology
Desk research of regulatory filings, trade association technical standards, and foundry capacity databases preceded structured interviews with plant engineers at Texas and Louisiana refineries, procurement leads at Alberta oil sands operators, and aftermarket service heads at Gulf Coast distributors. Primary fieldwork with UL certification engineers and NEMA standards committee participants combined with secondary validation against OSHA enforcement records and EPA methane compliance disclosures. Bottom-up motor shipment tracking by protection class and horsepower tier triangulated against top-down energy infrastructure investment flows.
Variance decomposition across motor type, application vertical, voltage class, and end-user industry anchored the analytical framework over the projection horizon. CAGRs derived from replacement cycle velocity in oil and gas infrastructure, NFPA 654 compliance timelines for grain handling facilities, and pharmaceutical manufacturing expansion patterns in Puerto Rico and Massachusetts. Forecast inputs incorporated rare earth magnet price trajectory assumptions and foundry capacity expansion schedules in Mexico.
The analysis sits within stated boundaries; outcomes outside sustained OSHA 29 CFR 1910.307 enforcement intensity or accelerated IECEx-NEMA harmonization would require recalibration. Forecasts reflect documented assumptions regarding copper and neodymium commodity paths, foundry throughput recovery, and petrochemical turnaround scheduling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
US Electric Motor Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
China AC Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Vietnam Air Compressor Market
Industrial Motors
AC Motor Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Spargers Market