
 Global Switched Reluctance Motor Market | 2026-2036
Global Switched Reluctance Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Switched Reluctance Motor Market Intelligence
Expanded manufacturing capacity in China for rare-earth-free motors is rewriting the supply landscape for switched reluctance motor components. Siemens AG leverages its extensive industrial automation portfolio to integrate SRMs into complete factory systems. Nidec Corporation competes on manufacturing scale and cost efficiency, particularly in fractional horsepower motor segments for appliances. Shandong Kehui Power Automation specializes in high-power applications for heavy industry within the domestic Chinese market.
A switched reluctance motor is an electric motor that operates by reluctance torque, featuring a simple, robust rotor without windings or permanent magnets. Its primary function is to provide highly reliable, fault-tolerant variable speed operation, especially in harsh environments or high-temperature applications. Within the application mix, industrial automation and HVAC systems command significant volume, while electric drives represent the fastest-growing segment. Sensorless control technology is gaining share over position sensor-based control due to its lower cost and reduced complexity.
Motor efficiency regulations, including the European Union's Ecodesign requirements and China's GB standards for energy conservation, directly influence design choices. These frameworks mandate minimum performance levels, creating opportunities for SRM technology which avoids losses associated with permanent magnets. Stakeholder decisions will hinge on balancing the higher initial cost of advanced digital control systems against the long-term operational savings and reliability gains.
Market Dynamics
The push for enhanced energy efficiency, codified by regulations like the European Union's Ecodesign Directive and China's GB standards, is the central force shaping the market. This creates a structural advantage for magnet-free designs that avoid specific material dependencies.
Growth Catalysts
- Industrial Automation Demand:The expansion of factory automation, particularly for precision electric drives in manufacturing and logistics, requires highly controllable and reliable motors, a core strength of SRM technology.
- Regulatory Mandates:The EU's Ecodesign Directive and similar energy performance standards in other jurisdictions compel OEMs to adopt more efficient motor technologies to meet minimum performance levels, benefiting SRMs.
- Electric Vehicle Sector:Government support for electric vehicle production, especially in China, creates significant volume demand for motors that do not rely on rare-earth permanent magnets, mitigating supply chain risks.
Market Restraints
- Control System Complexity:The requirement for sophisticated digital controllers and power electronics to manage torque ripple and acoustic noise adds significant cost and design complexity compared to conventional induction motors.
- Acoustic Noise and Vibration:Inherent torque ripple in switched reluctance motors produces higher levels of acoustic noise, which can be a disqualifying factor for applications in commercial HVAC or passenger vehicles.
- Competition from PMSMs:Permanent magnet synchronous motors offer superior power density and peak efficiency in many applications, presenting a strong substitution threat, particularly where fault tolerance is a lower priority.
Strategic Opportunities
- Harsh Environment Applications:The robust, magnet-free construction of SRMs makes them ideal for underpenetrated high-temperature applications in sectors like aerospace, mining, and oil and gas exploration equipment.
- Sensorless Control Integration:Pairing advanced sensorless control algorithms with next-generation power semiconductors like SiC or GaN can unlock higher performance, reduce system costs, and improve reliability.
- Indian Industrial Modernization:India's push for domestic manufacturing through policies like the PLI scheme presents a significant opportunity for SRMs in appliances, industrial pumps, and textile machinery.
Industry Challenges
- Specialized Engineering Talent:A scarcity of engineers with deep expertise in the complex control theory, power electronics, and electromagnetic design specific to SRMs constrains product development and application support.
- System Integration Hurdles:Retrofitting SRMs into equipment designed for induction motors often requires a complete redesign of the drive system, creating significant integration challenges and costs for OEMs.
- Lack of Standardization:The absence of widely accepted performance testing standards for SRMs, unlike mature IEC standards for induction motors, complicates procurement and direct comparison for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Switched Reluctance Motor Market |
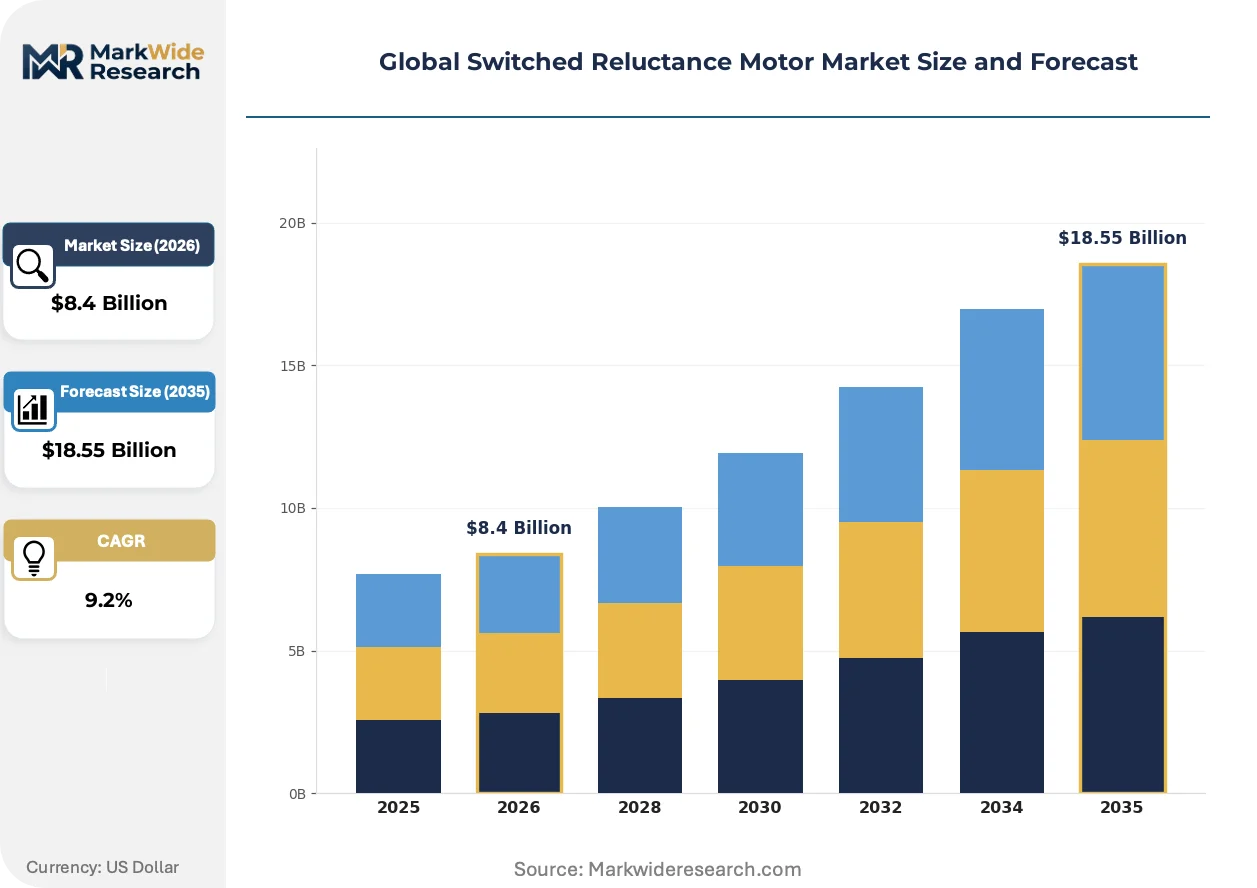
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fractional Horsepower, Medium Power, High Power, Ultra-High Power Technology: Digital Control, Analog Control, Sensorless Control, Position Sensor Based Control Application: HVAC Systems, Power Tools, Electric Drives, Industrial Automation End User: OEMs, Aftermarket Service Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Shandong Kehui Power Automation, ABB Ltd., Nidec Corporation, Magna International, Siemens AG, AMETEK, Maccon GmbH, Bosch Rexroth, VS Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Switched Reluctance Motor Market Strategic Shifts & Innovations
Convergence of advanced digital control capabilities with stringent energy efficiency regulations is redefining the role of switched reluctance motors. This shift is moving the technology from niche, fault-tolerant applications toward more mainstream industrial and automotive segments where reliability and lifecycle cost are paramount.
Sensorless control is an algorithm-based technique that calculates rotor position without physical hardware. Industrial automation and HVAC system manufacturers are adopting this technology to reduce component count, lower costs, and eliminate a potential point of failure. The market for motor control is migrating from expensive, failure-prone Hall-effect sensors toward more robust, software-driven estimation techniques.
China's GB standards for energy conservation and its national "dual carbon" goals impose strict minimum energy performance standards on industrial motors. These regulations create a strong compliance-driven incentive for factory operators to replace older, inefficient equipment. The heavy industry and manufacturing sectors are most affected, accelerating their adoption of efficient motor technologies that avoid losses associated with permanent magnets.
Original equipment manufacturers are shifting their evaluation criteria from upfront motor price to a total cost of ownership model. This change in procurement behavior prioritizes long-term operational savings from higher energy efficiency and reduced maintenance over the initial capital outlay. This TCO-focused purchasing is most visible in the European industrial sector, where high energy costs and ESG reporting amplify the value of reliability.
Global Switched Reluctance Motor Market Segmentation
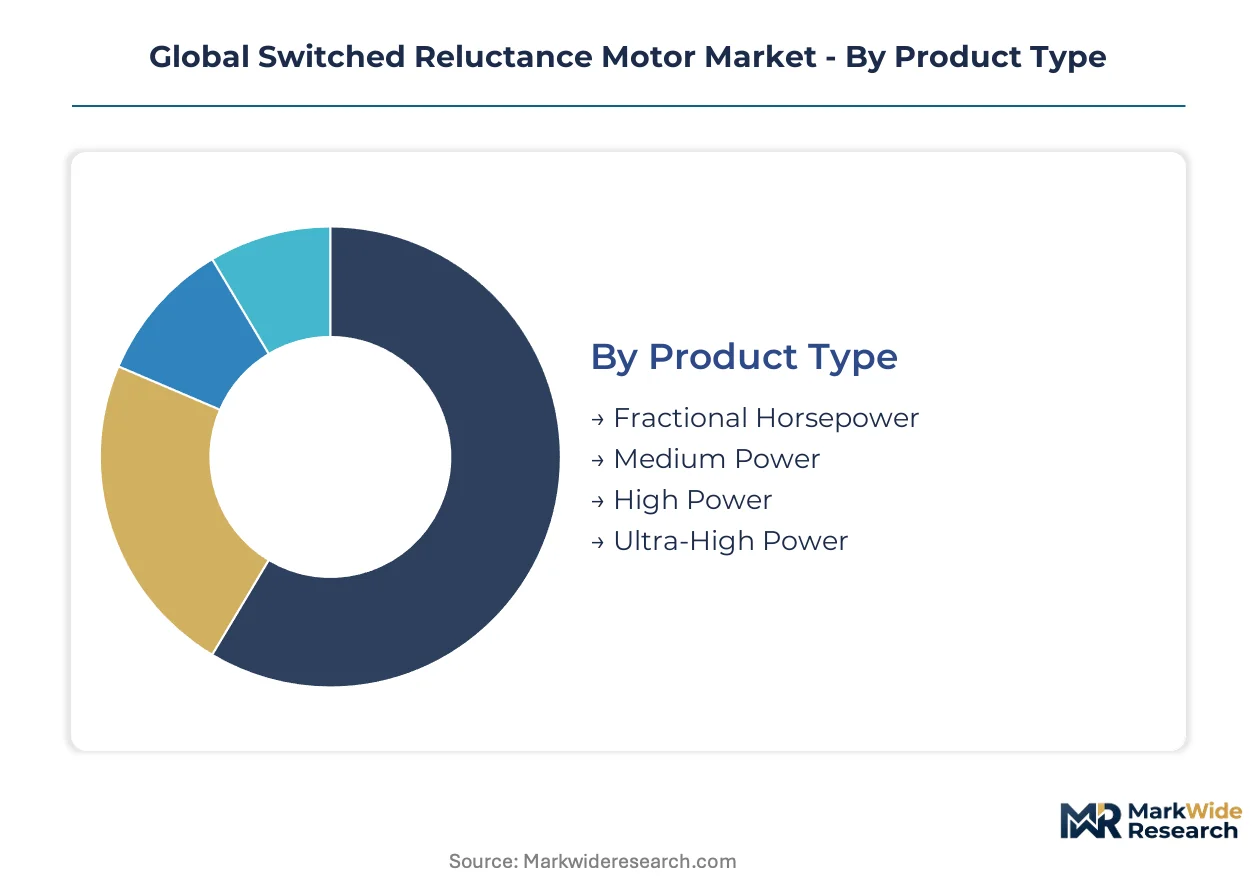
The global switched reluctance motor market exhibits diverse operational characteristics and end-use requirements. Understanding these distinct segments clarifies the varying demand drivers and technological preferences across industrial and automotive applications. This segmentation analysis provides a structured view of market dynamics.
Product Type:
Product type segmentation reveals a mature core of established motor configurations alongside emerging higher-power designs.
- Medium Power:These motors typically range from 1 kW to 100 kW, balancing efficiency and torque for industrial machinery. Demand concentrates in European factory automation, driven by strict energy efficiency mandates like the EU Ecodesign Directive.
- High Power:Exceeding 100 kW, these units are engineered for heavy-duty applications requiring sustained high torque and robustness. China's heavy industry and electric vehicle manufacturing sectors drive demand for these powerful SRMs.
- Fractional Horsepower:Motors below 746 Watts serve appliances and small tools, where cost efficiency and compact design are paramount.
- Ultra-High Power:Units over 500 kW target specialized applications such as mining equipment and large industrial pumps, emphasizing extreme durability.
Medium Power SRMs handle the majority of throughput; High Power SRMs are the fastest mover on share.
Technology:
Technology segmentation differentiates solutions based on their control complexity and associated system cost tiers.
- Sensorless Control:This technique estimates rotor position using algorithms, eliminating physical sensors to reduce cost and potential failure points. Industrial automation and HVAC systems in India are adopting this to improve system reliability.
- Digital Control:Utilizes microcontrollers for precise torque and speed management, offering advanced fault detection and integration capabilities. European industrial users prioritize digital control for complex factory systems, seeking operational savings.
- Analog Control:Relies on simpler electronic circuits for basic motor operation, suitable for cost-sensitive applications with less stringent performance needs.
- Position Sensor Based Control:Employs physical sensors like encoders or resolvers for accurate rotor position, essential for high-precision or safety-critical applications.
Demand for Sensorless Control is expanding most quickly, while Digital Control maintains its established volume.
Application:
Application segments are differentiated by the volume of motors consumed and their specific operational demands.
- Industrial Automation:SRMs provide precision control for robotics, conveyors, and machine tools, driving efficiency in manufacturing processes. China's factory modernization initiatives and robust logistics sector heavily utilize these motors.
- Electric Drives:This segment includes propulsion systems for electric vehicles and heavy-duty off-highway equipment, valued for magnet-free construction. Government support for EV production in China creates significant volume demand here.
- HVAC Systems:SRMs offer energy-efficient operation for fans and pumps in commercial and residential heating, ventilation, and air conditioning units.
- Power Tools:Robust SRM designs are suited for drills, saws, and grinders, where high torque and durability are critical for professional use.
Industrial Automation drives the largest installed base, but Electric Drives show the steepest expansion trajectory.
End User:
End-user segmentation categorizes purchasers by their role in the value chain and their procurement patterns.
- OEMs:Original Equipment Manufacturers integrate SRMs into their final products, such as industrial machinery, appliances, or vehicles. Siemens AG, for example, integrates SRMs into complete factory systems for its industrial automation portfolio.
- Vehicle Assemblers:These entities directly procure SRMs for integration into electric vehicles, seeking magnet-free solutions to mitigate supply chain risks. Chinese EV manufacturers represent a significant and growing customer base for these motors.
- Aftermarket Service Providers:These firms supply replacement motors and parts for maintenance, repair, and overhaul operations of existing equipment.
- Tier-1 Suppliers:Companies that supply sub-assemblies or components directly to OEMs, often acting as intermediaries for specialized SRM parts.
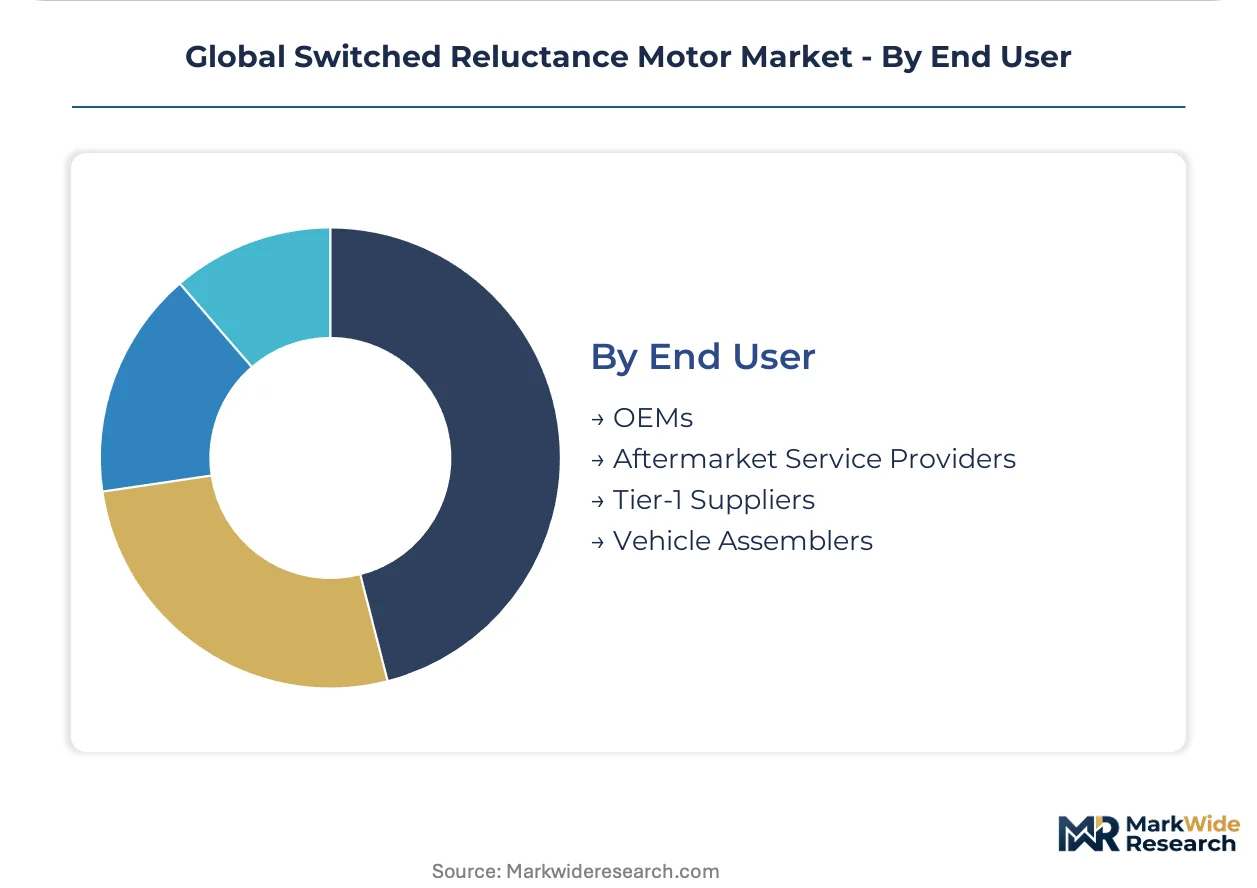
OEMs represent the largest procurement channel; Vehicle Assemblers are rapidly gaining purchasing influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for switched reluctance motors is concentrating in specific geographies. China's expanded capacity for rare-earth-free motors significantly influences the global supply landscape. This shift impacts component availability and pricing for OEMs worldwide.
China
China's robust demand for electric vehicles and heavy industrial machinery drives significant SRM adoption. The country's GB standards for energy conservation and national "dual carbon" goals compel industrial upgrades. Manufacturing hubs in the Yangtze River Delta are rapidly expanding production of high-power SRMs.
Germany
German industrial automation sectors require highly efficient and reliable electric drives for advanced manufacturing. The European Union's Ecodesign Directive mandates minimum performance levels, favoring magnet-free motor designs. Industrial centers like Bavaria prioritize digital control systems for complex factory applications.
United States
United States industrial modernization efforts and harsh environment applications in mining demand robust SRM technology. EPA regulations for energy efficiency compel manufacturers to adopt more advanced motor solutions. The Midwest manufacturing belt integrates SRMs into precision machinery for enhanced operational reliability.
India
India's push for domestic manufacturing through the PLI scheme creates substantial opportunity for SRM technology in various sectors. This policy incentivizes local production and adoption of efficient industrial components. Industrial clusters in Gujarat are integrating sensorless control SRMs into textile machinery and pumps.
Japan
Japanese manufacturers prioritize precision and reliability for advanced industrial machinery and robotics. METI energy efficiency standards encourage the adoption of innovative motor technologies that reduce energy consumption. The Kanto region focuses on developing high-performance SRMs for next-generation factory automation systems.
Global Switched Reluctance Motor Market Key Industry Players
Established industrial conglomerates and specialized motor manufacturers split the switched reluctance motor market. The competitive landscape features a tiered structure, with global players offering integrated solutions and regional specialists focusing on niche applications. Companies pursue strategic partnerships for technology co-development and expand manufacturing capacity to gain market share, especially in magnet-free designs. Portfolio diversification into advanced digital control systems and power electronics also remains a key competitive move. This strategic maneuvering aims to capture opportunities arising from energy efficiency mandates and electric vehicle growth.
Within the global industrial automation sector, Siemens AG represents an archetype of integrated solution providers, leveraging its broad portfolio to embed SRMs into complete factory systems. Nidec Corporation, a Japanese entity, exemplifies scale-driven manufacturing, focusing on cost-efficient fractional horsepower motors for appliances and general industrial use. Shandong Kehui Power Automation, a Chinese firm, anchors the high-power segment for heavy industry within its domestic market, addressing specific local demands. This mix highlights how diverse business models address varied end-user requirements and regional specificities across the market. Their distinct approaches underscore the varied market entry points and competitive advantages available to players.
| Leading Market Players |
|---|
| Shandong Kehui Power Automation |
| ABB Ltd. |
| Nidec Corporation |
| Magna International |
| Siemens AG |
| AMETEK |
| Maccon GmbH |
| Bosch Rexroth |
| VS Technology |
| Others |
Cost & Logistics Intelligence
Expanded manufacturing capacity in China for rare-earth-free motors drives both supplier behavior and pricing posture in the global switched reluctance motor market. This increased output influences the availability and cost of key SRM components worldwide.
Pricing Analysis
The European Union's Ecodesign Directive dictates the pricing tier structure for switched reluctance motors, driving differentiation based on efficiency ratings and integration complexity. Pricing stratifies across performance tiers and customization levels for specific industrial automation applications. Cost compression in the fractional horsepower segment is intensifying due to high-volume manufacturing scale in Asia. OEMs focused on energy efficiency and long-term operational savings are least price-sensitive, while small appliance manufacturers are most sensitive.
Supply Chain Analysis
Single-source vulnerability in power electronics dominates the switched reluctance motor supply chain, particularly for advanced SiC and GaN semiconductors. Component manufacturing concentrates heavily in China, Japan, and Germany. The industry relies on specialized magnetic steel and copper windings for stator production. OEMs procure motors directly from manufacturers or through Tier-1 suppliers and aftermarket service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The switched reluctance motor market presents a significant service-attach opportunity, with advanced digital control system upgrades and software-driven optimization expanding faster than hardware unit sales. This trend creates recurring revenue streams from performance monitoring and predictive maintenance solutions.
For Market Incumbents: Insulate core market share by deepening vertical integration into specialized power electronics and digital control software development. This strategy mitigates the threat from new entrants offering sensorless control solutions at lower costs. Invest in R&D for advanced acoustic noise reduction techniques to counter competition from PMSMs in noise-sensitive applications. Control over the entire drive system enhances competitive positioning against subsystem providers.
For New Entrants and Emerging Players: Build out niche capabilities in high-temperature and harsh environment applications like mining equipment or aerospace. The ultra-high power segment in emerging markets, particularly India's industrial modernization, represents the most penetrable geography. Target OEMs seeking robust, magnet-free solutions for specialized industrial pumps and textile machinery. Offer integrated sensorless control packages to simplify adoption and reduce system complexity for these specific applications.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized software and control system providers offering ongoing maintenance and optimization services. The switched reluctance motor market offers robust long-term viability over the next decade, driven by energy efficiency mandates. Target acquisition archetypes include mid-cap firms with proprietary sensorless control algorithms or advanced power electronics expertise. The signal to watch is the increasing penetration of SRMs into mainstream automotive platforms, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Digital Control R&D | Develop proprietary algorithms for torque ripple reduction, enhancing SRM competitiveness in noise-sensitive applications. |
| Manufacturing Capacity Expansion (China) | Scale production of high-power SRMs to meet electric vehicle and heavy industry demand in Asian markets. |
| Sensorless Control Integration | Reduce system cost and complexity for industrial automation and HVAC systems by eliminating physical position sensors. |
| Strategic Partnerships (Power Electronics) | Secure supply of next-generation SiC/GaN semiconductors, critical for high-performance SRM drive systems. |
| Certification Investment (EU Ecodesign) | Ensure compliance with stringent European energy efficiency mandates, opening access to premium industrial markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association reports, and company financial disclosures. This approach involved extensive interviews with OEM procurement managers, industrial automation engineers, power electronics specialists, and EV drivetrain developers. Bottom-up data aggregation and top-down market sizing provided robust validation. The analysis triangulated insights from these diverse sources to ensure comprehensive market understanding.
The forecast inputs considered macroeconomic indicators, technological advancements in control systems, and regional regulatory shifts. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, technology, application, end-user, and regional energy efficiency mandates. Compound Annual Growth Rates were derived from historical trends and projected adoption rates. Electric vehicle production targets and industrial automation investment levels served as key industry-specific inputs.
Practitioners should monitor shifts in rare-earth magnet pricing and new battery chemistries for early signals that could revise market forecasts. The analysis acknowledges that projections reflect inherent assumptions about technological progression and regulatory enforcement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
US Electric Motor Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Permanent Magnet Synchronous Motors Market