
 North America Refrigeration Oil Market | 2026-2036
North America Refrigeration Oil Market Size, Share, and Industry Trends Forecast 2026-2036
North America Refrigeration Oil Market Insights
Subscription-based oil condition monitoring is decoupling hardware sales from recurring service revenue in the North America refrigeration oil sector. Exxon Mobil Corporation leverages its integrated base oil and additive supply chain to control formulation costs across the region. Chevron Corporation sustains a dense distributor network that reaches independent servicing contractors in secondary U.S. markets. Shell Global differentiates through OEM co-development agreements with compressor manufacturers serving commercial refrigeration end users.
Refrigeration oil is a specialized lubricant formulated from refined mineral, synthetic alkylbenzene, or polyolester base stocks with viscosity grades spanning ISO 32 to ISO 100, designed to circulate with refrigerant while maintaining thermal stability and miscibility across evaporator and condenser temperature extremes. Synthetic oil commands the dominant value share due to its compatibility with hydrofluoroolefin and natural refrigerant chemistries that are displacing legacy HFC systems. Commercial refrigeration generates the largest application volume, though industrial refrigeration exhibits the fastest structural growth as ammonia-CO2 cascade systems expand in North American food processing plants.
The EPA enforces HFC phasedown timelines under the AIM Act that directly constrain refrigerant-lubricant pairing options available to equipment owners. The U.S. Department of Energy appliance efficiency standards and Canada's federal halocarbon regulations jointly elevate the performance threshold for approved lubricant formulations. Stakeholders must monitor state-level refrigerant rulemaking in California and pending amendments to ASHRAE safety standards that will determine acceptable oil chemistries for next-generation system architectures.
Market Dynamics
The EPA's AIM Act phasedown of hydrofluorocarbons is forcing immediate reformulation of refrigeration oils across the United States and Canada. Lubricant blenders must requalify chemistries for lower-GWP refrigerant pairings while maintaining thermal stability in cascade and transcritical CO2 architectures.
Growth Catalysts
- AIM Act Compliance Deadlines:The EPA's HFC phasedown timeline mandates retrofitting of commercial refrigeration fleets, creating sustained demand for synthetic alkylbenzene and polyolester formulations compatible with hydrofluoroolefin refrigerants.
- Food Processing Cluster Expansion:Cold storage construction in the U.S. Southeast and Pacific Northwest is accelerating bulk procurement of ISO 68 and ISO 100 viscosity grade oils for ammonia-CO2 cascade systems.
- Lower-GWP Refrigerant Migration:R-454B and R-1234yf adoption in commercial HVAC-refrigeration hybrids is pulling compatible lubricant formulations through distribution channels serving independent servicing contractors.
Market Restraints
- Base Oil Supply Concentration:Polyalphaolefin and polyolester base stock production concentrates among a limited set of Gulf Coast refiners, exposing blenders to feedstock allocation volatility during hurricane season disruptions.
- Refrigerant-Lubricant Miscibility Constraints:ASHRAE safety standard amendments pending approval will restrict oil chemistry options for flammable A2L and A3 refrigerant systems, extending qualification timelines.
- Mineral Oil Stranded Assets:Legacy R-22 and R-404A systems using naphthenic mineral oils face accelerated obsolescence as reclaimed refrigerant supplies dwindle and service costs exceed replacement economics.
Strategic Opportunities
- Mexican Cold Chain Infrastructure:Underpenetrated refrigerated warehousing and last-mile logistics in northern Mexico present first-mover positioning for synthetic oil suppliers establishing maquiladora-adjacent blending capacity.
- Subscription Monitoring Services:IoT-enabled oil condition analytics decouple hardware from recurring revenue, allowing lubricant vendors to capture lifetime value through predictive maintenance contracts with multi-site grocery chains.
- Natural Refrigerant System Convergence:Transcritical CO2 and ammonia-propane hybrid architectures in Canadian food processing plants require novel additive packages addressing copper plating and material compatibility.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:EPA Section 608 technician credentialing backlogs delay field deployment of qualified personnel for lower-GWP system servicing, constraining aftermarket oil demand realization.
- Formulation Testing Backlog:Compressor OEM co-development protocols and AHRI 570 certification queues extend product launch cycles, compressing window for capturing AIM Act transition demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Refrigeration Oil Market |
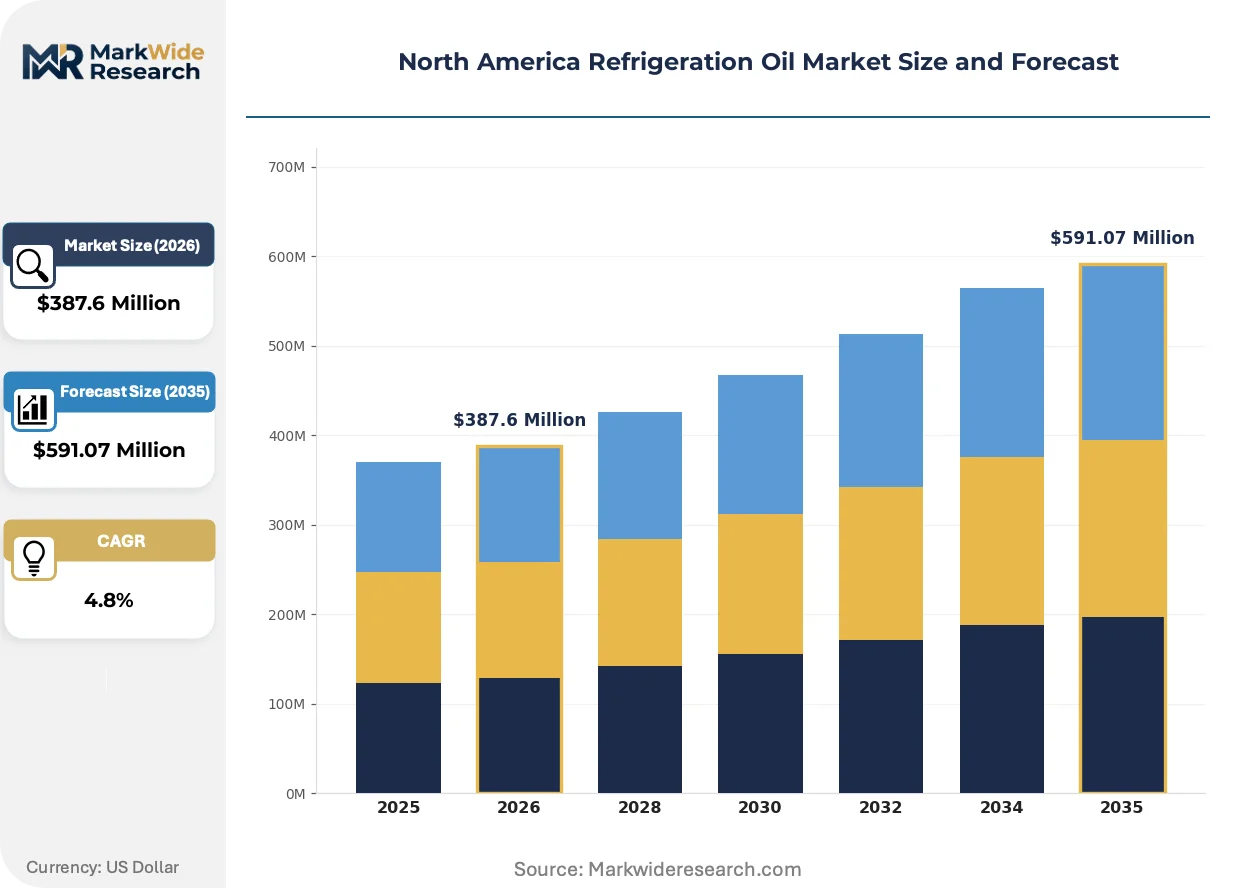
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Bio-based Oil, Refrigerant Oil Application: Commercial Refrigeration, Domestic Refrigeration, Industrial Refrigeration, Automotive Refrigeration Viscosity Grade: ISO 32, ISO 46, ISO 68, ISO 100 Distribution Channel: Online Retail, Offline Retail, Distributors, Wholesalers |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, Shell Global, FUCHS, Calumet Specialty Products Partners, Johnson Controls, Cosmo Oil Lubricants Co., Ltd., CAMCO Lubricants, Lubriplate Lubricants Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Refrigeration Oil Market Trends and Innovations
Synthetic lubricant architectures are converging with refrigerant thermodynamics to enable next-generation system efficiency. Three developments are compressing traditional formulation cycles and reshaping competitive positioning across the North American value chain.
Polyolester base stocks with optimized viscosity-temperature coefficients are unifying lubrication requirements across transcritical CO2 and subcritical ammonia systems. Food processors in the Midwest and Southeast are specifying these chemistries for new cascade installations to simplify inventory management. This unification is compressing the number of SKUs distributors must stock while elevating technical support requirements.
The EPA's Technology Transitions program under AIM Act Section 103 prohibits certain HFC refrigerants in new equipment categories on fixed phaseout dates. Original equipment manufacturers are front-loading lubricant qualification to secure compressor platform approvals ahead of refrigerant deadlines. Commercial refrigeration OEMs serving supermarket chains face the most compressed compliance timelines.
Condition-based monitoring via dielectric sensors and particle counters is displacing scheduled oil changes in large industrial refrigeration assets. Cold storage operators in California and Washington state are piloting these systems to reduce refrigerant exposure during maintenance events. This behavioral shift is fragmenting lubricant demand into smaller, higher-margin analytical service contracts.
North America Refrigeration Oil Market Segmentation
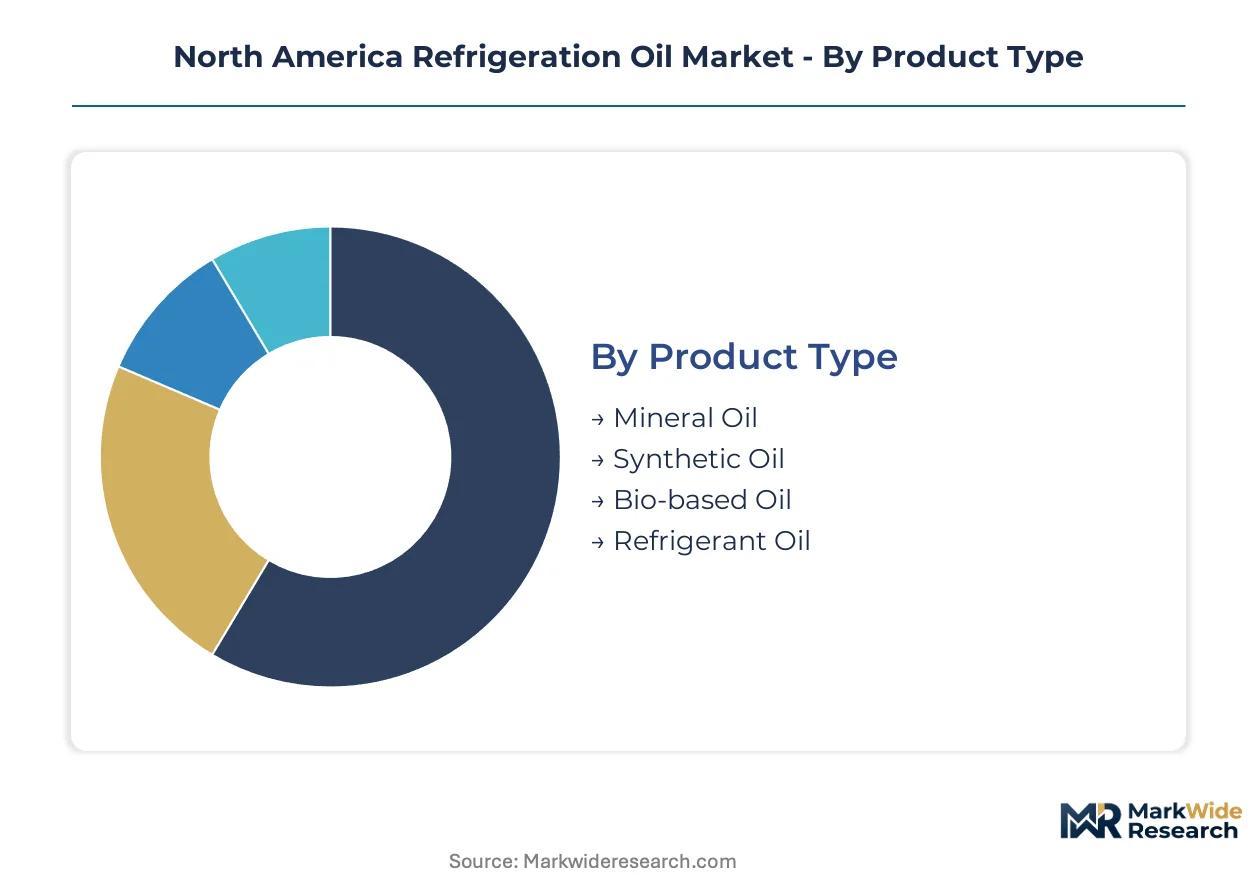
Refrigeration oil segmentation in North America reflects divergent paths between legacy system maintenance and next-generation refrigerant compatibility. The transition from hydrofluorocarbon to hydrofluoroolefin and natural refrigerant systems fragments demand across formulation chemistries, viscosity grades, and channel structures. Procurement patterns vary sharply between food processing clusters seeking bulk synthetic formulations and independent service contractors requiring just-in-time mineral oil replenishment.
Product Type:
Customization intensity spans from commodity mineral formulations to engineered synthetic architectures requiring OEM co-qualification.
- Mineral Oil:Refined naphthenic and paraffinic base stocks formulated for legacy R-22 and R-404A systems. Demand concentrates in the U.S. Southeast among independent servicing contractors maintaining aging supermarket refrigeration fleets amid dwindling reclaimed refrigerant supplies. The EPA's AIM Act phasedown accelerates asset obsolescence as service economics deteriorate.
- Synthetic Oil:Alkylbenzene and polyolester base stocks engineered for miscibility with lower-GWP refrigerants. Food processing clusters across the Pacific Northwest specify these formulations for ammonia-CO2 cascade systems, driven by compliance deadlines and thermal stability requirements in transcritical architectures.
- Bio-based Oil:Ester formulations derived from vegetable feedstocks targeting sustainability mandates in California and Washington state cold storage operations.
- Refrigerant Oil:Pre-mixed lubricant-refrigerant solutions packaged for field servicing of specific equipment platforms.
Most installed capacity flows through Synthetic Oil. Expansion is steepest in Bio-based Oil.
Application:
Volume scale inverts against margin structure, with commercial segments driving throughput and industrial segments commanding formulation premiums.
- Commercial Refrigeration:Supermarket display cases, walk-in coolers, and convenience store systems constitute the largest volume segment. The U.S. Southeast food retail corridor generates concentrated demand for ISO 68 viscosity formulations compatible with R-448A and R-449A retrofit blends.
- Industrial Refrigeration:Ammonia and CO2 systems in meat processing, dairy, and cold storage facilities. Canadian prairie grain terminals and Midwest U.S. protein processing plants are expanding cascade system deployments, requiring specialized additive packages addressing copper plating in high-pressure circuits.
- Domestic Refrigeration:Household refrigerator-freezer units using hermetic compressors with lifetime-fill lubricant charges.
- Automotive Refrigeration:Mobile air conditioning and transport refrigeration units, with R-1234yf compatibility driving polyolester adoption in fleet retrofit programs.
Commercial Refrigeration absorbs the highest absolute volumes. Industrial Refrigeration is climbing the fastest as food security investments accelerate.
Viscosity Grade:
Temperature operating windows and refrigerant miscibility curves determine grade selection across evaporator and condenser extremes.
- ISO 68:The workhorse grade for commercial refrigeration compressors operating in moderate climate zones. U.S. Gulf Coast cold storage operators specify this viscosity for balanced flow characteristics in R-404A replacement scenarios.
- ISO 100:Heavy-duty formulations for low-temperature industrial systems and high-ambient condensing environments. Ammonia-CO2 cascade installations in Alberta and Saskatchewan meat processing facilities favor this grade for boundary lubrication under high bearing loads.
- ISO 32:Light formulations for rotary and scroll compressors in commercial HVAC-refrigeration hybrid systems.
- ISO 46:Intermediate viscosity bridging automotive and light commercial applications with seasonal temperature variability.
ISO 68 dominates current procurement volumes. ISO 100 is gaining share fastest amid industrial system expansion.
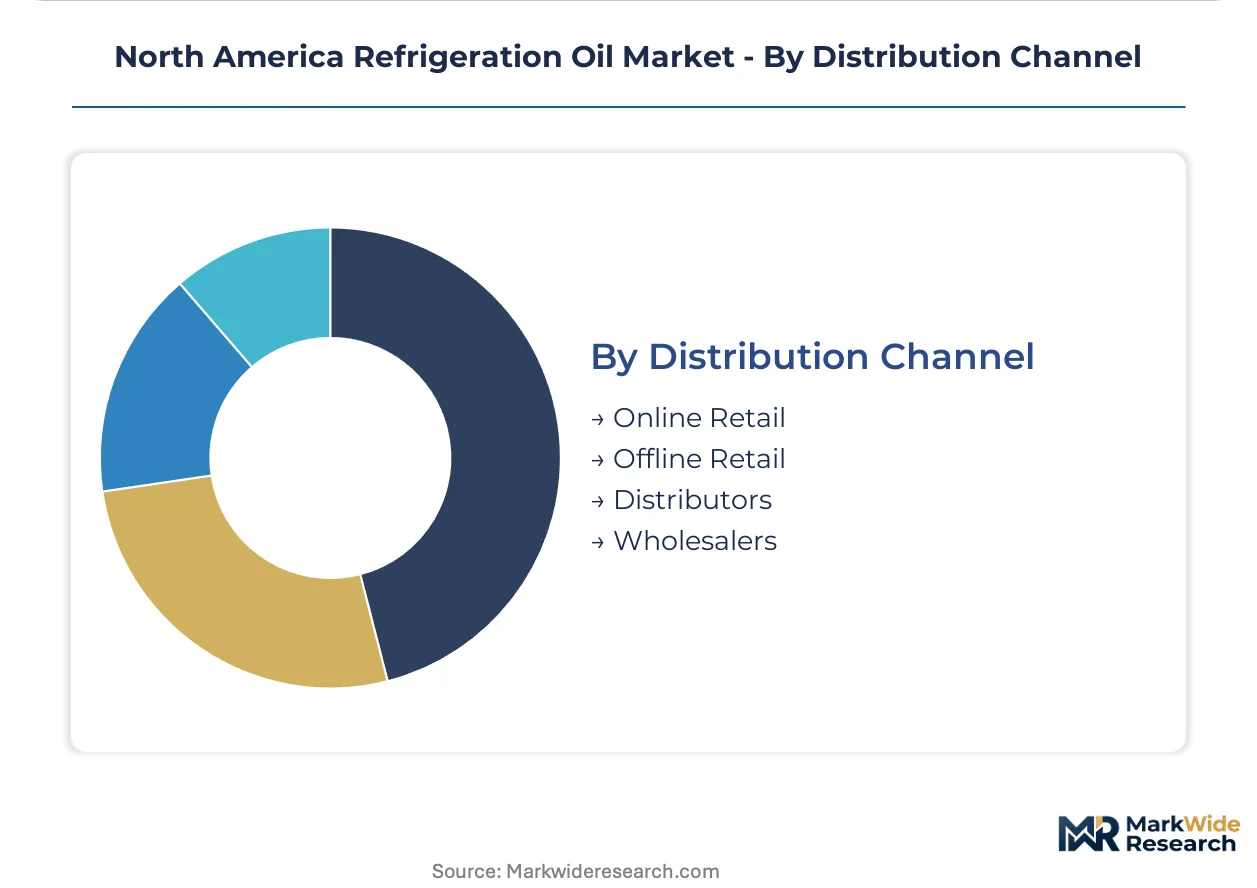
Distribution Channel:
Channel selection tracks customer scale and technical support requirements, fragmenting between self-service procurement and engineered solution delivery.
- Distributors:Technical wholesalers maintaining blender relationships and OEM certification documentation. Independent servicing contractors in secondary U.S. markets rely on these channels for same-day ISO 68 and ISO 100 availability and refrigerant-lubricant pairing guidance.
- Wholesalers:Volume aggregators supplying cold chain construction projects with bulk synthetic formulations. Pacific Northwest port-centric cold storage developments source through these channels for project-scale procurement efficiency.
- Online Retail:E-commerce platforms capturing small-lot demand from facility maintenance departments with predictable specification requirements.
- Offline Retail:Counter sales at regional supply houses serving emergency service calls and walk-in contractor traffic.
Distributors handle the majority of technical formulation sales. Online Retail is expanding most quickly as procurement digitization penetrates mid-sized grocery chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's refrigeration oil procurement trails the United States in absolute volume yet exceeds it in synthetic formulation intensity per installed ton of cooling capacity. Mexico's cold chain infrastructure remains underdeveloped relative to its northern neighbors, creating asymmetric growth trajectories across the trade bloc.
United States
Food processing clusters in the U.S. Southeast and Pacific Northwest drive concentrated demand for ISO 68 and ISO 100 synthetic formulations. The EPA's AIM Act phasedown mandates under Section 103 constrain refrigerant-lubricant pairings in new equipment categories. Port-centric cold storage developments in Georgia and Washington state accelerate bulk procurement of polyolester base stocks for ammonia-CO2 cascade systems.
Canada
Prairie grain terminals and Alberta meat processing facilities expand industrial refrigeration capacity requiring specialized additive packages. Federal halocarbon regulations administered by Environment and Climate Change Canada elevate performance thresholds for approved lubricant formulations. Transcritical CO2 installations in Ontario and Quebec food processing plants favor novel chemistries addressing copper plating in high-pressure circuits.
Mexico
Underpenetrated refrigerated warehousing in northern Mexico and last-mile logistics gaps in the Bajío Region present expansion opportunities for synthetic oil suppliers. The country's energy efficiency standards for commercial refrigeration equipment create compliance-driven formulation demand. Maquiladora-adjacent blending capacity in Nuevo León and Tijuana serves cross-border cold chain integration with U.S. distribution networks.
North America Refrigeration Oil Market Competitive Landscape
Top-tier vendors anchor formulation supply, while regional blenders and specialty distributors occupy service-intensive niches. The North America refrigeration oil sector exhibits moderate concentration with integrated petrochemical majors controlling base stock supply and independent compounders filling specification gaps. Strategic archetypes include integrated base oil producers, OEM-co-development specialists, and IoT-enabled service providers. Competitive moves center on backward integration into additive manufacturing and predictive maintenance contract capture.
Within the integrated petrochemical tier, Exxon Mobil Corporation and Chevron Corporation exemplify supply chain control through captive base oil production. Shell Global occupies a position as an OEM-co-development specialist with compressor manufacturer relationships. These three entities represent distinct competitive vectors: upstream raw material security, dense distribution reach, and equipment platform integration respectively.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| Shell Global |
| FUCHS |
| Calumet Specialty Products Partners |
| Johnson Controls |
| Cosmo Oil Lubricants Co., Ltd. |
| CAMCO Lubricants |
| Lubriplate Lubricants Company |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialty blenders in the U.S. Gulf Coast have consolidated fragmented regional production capacity, tightening supply discipline and anchoring price floors for polyolester base stocks. Their ownership structure prioritizes cash yield over market share expansion, insulating formulation margins from cyclical feedstock volatility while constraining spot-market liquidity for independent distributors.
Pricing Analysis
Capacity additions in Texas and Louisiana are reshaping price floors for synthetic alkylbenzene formulations as integrated refiners expand captive polyalphaolefin output. Three-tier pricing structure across premium, standard, and economy levels reflects AHRI 570 certification status and OEM co-qualification investment. Cost compression in mineral oil tiers is intensifying because reclaimed refrigerant shortages strand legacy system assets. Independent servicing contractors in secondary U.S. markets exhibit highest price sensitivity, while food processing clusters prioritize thermal stability specifications over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from compressor manufacturers, while technical distributors serve independent contractors through just-in-time inventory programs. Base stock production concentrates in the United States, Belgium, and South Korea, with Gulf Coast refiners supplying the majority of North American polyolester feedstock. Formulation draws from polyalphaolefin, alkylbenzene, and additive packages sourced through long-term offtake agreements. Single-source vulnerability in hurricane-exposed Gulf Coast refining creates supply interruption risk during peak storm seasons. Distribution runs through blender-owned technical distributors and third-party wholesalers with OEM certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America refrigeration oil market represents a late-cycle quality story as food processors specify premium synthetic formulations for ammonia-CO2 cascade compliance. Procurement is shifting toward subscription-based oil condition monitoring, decoupling hardware sales from recurring analytical service revenue.
For Market Incumbents: Anticipate margin compression from bio-based oil entrants targeting California and Washington state sustainability mandates. Defensive consolidation of additive manufacturing capabilities secures formulation cost control. Backward integration into base stock production in Texas and Louisiana insulates supply security against hurricane season disruptions. For New Entrants and Emerging Players: The price-point gap between premium OEM-qualified synthetics and economy mineral oils creates entry space for mid-tier alkylbenzene specialists. Mexican cold chain infrastructure in Nuevo León and Tijuana offers the most penetrable geography for maquiladora-adjacent blending capacity. Go-to-market positioning through compressor OEM co-development agreements bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders with stranded mineral oil exposure and limited synthetic formulation capabilities. Long-term viability over the coming decade favors blenders with integrated base stock supply and IoT-enabled service contract portfolios. The signal to watch is EPA Section 608 technician credentialing throughput as a leading indicator of aftermarket demand realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Production | Captive polyolester supply from Gulf Coast refiners reduces feedstock allocation risk during hurricane disruptions. |
| OEM Co-Development Agreements | Compressor manufacturer partnerships secure platform-specific lubricant qualifications ahead of AIM Act refrigerant deadlines. |
| Subscription Monitoring Services Launch | IoT-enabled oil condition analytics capture lifetime value through predictive maintenance contracts with grocery chains. |
| Maquiladora-Adjacent Blending Capacity | Nuevo León and Tijuana facilities serve cross-border cold chain integration with U.S. distribution networks. |
| Bio-Based Formulation Certification | California and Washington state sustainability mandates drive vegetable-derived ester demand in cold storage operations. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. The analysis combines structured interviews with lubricant blenders, compressor OEM procurement teams, cold chain operators, and independent servicing contractors with secondary validation. Secondary sources include EPA AIM Act regulatory filings, AHRI certification databases, U.S. customs trade data, and compressor manufacturer technical documentation. Bottom-up volume estimates from end-use application segments triangulate against top-down base stock production and trade flow analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models demand by product type, application segment, viscosity grade, and distribution channel, with cross-segment elasticity for refrigerant-lubricant pairing transitions. CAGRs derive from trend extrapolation of installed base evolution, retrofit cycle timing, and new equipment specification shifts. Forecast inputs include EPA Section 608 technician certification throughput and cold storage construction permits in the U.S. Southeast and Pacific Northwest.
Caveats apply where EPA refrigerant rulemaking amendments or ASHRAE safety standard revisions could materially shift the outlook for acceptable oil chemistries. Forecasts reflect assumptions regarding AIM Act compliance timelines and natural refrigerant adoption rates in food processing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Germany AC Motor Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
AC Motor Market
Industrial Motors
Power Stacker Market
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Gear Motor Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Spargers Market