
 Semiconductor Wafer Cleaning Equipment Market | 2026-2036
Semiconductor Wafer Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Wafer Cleaning Equipment Market Intelligence
The expansion of equipment-as-a-service (EaaS) models is fragmenting the traditional capital expenditure-heavy customer base. Established leaders like Lam Research Corporation leverage deep R&D pipelines to serve high-volume foundries with advanced single-wafer systems. SCREEN Holdings Co., Ltd. specializes in batch processing systems for memory production. Tokyo Electron Limited competes across a broad portfolio of single-wafer and batch solutions for various logic and memory applications.
Semiconductor wafer cleaning equipment comprises systems designed to remove particulate, metallic, and organic contaminants from silicon wafer surfaces during fabrication. These systems utilize wet or dry processes to achieve atomic-level cleanliness, which is critical for device yield and performance. Wet Cleaning Systems continue to dominate the market due to their effectiveness and established process recipes. Demand from Foundries for advanced Front-End Processing applications is the primary growth engine, especially for sub-10nm nodes.
Environmental regulations significantly influence equipment design and chemical consumption. Europe's REACH and RoHS directives restrict hazardous substances, while the US EPA scrutinizes chemicals used in some cleaning processes. These rules compel manufacturers to develop more sustainable solutions with lower water and chemical usage. Stakeholder decisions will hinge on balancing the capital cost of new equipment against the operational benefits of improved yield and regulatory compliance.
Market Dynamics
The industry-wide architectural shift to gate-all-around (GAA) transistors is the central force shaping the market. This transition fundamentally increases the number and complexity of cleaning steps required to achieve acceptable yields for sub-3nm logic chip manufacturing.
Growth Catalysts
- Advanced Node Transition:The migration to GAA and 3D NAND architectures necessitates more frequent and precise cleaning cycles to remove contaminants from complex, high-aspect-ratio structures, directly stimulating equipment demand.
- Foundry Investment:Concentrated capital expenditure by leading foundries in new fabrication clusters in Taiwan, South Korea, and the United States provides a direct pipeline for advanced single-wafer cleaning system orders.
- Compound Semiconductors:The adoption of silicon carbide (SiC) and gallium nitride (GaN) for power electronics and 5G RF devices opens new applications for specialized cleaning equipment designed to handle these fragile and chemically sensitive materials.
Market Restraints
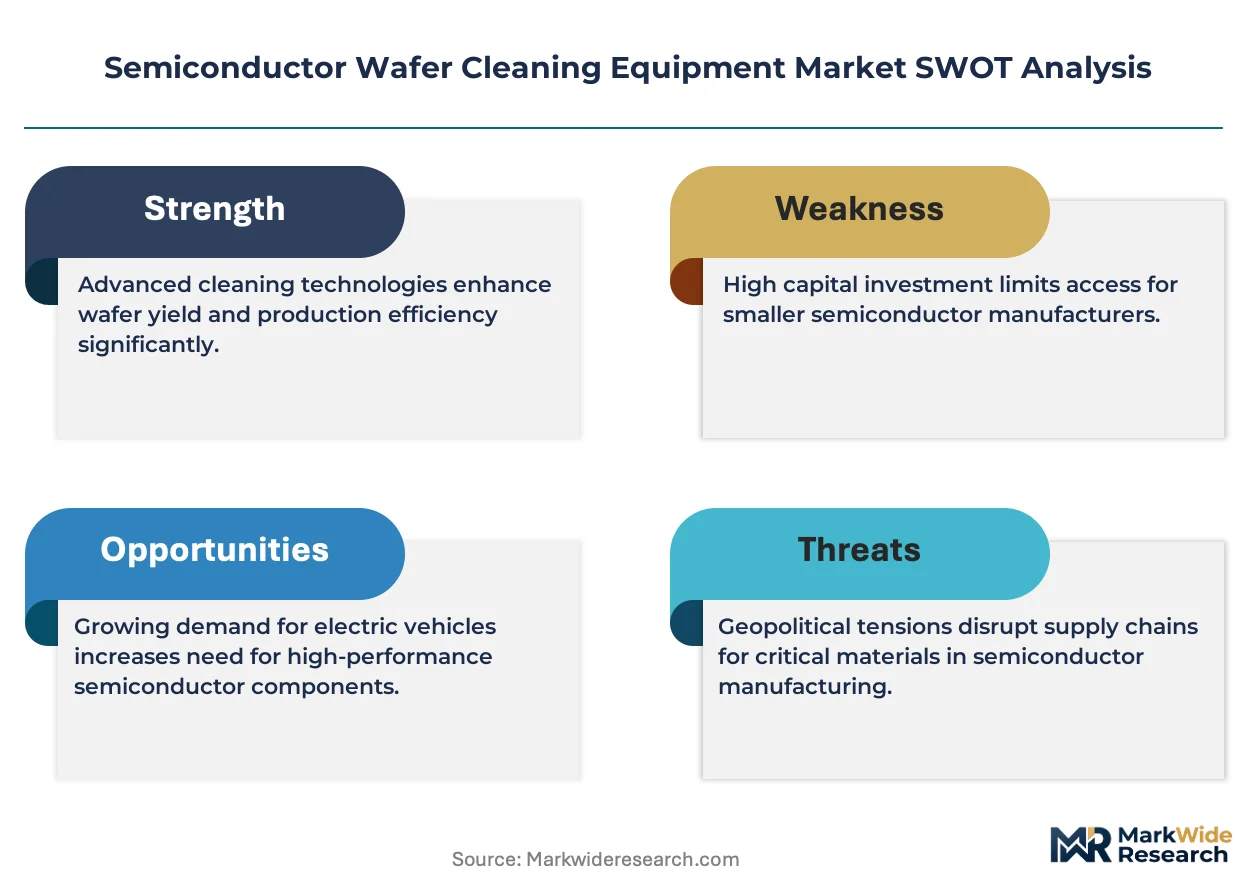
- High Capital Cost:The multi-million dollar price of advanced single-wafer cleaning systems for leading-edge nodes creates a significant barrier to entry for smaller fabs and integrated device manufacturers.
- Component Bottlenecks:Supply chain dependency on a limited number of vendors for high-purity quartzware, specialized valves, and advanced chemical delivery systems creates vulnerability to disruptions and price volatility.
- Technical Limitations:Existing cleaning processes struggle to effectively remove post-etch residues from new materials in advanced memory and logic devices without causing damage to delicate nanostructures, impacting device performance.
Strategic Opportunities
- Advanced Packaging Solutions:Developing cleaning technologies tailored for heterogeneous integration and chiplet-based designs presents a significant opportunity, as cleanliness between stacked dies is critical for reliability.
- Sustainable Technologies:Equipment designed with integrated chemical recycling and water reclamation systems can command a premium by helping fabs meet stringent environmental goals under frameworks like the EU Green Deal.
- Service-Based Models:The expansion of equipment-as-a-service (EaaS) offerings allows vendors to penetrate R&D labs and lower-volume fabs that cannot justify large capital outlays, creating new recurring revenue streams.
Industry Challenges
- Process Engineering Talent Scarcity:A shortage of engineers with deep expertise in plasma physics and advanced cleaning chemistries for sub-5nm process development hinders equipment optimization and new recipe qualification at customer sites.
- Chemical Regulation Compliance:Navigating the evolving restrictions on substances like certain fluorinated compounds under Europe's REACH and US EPA directives requires constant and costly reformulation of cleaning chemistries.
- Legacy System Integration:Ensuring new cleaning tools can seamlessly integrate with existing fab automation software and wafer handling systems without disrupting established manufacturing execution system (MES) protocols is a persistent challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Wafer Cleaning Equipment Market |
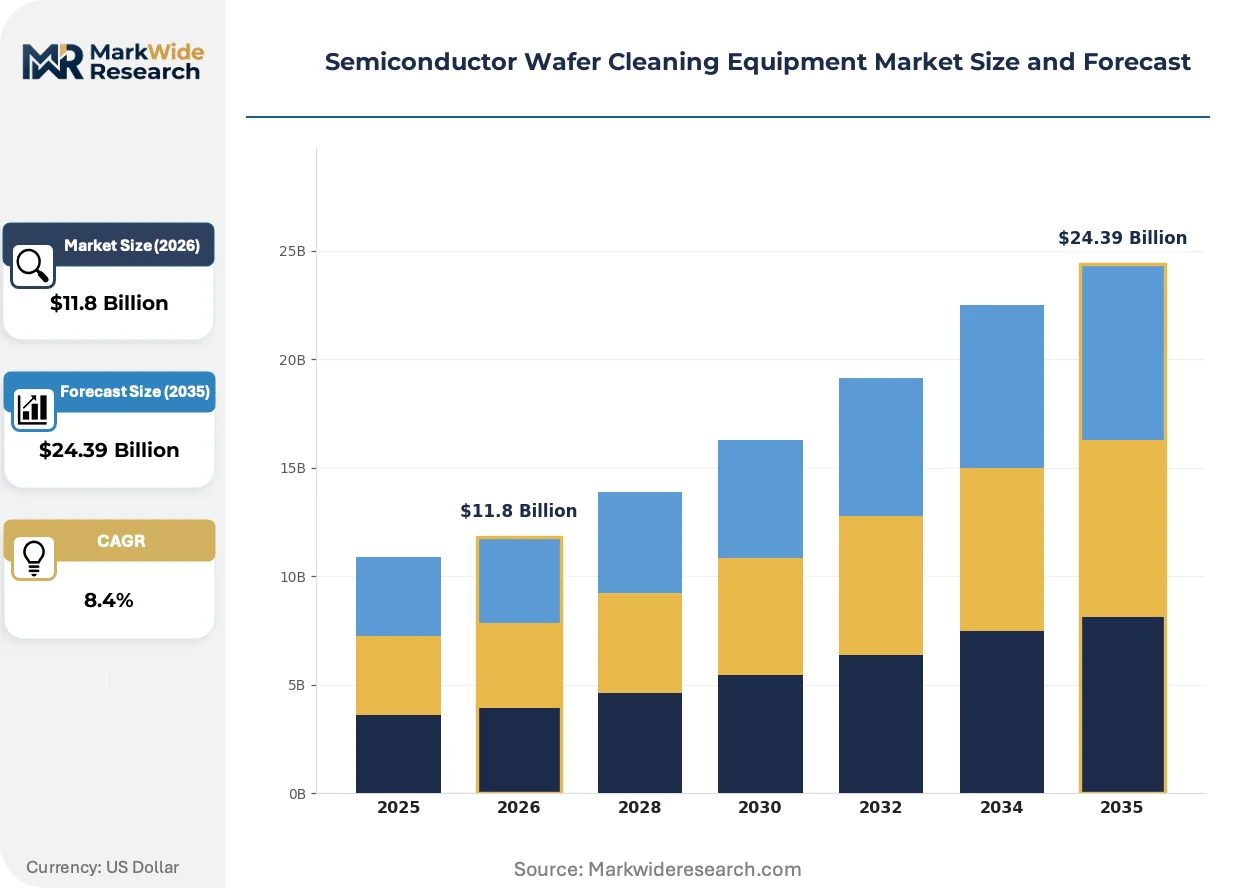
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Cleaning Systems, Dry Cleaning Systems, Plasma Cleaning Systems, Brush Scrubbers, Ultrasonic Cleaners Technology: Chemical Mechanical Planarization, Megasonic, Ozone-Based Cleaning, Vapor Phase, Laser Cleaning Application: Front-End Processing, Back-End Packaging, Photolithography Preparation, Defect Removal, Surface Preparation End User: Integrated Device Manufacturers, Foundries, OSAT Providers, Assembly Test Facilities, Backend Processors |
| Companies Covered | Applied Materials, Inc., Modutek Corporation, SCREEN Holdings Co., Ltd., AXUS Technology, Shibaura Mechatronics Corporation, Tokyo Electron Limited, ACM Research, Inc., SEMES, Lam Research Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Wafer Cleaning Equipment Market Strategic Shifts & Innovations
Innovation in the semiconductor wafer cleaning equipment market is driven by the dual pressures of enabling next-generation chip architectures and adhering to stricter environmental and chemical regulations. This forces advancements in both process control software and physical hardware design to improve efficiency and sustainability.
Digital twin technology is creating a complete virtual model of the physical cleaning chamber, its fluid dynamics, and chemical reactions. Leading-edge logic and memory foundries are adopting this for rapid process recipe development. This technology is virtualizing the expensive and time-consuming physical experimentation phase of process qualification, significantly reducing wafer and chemical waste while accelerating time-to-yield.
The US EPA’s ongoing scrutiny and proposed restrictions on per- and polyfluoroalkyl substances (PFAS) are impacting the industry. These chemicals are widely used in surfactants for wet cleaning processes and in components like seals and tubing. Consequently, equipment and chemical suppliers are accelerating R&D for PFAS-free alternatives to preempt regulatory mandates and ensure business continuity for North American fabs.
A move toward consumption-based procurement for specific cleaning modules is gaining momentum among certain fab operators. This model replaces the large, upfront capital expenditure with a recurring service fee that includes the equipment, consumables, and process support. This trend is most prominent in China and Europe, where mid-sized manufacturers use it to manage cash flow while accessing newer technologies.
Semiconductor Wafer Cleaning Equipment Market Segmentation
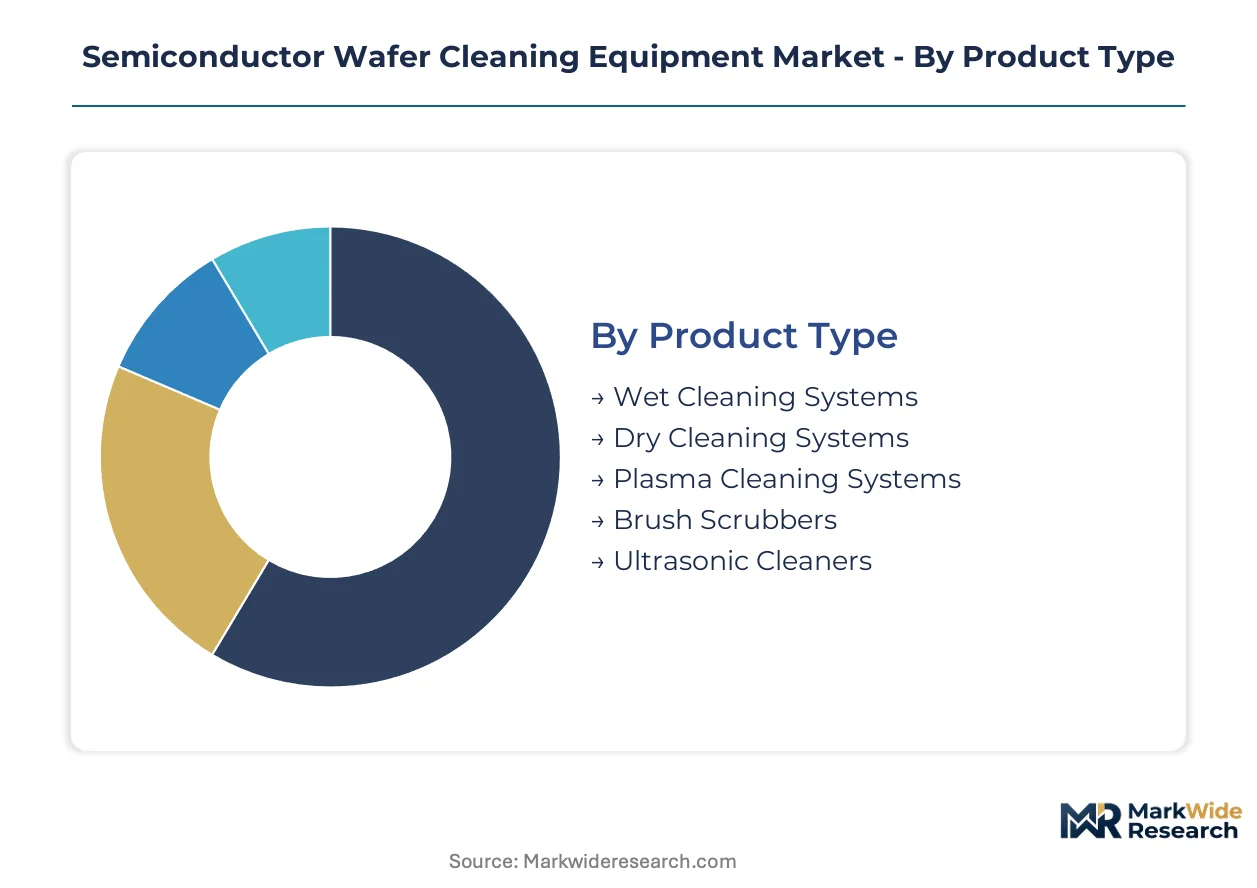
The semiconductor wafer cleaning equipment market segments reflect the diverse technological requirements and operational models across the microelectronics industry. Understanding these distinct segments is critical for equipment manufacturers to tailor their product development, service offerings, and strategic market penetration. Each category highlights specific challenges and opportunities within the complex wafer fabrication process.
Product Type:
The after-sales-service intensity varies significantly across product types, with complex single-wafer systems demanding extensive ongoing support, while more standardized batch systems require less frequent, but still specialized, maintenance. Equipment vendors often differentiate their service contracts based on the sophistication and uptime criticality of the installed cleaning solutions.
- Wet Cleaning Systems:These systems utilize chemical solutions and deionized water baths to remove contaminants, offering high effectiveness and established process recipes. Demand from leading foundries for sub-10nm logic manufacturing drives substantial investment in advanced wet cleaning platforms.
- Dry Cleaning Systems:Employing plasma, UV-ozone, or vapor-phase chemistries, these systems offer precise, damage-free cleaning for delicate structures and new materials. The transition to gate-all-around architectures and 3D NAND memory increases the need for sophisticated dry cleaning solutions.
- Plasma Cleaning Systems:These systems leverage ionized gases to remove organic residues and surface contaminants, particularly effective for post-etch cleaning. They provide a gentle cleaning action crucial for preserving fragile nanostructures.
- Brush Scrubbers:Mechanical scrubbing with brushes and deionized water physically removes larger particles from wafer surfaces. These are often used in less critical cleaning steps or for specific material types.
- Ultrasonic Cleaners:Utilizing high-frequency sound waves in a liquid medium, these systems dislodge particles from wafer surfaces. They find application in bulk cleaning and specific defect removal tasks.
Wet Cleaning Systems holds the largest share; momentum sits with Dry Cleaning Systems.
Technology:
The application focus of various cleaning technologies dictates their adoption rates and market relevance, with specific methods optimized for distinct contamination types or wafer process stages. Each technology addresses unique challenges in achieving atomic-level cleanliness for advanced semiconductor devices.
- Chemical Mechanical Planarization:This technology combines chemical etching with mechanical polishing to achieve highly planar wafer surfaces, critical for multi-layer device fabrication. It ensures uniform film thickness and reduces defects for subsequent lithography steps.
- Megasonic:Using high-frequency acoustic energy in a liquid bath, megasonic cleaning effectively removes sub-micron particles without causing damage to delicate structures. This method is essential for cleaning advanced node wafers with high aspect ratios.
- Ozone-Based Cleaning:This technology leverages ozone gas to oxidize and remove organic contaminants from wafer surfaces, offering a residue-free cleaning process. It is increasingly adopted for its environmental benefits and efficacy in specific applications.
- Vapor Phase:Utilizing chemical vapors, this method provides highly conformal cleaning for complex 3D structures. It minimizes liquid-induced damage and is suitable for sensitive materials.
- Laser Cleaning:Employing pulsed lasers, this technique ablates or desorbs contaminants from wafer surfaces. It offers precise, localized cleaning for specific defect removal.
Demand for Megasonic drives significant market activity, while Chemical Mechanical Planarization shows promising expansion.
Application:
Customer type influences the demand for specific cleaning applications, with foundries and integrated device manufacturers requiring comprehensive solutions across the entire fabrication workflow. The diverse needs of these end-users drive innovation in specialized cleaning processes for different stages of chip manufacturing.
- Front-End Processing:This category encompasses critical cleaning steps performed during transistor formation and interconnect patterning on the wafer. It is the primary growth engine due to the stringent cleanliness requirements of sub-10nm nodes.
- Back-End Packaging:Cleaning processes here prepare dies for packaging, including removing residues from dicing and ensuring clean surfaces for bonding. The rise of heterogeneous integration and chiplet designs increases the complexity and importance of these steps.
- Photolithography Preparation:Cleaning prior to lithography ensures defect-free resist coating and pattern transfer. This application is crucial for maintaining pattern fidelity at advanced nodes.
- Defect Removal:Specialized cleaning methods target specific particle, metallic, or organic defects that arise during various process steps. Effective defect removal directly impacts device yield.
- Surface Preparation:This involves pre-cleaning wafers before deposition or etching to ensure optimal surface conditions. It is fundamental for achieving good film adhesion and process control.
Front-End Processing commands the largest share, with Back-End Packaging experiencing rapid adoption.
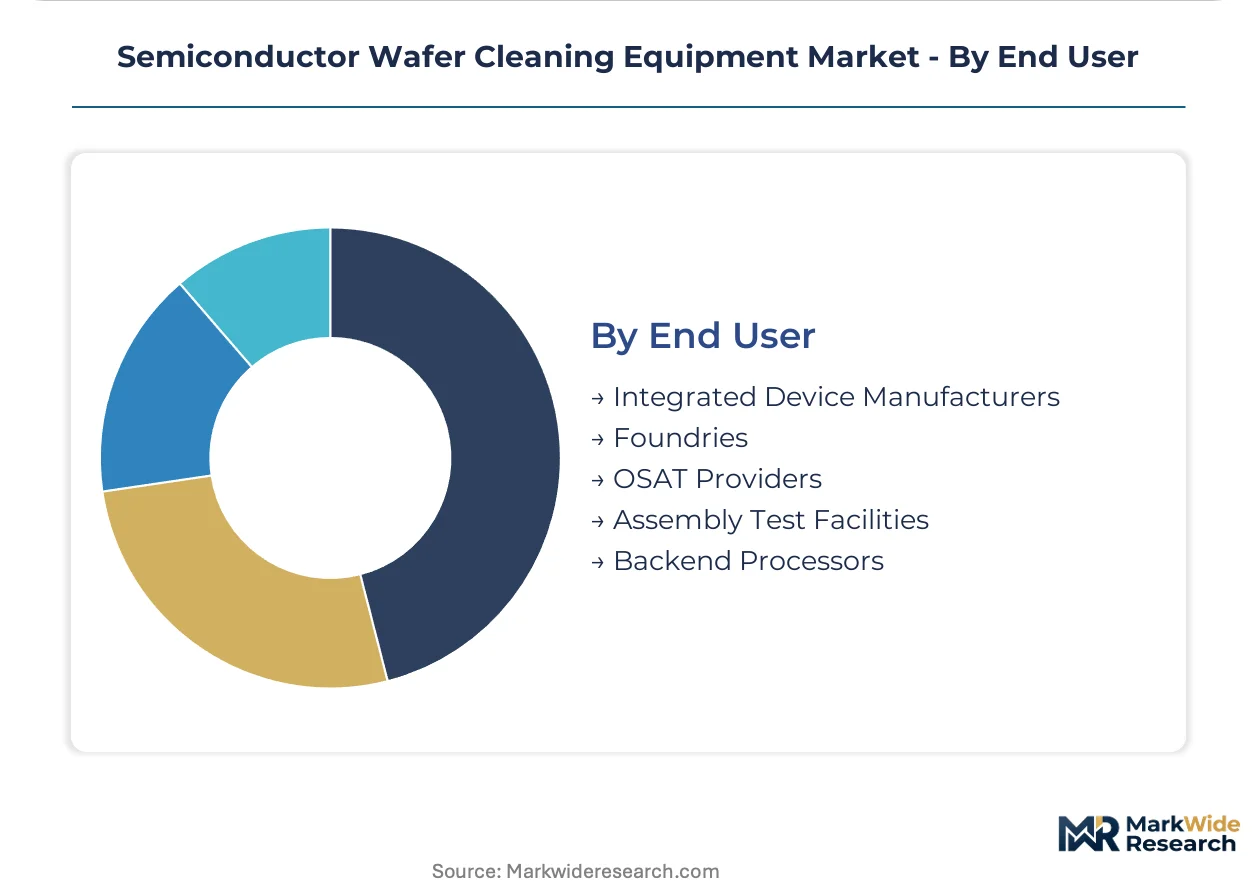
End User:
The volume and yield requirements of different end-users significantly shape their investment in wafer cleaning equipment, with high-volume foundries demanding the most advanced and reliable systems. Each end-user segment has distinct operational priorities and capital expenditure strategies.
- Integrated Device Manufacturers:These companies design, manufacture, and sell their own semiconductor products, requiring cleaning equipment across their entire vertically integrated fabrication lines. They invest in a broad range of cleaning solutions for diverse product portfolios.
- Foundries:Foundries specialize in manufacturing chips for other companies, operating at the leading edge of technology and high volume. Their demand for advanced single-wafer cleaning systems is a primary market driver, especially for sub-3nm logic processes.
- OSAT Providers:Outsourced Semiconductor Assembly and Test providers handle back-end processes like packaging and testing. They require cleaning equipment for post-dicing and pre-assembly steps.
- Assembly Test Facilities:These facilities focus on the final stages of chip production, including cleaning before and after assembly. Their equipment needs are tailored to packaging materials and processes.
- Backend Processors:This segment includes companies involved in various post-fabrication processes, such as thinning and polishing. They require cleaning solutions to prepare wafers for subsequent packaging.
Investment from Foundries remains substantial, as Integrated Device Manufacturers expands its operational footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global semiconductor wafer cleaning equipment market balances its reliance on key manufacturing hubs for both supply and demand. Advanced chip production, particularly for sub-10nm nodes, drives significant investment in specialized cleaning systems. This creates a complex interplay of technology transfer and localized manufacturing capabilities across major semiconductor regions.
United States
Foundry investments and advanced node development for logic chips primarily drive demand for sophisticated cleaning equipment. The US EPA's ongoing scrutiny of per- and polyfluoroalkyl substances (PFAS) compels manufacturers to develop sustainable chemical alternatives. Clusters in Arizona and New York are expanding with new fabs from Intel and GlobalFoundries, requiring extensive cleaning infrastructure.
South Korea
Memory production, including 3D NAND, and advanced logic manufacturing fuel the need for high-throughput wafer cleaning systems. The government actively supports the domestic semiconductor industry through various incentive programs and R&D initiatives. Major fabrication facilities in Gyeonggi Province, home to Samsung and SK Hynix, are continuous adopters of new cleaning technologies.
Taiwan
Leading-edge foundry expansion, particularly for gate-all-around (GAA) architectures, necessitates continuous upgrades in cleaning technology. The Taiwanese government provides substantial incentives to maintain its global leadership in semiconductor manufacturing. The Hsinchu Science Park remains a critical hub for TSMC and UMC, driving demand for advanced single-wafer cleaning systems.
China
The national drive for domestic chip production and the growth of mid-sized fabs adopting equipment-as-a-service models contribute to market expansion. The Ministry of Industry and Information Technology (MIIT) implements policies to bolster the local semiconductor supply chain. Numerous fabrication facilities across the Yangtze River Delta are increasing their cleaning equipment procurement.
Japan
Specialized material production and equipment innovation for next-generation devices sustain demand for advanced cleaning solutions. The Ministry of Economy, Trade and Industry (METI) promotes initiatives to strengthen Japan's semiconductor equipment ecosystem. The Kumamoto region is emerging as a new center for advanced manufacturing, including a TSMC fab, fostering equipment ecosystem growth.
Semiconductor Wafer Cleaning Equipment Market Key Industry Players
Platform integrators command the system tier, offering comprehensive cleaning solutions, while component specialists sit upstream providing critical subsystems and chemistries. The market structure is tiered, with established leaders focusing on high-volume foundries and niche players addressing specific material or process challenges. Strategic partnerships and continuous R&D investment are dominant competitive moves.
Within the established leader tier, Lam Research Corporation focuses its deep R&D pipelines on serving high-volume foundries with advanced single-wafer systems. SCREEN Holdings Co., Ltd. exemplifies specialization, offering batch processing systems primarily for memory production. Tokyo Electron Limited occupies a position with a broad portfolio, providing both single-wafer and batch solutions across logic and memory applications.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| Modutek Corporation |
| SCREEN Holdings Co., Ltd. |
| AXUS Technology |
| Shibaura Mechatronics Corporation |
| Tokyo Electron Limited |
| ACM Research, Inc. |
| SEMES |
| Lam Research Corporation |
| Others |
Cost & Logistics Intelligence
Hsinchu Science Park's concentrated manufacturing capacity directly influences pricing power for advanced single-wafer cleaning systems, reflecting the high capital intensity of leading-edge semiconductor fabrication.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure, blending project-based contracts for new fab installations with recurring service fees for ongoing maintenance. Price differentiation stems from the customization level required for specific chip architectures and the criticality of after-sales service for uptime. Pricing softness reflects intense competition among equipment vendors and the high capital cost for advanced systems. Smaller fabs and R&D labs are most price-sensitive, often opting for EaaS models, while leading foundries prioritize performance and uptime.
Supply Chain Analysis
The global supply of high-purity quartzware and specialized valves, critical inputs for advanced cleaning systems, concentrates heavily in Japan and Germany. Advanced chemical delivery systems also draw from specialized manufacturers in the United States. Single-source vulnerability for niche components creates potential for disruptions and price volatility. Distribution runs through a direct sales model, with equipment vendors providing direct installation and support to fabs worldwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor wafer cleaning market represents a high-growth disruption, driven by the architectural shift to gate-all-around (GAA) transistors.
For Market Incumbents: Build intellectual property moats around advanced process control software and next-generation chemical formulations. Forge strategic partnerships with leading foundries to co-develop solutions for sub-3nm nodes, mitigating threats from emerging regional competitors. Continuous R&D investment in damage-free cleaning chemistries remains a critical lever for maintaining market share.
For New Entrants and Emerging Players: China's mid-sized fab ecosystem presents significant underpenetration for specialized cleaning modules. Target advanced packaging solutions, where cleanliness between stacked dies is critical for reliability. Offer flexible equipment-as-a-service (EaaS) contracts bundled with process support to capture lower-volume fabs seeking consumption-based procurement models.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure play because semiconductor cleaning is indispensable for advanced chip manufacturing. Identify niche component suppliers with proprietary materials or software firms specializing in process optimization as attractive acquisition targets. Quarterly review of foundry capital expenditure announcements and regulatory updates is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D Investment in PFAS-Free Chemistries | Ensures compliance with evolving environmental regulations and secures market access in North America. |
| Strategic Partnerships with Foundries | Accelerates co-development of cleaning solutions for next-generation GAA and 3D NAND architectures. |
| Geographic Expansion into Emerging Fab Clusters | Establishes local support infrastructure and sales channels in growing regions like the US and Japan. |
| Component Supply Chain Diversification | Mitigates single-source vulnerability for critical high-purity quartzware and specialized valve components. |
| EaaS Model Deployment for Mid-Volume Fabs | Captures recurring revenue streams and penetrates smaller fab segments unable to afford large capital outlays. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. This involved extensive discussions with foundry process engineers, equipment R&D directors, chemical suppliers, and fab procurement managers. Secondary data was sourced from company annual reports, semiconductor industry association data, government technology roadmaps, and academic research papers. This approach ensures comprehensive data collection and robust bottom-up and top-down triangulation.
The calibration approach involved segmenting the market by product type, technology, application, and end-user, alongside regional adoption patterns. Compound annual growth rates were derived by analyzing historical trends and future demand projections across the analysis window. Key industry-specific forecast inputs included wafer starts at advanced nodes and capital expenditure plans of leading foundries over the projection horizon.
Practitioners should monitor shifts in global trade policies and the pace of new fab construction for early signals of market recalibration. Forecasts reflect assumptions regarding technological advancements and regulatory stability, which are subject to change. Quarterly review of foundry capex announcements and regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
United States Chip Mounter Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Global Semiconductor Photolithography Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market