
 Wafer Chucks Market | 2026-2036
Wafer Chucks Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer Chucks Market Insights
Multi-source procurement for ceramic substrates is hardening among tier-one equipment OEMs. Applied Materials leverages backward integration into alumina ceramic supply chains to secure chuck blank availability. KYOCERA Corporation anchors Japanese domestic production with vertically integrated fine-ceramic capabilities. CoorsTek competes through North American sintering capacity and specialized purity grades for plasma etch environments.
Wafer chucks are precision workholding devices that secure semiconductor wafers during lithography, etch, deposition, and inspection processes through electrostatic, vacuum, or mechanical clamping forces, typically machined from aluminum oxide or aluminum nitride ceramics with flatness tolerances below one micron. Electrostatic chucks dominate value capture due to their indispensability in sub-7nm lithography and plasma processing steps where vacuum or mechanical clamping introduces particle defects. Ceramic material formulations command the highest margin pools because alumina nitride's thermal conductivity requirements resist substitution by lower-cost alternatives, while polymer chucks gain traction in temporary bonding and deburring applications for MEMS wafer-level packaging.
FDA device regulations and EPA emissions frameworks indirectly shape chuck demand through their impact on domestic semiconductor equipment certification requirements, while China's MIIT enforces GB standards on ceramic material traceability that affect import qualification timelines. The EU's REACH and RoHS restrictions on heavy metal content in ceramic dopants constrain formulation flexibility for suppliers serving European fab tool builders. Stakeholders must monitor divergence between national semiconductor subsidy programs and their local content requirements for wafer handling subsystems.
Market Dynamics
Electrostatic chuck procurement is concentrating among Taiwan's Hsinchu Science Park foundries as sub-7nm lithography ramps strain ceramic substrate supply chains. Equipment OEMs now compete primarily on alumina nitride purity grades and thermal conductivity specifications rather than price.
Growth Catalysts
- Advanced node lithography:Sub-7nm patterning requirements mandate electrostatic clamping to eliminate particle defects from mechanical contact. Taiwan's foundry expansion drives volume procurement.
- MIIT dual carbon mandates:China's GB standards on ceramic material traceability and energy efficiency are accelerating domestic electrostatic chuck qualification for import substitution.
- Plasma etch intensity:High-aspect-ratio memory architectures extend chuck exposure to corrosive chemistries, shortening replacement cycles and expanding aftermarket demand.
Market Restraints
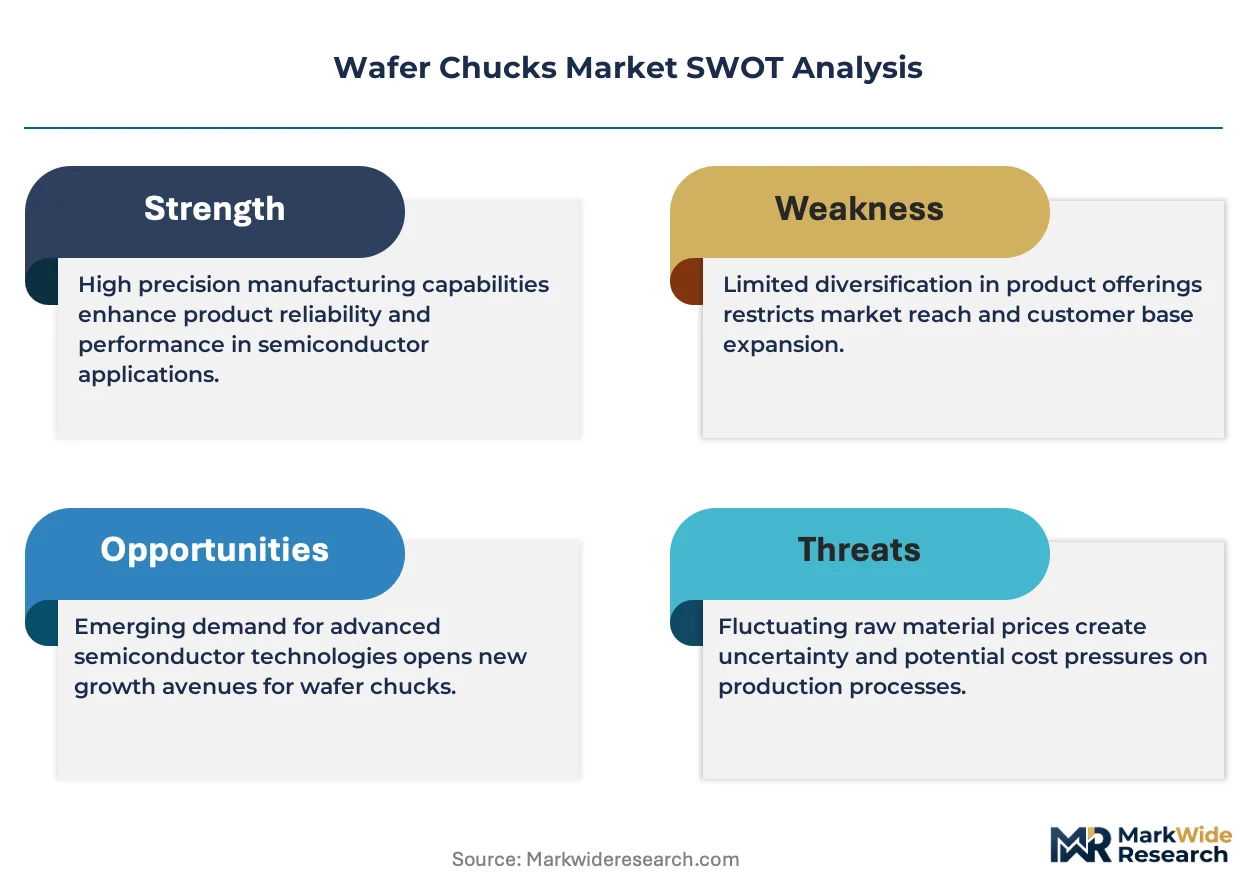
- Alumina nitride supply concentration:Sintering-grade powder production clusters in Japanese and Chinese suppliers, exposing OEMs to export control volatility and input cost spikes.
- REACH RoHS formulation constraints:EU heavy metal restrictions on ceramic dopants limit thermal conductivity optimization, forcing European tool builders to accept performance trade-offs or source from non-EU qualified suppliers.
- Polymer chuck substitution:Temporary bonding applications for MEMS wafer-level packaging increasingly adopt polymer chucks for cost-sensitive deburring steps, compressing ceramic chuck addressable market in packaging segments.
Strategic Opportunities
- India semiconductor manufacturing:PLI scheme subsidies for domestic fab construction create first-mover advantage for chuck suppliers establishing local calibration and refurbishment capabilities.
- Silicon carbide power device fabrication:Wide-bandgap wafer processing requires specialized thermal management profiles, opening premium pricing tiers for customized electrostatic chuck architectures.
- Equipment-as-a-service models:Foundry capex constraints favor chuck leasing arrangements with predictive maintenance telemetry, shifting revenue from unit sales to recurring service contracts.
Industry Challenges
- Ceramic metallization expertise scarcity:Plasma-sprayed electrode deposition requires rare combinations of materials science and vacuum process engineering, constraining qualified supplier expansion.
- Multi-standard certification timelines:Simultaneous qualification against SEMI standards, customer-specific particle protocols, and national safety regulations extends new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer Chucks Market |
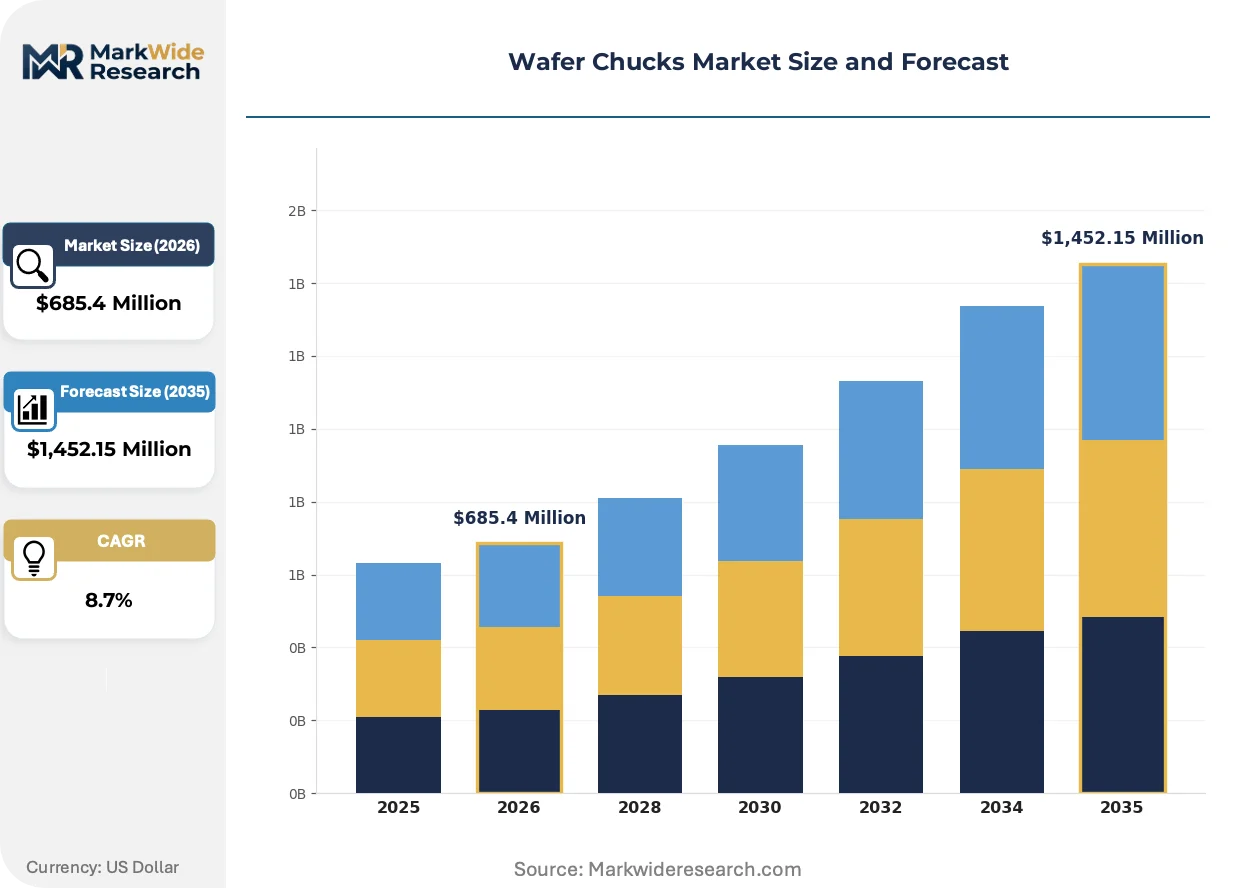
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrostatic Chucks, Vacuum Chucks, Mechanical Chucks, Hybrid Chucks Material: Ceramic, Silicon, Metal, Polymer End User: Semiconductor Fabrication, MEMS, Photonics, Solar Cells Technology: Dielectric, Adhesive, Magnetic, Electrostatic |
| Companies Covered | Applied Materials, Lam Research, SHINKO Electric Industries, TOTO Ltd., KYOCERA Corporation, Entegris, NGK Insulators, CoorsTek, Creative Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer Chucks Market Trends and Innovations
Wafer chuck architecture is fragmenting across thermal performance tiers as process diversity multiplies. Equipment builders now specify distinct ceramic formulations for logic, memory, and power device applications rather than deploying universal platforms.
Monolithic aluminum nitride electrostatic chucks with embedded tungsten electrode networks are decentralizing thermal management from external chiller systems to the wafer interface itself. Memory foundries in Taiwan's Hsinchu cluster are adopting these designs for high-aspect-ratio etch steps. The shift is compressing peripheral equipment footprints and reducing facility-level cooling capital.
REACH Annex XVII restrictions on boron compounds are forcing reformulation of alumina ceramic dopants used in plasma-facing chuck surfaces. European tool builders must now qualify alternative thermal conductivity enhancers or source from non-EU ceramic suppliers with divergent purity certifications. The regulatory friction is lengthening procurement cycles for EU-bound equipment by four to six months.
Consignment inventory arrangements are displacing traditional purchase-order relationships between foundries and chuck suppliers. Taiwan's leading foundries now require suppliers to maintain buffer stock at fab-adjacent logistics hubs, transferring working capital burden upstream. The model is most pronounced in Hsinchu and Taichung Science Park clusters where just-in-time delivery penalties are severe.
Wafer Chucks Market Segmentation
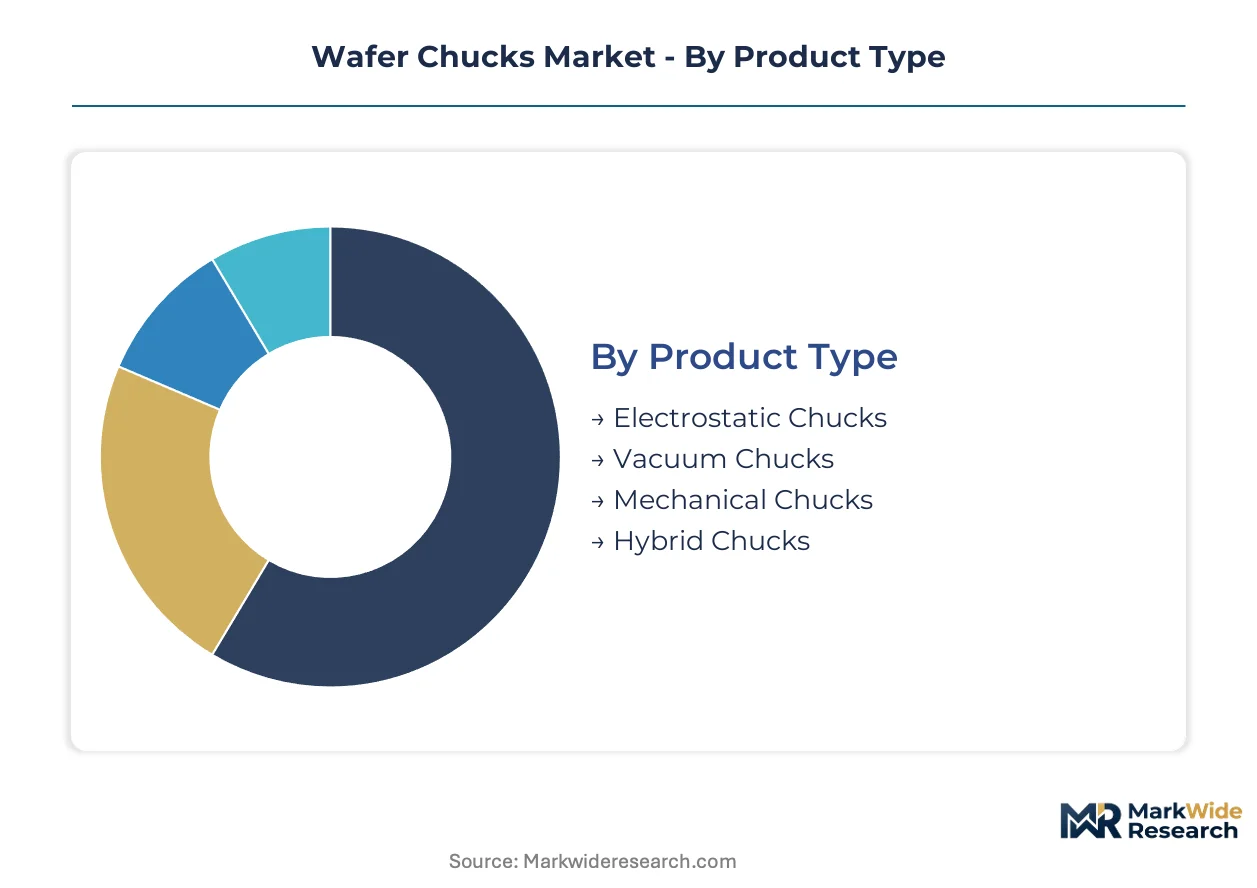
Wafer chuck segmentation reflects the tension between process precision requirements and cost optimization across semiconductor manufacturing tiers. Equipment OEMs now specify distinct architectures for lithography, etch, and packaging applications rather than deploying universal platforms.
Product Type:
Clamping mechanism selection pivots on thermal budget constraints and particle contamination thresholds at each process node.
- Electrostatic Chucks:Monolithic aluminum nitride bodies with embedded tungsten electrode networks dominate sub-7nm lithography and high-aspect-ratio plasma etch. Taiwan's Hsinchu Science Park foundries drive procurement concentration as advanced node capacity expands.
- Vacuum Chucks:Porous ceramic or metal plates with perimeter vacuum seals serve inspection and metrology applications where electrostatic fields interfere with sensitive measurements. Demand clusters in back-end-of-line wafer-level packaging facilities.
- Mechanical Chucks:Edge-grip or pin-support designs persist in solar cell manufacturing and legacy node fabrication where particle generation from mechanical contact remains acceptable.
- Hybrid Chucks:Dual-mode electrostatic-vacuum configurations address compound semiconductor processing where wafer bow from thermal mismatch requires adaptive clamping force distribution.
Mature deployment sits with mechanical chucks in cost-sensitive solar and legacy applications. Newer deployment is concentrated in electrostatic architectures for EUV lithography and advanced memory etch.
Material:
Substrate composition determines thermal conductivity ceilings, plasma corrosion resistance, and electrode integration feasibility.
- Ceramic:Aluminum oxide and aluminum nitride formulations command premium positioning due to plasma durability and dielectric properties required for electrostatic clamping. Sintering-grade powder supply concentrates in Japanese and Chinese suppliers.
- Silicon:Monocrystalline or polycrystalline silicon chucks serve specialized epitaxy applications where thermal expansion matching with processed wafers reduces stress-induced defect formation.
- Metal:Anodized aluminum or stainless steel substrates dominate vacuum chuck construction for inspection equipment where weight and machinability outweigh ceramic performance advantages.
- Polymer:Polyimide and PEEK formulations gain traction in temporary bonding and deburring steps for MEMS wafer-level packaging, compressing ceramic addressable market in cost-sensitive packaging segments.
Ceramic materials anchor high-value electrostatic applications. Polymer alternatives are expanding most quickly in advanced packaging workflows.
End User:
Process complexity and wafer value dictate chuck specification tiers across manufacturing verticals.
- Semiconductor Fabrication:Logic and memory foundries specify electrostatic chucks with sub-micron flatness tolerances for lithography and plasma etch. China's MIIT dual carbon mandates accelerate domestic qualification for import substitution.
- MEMS:Micro-electromechanical systems manufacturing employs polymer and hybrid chucks for temporary bonding during wafer thinning and deburring operations.
- Photonics:Indium phosphide and gallium arsenide wafer processing requires specialized thermal management profiles for compound semiconductor electrostatic chucks.
- Solar Cells:Crystalline silicon photovoltaic manufacturing utilizes mechanical and vacuum chucks at lower specification tiers given wafer thickness and cost sensitivity.
Semiconductor fabrication commands the steepest specification escalation. Solar cell applications remain anchored to mature mechanical designs.
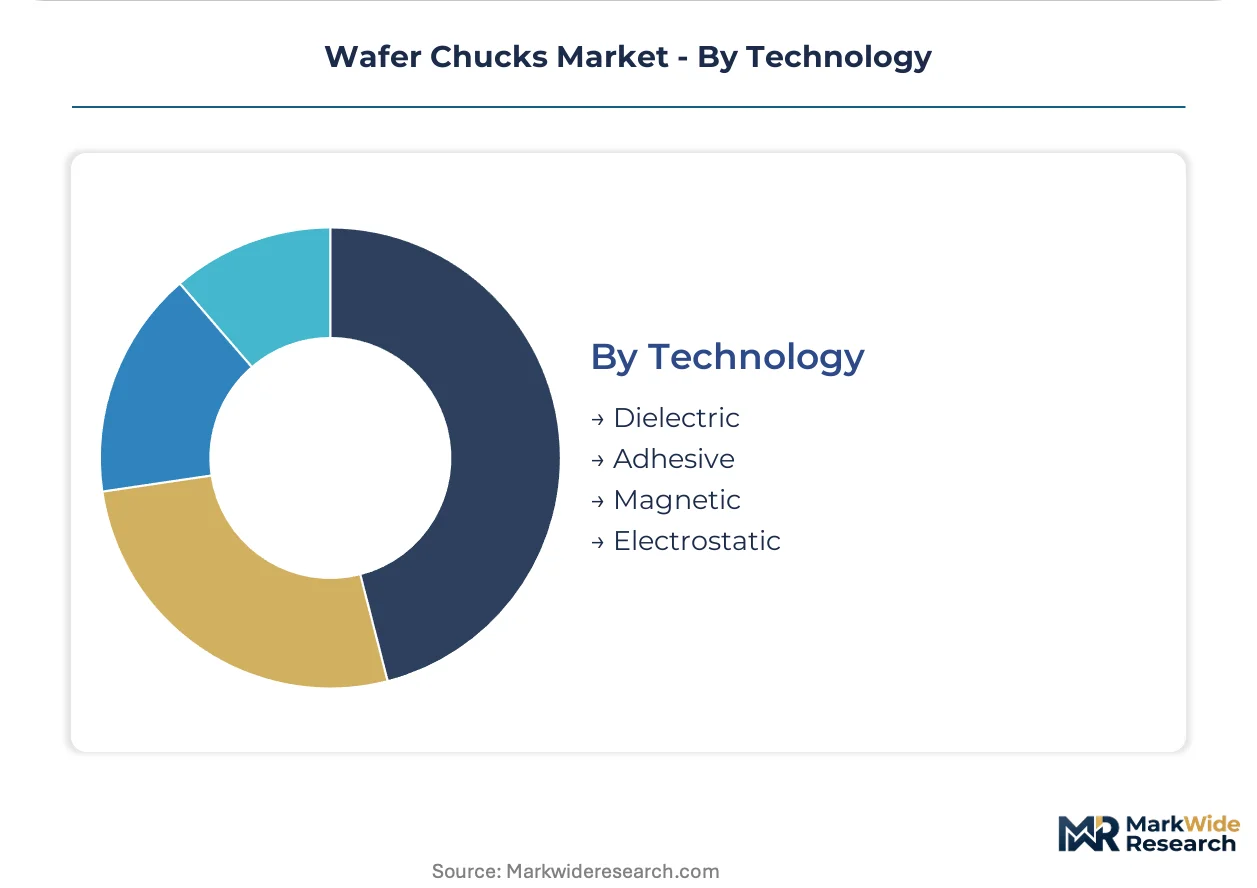
Technology:
Force generation mechanism selection balances clamping uniformity, thermal transfer efficiency, and process chemistry compatibility.
- Dielectric:Johnsen-Rahbek effect chucks with bulk resistivity control dominate plasma etch applications where uniform thermal contact prevents wafer temperature drift.
- Adhesive:Thermoplastic or UV-release adhesives enable temporary bonding for wafer-level packaging and 3D integration processes.
- Magnetic:Rare-earth magnetic clamping serves specialized steel wafer processing in magnetic memory and sensor applications.
- Electrostatic:Coulombic force generation through embedded electrode arrays provides non-contact clamping essential for particle-sensitive lithography steps.
Electrostatic technology anchors advanced node manufacturing. Dielectric variants retain positioning in high-power plasma etch environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park foundries concentrate electrostatic chuck procurement for sub-7nm lithography ramps. Equipment OEMs face ceramic substrate supply chain strain as advanced node capacity scales across multiple geographies.
Taiwan
TSMC and United Microelectronics drive electrostatic chuck volume procurement for EUV lithography and high-aspect-ratio plasma etch. The National Development Council's semiconductor advancement initiatives reinforce foundry capital expenditure on precision wafer handling equipment. Hsinchu Science Park anchors demand concentration where consignment inventory arrangements now dominate supplier relationships.
China
Domestic fab construction under the 14th Five-Year Plan accelerates electrostatic chuck qualification for import substitution targets. MIIT dual carbon mandates and GB standards on ceramic material traceability tighten energy efficiency requirements for substrate suppliers. Yangtze River Delta clusters in Shanghai and Suzhou house emerging domestic chuck calibration capabilities.
Japan
Sintering-grade alumina nitride powder production concentrates among Japanese suppliers serving global equipment OEMs. METI's semiconductor supply chain resilience programs support domestic ceramic substrate capacity expansion. Kyushu and Chubu industrial corridors maintain vertically integrated fine-ceramic manufacturing for plasma etch chuck applications.
United States
CHIPS Act subsidies drive domestic fab construction requiring electrostatic chuck procurement for advanced logic manufacturing. EPA emissions frameworks and FDA device regulations shape equipment certification requirements for domestic tool builders. Arizona and Texas fab projects create demand clusters for chuck refurbishment and calibration services.
South Korea
Samsung and SK Hynix memory foundries expand electrostatic chuck deployment for 3D NAND high-aspect-ratio etch steps. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative supports domestic supply chain localization. Pyeongtaek and Yongin semiconductor complexes concentrate demand for thermal management-optimized chuck architectures.
Wafer Chucks Market Competitive Landscape
Backward integration into ceramic substrate supply chains dominates the current landscape as equipment OEMs secure chuck blank availability. The vendor base stratifies across three tiers: integrated equipment builders with captive ceramic capabilities, specialized ceramic component suppliers, and regional fabrication specialists. Two archetypes define positioning: vertically integrated precision ceramic houses and equipment-anchored subsystem suppliers. Competitive moves center on alumina nitride purity grade differentiation and multi-source procurement hardening against supply concentration risk.
Among Japanese ceramic specialists, KYOCERA Corporation and SHINKO Electric Industries occupy positions within the vertically integrated tier, leveraging domestic fine-ceramic production networks. Applied Materials represents the equipment-anchored archetype through backward integration into alumina ceramic supply chains. CoorsTek anchors North American positioning through regional sintering capacity and specialized purity grades.
| Leading Market Players |
|---|
| Applied Materials |
| Lam Research |
| SHINKO Electric Industries |
| TOTO Ltd. |
| KYOCERA Corporation |
| Entegris |
| NGK Insulators |
| CoorsTek |
| Creative Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
Sintering-grade alumina nitride powder spot indices cascade through electrostatic chuck manufacturing into three distinct pricing tiers, with Taiwan's Hsinchu foundries absorbing premium markups for sub-7nm lithography specifications while packaging applications face cost compression from polymer substitutes.
Pricing Analysis
Volume procurement concentrates in standard-grade electrostatic chucks for memory foundries, while margin capture clusters in customized aluminum nitride architectures for EUV lithography. Price differentiation hinges on ceramic purity certification tiers and thermal conductivity specifications rather than brand positioning. Pricing pressure stems from consignment inventory arrangements transferring working capital burdens upstream to suppliers. MEMS packaging buyers exhibit highest price sensitivity as polymer chuck alternatives expand, whereas logic foundries prioritize performance over unit cost.
Supply Chain Analysis
China's MIIT domestic-content mandates and India's PLI scheme local sourcing requirements are reshaping procurement patterns for ceramic substrate qualification. Sintering-grade powder production concentrates in Japan and China, with Japanese suppliers anchoring high-purity grades for plasma etch applications. Raw material dependencies rest on tungsten electrode networks, boron-doped alumina formulations, and specialized metallization chemistries. Single-source vulnerability persists in plasma-sprayed electrode deposition expertise. Distribution runs through fab-adjacent logistics hubs under consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sintering-grade alumina nitride powder capacity constraints prop pricing premiums for electrostatic chuck suppliers, with qualified ceramic metallization expertise scarcity preventing rapid supply expansion.
For Market Incumbents: Hedge against REACH Annex XVII reformulation costs by qualifying non-EU ceramic suppliers with divergent purity certifications. Deepen backward integration into boron-free dopant supply chains before EU restrictions tighten. Secure multi-source procurement agreements with Japanese and Chinese powder producers to mitigate export control volatility. For New Entrants and Emerging Players: Launch via equipment-as-a-service leasing models targeting India's PLI-subsidized fab construction, where calibration and refurbishment capabilities remain underdeveloped. Focus on silicon carbide power device applications requiring specialized thermal management profiles, as this segment lacks entrenched supplier relationships. Pursue joint qualification programs with domestic tool builders in Yangtze River Delta clusters. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated ceramic houses with captive sintering capacity in Japan's Kyushu corridor, where METI resilience programs support capacity expansion. Long-term viability hinges on electrode deposition expertise scarcity resolving over the next decade. Monitor MIIT import substitution qualification timelines as inflection signals for domestic Chinese supplier market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Applied Materials and KYOCERA secure chuck blank availability against alumina nitride supply concentration. |
| Domestic Qualification for Import Substitution | China's MIIT GB standards accelerate local electrostatic chuck certification timelines in Yangtze River Delta. |
| Equipment-as-a-Service Deployment | Leasing models with predictive maintenance telemetry shift revenue from unit sales to recurring contracts. |
| Non-EU Supplier Qualification | REACH Annex XVII boron restrictions force European tool builders to source from alternative ceramic suppliers. |
| Silicon Carbide Thermal Architecture Development | Wide-bandgap wafer processing opens premium pricing tiers for customized electrostatic chuck designs. |
Research Methodology
Multi-period observation of foundry capital expenditure patterns, ceramic powder trade flows, and electrostatic chuck procurement volumes anchored the trend analysis, supplemented by interviews with semiconductor equipment procurement directors, ceramic substrate plant managers, plasma etch process engineers, and fab logistics coordinators. Secondary validation drew from SEMI equipment market data, MIIT GB standard filings, Japanese customs trade statistics, and EPA emissions framework updates. Bottom-up segment sizing triangulated against top-down fab capacity expansion models.
Segment-weighting across clamping mechanism types, ceramic material formulations, end-user verticals, and regional regulatory clusters structured the analytical framework over the projection horizon. CAGRs derived from installed base replacement cycle analysis and advanced node lithography ramp schedules. Forecast inputs incorporated REACH reformulation timelines and India's PLI scheme disbursement trajectories.
Export control volatility, REACH Annex XVII enforcement timing, and polymer chuck substitution rates in MEMS packaging are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on sintering-grade powder supply expansion and domestic qualification success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Tape on Reel Feeder Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Wafer Processing Equipment Market