
 Global Soldering Equipment Market | 2026-2036
Global Soldering Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soldering Equipment Market Intelligence
Consolidation among large-scale contract assembly services is rebalancing purchasing power away from smaller, independent electronics manufacturers. Kurtz Ersa leverages its extensive portfolio of wave and reflow systems to serve these high-volume accounts. JUKI Automation competes by offering integrated assembly line solutions, including soldering and inspection. American Hakko Products specializes in manual soldering stations for research and development and repair segments.
Soldering equipment encompasses machinery designed to form metallurgical joints, typically using a tin-based alloy, to connect electronic components to printed circuit boards. These systems provide precise temperature control and process automation essential for creating reliable electrical connections. Automated systems, including reflow and wave soldering machines, constitute the largest product segment, driven by mass production in consumer electronics. The adoption of laser soldering technology is accelerating, valued for its precision in high-density and heat-sensitive applications.
Product design and market access are heavily influenced by environmental and safety regulations. The EU’s RoHS directive restricts hazardous substances like lead, while China's GB standards and the US's OSHA guidelines govern equipment safety and workplace exposure limits. Equipment selection decisions will increasingly hinge on balancing the capital cost of automation against the operational costs and availability of skilled labor.
Market Dynamics
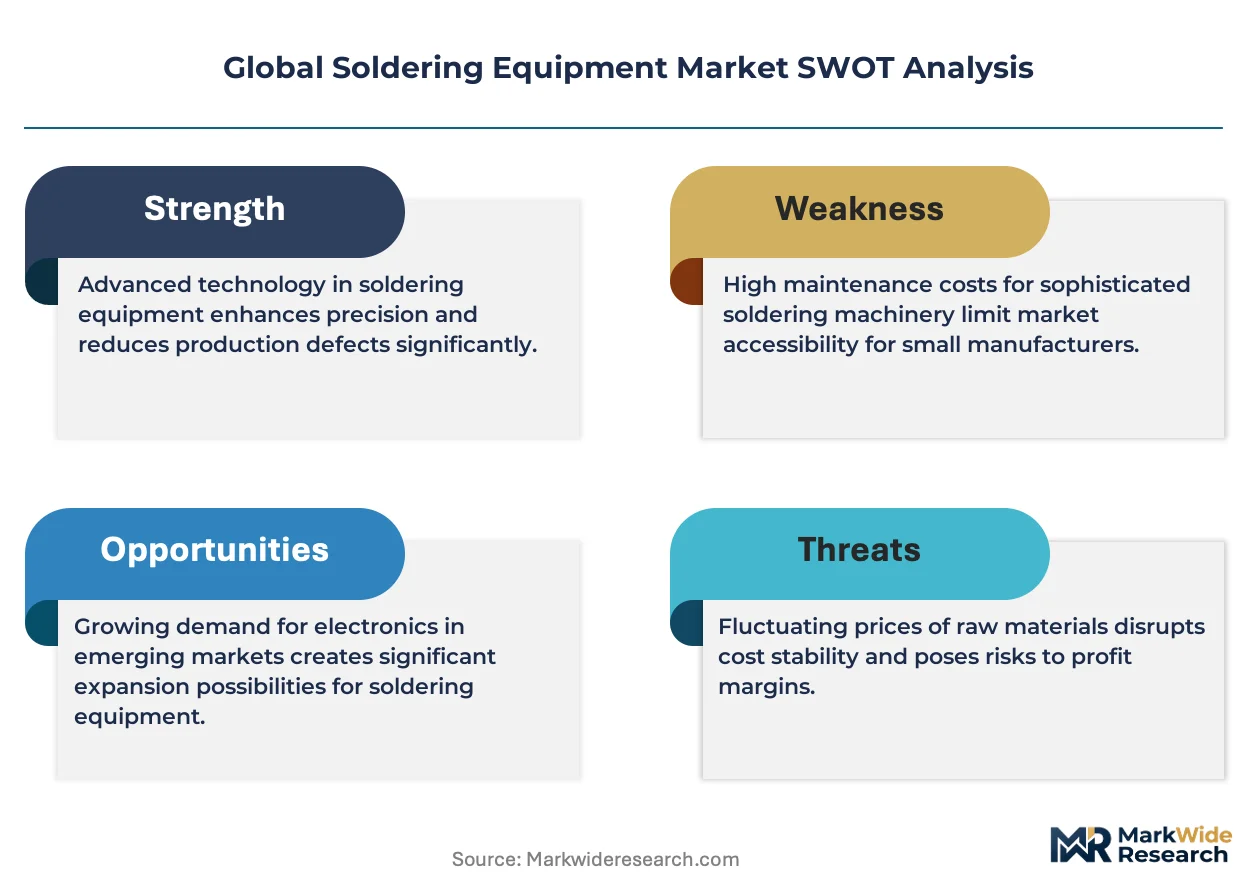
The imperative to produce smaller, more complex electronics while complying with global environmental mandates like the EU's RoHS directive is the central force shaping the soldering equipment market, compelling investment in advanced, automated, and lead-free capable systems.
Growth Catalysts
- Automotive Electronics Expansion:Demand for sophisticated soldering in advanced driver-assistance systems (ADAS) and electric vehicle battery management systems creates a significant pull for high-reliability automated equipment.
- Lead-Free Mandates:Regulations restricting hazardous substances, notably the EU's RoHS directive, directly compel electronics manufacturers to upgrade or replace legacy equipment to handle lead-free solder alloys.
- Manufacturing Nearshoring:Investment in new electronics assembly capacity in Mexico and Poland, driven by supply chain diversification strategies, generates direct demand for new soldering line installations.
Market Restraints
- High Capital Expenditure:The significant upfront cost of advanced automated systems, such as selective wave or laser soldering machines, presents a major barrier for smaller electronics manufacturers and startups.
- Process Thermal Constraints:Higher melting points of lead-free solders create thermal management challenges, risking damage to sensitive electronic components and complex substrates during the soldering process.
- Raw Material Price Volatility:Fluctuations in the price of tin, the primary constituent of modern solder alloys, introduce cost uncertainty into manufacturing operations and can impact equipment purchasing decisions.
Strategic Opportunities
- Medical Device Miniaturization:The growing market for compact, high-reliability medical electronics, which must adhere to standards like ISO 13485, opens a new vertical for precision soldering technologies.
- Process and Inspection Integration:Combining automated soldering systems with in-line automated optical inspection (AOI) technology creates a significant opportunity for vendors offering integrated, zero-defect process control solutions.
- Southeast Asian Assembly Hubs:Underpenetrated markets, particularly in Vietnam and Malaysia, represent a key growth frontier as multinational electronics firms establish and expand production facilities in the region.
Industry Challenges
- Skilled Technician Scarcity:A persistent shortage of operators and maintenance technicians with the expertise to run and service complex robotic and automated soldering systems constrains operational efficiency for manufacturers.
- Legacy System Integration:Integrating new, digitally controlled soldering equipment into existing production lines with older, analog machinery creates significant technical hurdles and potential workflow disruptions for assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soldering Equipment Market |
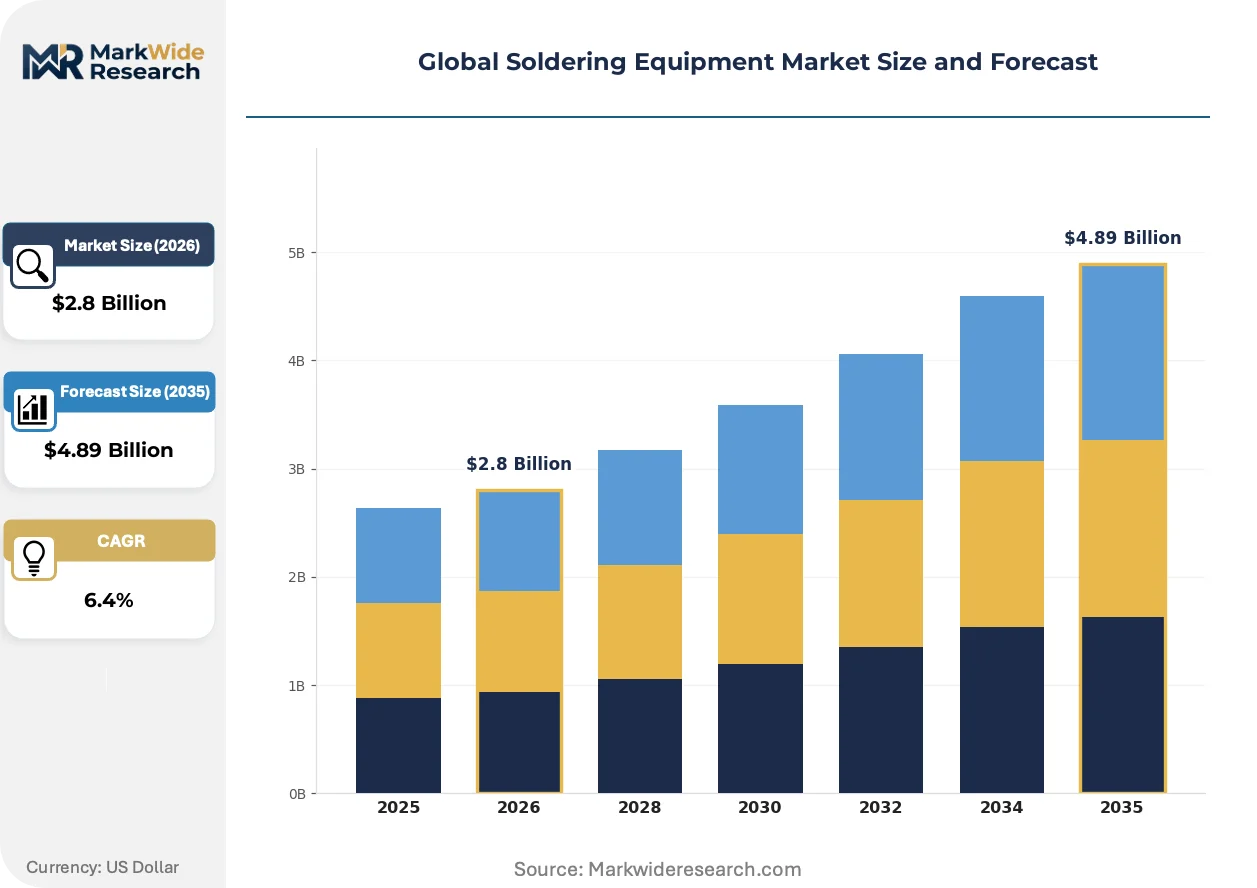
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Soldering Irons, Soldering Stations, Reflow Soldering Machines, Wave Soldering Machines, Hot Air Soldering Tools Technology: Lead-Free Soldering, Automation, Induction Heating, Ultrasonic Soldering, Laser Soldering Application: Consumer Electronics, Aerospace Hardware, Telecommunications Equipment, Industrial Controls, Printed Circuit Board Assembly End User: Electronics Manufacturers, Contract Assembly Services, Research Laboratories, Educational Institutes |
| Companies Covered | ITW EAE, BTU International, Kurtz Ersa, JUKI Automation, American Hakko Products, SEHO Systems GmbH, Rehm Thermal Systems, Pillarhouse International, TAMURA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soldering Equipment Market Strategic Shifts & Innovations
Precision and process control are the defining themes in equipment evolution. The market is shifting from bulk processing toward intelligent, selective soldering technologies capable of handling extreme component density and ensuring defect-free connections for mission-critical applications.
Laser soldering provides highly focused energy for joining individual components with minimal thermal impact on adjacent areas. Electronics manufacturers in the medical device and telecommunications sectors are adopting this technology for high-density and heat-sensitive applications. This technology is decentralizing soldering from a batch-oriented process to a selective, software-driven task performed on specific joints within a complex assembly.
Workplace safety regulations, including fume exposure limits set by the US Occupational Safety and Health Administration (OSHA), are influencing equipment design. This pressure forces manufacturers to incorporate advanced fume extraction and filtration systems directly into soldering stations and automated machinery. The manual soldering segment, used extensively for rework and prototyping, is most affected, accelerating the adoption of stations with integrated safety features.
A transition toward equipment-as-a-service (EaaS) models for high-value automated systems is altering procurement patterns. This approach allows contract manufacturers to access state-of-the-art technology through leasing or subscription contracts, replacing large, one-time capital expenditures. This trend is particularly visible in European markets, where it aligns with financial strategies that favor operational expenses and mitigate technology obsolescence risk.
Global Soldering Equipment Market Segmentation
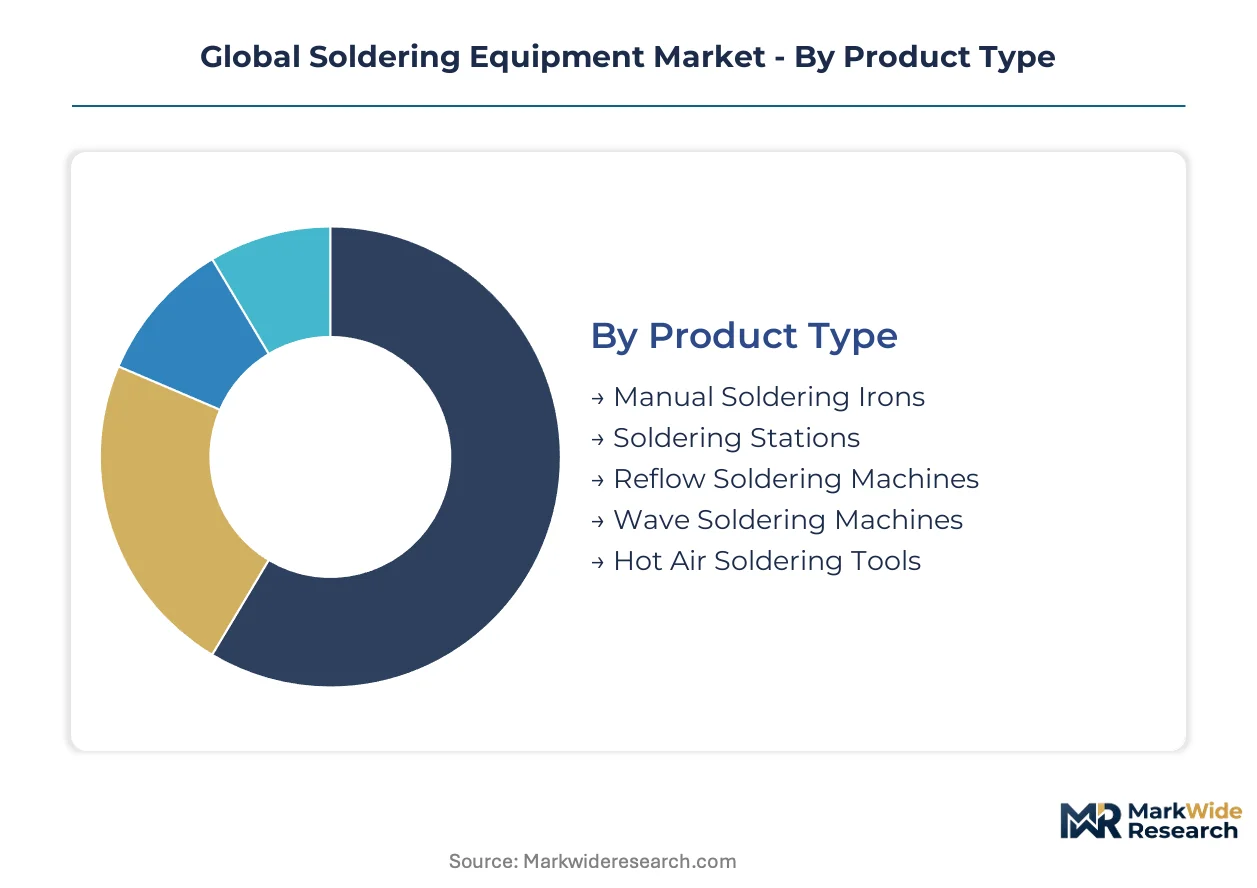
The Global Soldering Equipment Market segmentation delineates distinct product types, technologies, applications, and end-users, reflecting varied operational scales and technical demands across the electronics manufacturing ecosystem. Understanding these segments provides clarity on where investment and innovation are concentrating.
Product Type:
The product type segmentation highlights the fundamental distinction between high-volume automated systems and precision-focused manual tools.
- Reflow Soldering Machines:These systems heat entire circuit boards to melt solder paste, creating numerous electrical connections simultaneously. Demand is concentrated in consumer electronics manufacturing across Vietnam and Mexico, driven by high-throughput requirements for smartphones and tablets.
- Wave Soldering Machines:These machines pass PCBs over a wave of molten solder, primarily used for through-hole components. Automotive electronics production in Poland utilizes wave soldering for robust connections in ADAS modules, emphasizing reliability in harsh environments.
- Manual Soldering Irons:These handheld tools provide localized heat for precise, individual component attachment and repair in R&D labs.
- Soldering Stations:These integrated units offer temperature control and fume extraction for manual soldering, essential for prototyping in Germany.
- Hot Air Soldering Tools:These tools deliver controlled hot air for surface-mount device rework and removal, frequently used in electronics repair centers.
Mature deployment sits with Wave Soldering Machines. Newer deployment is concentrated in Reflow Soldering Machines.
Technology:
Technology advancements in soldering equipment address diverse application requirements, from environmental compliance to micro-component integration.
- Lead-Free Soldering:This technology uses tin-based alloys free from hazardous substances like lead, mandated by regulations such as the EU's RoHS directive. Manufacturers in China are upgrading equipment to handle higher melting points and ensure compliance for export markets.
- Laser Soldering:This technique applies highly localized heat with a focused laser beam, minimizing thermal stress on sensitive components. Medical device miniaturization in the US drives adoption for precision assembly of compact, high-reliability electronics.
- Automation:Integrated robotic systems perform soldering tasks with high repeatability and speed, crucial for mass production lines in Southeast Asia.
- Induction Heating:This method uses electromagnetic fields to generate heat directly within the solder joint, providing rapid and precise temperature control.
- Ultrasonic Soldering:This technique uses ultrasonic vibrations to break down oxides, enabling soldering without flux for challenging materials like aluminum.
Laser Soldering technology exhibits the steepest expansion trajectory.
Application:
Application areas define the specific performance and reliability requirements demanded by various customer segments.
- Consumer Electronics:This segment encompasses devices like smartphones, laptops, and wearables, requiring high-speed, automated soldering for miniaturized components. Large-scale contract manufacturers in Vietnam depend on advanced reflow systems for high-volume production.
- Printed Circuit Board Assembly:This foundational application involves attaching electronic components to PCBs, forming the basis for almost all electronic devices. Mexico's electronics assembly hubs utilize a mix of wave and reflow soldering for diverse board configurations.
- Aerospace Hardware:This application demands ultra-high reliability and precision soldering for components in avionics and satellite systems, often requiring stringent certifications.
- Telecommunications Equipment:This segment requires robust connections for network infrastructure and 5G devices, favoring automated systems with high throughput and signal integrity.
- Industrial Controls:This application involves soldering for robust electronic modules used in factory automation and process control, prioritizing durability and environmental resistance.
Consumer Electronics currently dominates demand, while Aerospace Hardware presents an emerging niche for specialized solutions.
End User:
End-user categories differentiate purchasing volumes and technical support needs for soldering equipment.
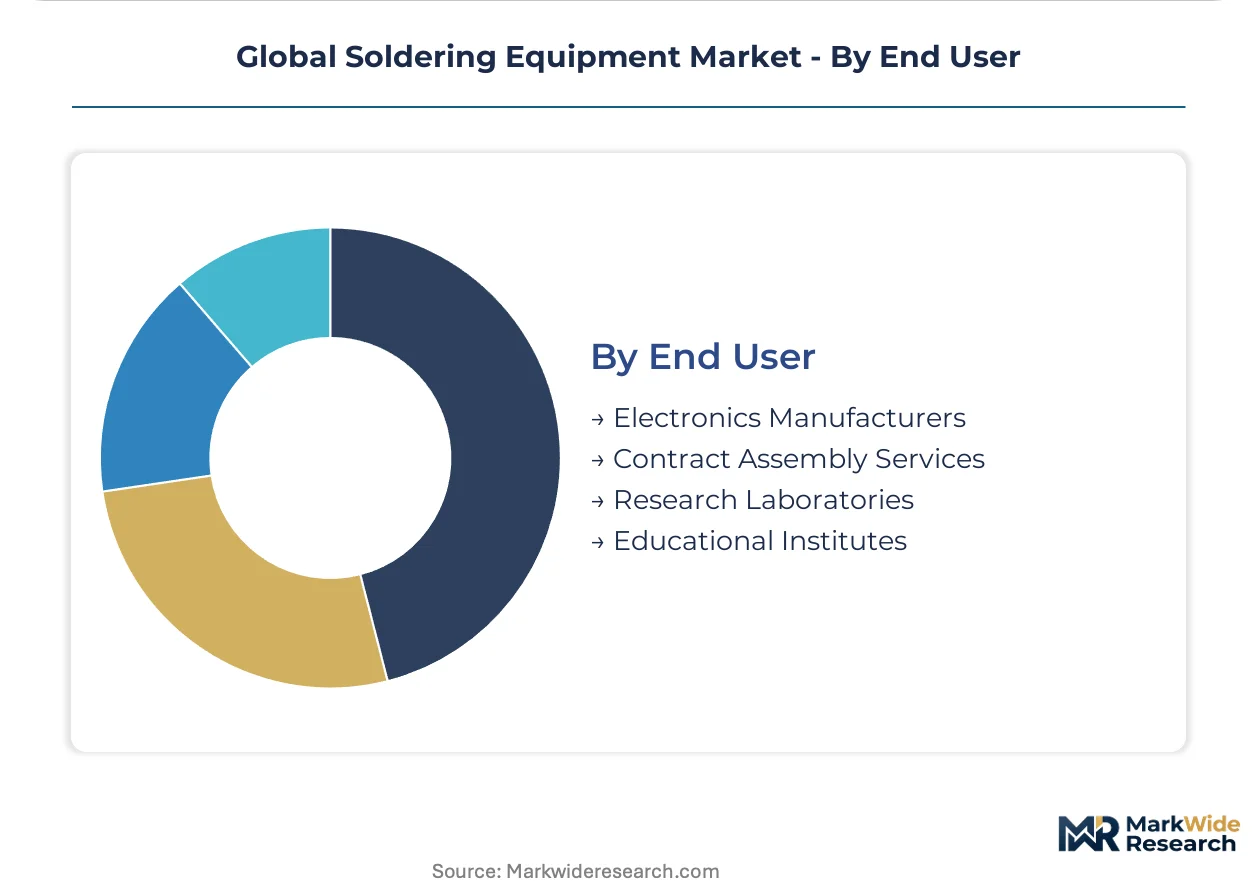
- Electronics Manufacturers:These entities produce their own electronic products, requiring a range of soldering equipment from manual stations for prototyping to integrated automated lines for production. Companies in Germany invest in advanced systems for in-house quality control.
- Contract Assembly Services:These firms specialize in manufacturing electronic products for other companies, necessitating flexible, high-volume automated soldering solutions. Mexican contract manufacturers leverage diverse equipment to serve multiple clients efficiently.
- Research Laboratories:These facilities utilize manual soldering stations and specialized tools for new product development and material science investigations.
- Educational Institutes:These organizations employ basic soldering equipment for training students in electronics assembly and repair techniques.
Electronics Manufacturers and Contract Assembly Services account for the largest share of equipment procurement, while Research Laboratories exhibit highly specialized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tin-based alloys form the core of soldering equipment functionality, influencing manufacturing hubs globally. Global supply chains for these critical materials impact equipment procurement decisions. Key manufacturing regions drive demand for advanced soldering systems.
United States
Medical device miniaturization and aerospace hardware demand advanced soldering solutions in the United States. OSHA guidelines for workplace exposure influence equipment design, particularly for fume extraction. Silicon Valley facilities drive demand for precision laser soldering for high-density applications.
Germany
German industrial controls and high-value electronics manufacturing require reliable soldering equipment. The EU's RoHS directive compels manufacturers to adopt lead-free soldering technologies. Bavarian electronics manufacturers invest in advanced automated systems for in-house quality control.
China
Chinese consumer electronics production and export markets create substantial demand for soldering equipment. China's GB standards mandate compliance, driving upgrades for lead-free solders. Shenzhen's electronics assembly hubs upgrade equipment for mass production and global market access.
Mexico
Mexican contract assembly services and growing automotive electronics production boost soldering equipment demand. Trade policies and supply chain diversification strategies attract significant manufacturing investments. Tijuana and Juarez contract manufacturers leverage diverse equipment to serve multiple international clients.
Vietnam
Vietnamese consumer electronics manufacturing drives demand for high-speed, automated soldering systems. Local environmental regulations and export compliance standards shape equipment procurement decisions. Ho Chi Minh City's manufacturing facilities are expanding production, requiring advanced reflow systems.
Global Soldering Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche precision applications and integrated solutions. The market exhibits a tiered structure, with large equipment manufacturers alongside specialized tool providers. Strategic archetypes include high-volume automated system providers, precision manual tool specialists, and integrated assembly line solution providers. Dominant competitive moves involve portfolio diversification to cover diverse customer needs and strategic partnerships to offer integrated process and inspection solutions.
Within the high-volume automated systems tier, Kurtz Ersa exemplifies a broad portfolio approach, serving large-scale contract assembly services with wave and reflow systems. JUKI Automation occupies a position as a provider of integrated assembly line solutions, encompassing soldering and inspection technologies. American Hakko Products represents specialization in manual soldering stations, catering to research and development as well as repair segments. These companies illustrate the varied approaches to serving distinct customer segments across the soldering equipment market, from mass production to precision rework.
| Leading Market Players |
|---|
| ITW EAE |
| BTU International |
| Kurtz Ersa |
| JUKI Automation |
| American Hakko Products |
| SEHO Systems GmbH |
| Rehm Thermal Systems |
| Pillarhouse International |
| TAMURA Corporation |
| Others |
Cost & Logistics Intelligence
Large-scale contract assembly services, prevalent in Vietnam and Mexico, leverage their purchasing power to drive competitive pricing for high-volume automated soldering systems. This concentration of demand shapes equipment procurement patterns and influences vendor strategies.
Pricing Analysis
Volume-based sales of automated reflow and wave soldering machines typically operate on tighter margins due to intense competition among large equipment manufacturers. Precision laser soldering systems, however, command higher margins reflecting their specialized technology and niche application in medical devices. Price differentiation stems from technology complexity and after-sales service bundles. Pricing softness reflects the high capital expenditure barrier for smaller manufacturers. Contract assembly services exhibit high price sensitivity for standard equipment.
Supply Chain Analysis
Dual-sourcing requirements for critical components, especially from major electronics manufacturers, influence the supply chain for soldering equipment. Supply concentration for specialized components like high-precision optics and temperature sensors sits in Germany and Japan. Raw material dependencies include tin, copper, and specialized ceramics for heating elements. Commodity price volatility, particularly for tin, introduces cost uncertainty. Distribution runs through a mix of direct sales teams and regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soldering equipment market functions as a cost-of-compliance story, where the EU's RoHS directive creates a significant barrier-to-entry moat for manufacturers of lead-free capable systems. Compliance with environmental mandates is non-negotiable for global market access.
For Market Incumbents:
Extend portfolio integration to offer complete automated lines, including in-line AOI, to counter emerging niche players. Consolidate market share in high-growth regions like Southeast Asia through strategic partnerships with local distributors. Invest in R&D for advanced thermal management solutions, addressing the challenges posed by higher melting points of lead-free solders. This proactive approach mitigates the threat of specialized laser soldering firms.
For New Entrants and Emerging Players:
Begin with targeting the medical device miniaturization segment in the US, which demands high-precision laser soldering technology. This niche offers higher margins and less direct competition from broad-portfolio incumbents. Develop integrated process control software for existing manual stations, providing a go-to-market angle focused on enhanced safety and data logging for R&D labs. Focus on underpenetrated markets like Malaysia for initial market entry.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking technology-differentiated assets with strong intellectual property in laser soldering. Long-term viability for this market spans beyond a decade, driven by continuous miniaturization and automation. Target mid-sized firms specializing in advanced thermal management or integrated AOI solutions. The signal to watch is the increasing adoption rate of equipment-as-a-service models in European markets, indicating a shift in procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Kurtz Ersa expands its offerings to serve diverse consumer electronics manufacturing needs. |
| Technology Licensing | JUKI Automation licenses laser soldering patents, enhancing its integrated assembly solutions. |
| After-Sales Service Enhancement | American Hakko Products strengthens its repair network, supporting R&D labs globally. |
| Regional Manufacturing Expansion | SEHO Systems establishes production in Vietnam, serving growing Southeast Asian assembly hubs. |
| Equipment-as-a-Service Launch | Rehm Thermal Systems introduces EaaS models in Germany, aligning with financial strategies. |
Research Approach
Multi-period observation of equipment sales volumes and technology adoption rates anchored the trend analysis, supplemented by interviews with electronics manufacturing executives and R&D engineers. Primary insights were gathered from procurement managers at contract assembly services and technical specialists at medical device firms. Secondary validation drew from EU RoHS directive updates, OSHA guidelines, and trade data from Vietnam and Mexico. Bottom-up and top-down triangulation ensured data coherence.
Segment weighting by product type, technology, application, and end-user informed the quantitative model, factoring regional manufacturing shifts. Equipment life cycles and replacement rates were integrated as key inputs. Compound annual growth rates derived through regression analysis of historical trends and projected market dynamics over the projection horizon. Component miniaturization and lead-free compliance mandates served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; automated systems carry tighter precision than manual tools. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Deviation in raw material price volatility or global trade policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Global Semiconductor Photolithography Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Tape on Reel Feeder Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market