
 Global Semiconductor Photolithography Market | 2026-2036
Global Semiconductor Photolithography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Photolithography Market Outlook
ISO 14644 cleanroom certification is reorganizing supplier tiers in semiconductor photolithography. ASML leverages its monopoly on extreme ultraviolet lithography systems to command pricing power across foundry supply chains. Nikon Corporation anchors its position through deep ultraviolet scanner specialization for mature nodes. Canon competes in i-line and KrF stepper segments where cost sensitivity dominates procurement decisions.
Semiconductor photolithography encompasses the transfer of geometric patterns from photomasks to photosensitive substrates using ultraviolet or electron-beam exposure, with critical dimensions now reaching sub-3 nanometer resolution through EUV wavelengths of 13.5 nanometers. Scanner systems lead capital expenditure allocation as foundries pursue single-exposure patterning at advanced nodes. Extreme Ultraviolet technology captures the fastest expansion trajectory despite tool complexity and source power constraints. Deep Ultraviolet equipment sustains volume across automotive and industrial chip production where node migration lags leading-edge logic.
The US CHIPS Act and NIST frameworks impose domestic content requirements on fabs receiving federal incentives, directly conditioning equipment procurement geography. The EU AI Act and REACH chemical restrictions from ECHA constrain photoresist formulations and process chemistry approvals. Japan's METI coordinates supply chain resilience initiatives affecting lithography component sourcing. Stakeholders must monitor which regulatory jurisdictions win fabrication investment commitments to anticipate equipment demand clustering.
Market Dynamics
ASML's monopoly on EUV scanners is restructuring competitive access to sub-3nm manufacturing, forcing foundries into long-term co-development contracts and reshaping capital allocation timelines across Taiwan, South Korea, and the United States.
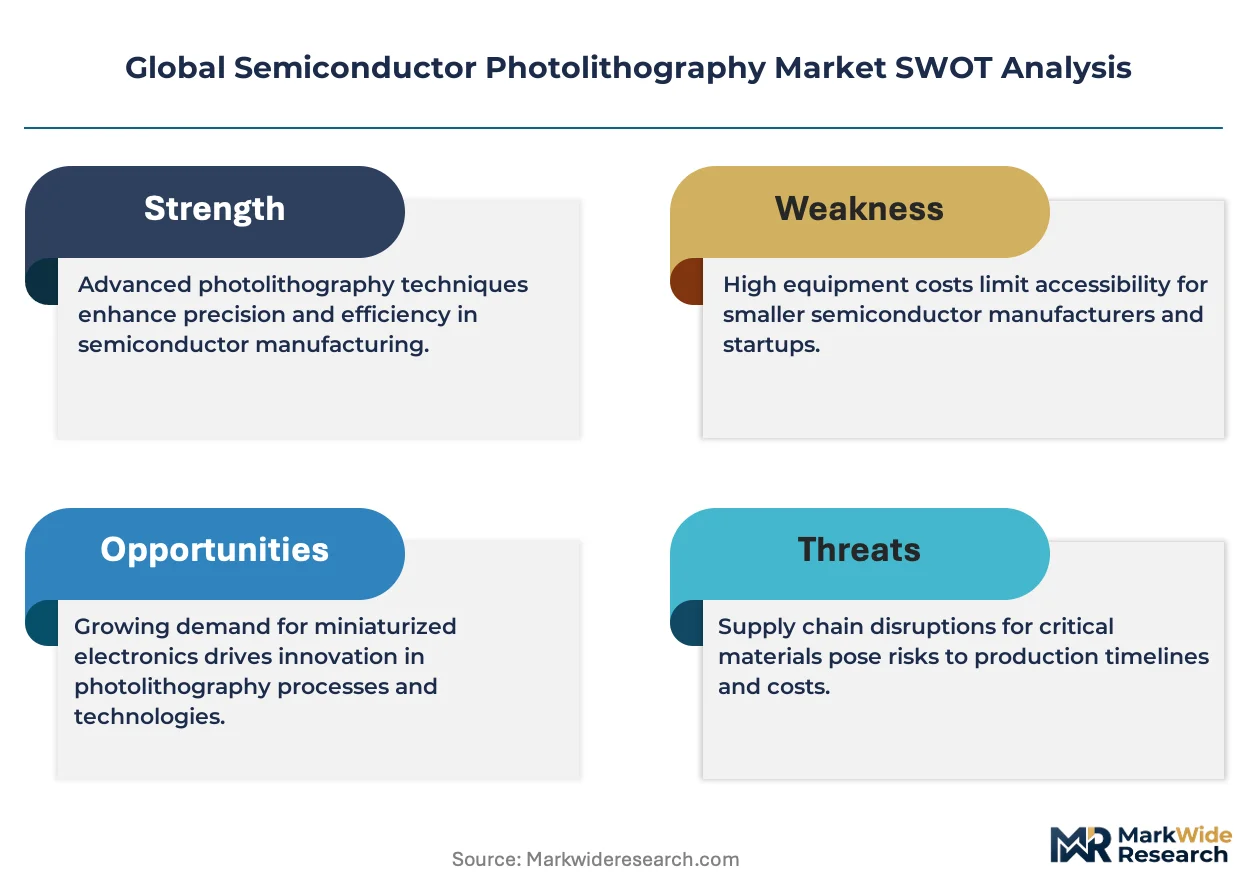
Growth Catalysts
- CHIPS Act incentives:US fabs receiving federal subsidies must source qualifying domestic equipment, accelerating qualification timelines for lithography component suppliers establishing American manufacturing footprints.
- AI accelerator demand:Hyperscalers are contracting dedicated advanced-node capacity from TSMC and Samsung Foundry, directly expanding EUV scanner deployment schedules.
- High-NA EUV maturation:Next-generation numerical aperture systems are resolving sub-2nm critical dimensions, enabling single-exposure patterning that reduces process complexity for logic manufacturers.
Market Restraints
- EUV source power constraints:Plasma-generated 13.5nm wavelength production remains energy-intensive, limiting throughput and elevating operating costs per wafer pass.
- Optics supply concentration:Zeiss SMT maintains exclusive production of EUV-grade aspherical mirrors, creating single-source dependency for scanner manufacturers.
- REACH chemical restrictions:ECHA's evolving substance authorization lists are constraining photoresist solvent formulations, extending qualification cycles for new materials.
Strategic Opportunities
- India semiconductor incentives:PLI scheme disbursements and state-level subsidies are attracting lithography equipment distributors to establish technical service centers in Gujarat and Tamil Nadu.
- Photoresist recycling infrastructure:Closed-loop solvent recovery systems are reducing material waste costs for high-volume foundries operating DUV immersion lines.
- Digital twin integration:Virtual scanner commissioning is compressing fab installation timelines and reducing physical prototype iterations for new process nodes.
Industry Challenges
- EUV technician scarcity:Specialized vacuum system maintenance and plasma source engineering skills command premium compensation, constraining fab staffing scalability.
- Multi-patterning complexity:Self-aligned quadruple patterning requirements at mature nodes are extending cycle times and defect inspection burdens for automotive chip producers.
- ISO 14644 certification backlogs:Cleanroom validation queue delays are pushing equipment delivery schedules and compressing installation windows at greenfield sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Photolithography Market |
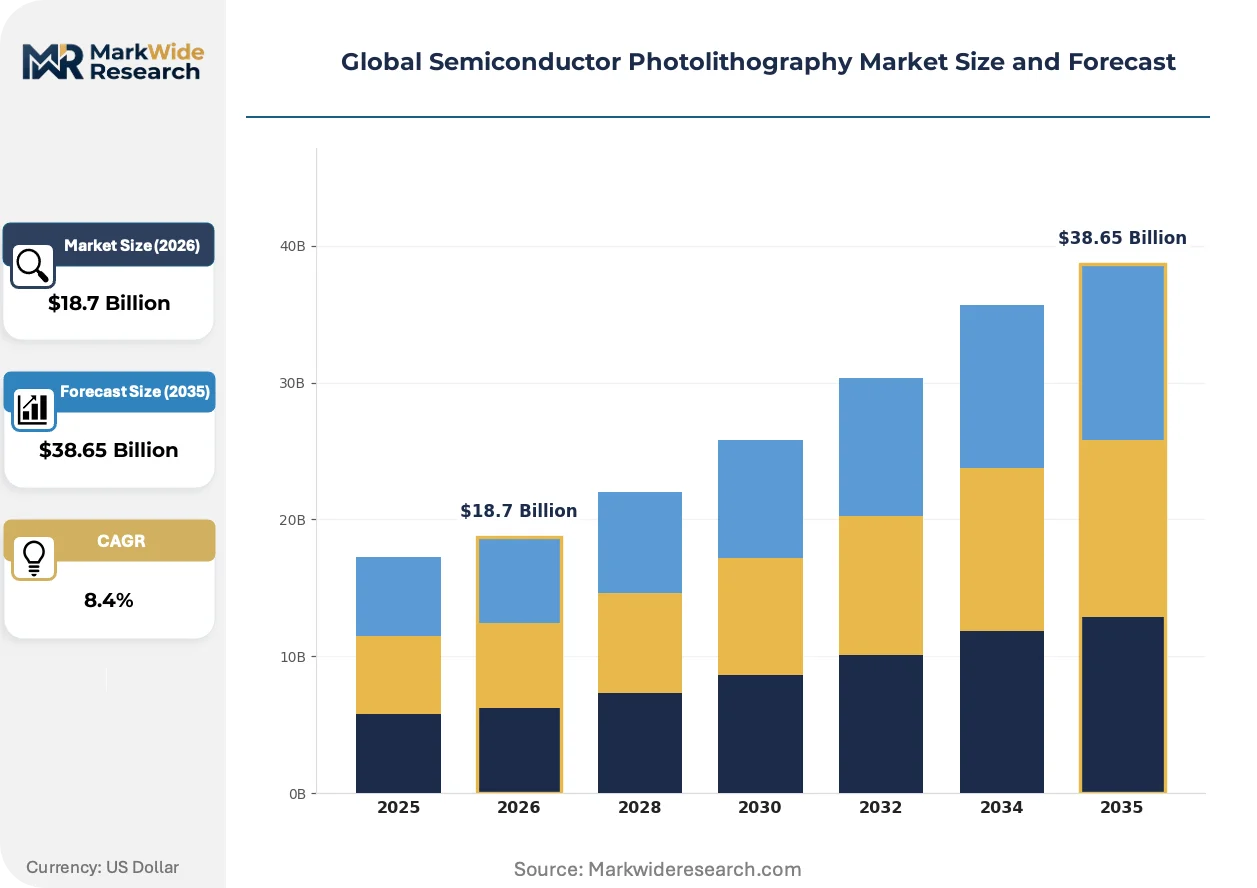
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stepper, Scanner, Mask/Etch System, Automation Tools Application: Integrated Circuits, LED Manufacturing, MEMS, Display Technology Technology: Extreme Ultraviolet, Deep Ultraviolet, Nanoimprint, Focal Plane End User: OEMs, Foundries, Research Institutions, Semiconductor Firms |
| Companies Covered | ASML, Nikon Corporation, Canon, JEOL, SUSS MicroTec, EV Group, NuFlare Technology, Veeco Instruments, Applied Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Photolithography Market Strategic Shifts
Computational lithography advances and scanner-source integration are compressing the resolution-enhancement technology pipeline, while regulatory chemical frameworks and procurement model evolution are restructuring supplier-fab relationships across major manufacturing clusters.
High-NA EUV architecture is supplanting multi-patterning DUV approaches for critical layers at 2nm and below. Samsung Foundry and Intel are prioritizing 0.55NA system reservations for 2027 production ramps. This transition is compressing the economic viability window for existing low-NA EUV fleets in leading-edge logic.
EU AI Act algorithmic transparency mandates are conditioning automated defect classification system deployments in European fabs. Equipment suppliers must now document machine-learning training data provenance for pattern-recognition modules. Automotive semiconductor manufacturers sourcing from German and French facilities face accelerated compliance verification schedules.
Foundries are consolidating lithography maintenance contracts under multi-year outcome-based agreements that unbundle spare parts from labor pricing. Equipment OEMs are responding with predictive analytics subscriptions that guarantee uptime thresholds. This restructuring is most pronounced in Taiwan and South Korea where scanner fleet densities justify dedicated on-site engineering teams.
Global Semiconductor Photolithography Market Segmentation
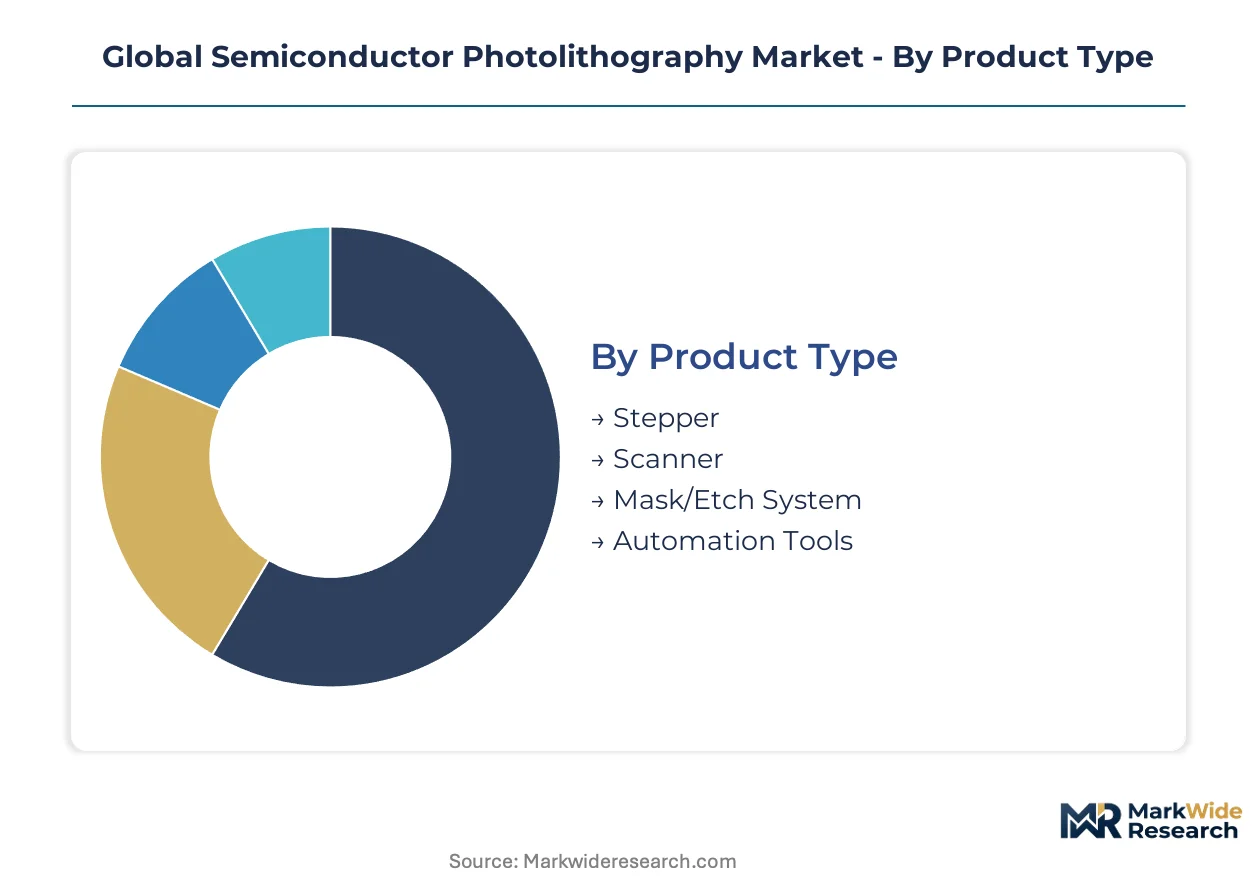
Photolithography equipment segmentation reveals how capital allocation priorities diverge across node geometries, regulatory jurisdictions, and customer scale. Equipment suppliers calibrate product roadmaps against these fault lines to capture foundry expansion cycles and compliance-driven replacement demand.
Product Type:
Regulatory differentiation in cleanroom certification and NIST traceability requirements splits procurement specifications between high-volume foundries and research facilities. US CHIPS Act domestic content rules favor stepper and scanner platforms with qualifying American component sourcing.
- Scanner:These systems achieve sub-3nm resolution through synchronized mask-wafer scanning architectures with EUV or DUV light sources. TSMC and Samsung Foundry in Taiwan and South Korea concentrate orders for High-NA EUV scanners as they advance toward 2nm production ramps. Scanner procurement absorbs the dominant share of fab capital expenditure budgets.
- Stepper:Whole-field exposure systems dominate mature node production and specialty chip manufacturing where throughput requirements moderate. Automotive semiconductor producers in Germany and Japan favor stepper platforms for power management and sensor chips where node migration lags leading-edge logic.
- Mask/Etch System:Photomask patterning and plasma etch modules complete the lithography cluster for multi-patterning process flows.
- Automation Tools:Wafer handling robotics and metrology integration reduce human contamination risk in ISO 14644 Class 1 environments.
Scanner systems handle the majority of throughput; Mask/Etch System is the fastest mover on share as multi-patterning complexity escalates.
Application:
Cost tier stratification separates leading-edge logic manufacturing from specialty applications where equipment depreciation cycles extend. High-NA EUV investments concentrate in Integrated Circuits while LED and Display applications prioritize cost-optimized DUV platforms.
- Integrated Circuits:Logic and memory chip production demands the highest resolution patterning capabilities with EUV single-exposure for critical layers. Foundries in Taiwan, South Korea, and the United States are expanding EUV scanner deployment to meet hyperscaler AI accelerator contracts.
- Display Technology:Large-panel lithography for OLED and microLED backplanes requires specialized scanning optics and substrate handling for Gen 8.5+ glass sizes. Samsung Display and LG Display in South Korea anchor demand for panel-level patterning systems.
- LED Manufacturing:GaN and sapphire substrate patterning for solid-state lighting uses i-line and KrF steppers with less stringent resolution requirements.
- MEMS:Microelectromechanical systems for automotive pressure sensors and consumer motion chips utilize mature-node lithography with thick photoresist processing.
Integrated Circuits commands the dominant equipment spend; Display Technology is climbing the fastest as panel makers transition to OLED-on-silicon and microLED architectures.
Technology:
Customer type segmentation separates capital-constrained research institutions from foundries with multi-billion dollar equipment budgets. EUV qualification timelines and source power constraints create divergent procurement patterns between leading-edge and trailing-edge manufacturers.
- Extreme Ultraviolet:13.5nm wavelength systems from ASML enable single-exposure patterning at 3nm and below. Intel, TSMC, and Samsung Foundry are reserving High-NA EUV systems for 2027 production ramps.
- Deep Ultraviolet:193nm immersion and dry systems sustain volume production across automotive, industrial, and mature logic nodes. Nikon and Canon supply DUV platforms where cost sensitivity dominates procurement.
- Nanoimprint:Mechanical patterning alternative for photonics and biochip applications requiring non-standard materials incompatible with optical exposure.
- Focal Plane:Image sensor-optimized lithography for backside-illuminated CMOS and stacked sensor architectures.
Deep Ultraviolet sustains the largest installed base; Extreme Ultraviolet is gaining share fastest as foundries advance below 3nm nodes.
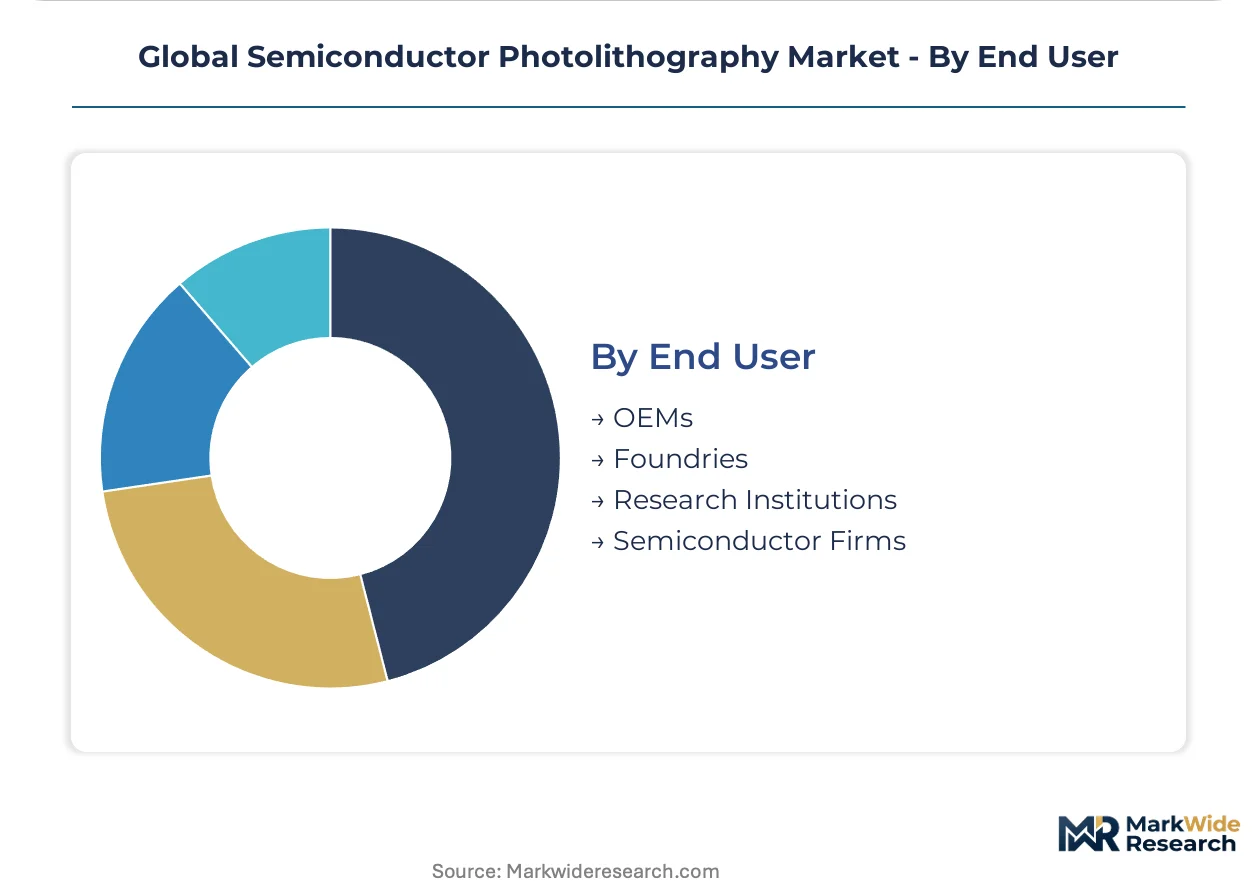
End User:
Volume concentration separates high-throughput foundries from low-volume research and prototyping facilities. OEMs and semiconductor firms with captive fabrication face distinct qualification timelines compared to merchant foundries serving fabless customers.
- Foundries:Merchant manufacturers including TSMC, Samsung Foundry, and GlobalFoundries operate the densest scanner fleets with dedicated on-site engineering teams. Foundry capital expenditure cycles directly determine EUV equipment demand amplitude.
- Semiconductor Firms:Integrated device manufacturers like Intel and Texas Instruments combine leading-edge and mature-node production across multiple facilities. IDM equipment procurement balances EUV adoption for logic against DUV sustainment for analog and power products.
- OEMs:Original equipment manufacturers with captive chip production for automotive and industrial systems.
- Research Institutions:Universities and national laboratories operate lower-throughput systems for process development and academic training.
Foundries deploy the majority of new capacity; Semiconductor Firms are expanding fastest as IDMs reshore fabrication under CHIPS Act incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US CHIPS Act disbursements are accelerating fab construction timelines across multiple jurisdictions. Taiwan and South Korea maintain the densest EUV scanner deployments. Germany and Japan anchor equipment component supply chains through specialized optics and materials clusters.
United States
Intel and TSMC are expanding Arizona fabrication complexes with EUV-qualified cleanrooms. CHIPS Act NIST frameworks mandate domestic content thresholds for federal incentive recipients. Phoenix and Hillsboro clusters are attracting Zeiss SMT service engineers for mirror maintenance localization.
Taiwan
TSMC's Nanke and Hsinchu Science Park expansions are absorbing the majority of High-NA EUV system allocations. The island's national development council coordinates water and power infrastructure for sub-2nm node ramps. Taichung's Central Taiwan Science Park is adding immersion DUV capacity for specialty chip foundry services.
South Korea
Samsung Foundry and SK Hynix are reserving EUV scanners for Pyeongtaek and Yongin memory complexes. Korea's Ministry of Trade, Industry and Energy funds domestic photoresist development to reduce Japanese import dependency. Seoul capital area engineering pools are specializing in plasma source maintenance for ASML fleet uptime guarantees.
Japan
Nikon and Canon maintain DUV stepper production in Kumamoto and Utsunomiya for mature node foundries. METI supply chain resilience initiatives are qualifying domestic EUV pellicle and resist suppliers. Kyushu's silicon island cluster is expanding 300mm wafer output for automotive semiconductor customers.
Germany
Zeiss SMT's Oberkochen facility remains the exclusive source for EUV-grade aspherical mirror systems. ECHA REACH chemical restrictions are extending photoresist formulation qualification cycles for Dresden and Regensburg fabs. Bavaria's semiconductor ecosystem is attracting lithography automation suppliers for service center localization.
Global Semiconductor Photolithography Market Competitive Environment
Player mix skews toward integrated lithography system specialists with captive optics supply chains. Market structure concentrates around three equipment archetypes: EUV scanner monopolists, DUV platform dualists, and niche stepper generalists. Competitive dynamics revolve around co-development contract structures and multi-year outcome-based maintenance agreements. Strategic moves emphasize regional service center expansion and predictive analytics subscription unbundling.
Within the integrated system tier, ASML Holding N.V. exemplifies the EUV monopoly archetype through its exclusive scanner production position. Nikon Corporation and Canon Inc. occupy the DUV specialization segment where mature node cost sensitivity dominates procurement patterns. These three anchors represent distinct competitive vectors: wavelength exclusivity, optical heritage leverage, and portfolio breadth across i-line through ArF immersion platforms.
| Leading Market Players |
|---|
| ASML |
| Nikon Corporation |
| Canon |
| JEOL |
| SUSS MicroTec |
| EV Group |
| NuFlare Technology |
| Veeco Instruments |
| Applied Materials |
| Others |
Value Chain & Pricing Dynamics
High-NA EUV system substitution for multi-patterning DUV workflows is redrawing procurement economics across Taiwan, South Korea, and the United States while compressing pricing power for legacy scanner fleets. This wavelength transition simultaneously concentrates supply geography around ASML's Veldhoven production and Zeiss SMT's Oberkochen optics, amplifying cost-plus contract leverage for equipment OEMs serving sub-3nm foundry demand.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate EUV scanner procurement, binding foundry customers to ASML's component cost pass-through structures. Price differentiation rests on numerical aperture tier and NIST traceability certification, with High-NA systems commanding substantial premiums over 0.33NA configurations. Pricing pressure stems from hyperscaler AI accelerator contracts compressing depreciation schedules for leading-edge logic manufacturers. Mature node automotive chip producers exhibit highest price sensitivity, while dedicated AI foundry capacity builders demonstrate lowest elasticity.
Supply Chain Analysis
Inbound logistics costs for EUV-grade aspherical mirrors from Rotterdam port congestion have elevated landed costs for Zeiss SMT deliveries to Arizona and Hsinchu fabs. Component sourcing draws from Germany for precision optics, Japan for pellicle membranes and photoresist precursors, and the Netherlands for scanner system integration. Single-source vulnerability concentrates in Zeiss SMT's exclusive EUV mirror production. Distribution runs through direct OEM-foundry co-development agreements with dedicated on-site engineering teams rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from regulatory jurisdiction competition for CHIPS Act and EU AI Act compliance, creating specialized equipment qualification niches across American, European, and East Asian manufacturing clusters.
For Market Incumbents: Secure exclusive service contracts for High-NA EUV field maintenance before technician scarcity intensifies staffing competition. Lock in backward integration into EUV pellicle supply through METI-coordinated Japanese supplier partnerships. Threat of Nikon and Canon DUV price aggression in mature node segments demands proactive capacity reservation in automotive semiconductor foundry accounts. For New Entrants and Emerging Players: Differentiate on photoresist recycling infrastructure and closed-loop solvent recovery systems for DUV immersion lines serving cost-pressured automotive chip producers. White-space targets concentrate in India's Gujarat and Tamil Nadu technical service centers under PLI scheme disbursements, plus EU AI Act algorithmic transparency documentation for automated defect classification modules. Go-to-market leverage rests on predictive analytics subscriptions guaranteeing uptime thresholds. For Investors and Strategic Acquirers: EU AI Act and REACH chemical restriction implementation reshapes the acquisition landscape toward photoresist formulation specialists with ECHA pre-approval status. Five-to-ten year viability favors suppliers with dual-use DUV-EUV qualification capabilities across Taiwan and South Korea manufacturing clusters. Target acquisition archetype: mid-scale automation tool vendors with ISO 14644 Class 1 wafer handling robotics. Signal to watch: cleanroom validation queue delays accelerating equipment delivery premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV System Reservation | Intel and Samsung Foundry bookings for 0.55NA production ramps secure sub-2nm patterning capacity. |
| Backward Integration into Optics | ASML's Zeiss SMT exclusivity agreements tighten control over aspherical mirror supply chains. |
| Domestic Content Qualification | CHIPS Act NIST frameworks condition federal incentive receipt on American component sourcing. |
| Predictive Analytics Subscription | Outcome-based maintenance contracts unbundle spare parts pricing from labor in Taiwan scanner fleets. |
| Photoresist Recycling Infrastructure | Closed-loop solvent recovery reduces material waste costs for Samsung Foundry DUV immersion lines. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with fab equipment procurement directors, EUV maintenance technicians, photoresist formulation chemists, and cleanroom certification auditors; and secondary validation through SEC equipment supplier filings, ECHA REACH substance authorization lists, and customs data for lithography component trade flows. Bottom-up scanner deployment tallies across Taiwan, South Korea, and United States fabs were triangulated against top-down foundry capital expenditure disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning technology tier, application node geometry, end-user scale, and regional regulatory cluster. CAGRs were derived from equipment shipment trajectories weighted against AI accelerator demand elasticity and domestic content requirement implementation pace. Forecast inputs incorporated High-NA EUV source power maturation curves and photoresist formulation qualification cycle durations.
Decision-makers should treat outputs as directional under assumptions of continued EUV scanner monopoly structure and stable CHIPS Act disbursement timelines; material deviation in either would warrant model refresh. Specific risk factors include ECHA chemical restriction expansion and Taiwan Strait logistics disruption scenarios. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Solar Module Production Equipment Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Resist Processing Equipment Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Chip Conveyors Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Global Wafer Cleaning Equipment Market