
 Vacuum Soldering System Market | 2026-2036
Vacuum Soldering System Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Soldering System Market Insights
Void-free joint formation through controlled atmosphere soldering is tilting process roadmaps across high-reliability electronics manufacturing. Kurtz Ersa leverages its European installed base to sustain technical service density in automotive power module lines. Palomar Technologies anchors North American precision assembly with specialized vacuum pressure control systems for photonic packages. Centrotherm competes in Asia-Pacific through localized thermal process engineering and regional application support.
Vacuum soldering systems deploy sealed process chambers where oxygen levels drop below 100 ppm, enabling fluxless or low-flux bonding of copper-pillar, die-attach, and IGBT substrates at temperatures ranging from 150°C to 400°C. Batch vacuum soldering retains dominance in prototype and low-to-medium volume settings where flexibility outweighs throughput economics. Continuous vacuum soldering captures expanding share in automotive IGBT and SiC module lines where line-integration and uptime metrics govern procurement decisions. Infrared heating technology leads installed capacity, though convection heating gains traction for uniform thermal profiles on large-area substrates.
EU RoHS restrictions on lead content and REACH substance controls shape material choices and process validation requirements for vacuum soldering equipment sold into European automotive and medical device supply chains. FDA quality system regulations and ISO 13485 medical device standards in the United States impose documentation and repeatability benchmarks that elevate specifications for systems serving implantable and diagnostic electronics. Stakeholders must monitor evolving thermal interface requirements for wide-bandgap semiconductors and assess whether current vacuum chamber architectures accommodate larger substrate formats without throughput degradation.
Market Dynamics
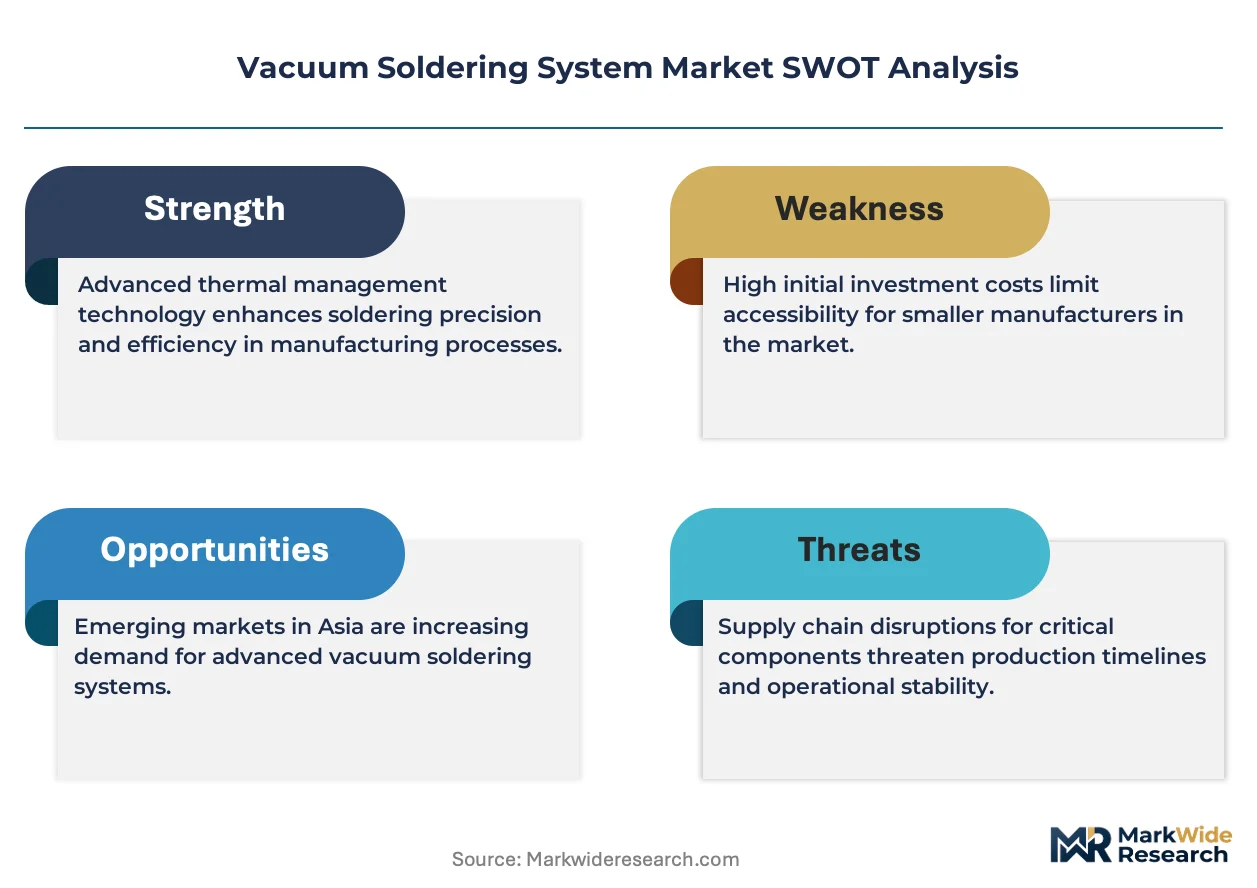
Wide-bandgap semiconductor proliferation is compressing thermal process tolerances and forcing vacuum soldering equipment architectures toward higher temperature stability and larger chamber formats. SiC and GaN power modules now dominate automotive inverter procurement, rewriting specifications for void-free die-attach and substrate bonding.
Growth Catalysts
- EU RoHS void-reduction mandates:European automotive electronics suppliers must achieve sub-5% void content in solder joints, accelerating replacement of atmospheric reflow with vacuum-assisted systems in power module assembly lines.
- Taiwan semiconductor packaging expansion:Flip-chip and advanced packaging facilities around Hsinchu are adding vacuum soldering capacity to handle copper-pillar interconnects for high-performance computing chips.
- SiC substrate bonding requirements:Silicon carbide power modules demand fluxless processing to prevent contamination of thermal interface materials, directly expanding addressable equipment demand.
Market Restraints
- High-purity gas supply concentration:Nitrogen and forming gas supply for vacuum chamber purging concentrates in East Asian industrial gas networks, exposing European and North American equipment operators to input cost volatility and delivery uncertainty.
- Chamber size-throughput tradeoff:Large-format IGBT and EV power module substrates require expanded vacuum chamber volumes that degrade temperature uniformity and cycle time economics versus legacy semiconductor packages.
- CE marking compliance friction:European machinery directive conformity assessment timelines extend 6-12 months for vacuum soldering systems, delaying revenue recognition for equipment vendors targeting EU automotive supply chains.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor assembly and testing attract vacuum soldering system deployment to emerging packaging facilities in Gujarat and Karnataka.
- Photonic package integration:Co-packaged optics for AI datacenter interconnects create demand for precision vacuum pressure control in hybrid optical-electronic assembly processes.
- Convection-infrared hybrid heating convergence:Combined thermal technologies enable uniform profiles on large ceramic substrates while maintaining the ramp rate control of infrared systems, opening new equipment configuration categories.
Industry Challenges
- Vacuum process engineering talent scarcity:Specialized expertise in chamber design, gas flow dynamics, and thermal profiling for void-free soldering remains concentrated among senior engineers at established equipment vendors and Tier-1 automotive electronics suppliers.
- ISO 13485 medical device certification timelines:Equipment validation for implantable electronics applications requires 18-24 month documentation cycles that compress vendor development roadmaps and strain customer project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Soldering System Market |
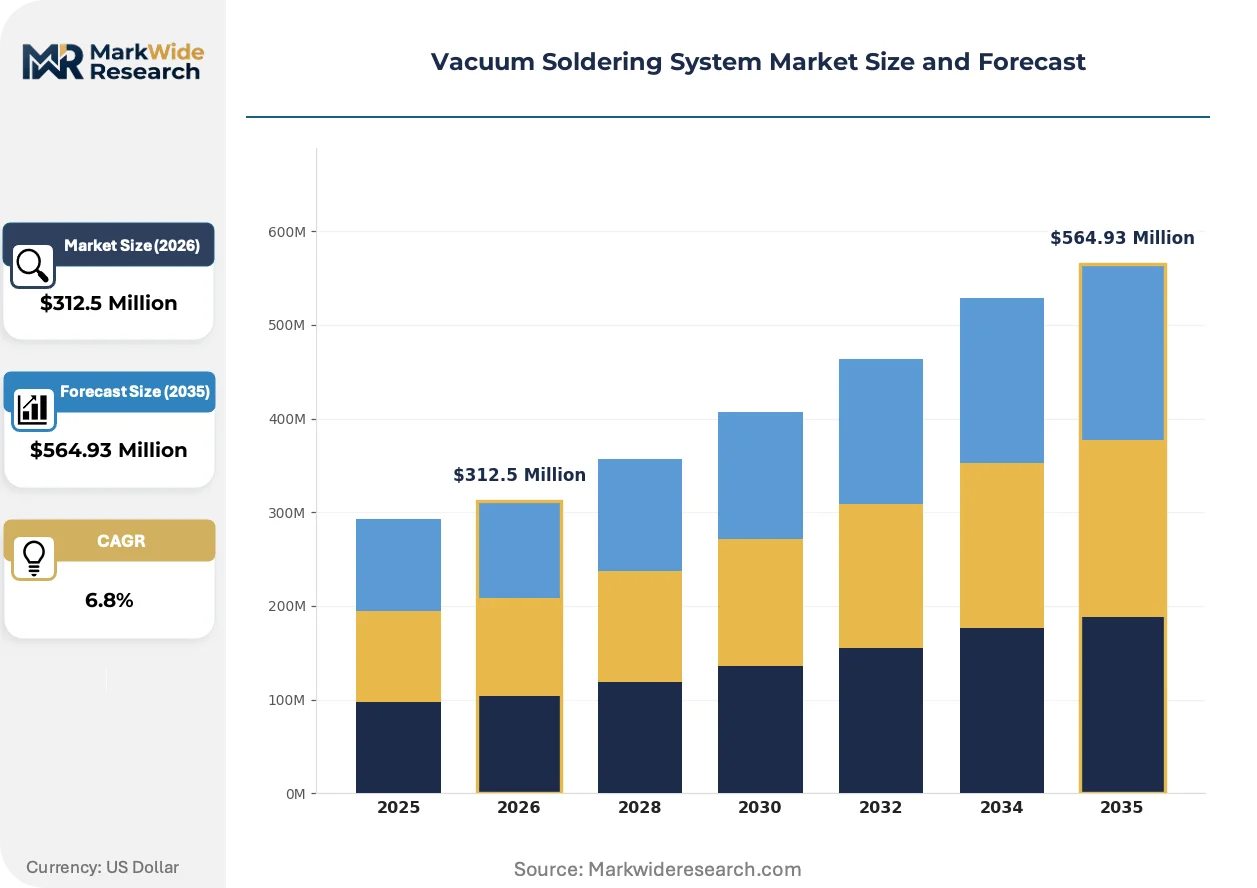
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Vacuum Soldering, Continuous Vacuum Soldering, Vacuum Reflow Soldering, Hybrid Vacuum Soldering Technology: Infrared Heating, Convection Heating, Microwave Heating, Induction Heating, Ultrasonic Heating Application: Electronics Assembly, Automotive Components, Aerospace Equipments, Medical Devices, Telecommunication Equipment End User: OEM Manufacturers, Contract Manufacturers, Research & Development Labs, Electronic Contract Assemblers |
| Companies Covered | Kurtz Ersa, PINK GmbH Thermosysteme, Palomar Technologies, Centrotherm, BTU International, Rehm Thermal Systems, ASSCON Systemtechnik-Elektronik GmbH, Heller Industries, SMT Wertheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Soldering System Market Trends and Innovations
Process control digitization and closed-loop thermal management are displacing operator-dependent recipe tuning across high-mix electronics manufacturing environments. Equipment vendors now embed machine learning modules that predict void formation from real-time chamber sensor arrays.
Real-time void detection using inline X-ray feedback is digitizing quality assurance workflows in automotive power module lines. Tier-1 suppliers in Germany and South Korea are piloting systems that adjust vacuum pressure and temperature profiles mid-cycle based on live joint imaging. This capability compresses process development cycles from weeks to days and reduces scrap rates in high-volume IGBT production.
REACH substance restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of vacuum chamber seals and thermal interface materials used in European medical and automotive electronics manufacturing. Equipment vendors must qualify alternative elastomer compounds that maintain vacuum integrity across 150-400°C operating windows. German automotive electronics suppliers are accelerating supplier audits to ensure downstream compliance with ECHA authorization requirements.
Service contract unbundling is fragmenting traditional equipment procurement models in North American precision assembly. Photonics and aerospace electronics buyers now separate hardware acquisition from process engineering support, purchasing vacuum soldering platforms through capital equipment channels while contracting specialized thermal recipe development through independent process consultants. This bifurcation is most visible in California and Massachusetts clusters serving defense and satellite communications applications.
Vacuum Soldering System Market Segmentation
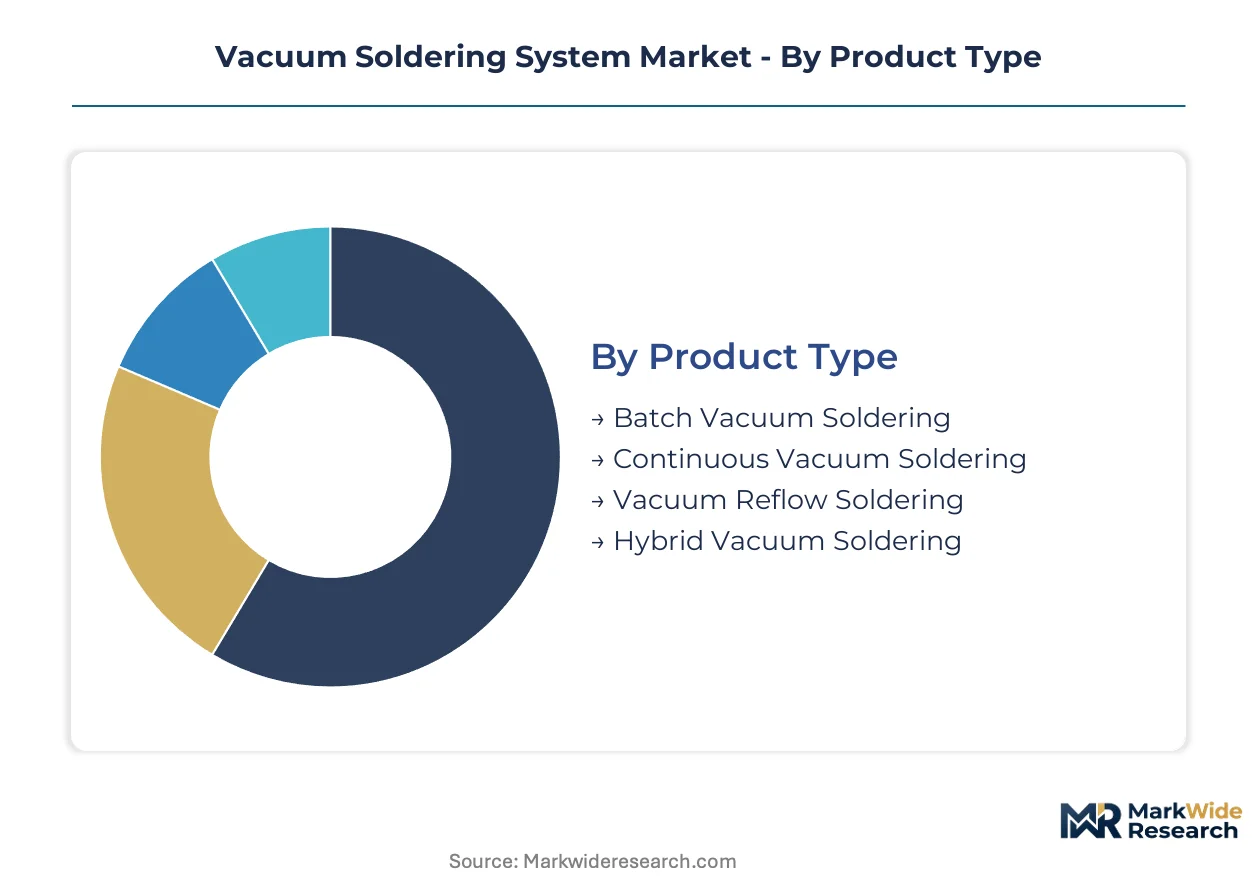
Vacuum soldering equipment configurations diverge sharply across thermal process requirements and production economics. Equipment vendors structure service contracts and spare parts programs around distinct product architectures, creating divergent aftermarket revenue streams.
Product Type:
After-sales-service intensity varies dramatically across vacuum soldering architectures, with continuous systems demanding predictive maintenance contracts and batch platforms relying on episodic technical support.
- Batch Vacuum Soldering:Sealed chamber systems process discrete substrate lots under programmable vacuum and thermal profiles. Flexibility for prototype and low-volume production drives demand at Hsinchu packaging houses handling copper-pillar flip-chip development.
- Continuous Vacuum Soldering:Inline conveyorized chambers enable uninterrupted substrate flow with integrated gas purging and zone-controlled heating. Automotive IGBT lines in Germany specify these systems for throughput metrics exceeding 500 units per hour.
- Vacuum Reflow Soldering:Modified atmospheric reflow platforms with vacuum extraction modules for void reduction. Compact footprint suits contract manufacturers in Seoul metropolitan clusters with space-constrained SMT lines.
- Hybrid Vacuum Soldering:Combines batch precision with continuous material handling for mid-volume power module assembly. Emerging configuration gaining traction at SiC substrate bonding facilities.
By volume, batch systems lead installed base. By growth pace, continuous vacuum soldering is climbing the fastest.
Technology:
Heating modality selection governs thermal uniformity specifications and energy consumption profiles across substrate formats.
- Infrared Heating:Quartz lamp arrays deliver rapid ramp rates with zone-selectable intensity. Dominates legacy semiconductor packaging capacity in Taiwan due to mature process libraries and technician familiarity.
- Convection Heating:Forced gas circulation achieves uniform temperature distribution across large ceramic substrates. SiC power module manufacturers in South Korea specify convection systems for 300mm+ substrate formats.
- Microwave Heating:Dielectric heating enables selective energy coupling with reduced thermal mass sensitivity. Niche deployment at research labs exploring fluxless bonding of temperature-sensitive photonic components.
- Induction Heating:Eddy current generation provides rapid, contactless substrate heating. Limited adoption for metallic substrate applications requiring localized thermal zones.
- Ultrasonic Heating:Acoustic energy assists solder wetting and void expulsion in specialized die-attach processes. Experimental deployment at medical device contract manufacturers qualifying implantable electronics.
Infrared retains largest installed capacity. Convection is gaining share fastest among new automotive power module procurement.
Application:
End-use sector requirements fragment equipment specifications across thermal profile tolerances, documentation standards, and chamber size demands.
- Electronics Assembly:High-mix PCB and component soldering with void-reduction requirements for BGA and QFN packages. Contract assemblers in Taiwan drive volume demand for flexible batch configurations.
- Automotive Components:IGBT, SiC, and power module bonding with sub-5% void mandates under EU RoHS. German Tier-1 suppliers specify continuous systems with inline X-ray quality feedback.
- Aerospace Equipments:High-reliability soldering for avionics with extensive process documentation and traceability requirements. US defense contractors impose AS9100 quality system compliance.
- Medical Devices:Implantable and diagnostic electronics with FDA quality system regulation and ISO 13485 validation. Extended equipment qualification timelines compress vendor development roadmaps.
- Telecommunication Equipment:Base station and optical transceiver assembly with precision pressure control for photonic packages. 5G infrastructure deployment expands demand at South Korean network equipment manufacturers.
Electronics assembly commands largest equipment volume. Automotive components show steepest expansion trajectory.
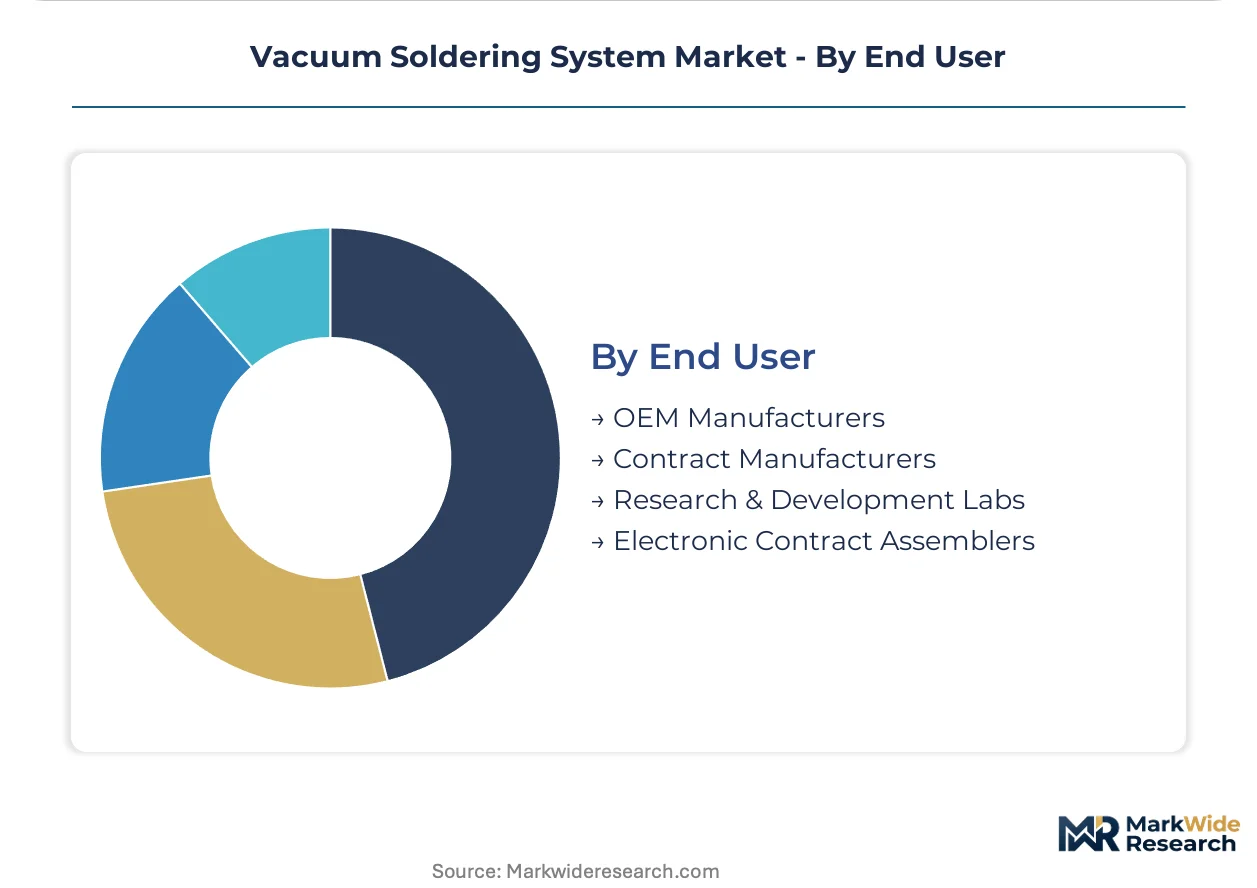
End User:
Customer type shapes procurement patterns, with OEMs favoring captive process development and contract manufacturers prioritizing equipment flexibility.
- OEM Manufacturers:Vertically integrated electronics producers with dedicated vacuum soldering capacity for proprietary product lines. Automotive power module OEMs in Germany invest in continuous systems with integrated process control.
- Contract Manufacturers:Electronics manufacturing services providers serving multiple customers with varying thermal process requirements. Taiwanese and South Korean EMS firms maintain diverse batch system portfolios.
- Research & Development Labs:Universities and corporate innovation centers exploring novel soldering chemistries and wide-bandgap semiconductor attachment. Process flexibility outweighs throughput economics.
- Electronic Contract Assemblers:Specialized providers focusing on high-reliability or regulated industries with intensive documentation requirements. Medical device assemblers in Massachusetts and California clusters dominate this segment.
Contract manufacturers represent largest equipment volume. OEM manufacturers are expanding capacity fastest amid automotive electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification and semiconductor packaging expansion concentrate vacuum soldering system procurement across three dominant buyer archetypes: German Tier-1 power module suppliers, Taiwanese flip-chip packaging houses, and South Korean SiC device manufacturers.
Germany
Automotive IGBT and SiC module assembly lines drive continuous vacuum soldering demand at Continental, Infineon, and Bosch facilities. EU RoHS void-reduction mandates and CE marking machinery directive compliance shape equipment specifications. Bavarian and Baden-Württemberg industrial clusters around Munich and Stuttgart host concentrated power electronics manufacturing capacity.
Taiwan
Flip-chip and advanced packaging expansion at TSMC backend facilities and OSATs generates batch vacuum soldering procurement for copper-pillar interconnect development. National development fund subsidies for semiconductor self-sufficiency accelerate capital equipment deployment. Hsinchu Science Park and Taichung precision machinery corridors anchor regional demand concentration.
South Korea
SiC power module manufacturing for Hyundai-Kia electric vehicle platforms expands vacuum soldering capacity requirements. KBA automotive certification and MFDS medical device standards impose quality system documentation burdens. Seoul metropolitan area and Busan-Ulsan industrial belt concentrate electronics manufacturing and automotive component assembly.
United States
Defense and aerospace electronics contractors sustain demand for high-reliability vacuum soldering with AS9100 quality system compliance. FDA quality system regulations and ISO 13485 medical device standards govern implantable electronics equipment validation. Greater Boston and California defense-aerospace clusters drive precision assembly requirements.
China
Domestic SiC substrate and power module manufacturing expansion accelerates vacuum soldering equipment procurement for BYD, CATL, and state-owned automotive electronics suppliers. GB standards and MIIT industrial policy guide equipment localization requirements. Yangtze River Delta and Pearl River Delta electronics manufacturing belts concentrate demand.
Vacuum Soldering System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented vacuum soldering system supply. European thermal process equipment heritage sustains multiple mid-scale specialists, while Asian electronics manufacturing scale concentrates procurement leverage among contract manufacturers. Three strategic archetypes dominate: precision photonics specialists, automotive power module system integrators, and batch-flexibility providers for high-mix packaging. M&A activity targets complementary heating technology portfolios, and geographic expansion through localized application engineering accelerates among vendors seeking Asian market share.
Among German-based thermal process specialists, Kurtz Ersa, PINK GmbH Thermosysteme, and Rehm Thermal Systems exemplify the European equipment heritage archetype with established automotive electronics customer relationships. These GmbH-structured entities occupy positions sustained by technical service density in power module assembly lines. Centrotherm represents the Asia-Pacific market access archetype through localized thermal process engineering capabilities. Palomar Technologies anchors North American precision positioning within photonic and aerospace electronics segments.
| Leading Market Players |
|---|
| Kurtz Ersa |
| PINK GmbH Thermosysteme |
| Palomar Technologies |
| Centrotherm |
| BTU International |
| Rehm Thermal Systems |
| ASSCON Systemtechnik-Elektronik GmbH |
| Heller Industries |
| SMT Wertheim |
| Others |
Pricing and Supply Chain Analysis
East Asian industrial gas networks concentrating high-purity nitrogen and forming gas supply for vacuum chamber purging concentrate margin pools with equipment vendors bundling gas management systems into long-term service contracts. Automotive power module manufacturers in Germany and South Korea absorb input cost volatility through indexed maintenance agreements while prototype houses in Taiwan favor unbundled hardware procurement with spot gas purchasing.
Pricing Analysis
Cost-plus contracts with steel and quartz indexation dominate continuous vacuum soldering system procurement for automotive IGBT lines. Pricing stratifies across CE-marked premium systems, standard industrial configurations, and economy batch platforms for prototype development. Cost compression in economy tiers is intensifying because Chinese equipment vendors are expanding convection heating offerings at lower price points. Contract manufacturers in Taiwan exhibit highest price sensitivity due to high-mix, low-volume production economics, while German Tier-1 automotive suppliers prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
High-purity gas feedstock draws from South Korea, Taiwan, and Japan industrial gas production clusters. Vacuum chamber fabrication rests on specialized steel alloys from German and Japanese metallurgical suppliers, while quartz lamp arrays for infrared heating systems source from Chinese and American optical component manufacturers. Single-source vulnerability concentrates in large-format ceramic substrate supply for SiC power modules. Distribution runs through direct equipment vendor sales teams for automotive OEMs and regional distributor networks serving contract manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum soldering equipment markets increasingly function as service-attach businesses where predictive maintenance contracts and process engineering retainers expand faster than hardware shipments. Vendors capturing recurring revenue from gas management optimization and thermal recipe development outpace competitors reliant on transactional equipment sales.
For Market Incumbents: Pre-empt Chinese equipment vendors in convection heating segments by accelerating CE-marked large-format chamber development for SiC substrate bonding. Lock in automotive OEM relationships through captive process engineering teams embedded at Continental and Infineon facilities. Defend against unbundled service competition by integrating real-time void detection modules that create switching costs through proprietary data archives.
For New Entrants and Emerging Players: Pursue India PLI scheme subsidies for semiconductor assembly equipment by establishing localized application engineering in Gujarat packaging corridors. Target photonic package integration for AI datacenter interconnects where precision vacuum pressure control commands premium positioning. Enter through hybrid heating technology partnerships with established infrared vendors seeking convection capability gaps.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous vacuum soldering configurations as automotive line-integration requirements demand larger cleanroom footprints and integrated quality feedback systems. Long-term viability favors vendors with installed base density enabling aftermarket service scaling rather than pure-play equipment manufacturers. Monitor CE marking compliance timeline extensions as an inflection signal for European market access friction affecting revenue recognition predictability.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Expansion | Recurring revenue from automotive IGBT lines at Bosch and Hyundai-Kia facilities stabilizes vendor cash flows. |
| Convection-Infrared Hybrid Heating Development | Combined thermal technology addresses 300mm+ SiC substrate uniformity requirements for South Korean power module manufacturers. |
| India PLI Scheme Localization | Gujarat and Karnataka semiconductor assembly incentives attract vacuum soldering deployment for emerging packaging facilities. |
| Real-Time Void Detection Integration | Inline X-ray feedback systems at German Tier-1 suppliers compress process development cycles and reduce scrap rates. |
| PFAS-Free Seal Material Qualification | ECHA REACH compliance for vacuum chamber elastomers protects European medical and automotive electronics market access. |
Research Methodology
A standing panel of vacuum process engineering directors, automotive power module procurement leads, semiconductor packaging operations managers, and thermal equipment aftermarket service heads provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with equipment vendor technical sales teams and validation against secondary sources including SEC filings from thermal process equipment manufacturers, ECHA REACH substance restriction updates, and Korea Trade-Investment Promotion Agency semiconductor equipment import data. Bottom-up equipment shipment tracking and top-down electronics manufacturing capacity analysis were triangulated to constrain volume estimates.
Scenario-bracketing around automotive electrification penetration rates and wide-bandgap semiconductor adoption curves bounded the projection range across the analysis window. Segmentation modeling incorporated product type, heating technology, application sector, and end-user procurement pattern dimensions. CAGRs were derived from equipment replacement cycle analysis and capacity expansion announcements at TSMC backend facilities, Infineon power module lines, and emerging India semiconductor packaging ventures. Forecast inputs included industrial gas price indices and CE marking compliance timeline distributions.
Sensitivities concentrate around SiC substrate format evolution and REACH substance restriction scope expansion. Forecasts reflect documented assumptions regarding automotive IGBT line automation trajectories and photonic package integration timelines. Cross-checking against SEMI equipment shipment databases and national customs records for vacuum soldering system trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
Global Semiconductor Wafer Polishing and Grinding Equipment Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Sputtering Equipment Cathode Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market