
 United States Chip Mounter Market | 2026-2036
United States Chip Mounter Market Size, Share, and Industry Trends Forecast 2026-2036
United States Chip Mounter Market Intelligence
The capital-intensity divergence between high-volume OEMs and niche automation houses is unwinding as domestic fab buildouts force equipment makers to choose between scale and specialization. Fuji Corporation leverages its precision motion-control heritage to anchor premium placements in advanced packaging nodes. Yamaha Motor competes through modular platform architectures that reduce retooling downtime for mid-tier contract manufacturers. Hanwha Precision Machinery sustains aggressive positioning in the high-speed segment by controlling servo-drive supply chains internally.
Chip mounters are precision electromechanical systems that place surface-mount devices onto printed circuit boards with placement accuracy typically measured in microns, operating through pick-and-place heads, vision alignment subsystems, and conveyor-fed substrate handling. Their primary purpose is to automate the mounting stage of PCB assembly for consumer electronics, automotive control modules, and telecommunications infrastructure. SMD mounters dominate unit volume as miniaturization trends in smartphones and wearables sustain demand for sub-millimeter component handling, while high-speed mounters capture expanding margin pools in server and base-station board production where throughput rates determine fab economics. Vision systems technology leads replacement cycles as manufacturers integrate AI-enhanced defect detection directly into placement heads, reducing downstream inspection bottlenecks.
FDA device-quality standards for automotive medical-grade electronics and FCC electromagnetic compatibility requirements shape equipment certification pathways, while OSHA machine-safety regulations mandate guarding protocols that influence gantry and feeder designs. The SEC's climate-disclosure rules are pressing publicly traded electronics manufacturers to document supply-chain emissions, indirectly favoring domestic mounter deployments that shorten component shipping distances. Stakeholders must weigh whether captive equipment-service capabilities or third-party automation partnerships better align with the capital-deployment rhythms of CHIPS Act-funded fabs.
Market Dynamics
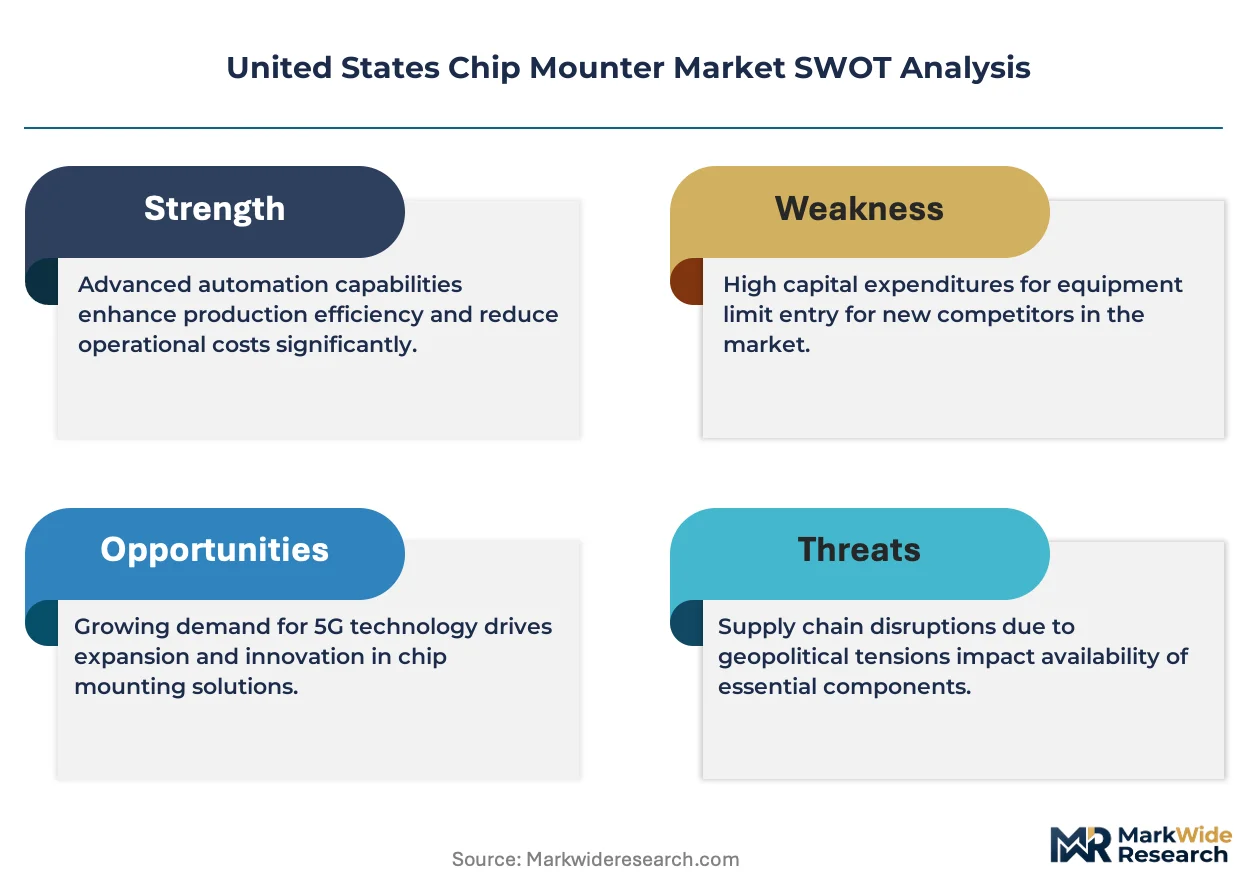
Domestic fab construction under the CHIPS Act is compressing equipment procurement timelines as Arizona, Texas, and Ohio corridors compete for finite installation engineering capacity. This capital-deployment surge is restructuring how mounter vendors allocate technical service resources across multiple simultaneous buildouts.
Growth Catalysts
- CHIPS Act funding framework:Federal capital subsidies are redirecting semiconductor packaging investment toward domestic corridors, concentrating demand for precision placement systems in federally designated fabrication zones.
- EV powertrain scaling:Automotive electronics manufacturers are accelerating procurement of high-speed mounters as electric vehicle inverter and battery management module production expands across Michigan and Tennessee assembly networks.
- ADAS module proliferation:Advanced driver-assistance system sensor integration is sustaining demand for micron-accuracy placement in radar and lidar PCB assemblies serving Detroit and Southern California automotive clusters.
Market Restraints
- Precision motion-component import concentration:Linear motor and encoder supply chains remain concentrated in East Asian manufacturing bases, exposing domestic mounter assembly to geopolitical shipping disruptions.
- Installation engineering scarcity:Qualified field service technicians for gantry calibration and vision system alignment are concentrated among a small cohort of OEM-trained specialists.
- OSHA machine-safety compliance costs:Guarding protocol mandates for high-speed pick-and-place heads add non-trivial mechanical complexity and documentation burden to equipment certification pathways.
Strategic Opportunities
- Ohio fabrication corridor emergence:Intel's announced packaging investments in the Midwest are creating greenfield demand for mounter installations without incumbent vendor relationships.
- AI-enhanced vision convergence:Machine learning defect detection integrated directly into placement heads is opening premium pricing tiers for equipment reducing downstream inspection station counts.
- Service contract unbundling:Third-party automation partnerships are displacing traditional captive maintenance models among mid-tier contract manufacturers seeking operational flexibility.
Industry Challenges
- Multi-axis motion control expertise gap:The specialized skill set combining servo tuning, vision alignment, and conveyor synchronization remains scarce in domestic labor markets.
- Legacy SMT line integration friction:New mounter generations must communicate with heterogeneous existing equipment across decades-old factory networks without unified control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Chip Mounter Market |
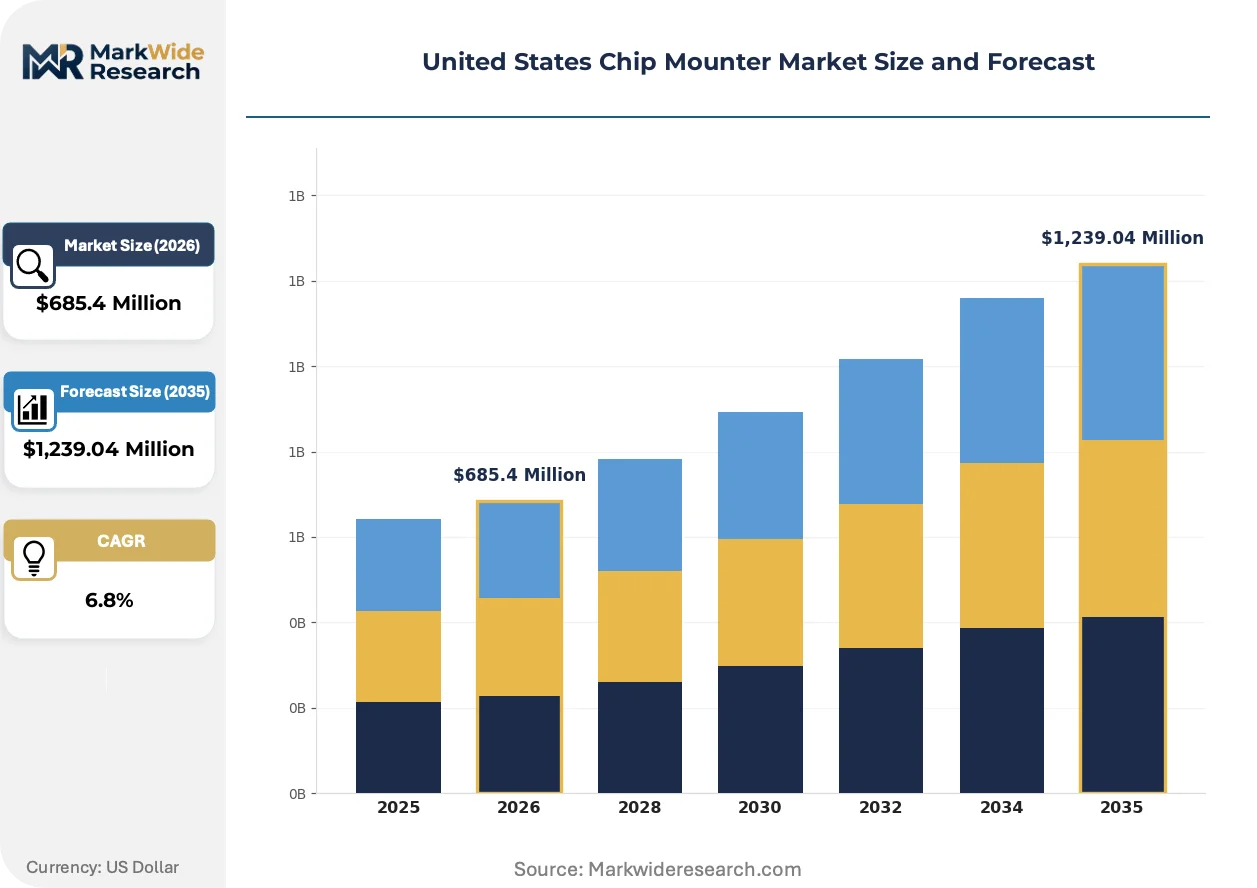
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SMD Mounters, THT Mounters, Hybrid Mounters, High-Speed Mounters Technology: Laser Technology, Hybrid Technology, Optical Inspection, Vision Systems End User: Consumer Electronics, Telecommunications, Automotive, Industrial Equipment Size: Small Size, Medium Size, Large Size, Ultra Large Size |
| Companies Covered | ASM Assembly Automation, Fuji Corporation, Yamaha Motor, Panasonic Corporation, Mycronic AB, Hanwha Precision Machinery, Juki Corporation, Samsung Techwin, Universal Instruments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Chip Mounter Market Strategic Shifts & Innovations
Equipment intelligence is migrating from peripheral quality stations directly into placement heads, compressing inspection workflows and reshaping factory floor layouts. This convergence of motion precision and real-time analytics is redefining competitive differentiation among domestic system vendors.
AI-enhanced vision alignment is supplanting rule-based image processing in high-mix PCB assembly environments. Tier-one automotive module manufacturers in Michigan and Texas are adopting these systems at accelerated replacement cycles. The technology is supplanting downstream optical inspection stations and enabling single-pass assembly flows that reduce factory footprint requirements.
SEC climate-disclosure rules are pressing publicly traded electronics manufacturers to document supply-chain emissions from semiconductor packaging operations. Equipment procurement committees are now weighting domestic mounter deployments more heavily in capital allocation decisions. Medical-grade and automotive PCB producers in Minnesota and Massachusetts are responding fastest to these documentation requirements.
Outcome-based equipment performance contracts are displacing traditional capital purchase models among mid-volume contract manufacturers. Arizona and Texas fab-adjacent assemblers are piloting throughput-guarantee arrangements where vendors retain ownership risk. This shift is most visible among automotive electronics suppliers seeking to preserve balance-sheet flexibility during CHIPS Act-funded capacity expansions.
United States Chip Mounter Market Segmentation
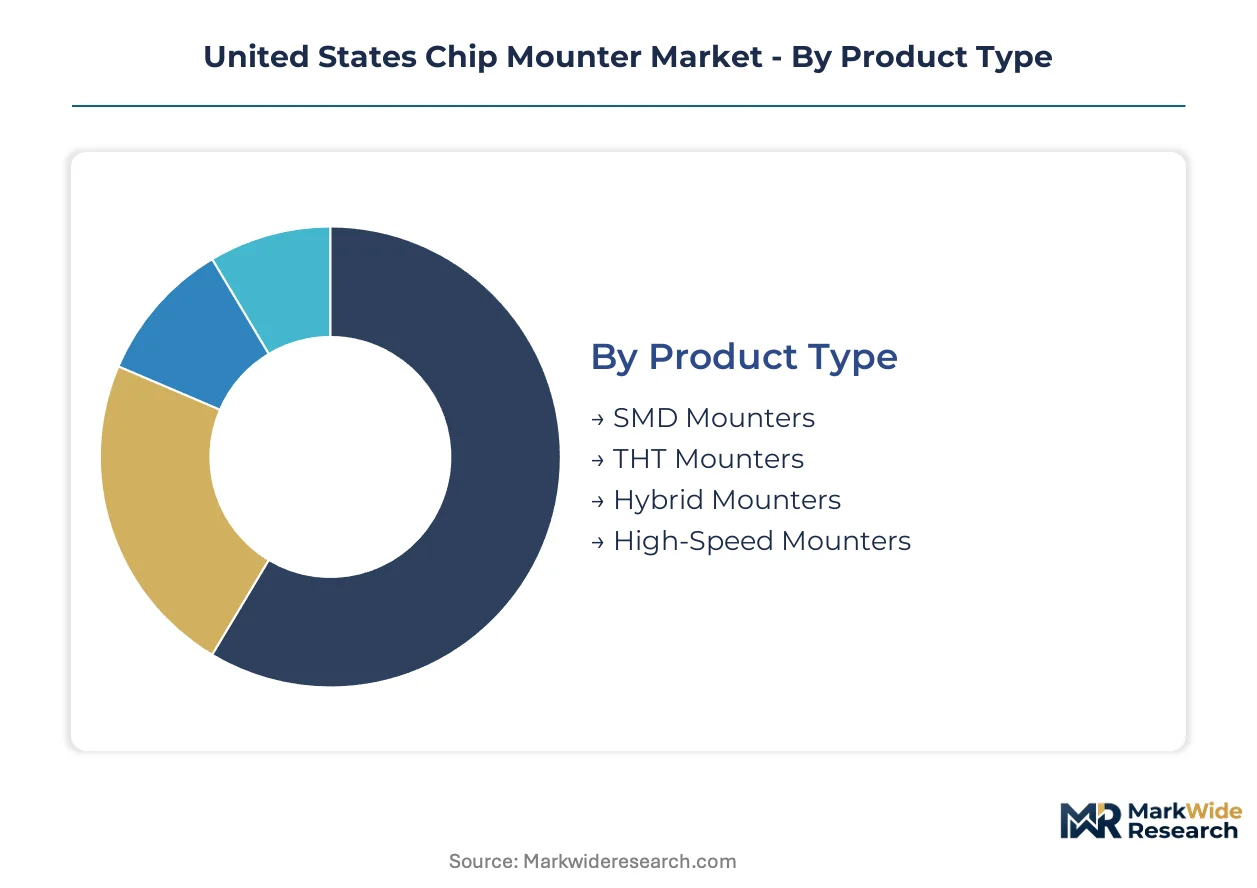
Segmentation reveals how chip mounter demand fragments across precision requirements, throughput economics, and substrate scale. Equipment specification mismatches with end-use duty cycles drive replacement cycles and vendor selection criteria across domestic manufacturing corridors.
Product Type:
SMD mounters face the strongest substitution pressure as miniaturization requirements in wearables and medical devices push placement accuracy below 25 microns, compressing margins for legacy mechanical alignment systems.
- SMD Mounters:These systems handle surface-mount devices with placement precision measured in single-digit microns, utilizing vacuum pick-up heads and vision alignment subsystems. Demand concentrates in Arizona and Texas consumer electronics packaging lines where smartphone board miniaturization sustains equipment refresh cycles. Component shrinkage below 01005 package sizes is forcing gantry stiffness upgrades.
- High-Speed Mounters:Optimized for throughput rates exceeding 100,000 components per hour through parallel placement heads and continuous board feeding mechanisms. Michigan and Tennessee automotive module manufacturers deploy these for inverter and battery management PCB production where line speed determines per-unit economics. The CHIPS Act packaging buildouts are accelerating procurement timelines for these systems.
- THT Mounters:Through-hole technology systems for legacy industrial and power electronics requiring mechanical component insertion force.
- Hybrid Mounters:Dual-capability platforms combining surface-mount and through-hole processing for mixed-technology PCB assembly.
SMD mounters anchor the volume base while high-speed mounters gain share at the steepest rate.
Technology:
Cost tier stratification separates premium vision-integrated systems from baseline mechanical alignment platforms, with price differentials exceeding threefold between entry-level and AI-enhanced configurations.
- Vision Systems:Camera-based alignment subsystems employing multi-angle illumination and pattern recognition algorithms for sub-micron placement accuracy. Ohio and Arizona fabs specify these for advanced packaging nodes where die placement precision determines yield. AI-enhanced defect detection integrated directly into placement heads is displacing downstream optical inspection stations.
- Optical Inspection:Post-placement verification modules using high-resolution imaging to detect offset, rotation, and solder paste defects. Massachusetts medical-grade electronics manufacturers require these for FDA device-quality documentation. The technology is converging with placement heads to enable single-pass assembly flows.
- Laser Technology:Non-contact alignment and component measurement using structured light projection for transparent or reflective substrate handling.
- Hybrid Technology:Combined mechanical and optical sensing approaches for high-mix production environments with frequent changeovers.
Vision systems command the premium tier while optical inspection expands most quickly through convergence with placement head intelligence.
End User:
Application-specific duty cycles range from high-mix, low-volume medical prototyping to continuous automotive mass production, dictating feeder capacity and changeover automation requirements.
- Automotive:Radar, lidar, and powertrain PCB assembly requiring IPC-A-610 Class 3 reliability standards and traceable placement data. Detroit and Southern California clusters are scaling ADAS module production with micron-accuracy gantry systems. NHTSA functional safety requirements are mandating redundant vision verification.
- Consumer Electronics:Smartphone, tablet, and wearable board assembly characterized by extreme miniaturization and rapid product cycles. Texas and Arizona contract manufacturers run these lines at maximum throughput with automated feeder replenishment.
- Telecommunications:Base station and server motherboard production where board size and component variety demand flexible placement platforms.
- Industrial Equipment:Control system and power electronics PCB assembly with emphasis on durability and extended service intervals.
Consumer electronics anchors the volume base while automotive climbs the fastest on EV powertrain scaling.
Size:
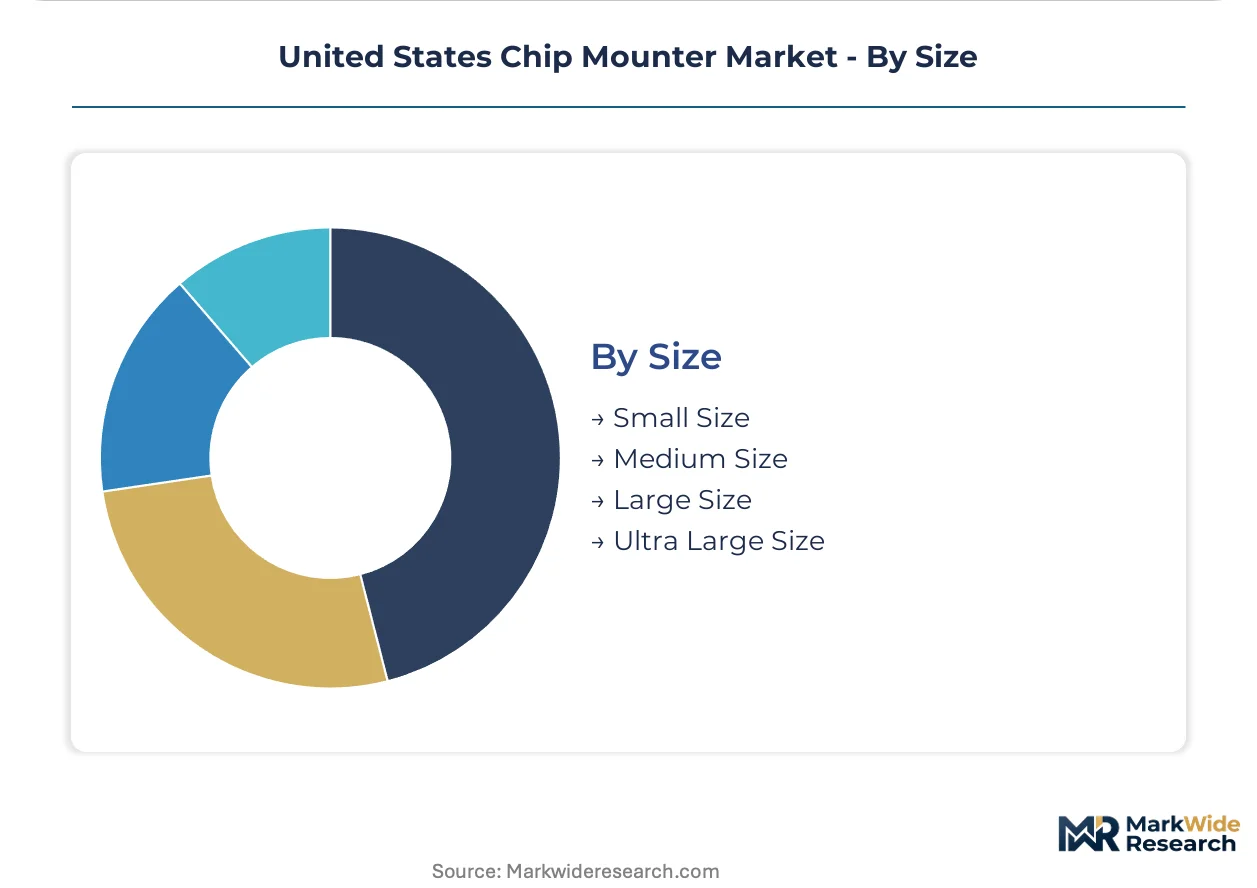
Volume concentration favors medium-format systems serving standard PCB dimensions, while substrate scale extremes create specialized demand pockets with distinct competitive dynamics.
- Medium Size:Platforms accommodating PCB dimensions up to 460mm x 510mm, capturing the majority of smartphone, automotive, and industrial control board production. Arizona and Texas fab-adjacent assemblers standardize on this format for operational flexibility across contract manufacturing portfolios.
- Large Size:Systems handling server motherboard and telecommunications backplane dimensions exceeding 600mm on longest edge. Ohio and Arizona hyperscale computing packaging lines require these for data center infrastructure buildouts. Gantry stiffness and thermal stability become critical specification parameters.
- Small Size:Compact benchtop or cell-integrated systems for prototyping and low-volume medical electronics.
- Ultra Large Size:Specialized platforms for display driver boards and aerospace panel assemblies with custom conveyor architectures.
Medium size systems anchor the volume base while large size configurations gain share fastest on server and base station demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Arizona and Texas fabrication corridors where CHIPS Act subsidies compress procurement timelines, while Midwest assembly networks absorb margin pressure from engineering scarcity and legacy integration burdens.
Arizona
TSMC and Intel packaging investments drive precision placement system demand across Phoenix and Tucson metro areas. NHTSA functional safety standards for automotive radar modules mandate redundant vision verification systems. Chandler and Gilbert industrial parks host the densest concentration of high-speed mounter installations serving fab-adjacent contract manufacturers.
Texas
Samsung Austin Semiconductor expansion and emerging EV powertrain clusters sustain dual demand vectors for SMD and high-speed platforms. SEC climate-disclosure rules press Dallas-Fort Worth assemblers to document supply-chain emissions, favoring domestic equipment deployments. Austin and Richardson electronics corridors concentrate mid-tier contract manufacturers seeking operational flexibility.
Ohio
Intel's announced packaging investments in the Midwest create greenfield demand without incumbent vendor relationships. OSHA machine-safety regulations for high-speed pick-and-place heads add mechanical complexity to equipment certification pathways. Columbus and Cleveland metro areas anchor emerging automotive electronics clusters serving Detroit supply chains.
Michigan
ADAS module proliferation and EV inverter production sustain demand for micron-accuracy gantry systems across Detroit and Ann Arbor automotive corridors. NHTSA traceable placement data requirements shape equipment specification for radar and lidar PCB assembly. Grand Rapids contract manufacturers scale battery management module production with compressed installation timelines.
Tennessee
Automotive electronics suppliers preserve balance-sheet flexibility through outcome-based equipment performance contracts during capacity expansions. EPA emissions documentation requirements influence capital allocation toward domestic mounter deployments. Nashville and Memphis industrial zones concentrate high-speed mounter installations for powertrain PCB production.
United States Chip Mounter Market Key Industry Players
Concentration sits with precision motion-control specialists and modular platform architects serving distinct tier requirements. The vendor base stratifies across premium placement accuracy providers, high-speed throughput optimizers, and flexible mid-tier contract manufacturing specialists. Two dominant competitive moves define current positioning: AI-enhanced vision convergence into placement heads reducing downstream inspection stations, and service contract unbundling displacing traditional captive maintenance models.
Among Japanese precision equipment manufacturers, Fuji Corporation and Yamaha Motor occupy differentiated archetype positions—Fuji leveraging heritage in advanced packaging nodes, Yamaha competing through modular architectures reducing retooling downtime. Hanwha Precision Machinery anchors the high-speed segment through internal servo-drive supply chain control. These three exemplify how equipment vendors allocate technical service resources across simultaneous CHIPS Act-funded buildouts.
| Leading Market Players |
|---|
| ASM Assembly Automation |
| Fuji Corporation |
| Yamaha Motor |
| Panasonic Corporation |
| Mycronic AB |
| Hanwha Precision Machinery |
| Juki Corporation |
| Samsung Techwin |
| Universal Instruments |
| Others |
Cost & Logistics Intelligence
Capacity utilization at domestic CHIPS Act fabrication corridors concentrates procurement leverage among Arizona and Texas contract manufacturers, compressing price floors for standard-configured systems while elevating premiums for AI-enhanced vision platforms. This scale asymmetry forces equipment vendors to absorb margin pressure on baseline SMD mounters while extracting value from advanced packaging configurations serving Intel and TSMC packaging lines.
Pricing Analysis
Configured-to-order pricing spreads threefold above standard platform baselines, with AI-integrated vision systems commanding the upper tier against mechanical-alignment alternatives. Pricing stratifies across premium, standard, and economy tiers based on placement accuracy certification and after-sales service bundling. Cost compression in the standard tier intensifies because mid-tier contract manufacturers consolidate purchasing through third-party automation partnerships. Automotive electronics manufacturers in Michigan and Tennessee exhibit the lowest price sensitivity due to NHTSA traceability requirements, while consumer electronics assemblers in Arizona prioritize throughput economics over feature depth.
Supply Chain Analysis
Port congestion along transpacific trade lanes elevates inbound logistics costs for linear motors and precision encoders sourced from Japan and Taiwan. Component supply concentrates in East Asian manufacturing bases, with servo drives drawing from South Korean fabrication and granite gantry substrates resting on Italian and German quarry networks. Single-source vulnerability pervades high-resolution camera modules for vision alignment subsystems. Distribution runs through OEM-direct channels for Tier 1 automotive accounts, while mid-tier contract manufacturers procure through regional automation distributors with field service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic semiconductor packaging buildouts represent an early-cycle expansion story, with CHIPS Act capital deployment accelerating equipment replacement timelines beyond historical semiconductor capital expenditure rhythms.
For Market Incumbents: Secure field service technician capacity across simultaneous Arizona, Texas, and Ohio buildouts before installation engineering scarcity hardens into a binding constraint. Deepen backward integration into servo-drive production to offset East Asian component supply risks. Defend premium positioning by embedding AI-enhanced defect detection directly into placement heads, displacing downstream optical inspection vendors.
For New Entrants and Emerging Players: Differentiate on modular platform architectures that minimize retooling downtime for high-mix contract manufacturers in the Austin and Richardson corridors. Target the Ohio fabrication corridor where Intel's greenfield investments have not yet solidified incumbent vendor relationships. Penetrate through outcome-based performance contracts that transfer ownership risk from balance-sheet-constrained automotive electronics suppliers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision motion-control specialists with captive vision algorithm development capabilities over commodity high-speed platform assemblers. Long-term viability hinges on service contract unbundling trends and the displacement of traditional captive maintenance models. Monitor EPA emissions documentation requirements as the signal to watch for accelerated domestic equipment deployment decisions among publicly traded electronics manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Vision Integration | Machine learning defect detection embedded in placement heads reduces downstream inspection station counts for Ohio advanced packaging lines. |
| Backward Integration into Servo Drives | In-house production of precision motion components mitigates East Asian supply chain exposure for domestic gantry assembly operations. |
| Outcome-Based Performance Contracts | Throughput-guarantee arrangements preserve balance-sheet flexibility for Tennessee automotive electronics suppliers during capacity expansions. |
| Field Service Network Expansion | Installation engineering capacity concentrated in Arizona and Texas corridors addresses multi-site CHIPS Act buildout demands. |
| Modular Platform Architecture Development | Reduced retooling downtime captures high-mix contract manufacturing demand across Austin and Richardson electronics clusters. |
Research Approach
Cross-validation between OEM procurement officer interviews and SEC equipment capex disclosures anchors the qualitative findings on capital allocation priorities. Primary fieldwork encompassed semiconductor packaging engineers, automation integration specialists, field service technicians, and contract manufacturing operations directors. Secondary sources included CHIPS Act funding announcements, OSHA machine-safety regulatory filings, EPA emissions documentation requirements, and NHTSA automotive electronics standards. Bottom-up equipment shipment tallies triangulated against top-down fab construction pipeline estimates.
Sensitivity analysis around CHIPS Act appropriation timing and EV powertrain production scaling informs the analytical framework across the projection horizon. Segmentation dimensions encompass product type, technology tier, end-use application, and regional fabrication corridor. CAGRs derive from equipment procurement timeline compression observed in Arizona, Texas, and Ohio buildouts. Forecast inputs incorporate Intel and TSMC packaging investment schedules alongside NHTSA functional safety mandate adoption curves.
Decision-makers should treat outputs as directional under sustained CHIPS Act funding execution and domestic EV production scaling assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without contingency for geopolitical trade disruption or semiconductor demand cyclicality. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
Global Semiconductor Wafer Polishing and Grinding Equipment Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
Chip Probing Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Chip Mounter Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Partition Inserter Machines Market