
 Global Semiconductor Front-End Equipment Market | 2026-2036
Global Semiconductor Front-End Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Front-End Equipment Market Foresight
Taiwan's foundry capacity expansion is tilting procurement volumes toward advanced lithography and deposition systems. Applied Materials leverages its broad process technology portfolio to sustain equipment shipments across multiple wafer fabrication nodes. ASML anchors extreme ultraviolet lithography supply through its monopoly on high-NA EUV scanners. Tokyo Electron competes aggressively in etching and cleaning segments where process precision requirements intensify with each node shrink.
Semiconductor front-end equipment encompasses the machinery used to fabricate integrated circuits on silicon wafers before packaging, including systems that achieve patterning resolution below three nanometers through extreme ultraviolet wavelengths. These tools perform film deposition, material removal, ion implantation, and critical dimension measurement under vacuum conditions with sub-angstrom precision, enabling the transistor density gains that power advanced computing, storage, and communications devices. Photolithography equipment commands the largest capital allocation share due to ASML's EUV scanner dominance and the technology's irreplaceable role in sub-seven-nanometer production. Deposition systems, particularly atomic layer deposition platforms, represent the fastest-growing equipment category as three-dimensional NAND stacking and gate-all-around transistor architectures multiply film layer counts exponentially. Etching equipment maintains structural importance as chip designs transition from FinFET to nanosheet geometries, requiring increasingly anisotropic plasma etch profiles.
The EPA enforces stringent emissions controls on perfluorinated compound releases from CVD and etch processes, compelling equipment makers to integrate abatement systems or face foundry exclusion. REACH restrictions on hazardous chemicals in the EU reshape material qualification pathways for deposition precursors and cleaning chemistries, extending equipment validation cycles. China's GB standards and MIIT localization directives steer domestic procurement toward NAURA Technology and other indigenous suppliers for mature-node tools. Stakeholders must monitor how export control frameworks evolve around EUV source technology, as licensing shifts could abruptly reconfigure equipment availability across China's memory and logic fabrication projects.
Market Dynamics
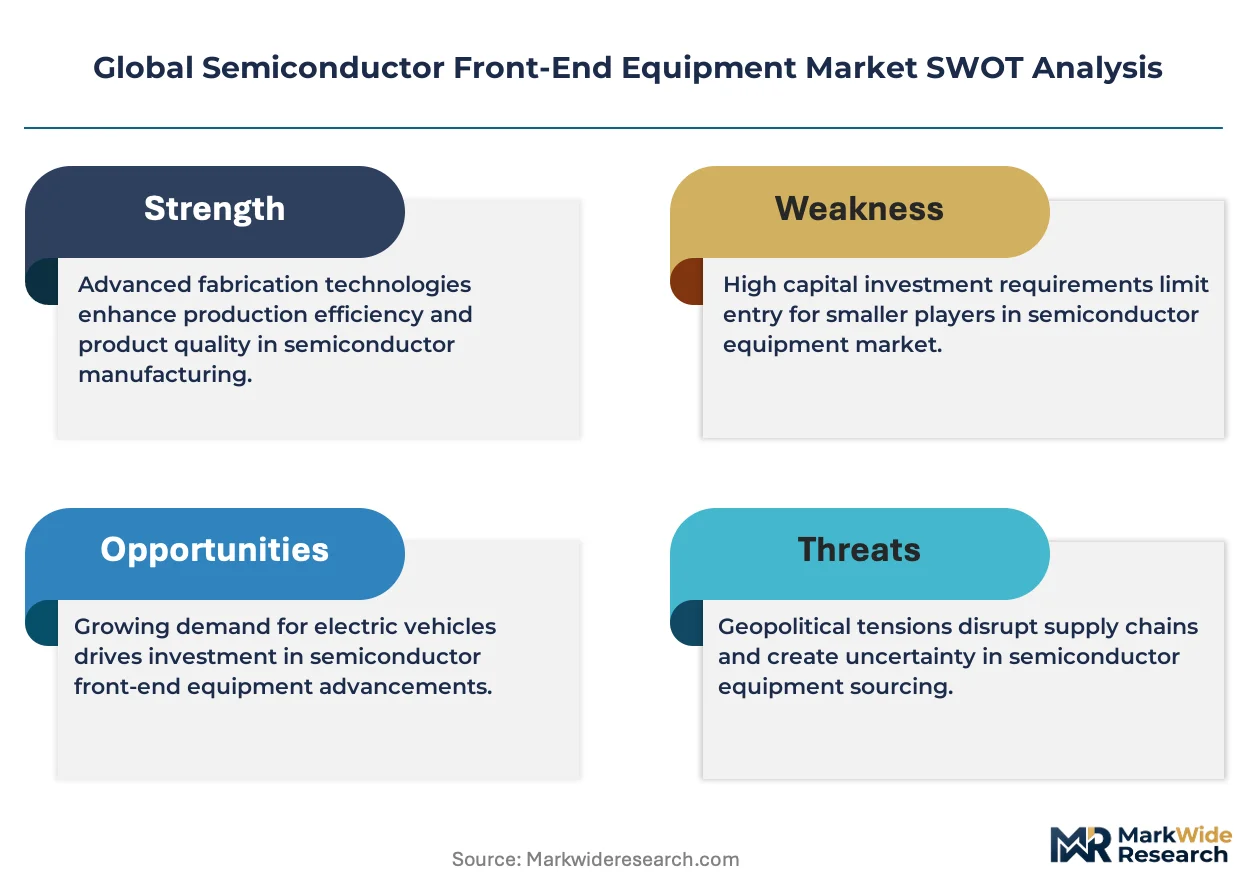
High-NA EUV lithography introduction is forcing simultaneous retooling of deposition and etch platforms to maintain process compatibility at sub-two-nanometer nodes, compressing equipment validation timelines and amplifying procurement coordination demands across foundry ecosystems.
Growth Catalysts
- CHIPS Act disbursements:US Department of Commerce funding streams accelerate cleanroom construction and tool installation timelines at domestic fabrication facilities, pulling forward equipment delivery schedules.
- Gate-all-around transistor migration:Samsung and TSMC process roadmaps mandate atomic layer deposition tool refreshes to enable nanosheet channel formation, expanding chamber counts per fab.
- Hsinchu cluster density effects:Taiwan's concentrated supplier ecosystem reduces logistics friction and enables same-day spare part availability, reinforcing procurement preference for co-located equipment vendors.
Market Restraints
- Neon gas supply concentration:Ukrainian purification infrastructure disruptions expose lithography laser dependency on single-source noble gas supply chains, triggering price volatility and rationing protocols.
- EUV source component bottlenecks:ASML's monopoly on high-NA scanner subsystems creates single-point-of-failure risk for advanced node capacity expansion timelines.
- REACH precursor authorization delays:ECHA's extended chemical safety assessments stall new deposition chemistry qualifications, elongating equipment validation cycles for European-bound tools.
Strategic Opportunities
- India's semiconductor mission:Ministry of Electronics and Information Technology production-linked incentives attract foundry investments in Gujarat and Karnataka, opening greenfield equipment procurement markets.
- Photonics-electronics convergence:Silicon photonics packaging requirements drive heterogeneous integration tool demand, expanding addressable market beyond traditional logic and memory verticals.
- Carbon border adjustment mechanism:EU CBAM implementation favors equipment platforms with integrated abatement systems, creating preference differentiation for low-emission deposition and etch technologies.
Industry Challenges
- Plasma physics expertise scarcity:Specialized process engineering talent for high-aspect-ratio etch development commands premium compensation, constraining toolmaker R&D velocity.
- Multi-node tool qualification overhead:Simultaneous support for planar, FinFET, and nanosheet architectures fragments engineering resources and extends development cycles.
- Export license uncertainty:Bureau of Industry and Security Entity List restrictions complicate sales channel planning for China-bound mature-node equipment, requiring parallel compliance and market-access strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Front-End Equipment Market |
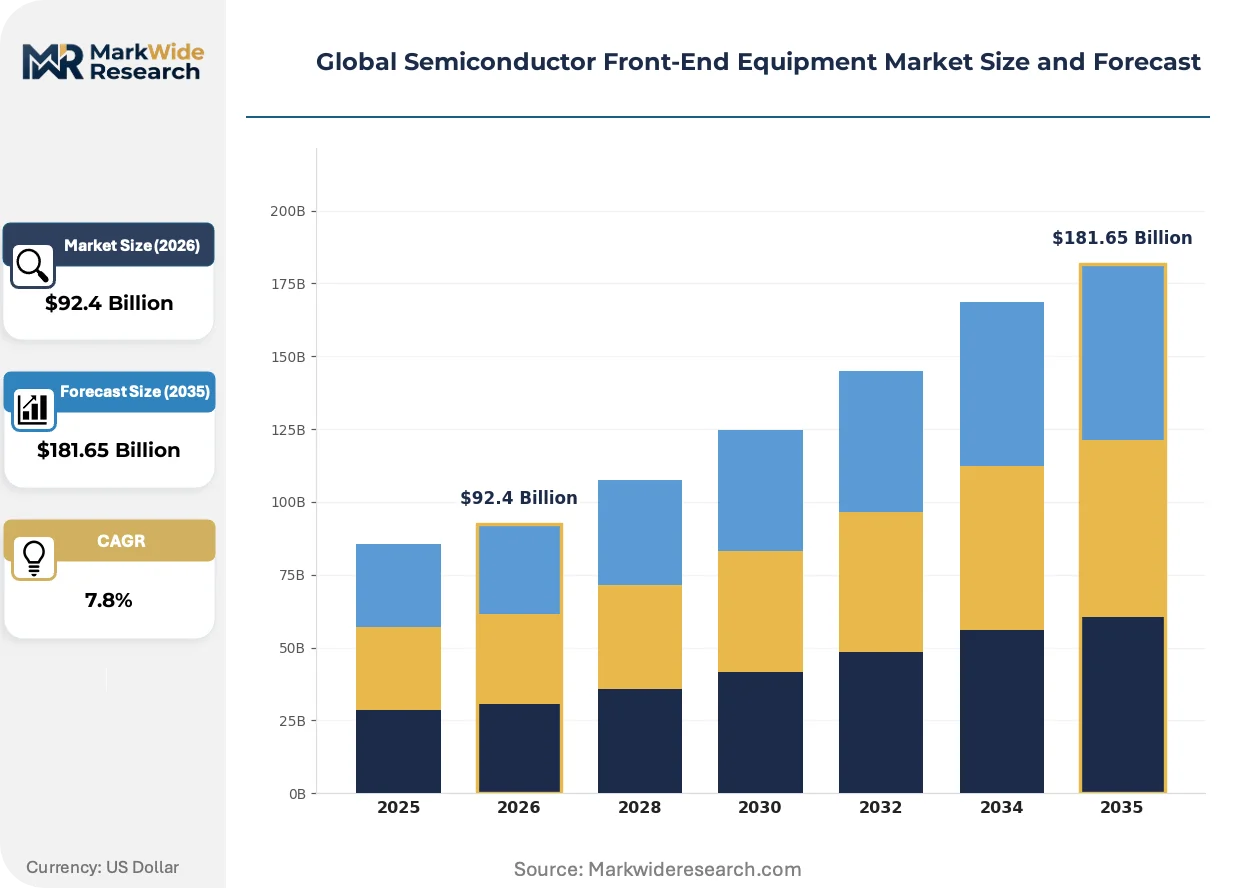
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $181.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Photolithography, Deposition, Etching, Implantation, Cleaning, Metrology Technology: Extreme Ultraviolet, Deep Ultraviolet, Atomic Layer Deposition, Chemical Vapor Deposition, Plasma Etching, Electron Beam Lithography Application: Memory Chips, Logic Devices, Analog Chips, Microelectromechanical Systems, Power Devices, Sensors End User: Foundries, IDM Companies, Assembly & Test Facilities, Fabless Companies, Pure-Play Manufacturers, Research Laboratories |
| Companies Covered | Applied Materials, ASML, Lam Research, Tokyo Electron, KLA Corporation, ASM International, SCREEN Holdings, Hitachi High-Tech, NAURA Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Front-End Equipment Market Shifts & Advancements
Equipment architectures are converging around modularity and predictive maintenance integration, driven by foundry demands for faster technology transitions and minimized unplanned downtime. Toolmakers now embed sensor networks and machine learning diagnostics as standard configurations rather than aftermarket add-ons.
Directed self-assembly patterning is rendering obsolete costly quadruple-patterning lithography steps for certain memory layer applications. NAND flash manufacturers at Samsung and SK Hynix are piloting block copolymer systems for contact and via layers. This materials-driven approach compresses process complexity and reduces scanner utilization hours per wafer.
EPA New Source Performance Standards for semiconductor fabrication facilities tighten perfluorinated compound emission thresholds starting in 2026. Equipment vendors must integrate point-of-use abatement systems as standard configurations rather than optional accessories. US-based foundries face accelerated capital deployment timelines to achieve compliance before permit renewal cycles.
Foundries now unbundle service contracts from initial equipment purchases, treating maintenance and upgrade expenditures as separate procurement categories with distinct vendor evaluation criteria. TSMC and Intel have established independent service provider qualification programs. This purchasing transformation is most advanced in Taiwan and the United States, where equipment installed bases support competitive third-party service ecosystems.
Global Semiconductor Front-End Equipment Market Segmentation
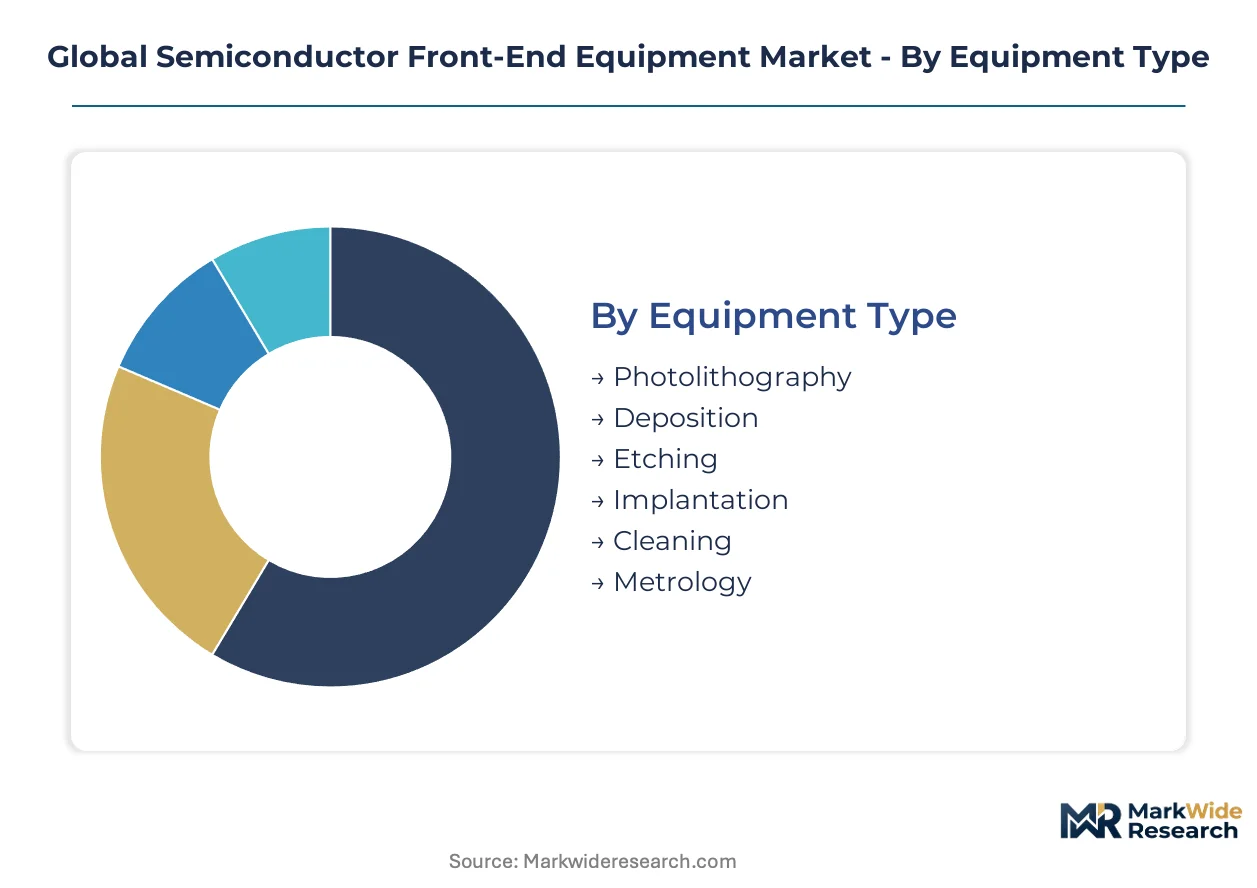
Segmentation in semiconductor front-end equipment reveals how capital allocation priorities diverge across process technologies, device architectures, and manufacturing business models. Equipment vendors calibrate R&D roadmaps and service networks against these distinct demand profiles, while foundries optimize procurement strategies by matching tool specifications to specific wafer fabrication requirements.
Equipment Type:
Mature deposition and etching platforms anchor installed bases across legacy nodes, while emerging lithography systems command disproportionate capital intensity at the leading edge.
- Photolithography:Extreme ultraviolet and deep ultraviolet scanners project circuit patterns onto photoresist-coated wafers with sub-nanometer overlay precision. Taiwan's Hsinchu cluster concentrates procurement for EUV systems as TSMC advances to angstrom-class nodes, with single-tool price points exceeding $350 million amplifying foundry capex cycles.
- Deposition:Chemical vapor deposition and atomic layer deposition systems build conductive and insulating films with atomic-scale thickness control. South Korean memory manufacturers at Samsung and SK Hynix drive chamber count expansion for 3D NAND stacking, where vertical layer multiplication demands sequential deposition sequences.
- Etching:Plasma etch systems remove material anisotropically to form high-aspect-ratio transistor structures. Process recipes vary by device architecture.
- Implantation:Ion implanters introduce dopant atoms to modulate silicon conductivity for source-drain engineering.
- Cleaning:Wet and dry cleaning platforms remove particulate and chemical residues between process steps.
- Metrology:Critical dimension scanning electron microscopes and optical scatterometers verify pattern fidelity across production lots.
Photolithography handles the majority of throughput value concentration; deposition is the fastest mover on share as three-dimensional architectures proliferate.
Technology:
Cost tier stratification separates billion-dollar lithography investments from sub-$10 million process modules, with customer type determining technology access levels.
- Extreme Ultraviolet:13.5-nanometer wavelength lithography enables single-exposure patterning at sub-seven-nanometer nodes. ASML maintains exclusive supply of high-NA EUV scanners, with Intel and Samsung securing early access through co-development partnerships.
- Deep Ultraviolet:193-nanometer immersion lithography with multi-patterning extends cost-effective production at mature and trailing-edge nodes. Chinese foundries concentrate procurement here due to export control restrictions on EUV source technology.
- Atomic Layer Deposition:Self-limiting surface reactions deposit conformal films on complex three-dimensional topography. Gate-all-around transistor migration at Samsung and TSMC accelerates chamber demand for nanosheet channel isolation.
- Chemical Vapor Deposition:Gas-phase reactions form dielectric and metal layers across planar and patterned surfaces.
- Plasma Etching:Reactive ion etching and atomic layer etching achieve directional material removal with selectivity control.
- Electron Beam Lithography:Maskless direct-write patterning serves prototyping and low-volume specialty device production.
Deep ultraviolet dominates unit volume across foundry installed bases; atomic layer deposition is expanding most quickly as nanosheet architectures multiply film stack complexity.
Application:
Volume concentration in memory and logic segments contrasts with margin profiles in analog and power devices, where longer product lifecycles extend equipment depreciation schedules.
- Memory Chips:DRAM and NAND flash fabrication demands high-throughput deposition and etch platforms for repetitive array structures. South Korean and Japanese manufacturers lead 3D NAND layer count competition, with string stacking architectures multiplying etch depth requirements.
- Logic Devices:Microprocessor and mobile SoC production prioritizes lithography resolution and transistor density metrics. Taiwan's foundry ecosystem concentrates leading-edge logic capacity, with gate-all-around transitions refreshing atomic layer deposition tool specifications.
- Analog Chips:Bipolar and CMOS analog processes utilize mature-node equipment with emphasis on parameter matching and noise performance.
- Microelectromechanical Systems:Bulk and surface micromachining integrate mechanical structures with electronic control circuits.
- Power Devices:Wide-bandgap silicon carbide and gallium nitride processing requires specialized high-temperature and high-voltage equipment configurations.
- Sensors:Image sensor and environmental sensor fabrication combines optical and electronic process modules.
Memory chips handle the majority of throughput; logic devices are gaining share fastest as advanced packaging integration expands addressable silicon content per system.
End User:
Geographic dispersion separates concentrated foundry procurement in East Asia from fragmented IDM demand across North America and Europe.
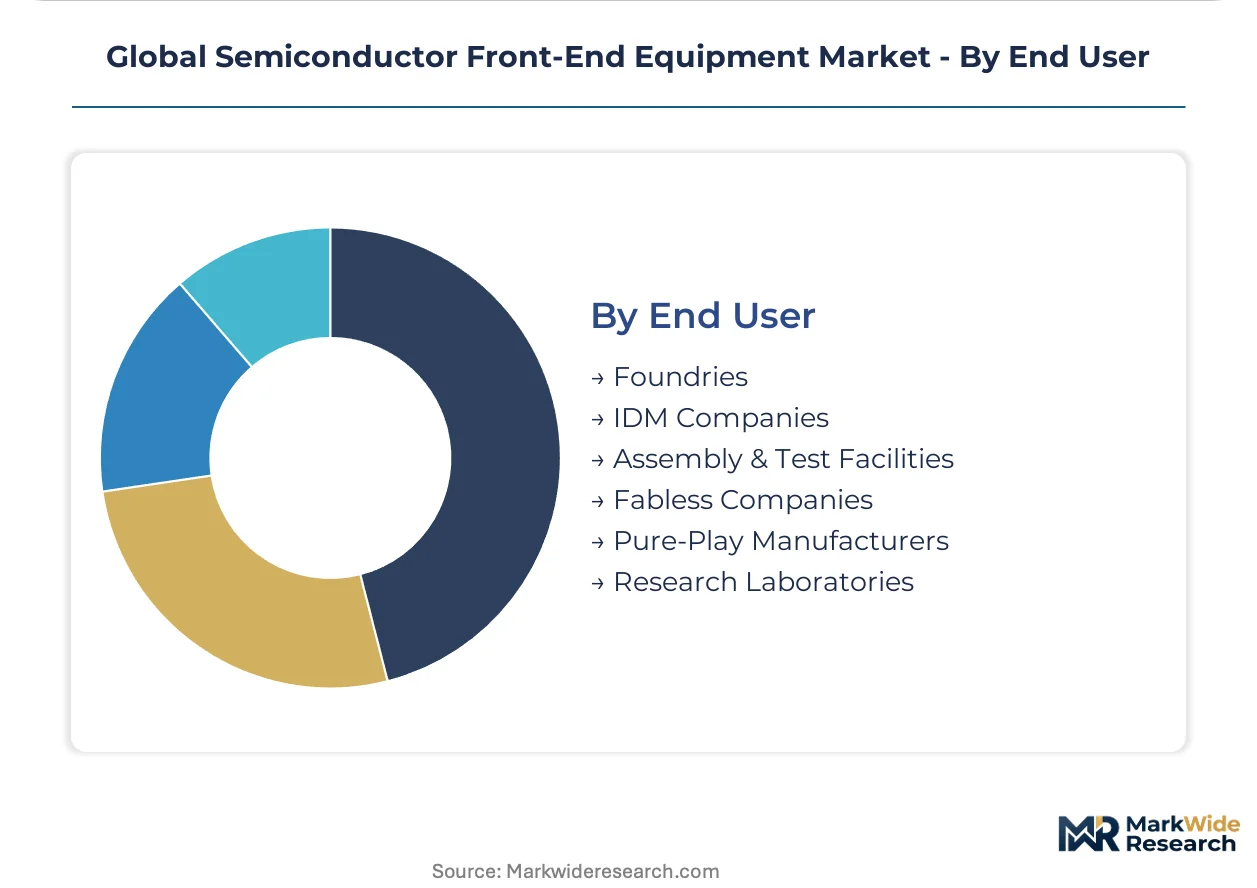
- Foundries:Pure-play wafer fabrication services procure equipment to serve diverse fabless customer portfolios. Taiwan's TSMC and United Microelectronics anchor the world's densest front-end equipment procurement ecosystem, with Hsinchu Science Park logistics enabling same-day spare part availability.
- IDM Companies:Integrated device manufacturers combine design and fabrication capabilities for proprietary product lines. Intel's manufacturing expansion in Arizona and Ohio pulls forward equipment delivery schedules through CHIPS Act funding acceleration.
- Assembly & Test Facilities:Outsourced semiconductor assembly and test providers focus on back-end equipment with limited front-end exposure.
- Fabless Companies:Design-only semiconductor firms influence equipment specifications through foundry process co-development without direct procurement.
- Pure-Play Manufacturers:Specialty foundries serving analog, power, and MEMS segments operate at larger process geometries.
- Research Laboratories:Academic and government research facilities pilot emerging process technologies at reduced throughput scales.
Foundries dominate capital deployment volume; IDM companies are climbing the fastest on share as Intel and Samsung expand captive manufacturing capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates where foundry capital deployment runs deepest. Taiwan, South Korea, and the United States anchor lithography and deposition system demand through distinct regulatory and industrial pathways.
Taiwan
TSMC's Hsinchu Science Park cluster generates the densest front-end equipment procurement ecosystem globally. The National Science and Technology Council administers tax incentives and land-use permits that compress cleanroom construction timelines. Tainan's Southern Taiwan Science Park absorbs expanding EUV scanner installations as angstrom-class node transitions accelerate.
South Korea
Samsung and SK Hynix drive atomic layer deposition chamber demand for 3D NAND string stacking architectures. The Ministry of Trade, Industry and Energy coordinates semiconductor R&D tax credits through the K-Semiconductor Belt initiative. Pyeongtaek's semiconductor complex hosts the world's highest concentration of high-aspect-ratio etch platforms for vertical memory structures.
United States
Intel's Arizona and Ohio manufacturing expansions pull forward equipment delivery schedules through CHIPS Act funding acceleration. The EPA enforces New Source Performance Standards tightening perfluorinated compound emission thresholds from 2026. Phoenix's semiconductor corridor attracts applied materials and lam research service infrastructure co-location.
China
Domestic foundries concentrate procurement on deep ultraviolet lithography and mature-node deposition systems due to export control restrictions. MIIT localization directives steer capital toward NAURA Technology and indigenous equipment suppliers for trailing-edge tools. Shanghai's Zhangjiang Hi-Tech Park hosts the principal cluster for non-EUV wafer fabrication capacity expansion.
Japan
Tokyo Electron and SCREEN Holdings anchor etching and cleaning equipment supply from Kyoto and Osaka industrial corridors. METI's semiconductor revitalization strategy funds domestic equipment maker R&D through public-private partnerships. Kumamoto's Kyushu region concentrates silicon wafer and photoresist material supply chains feeding front-end tool validation cycles.
Global Semiconductor Front-End Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The market structure consolidates around lithography scanner monopolies while fragmenting across deposition, etch, and metrology subsystems. Three archetypes dominate: full-platform vendors spanning multiple process modules, single-technology specialists with deep process expertise, and regional champions serving captive domestic demand. Competitive dynamics center on co-development partnerships for node transitions and service contract unbundling that separates maintenance revenue from initial tool sales.
Among Netherlands-based lithography specialists, ASML occupies the exclusive high-NA EUV scanner position. Applied Materials and Lam Research exemplify the full-platform archetype across Santa Clara-based equipment portfolios. Tokyo Electron represents the precision-process specialist model in etching and cleaning segments. These three anchors illustrate how geographic clustering around Hsinchu, Silicon Valley, and Kyoto-Osaka corridors shapes competitive positioning through supplier ecosystem density effects.
| Leading Market Players |
|---|
| Applied Materials |
| ASML |
| Lam Research |
| Tokyo Electron |
| KLA Corporation |
| ASM International |
| SCREEN Holdings |
| Hitachi High-Tech |
| NAURA Technology |
| Others |
Supply & Pricing Matrix
ASML's monopoly on high-NA EUV source technology concentrates upstream margin capture in the Netherlands, while downstream foundries in Taiwan and South Korea absorb capital intensity through multi-year depreciation schedules and co-development partnerships that lock in pricing bands.
Pricing Analysis
EPA New Source Performance Standards dictate the pricing tier structure for US-bound equipment by mandating integrated abatement systems as baseline configurations rather than optional modules. Three-tier pricing structure across premium, standard, and economy levels separates EUV-compatible platforms with full environmental compliance from legacy deposition tools without point-of-use scrubbers. Cost compression in mature-node etch equipment is intensifying because Chinese foundries face Entity List restrictions that limit technology access and compress procurement budgets. Memory manufacturers at Samsung and SK Hynix demonstrate the least price sensitivity due to 3D NAND layer-count roadmaps that mandate chamber count expansion regardless of unit economics.
Supply Chain Analysis
Neon gas purification infrastructure in Ukraine and South Africa feeds lithography laser systems with critical noble gas feedstock that lacks short-term substitution pathways. Taiwan, Japan, and the United States anchor precision component manufacturing for vacuum chambers, ion sources, and optical subassemblies. Single-source vulnerability concentrates around ASML's EUV source component ecosystem, where Zeiss optics and Cymer laser subsystems create unbreakable supply chain dependencies. Distribution runs through direct foundry relationships with equipment OEMs, bypassing traditional distributor networks due to tool complexity and installation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma physics expertise scarcity constrains toolmaker R&D velocity and creates asymmetric returns for firms that secure specialized process engineering talent pools ahead of nanosheet architecture transitions.
For Market Incumbents: Build switching-cost moats through predictive maintenance platform integration that embeds machine learning diagnostics as standard configurations rather than aftermarket add-ons. Deepen backward integration into critical subcomponent supply to reduce exposure to Zeiss optics and Cymer laser bottlenecks. Co-development partnerships with TSMC and Intel for angstrom-class node transitions lock out competing equipment vendors through exclusive process recipe validation cycles. For New Entrants and Emerging Players: Pursue heterogeneous integration tool demand for silicon photonics packaging applications where traditional lithography and etch incumbents lack established process expertise. India's Gujarat and Karnataka greenfield foundry projects offer the most penetrable geography due to Ministry of Electronics and Information Technology production-linked incentives that accelerate procurement timelines. Position around integrated abatement system specialization to capture EU Carbon Border Adjustment Mechanism compliance premiums as European-bound equipment faces tightened emission thresholds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed deposition and metrology specialists that consolidated during the trailing-node equipment cycle and now face refresh demands from gate-all-around transistor migrations. Long-term viability hinges on exposure to atomic layer deposition chamber demand expansion rather than commoditized chemical vapor deposition platforms. Watch for Bureau of Industry and Security licensing shifts on China-bound mature-node equipment as the inflection indicator that would abruptly reconfigure addressable market boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Development Partnership for High-NA EUV | Intel and Samsung secure early scanner access through ASML collaboration, locking in node transition timelines. |
| Integrated Abatement System Platform Launch | Equipment vendors embed EPA-compliant scrubbers as standard to capture US foundry procurement preference. |
| Atomic Layer Deposition Chamber Expansion | Tokyo Electron and ASM International scale manufacturing to meet TSMC nanosheet isolation film demands. |
| Service Contract Unbundling Program | TSMC and Intel establish independent third-party service provider qualifications, fragmenting maintenance revenue pools. |
| India Greenfield Manufacturing Footprint | Applied Materials and Lam Research establish service infrastructure co-location in Gujarat to support emerging foundry clusters. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with fab operations directors, equipment procurement managers, process integration engineers, and aftermarket service heads; and secondary validation through SEC equipment maker filings, SEMI industry association reports, customs trade data for lithography scanner imports, and foundry capital expenditure disclosures. Bottom-up triangulation against top-down market sizing cross-checked individual tool shipment estimates against aggregate wafer fabrication capacity expansion announcements.
Forecast inputs considered equipment type segmentation by lithography, deposition, etch, implantation, cleaning, and metrology modules; technology tiers spanning EUV, DUV, ALD, CVD, and plasma etching platforms; and application splits across memory, logic, analog, and power device manufacturing. CAGRs were derived from installed base replacement cycles, node transition roadmaps, and chamber-per-wafer-start ratios for 3D NAND string stacking architectures. The modeling period incorporated EPA emission compliance deadlines and MIIT localization directive implementation timelines as structural demand shifters.
Sensitivities concentrate around export license uncertainty for China-bound equipment, neon gas supply disruptions from Eastern European purification infrastructure, and REACH precursor authorization delays that elongate deposition chemistry qualification cycles. Cross-checking against SEMI quarterly equipment billings data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
Ion Milling System Market