
 Thin Film Deposition Equipment Market | 2026-2036
Thin Film Deposition Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Deposition Equipment Market Outlook
Market Context
The direct sales channel between equipment OEMs and logic foundries is narrowing as memory makers consolidate procurement desks. Applied Materials Inc. leverages its installed base to sustain service revenue attach rates across etch and deposition platforms. Tokyo Electron Limited anchors its position through co-development partnerships at leading-edge nodes. Lam Research Corporation competes aggressively in high-aspect-ratio conductor etch, a critical enabler for 3D NAND stacking.
Technical and Segment Structure
Thin film deposition equipment creates controlled material layers from angstrom to micron thickness through vacuum-based physical or chemical processes, with chamber pressure, temperature uniformity, and precursor purity determining film stoichiometry and defect density. Atomic Layer Deposition leads in high-k metal gate and advanced packaging applications where sub-nanometer precision governs device performance. Physical Vapor Deposition occupies mature margin pools in hard disk drive and general industrial coating segments where tool longevity outweighs throughput demands.
Regulatory Environment
The U.S. Department of Commerce export controls and Japan METI licensing requirements restrict deposition tool shipments to specific Chinese fabs, fragmenting equipment availability by geography. The EU Chips Act and U.S. CHIPS and Science Act tie subsidy disbursement to domestic content thresholds, reshaping where OEMs locate final assembly and where foundries site greenfield capacity. Stakeholders must monitor how multilateral coordination on semiconductor equipment controls evolves relative to individual national industrial policy timelines.
Market Dynamics
Equipment OEMs face intensifying pressure as logic foundries consolidate procurement desks while memory makers delay capacity additions, compressing order visibility windows from twelve to six months for deposition tool vendors.
Growth Catalysts
- Advanced Node Migration:Logic foundries in Taiwan and South Korea are expanding atomic layer deposition capacity for gate-all-around transistor architectures. Sub-nanometer precision requirements pull equipment refresh cycles forward.
- CHIPS Act Localization:The U.S. CHIPS and Science Act ties subsidy disbursement to domestic fab construction, redirecting capital equipment flows toward Arizona and Texas greenfield sites.
- 3D NAND Stacking:Memory manufacturers are extending string heights beyond 200 layers, multiplying deposition steps per wafer and driving chamber throughput requirements.
Market Restraints
- Precursor Supply Concentration:High-purity metal-organic precursors for ALD processes concentrate among Japanese and German chemical suppliers, exposing deposition tool utilization to single-source fragility.
- Export Control Friction:U.S. Department of Commerce licensing requirements and Japan METI restrictions fragment equipment availability for mature-node Chinese fabs, forcing OEMs to maintain parallel product configurations.
- Technical Talent Scarcity:Vacuum technology and plasma physics expertise pools concentrate in legacy semiconductor regions, constraining service scaling for tools deployed in emerging fabrication clusters.
Strategic Opportunities
- India Fab Incentives:The country's PLI scheme for semiconductor manufacturing creates virgin demand for deposition equipment as Micron and Tata Electronics establish assembly and test facilities in Gujarat.
- Advanced Packaging Interposers:Through-silicon via and redistribution layer applications are opening deposition tool orders from OSATs previously served by general industrial coating vendors.
- Carbon Border Adjustments:The EU's impending carbon border mechanism on embedded emissions in imported goods incentivizes European-located tool manufacturing to satisfy domestic content thresholds.
Industry Challenges
- Chamber Matching Complexity:Foundry customers demand cross-chamber uniformity within 1 percent for critical layers, requiring OEMs to maintain statistical process control databases across installed bases exceeding 10,000 chambers.
- Legacy Tool Integration:Brownfield expansions in Japan and the United States require deposition platforms to communicate with 1990s-era factory automation systems through custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Deposition Equipment Market |
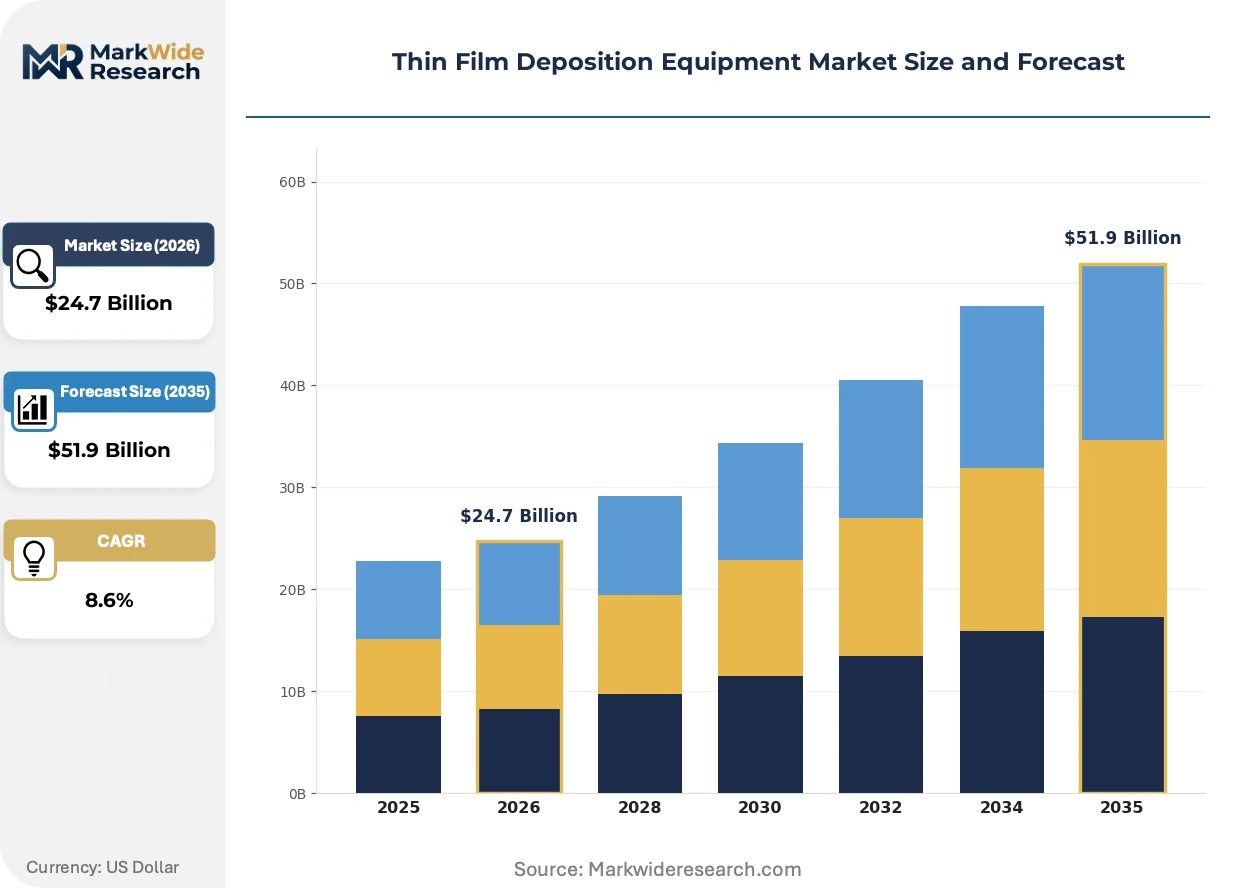
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVD, CVD, ALD, Etching End User: Semiconductors, Electronics, Optics, Solar Cells Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Atomic Layer Deposition, Molecular Beam Epitaxy Application: Coatings, Thin Film Solar Cells, Membranes, Sensors |
| Companies Covered | Applied Materials Inc., Lam Research Corporation, Tokyo Electron Limited, ASM International NV, Veeco Instruments Inc., ULVAC, Aixtron SE, Canon ANELVA Corporation, Intevac Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Deposition Equipment Market Strategic Shifts
Deposition technology evolution centers on precision-compression and process-integration, with equipment architectures converging toward cluster-tool modularity that enables in-situ metrology and reduces wafer queue time between process steps.
Atomic layer deposition is collapsing the distinction between front-end-of-line transistor formation and back-end-of-line interconnect processing. Memory manufacturers are adopting ALD for high-aspect-ratio capacitor electrodes previously served by chemical vapor deposition. This convergence is collapsing equipment procurement categories, forcing vendors to restructure product lines around unified platform architectures rather than discrete tool families.
Japan METI licensing requirements for deposition equipment exports to designated Chinese fabs are fragmenting supply chain geography. OEMs are relocating final assembly to Malaysia and Singapore to satisfy origin-certification requirements while maintaining component sourcing from restricted jurisdictions. Equipment configurations destined for China now diverge at the subassembly level, with chamber designs omitting specific precursor delivery modules.
Foundry procurement desks are consolidating deposition tool purchasing under single-source framework agreements that bundle chamber hardware with multi-year service contracts and consumable supply. This disintermediates traditional equipment distributors in Taiwan and South Korea. The shift is most visible at leading-edge nodes where tool uptime guarantees now determine contract awards rather than capital cost alone.
Thin Film Deposition Equipment Market Segmentation
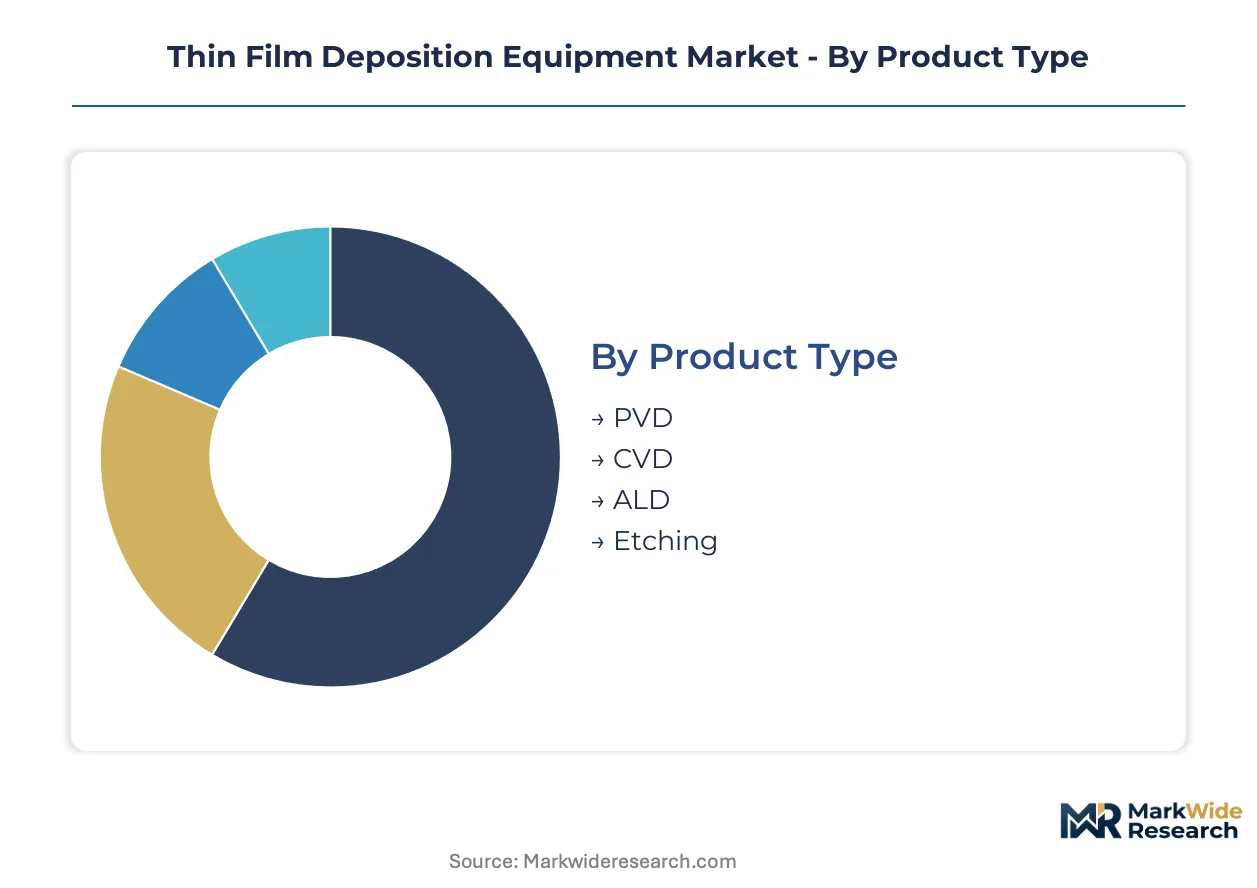
Deposition equipment procurement patterns diverge sharply by process technology and end-use vertical, with logic foundries, memory manufacturers, and photovoltaic producers each demanding distinct chamber architectures. Understanding these segment boundaries clarifies where OEMs must maintain parallel product lines versus unified platform strategies.
Product Type:
Cost tier differentiation separates mature-margin equipment from precision-premium platforms, with capital intensity and chamber complexity driving purchasing committee composition.
- PVD:Sputtering and evaporation systems deposit metal and dielectric films through physical transfer of target material in high-vacuum environments. Hard disk drive manufacturers in Japan and general industrial coating operations absorb the majority of unit volume, prioritizing tool longevity and low cost of ownership over throughput optimization.
- ALD:Sequential self-limiting surface reactions enable angstrom-level thickness control for high-k dielectrics and metal gate stacks. Taiwan and South Korea logic foundries are expanding ALD capacity for gate-all-around transistor architectures, pulling equipment refresh cycles forward through sub-nanometer precision mandates.
- CVD:Thermally activated gas-phase reactions deposit conformal films across complex topographies at higher throughput than atomic layer alternatives.
- Etching:Plasma and wet chemical systems selectively remove material to pattern deposited films, with chamber designs increasingly integrated with deposition clusters.
PVD commands the established base across industrial coating segments. The steepest expansion runs through ALD as advanced node migration accelerates equipment replacement.
End User:
Application maturity determines whether customers prioritize throughput, precision, or total cost of ownership in equipment specification.
- Semiconductors:Logic foundries and memory fabs operate the most demanding deposition environments, with chamber uniformity specifications tighter than 1 percent for critical layers. Taiwan, South Korea, and United States fabs are scaling capital expenditure for advanced node production, with the U.S. CHIPS Act redirecting equipment flows toward Arizona and Texas greenfield sites.
- Solar Cells:Photovoltaic manufacturers deploy CVD and PVD systems for anti-reflective coatings and transparent conductive oxide deposition. Chinese producers dominate absorption for mature-node expansion, though India PLI scheme incentives are creating virgin demand as Micron and Tata Electronics establish facilities in Gujarat.
- Electronics:Display panel and printed circuit board producers utilize mid-tier deposition systems where film functionality outweighs atomic-scale precision.
- Optics:Lens and mirror coating operations demand specialized ion-assisted deposition for optical interference control.
Semiconductor end users absorb the premium equipment volume. Solar cell manufacturing is gaining share fastest as photovoltaic deployment accelerates capacity buildouts.
Technology:
Process physics and precursor chemistry define equipment architecture, with vacuum requirements and temperature windows determining factory infrastructure needs.
- Physical Vapor Deposition:Sputtering, evaporation, and ion plating systems transfer material from solid targets without chemical reaction. Hard disk drive and decorative coating segments sustain demand where film stoichiometry tolerances permit broader process windows.
- Atomic Layer Deposition:Sequential precursor exposure achieves self-limiting monolayer growth with exceptional conformality. Gate-all-around transistor architectures and advanced packaging interposers are collapsing the distinction between front-end and back-end processing, forcing vendors toward unified platform architectures.
- Chemical Vapor Deposition:Gas-phase precursor decomposition deposits films at rates exceeding ALD, serving memory capacitor and interconnect liner applications.
- Molecular Beam Epitaxy:Ultra-high-vacuum evaporation of elemental sources enables single-crystal film growth for compound semiconductor and research applications.
Chemical vapor deposition retains the largest installed footprint. Atomic layer deposition is climbing the fastest as precision requirements compress across logic and memory segments.
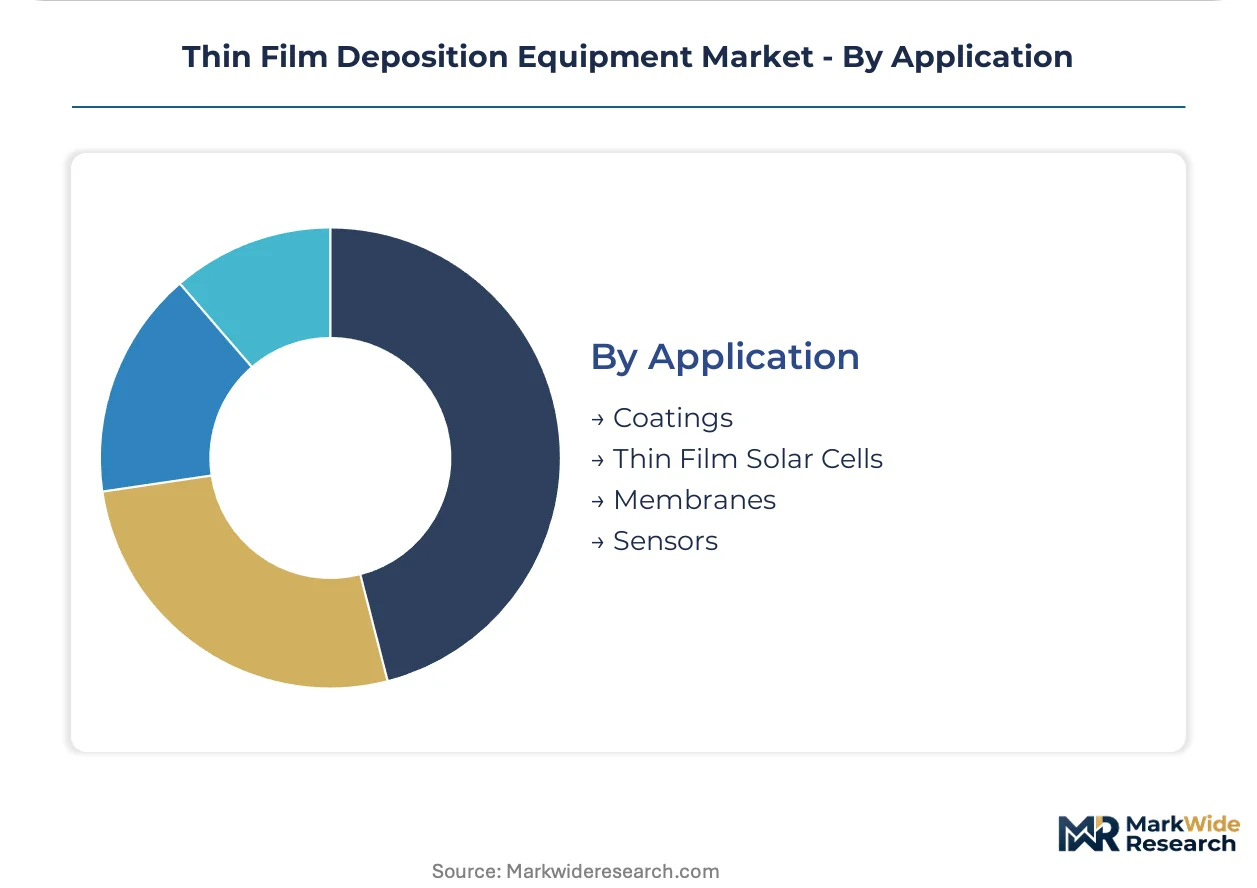
Application:
Functional requirements dictate film property priorities, from optical transparency to mechanical durability to electrical conductivity.
- Coatings:Protective and decorative films span automotive trim, architectural glass, and cutting tool segments. General industrial absorption concentrates in Germany and Japan manufacturing clusters where tool longevity outweighs throughput demands.
- Thin Film Solar Cells:Cadmium telluride and copper indium gallium selenide deposition requires specialized vapor transport and sputtering configurations. Chinese fabs drive mature-node expansion while India PLI incentives redirect supply chain geography.
- Membranes:Gas separation and filtration applications utilize controlled porosity through deposition parameter tuning.
- Sensors:Piezoelectric and chemiresistive films demand precise stoichiometry control for signal transduction reliability.
Coatings applications anchor the mature equipment base. Thin film solar cell manufacturing shows the steepest expansion trajectory as photovoltaic capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung harbor container throughput underwrites Taiwan's semiconductor logistics corridor, moving deposition chambers from Japanese ports to Hsinchu Science Park fabs within 72 hours. This maritime infrastructure anchors the Asia-Pacific equipment flow architecture.
United States
Intel and TSMC are scaling Arizona greenfield fabs for 3nm-class production, pulling ALD and CVD equipment orders toward Phoenix and Tucson clusters. The U.S. CHIPS and Science Act ties subsidy disbursement to domestic construction milestones, compressing tool delivery timelines for OEMs. Austin and Dallas-Fort Worth house expanding Applied Materials and Lam Research service centers supporting these deployments.
China
Domestic fabs in Shanghai and Wuxi are absorbing mature-node deposition tools for 28nm and above processes, driven by import substitution mandates under MIIT industrial policy. The Yangtze Memory Technologies and Hua Hong Semiconductor expansions concentrate equipment demand in the Yangtze River Delta. Japan METI licensing requirements fragment supply availability, forcing parallel product configurations for China-bound shipments.
South Korea
Samsung Electronics and SK Hynix are extending 3D NAND string heights beyond 300 layers, multiplying deposition steps per wafer in Pyeongtaek and Icheon fabs. The Korean MFDS coordinates precursor chemical safety standards with equipment qualification protocols. Seoul Capital Area clusters anchor high-aspect-ratio conductor etch and ALD capacity additions for gate-all-around transistor ramps.
Japan
Tokyo Electron and Canon ANELVA maintain deposition tool manufacturing in Nagano and Kanagawa prefectures, serving domestic logic and memory customers. METI export licensing to designated Chinese fabs fragments equipment availability by destination. The Chubu region around Nagoya houses specialized precursor chemical suppliers feeding ALD processes for advanced node production.
India
Micron Technology and Tata Electronics are establishing assembly and test facilities in Gujarat under the PLI scheme for semiconductor manufacturing, creating virgin deposition equipment demand. The country's CEA coordinates power infrastructure standards for fab construction timelines. Dholera Special Investment Region is emerging as a concentration point for first-generation Indian semiconductor fabrication capacity.
Thin Film Deposition Equipment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in precursor delivery, vacuum pumping, and chamber architecture. The vendor base concentrates around three firms with installed bases exceeding 10,000 chambers each, while mid-tier players compete on specific process modules. Two strategic archetypes dominate: full-stack platform vendors bundling hardware with multi-year service contracts, and process-specific specialists capturing niche applications. Competitive moves center on co-development partnerships at leading-edge nodes and geographic relocation of final assembly to satisfy origin-certification requirements.
Among U.S.-based platform vendors, Applied Materials Inc. and Lam Research Corporation exemplify the full-stack archetype with extensive installed bases across etch and deposition platforms. Tokyo Electron Limited represents the integrated Japanese model, anchoring its position through proximity to domestic precursor supply chains and leading-edge node partnerships. These three firms collectively occupy the premium tier where tool uptime guarantees determine contract awards.
| Leading Market Players |
|---|
| Applied Materials Inc. |
| Lam Research Corporation |
| Tokyo Electron Limited |
| ASM International NV |
| Veeco Instruments Inc. |
| ULVAC |
| Aixtron SE |
| Canon ANELVA Corporation |
| Intevac Inc. |
| Others |
Value Chain & Pricing Dynamics
The Kaohsiung harbor container throughput cost dynamics amplify pricing power for Japanese and German precursor suppliers while compressing margins for mid-tier equipment vendors serving price-sensitive solar cell manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates foundry-proven ALD platforms from refurbished CVD systems and general industrial sputtering tools.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with logic foundries extracting steepest hardware discounts through multi-year service contract bundling. Price differentiation rests on chamber uptime guarantees and precursor purity certification tiers. Cost compression in standard-tier PVD equipment is intensifying because Chinese solar manufacturers are consolidating orders under reverse-auction terms. Solar cell producers exhibit highest price sensitivity; Taiwan logic foundries prioritize total cost of ownership over capital expenditure.
Supply Chain Analysis
Upstream feedstock concentration in Japan and Germany for high-purity metal-organic precursors creates single-source vulnerability for ALD tool utilization. Vacuum pumps and RF power supplies draw from specialized component ecosystems in the United States and Japan. Tariff exposure on China-bound shipments fragments equipment configurations at the subassembly level. Distribution runs through direct OEM-foundry relationships disintermediating traditional Taiwanese equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin film deposition equipment markets reward service-attach strategies where consumable precursor supply contracts and chamber refurbishment revenue expand faster than new tool shipments. Foundry procurement desks now weight multi-year uptime guarantees above capital cost in vendor selection.
For Market Incumbents: Insulate installed base relationships by embedding field service engineers within Arizona and Texas greenfield fabs before competitor tool qualification. Deepen backward integration into precursor chemical distribution to capture recurring revenue streams threatened by Japanese supplier direct sales initiatives. For New Entrants and Emerging Players: Establish a beachhead in India PLI scheme greenfield sites where virgin demand lacks incumbent service infrastructure. Target photovoltaic CVD retrofits where price sensitivity exceeds precision requirements. Partner with domestic Indian engineering firms for localized chamber assembly to satisfy origin-certification thresholds. For Investors and Strategic Acquirers: Component specialists with vacuum pumping and RF generator expertise represent compelling acquisition targets as OEMs seek captive supply of critical subsystems. Long-term viability hinges on exposure to advanced node migration rather than mature-node replacement cycles. Monitor Japan METI licensing enforcement intensity as inflection indicator for China-bound revenue exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Development Partnership | Tokyo Electron anchors market position through leading-edge node joint engineering with Samsung and TSMC. |
| Geographic Relocation of Final Assembly | OEMs shift Malaysian and Singapore assembly operations to satisfy EU Chips Act domestic content thresholds. |
| Service Contract Bundling | Applied Materials extends revenue per chamber through multi-year consumable supply agreements. |
| Precursor Supply Integration | Lam Research secures chemical supply chains through partnerships with German metal-organic suppliers. |
| Cluster Tool Modularity Investment | ASM International converges ALD and CVD architectures to reduce wafer queue time between process steps. |
Study Parameters
A spread of perspectives from fab procurement directors, equipment OEM sales engineers, precursor chemical supply managers, and vacuum technology R&D leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, Japan METI trade statistics, and EU Chips Act implementation documents. Bottom-up chamber shipment tallies and top-down foundry capex tracking were triangulated to anchor volume estimates.
Demand-supply-balance framing shaped the analytical approach across the analysis window, with segmentation modeling across technology type, end-use vertical, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle compression and capacity expansion announcements. Forecast inputs incorporated gate-all-around transistor architecture ramps and 3D NAND layer count trajectories as technology-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or multilateral export control coordination would shift the trajectory. Forecasts reflect documented assumptions regarding subsidy disbursement timelines and precursor chemical supply stability. Cross-checking against WSTS semiconductor equipment spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
United States Chip Mounter Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Global Capacitor Winding Machines Market