
 Lithographic Photomasks Market | 2026-2036
Lithographic Photomasks Market Size, Share, and Industry Trends Forecast 2026-2036
Lithographic Photomasks Market Insights
EUV-grade mask blanks is redrawing competitive hierarchies in lithographic photomasks. Toppan Photomasks leverages captive substrate technology to dominate high-NA EUV supply. Photronics sustains dual-source manufacturing across Asia and North America. HOYA Corporation anchors the critical multilayer mirror blank layer that few rivals replicate.
A lithographic photomask is a quartz substrate coated with patterned chrome or phase-shifting films, transmitting or modulating light at wavelengths as short as 13.5 nanometers to project circuit geometries onto silicon wafers. Phase shift masks command premium positioning as foundries push below 3nm resolution limits. Extreme Ultraviolet Lithography masks carry the steepest technical barriers and fastest value growth among technology segments. Semiconductor Manufacturers absorb the majority of mask volume, though Display Manufacturers are expanding procurement for OLED micro-patterning.
ISO 10110 surface quality standards, SEMI P37 EUV substrate specifications, and Japan's METI semiconductor supply chain security directives collectively tighten mask qualification protocols. REACH chemical restrictions in Europe and EPA hazardous substance rules in the United States constrain chrome etching chemistries and cleaning processes. Stakeholders must weigh capital intensity against the narrowing supplier base capable of certifying EUV-grade blanks.
Market Dynamics
Extreme Ultraviolet Lithography mask qualification is compressing supplier margins while concentrating procurement power among three leading-edge foundry clusters. The transition from 193nm immersion to 13.5nm EUV wavelengths demands entirely new substrate architectures, forcing mask houses to rebuild capital bases around multilayer mirror deposition systems.
Growth Catalysts
- SEMI P37 Substrate Mandates:Taiwan's foundry leadership is accelerating EUV blank certification timelines, pulling mask vendors into co-development partnerships with equipment makers.
- 3nm Node Ramp:Phase shift mask complexity is multiplying as transistor density targets exceed 200 million per square millimeter, extending mask write times and unit values.
- South Korea Display Pivot:OLED micro-patterning for augmented reality headsets is opening captive mask demand outside traditional semiconductor channels.
Market Restraints
- Quartz Substrate Oligopoly:Synthetic fused silica supply concentrates among Japanese and German specialty glass makers, exposing mask fabricators to input rationing during capacity crunches.
- Chrome Etching Chemistry Constraints:EPA hazardous substance rules and ECHA REACH restrictions are eliminating conventional wet-etch processes, forcing costly dry-etch retrofits.
- EUV Defect Detection Bottlenecks:Actinic inspection tools remain scarce, extending mask qualification cycles and inflating work-in-process inventory.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic fab construction are creating first-mover advantage for mask vendors establishing local patterning service centers.
- High-NA EUV Convergence:The intersection of anamorphic optics and pellicle architecture is opening specialist niches for membrane stress-engineering capabilities.
- Photonics Packaging:Silicon photonics interposers for AI accelerators are adopting DUV mask patterning at volumes previously reserved for leading-edge logic.
Industry Challenges
- Multilayer Deposition Expertise Gap:Fewer than fifty technicians worldwide possess production-grade Mo/Si sputtering calibration experience, constraining capacity expansion.
- ISO 10110 Surface Quality Certification:Sub-50 picometer flatness verification requires atomic force microscopy infrastructure that smaller mask houses cannot amortize.
- Legacy 248nm Tooling Stranding:Obsolescence risk in mature node mask production is compressing depreciation schedules and complicating capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithographic Photomasks Market |
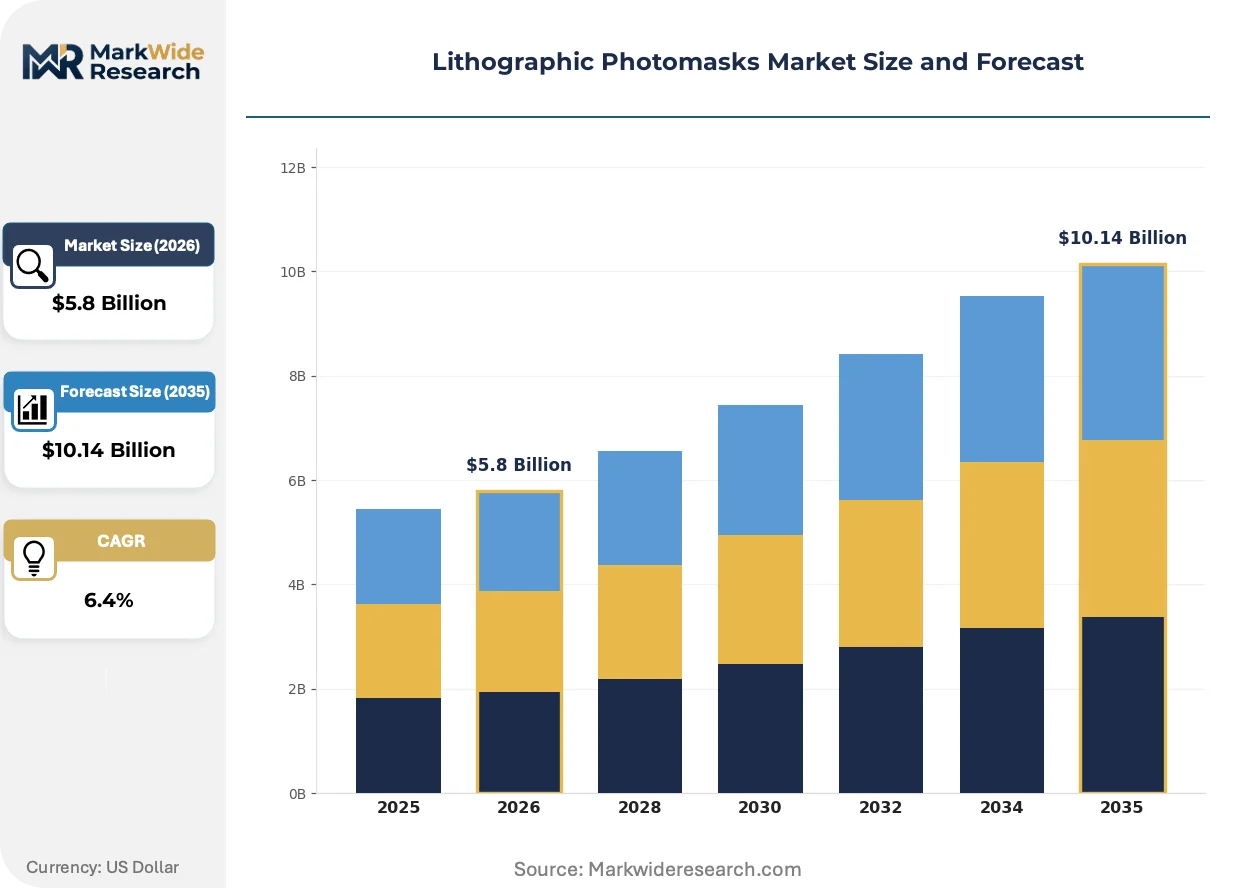
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binary Masks, Phase Shift Masks, Optical Masks, Immersion Masks End User: Semiconductor Manufacturers, Research Institutions, Display Manufacturers, Electronics Companies Technology: 193nm Lithography, Extreme Ultraviolet Lithography, Electron Beam Lithography, Nanoimprint Lithography Application: Integrated Circuits, Flat Panel Displays, MEMS, Photonic Devices |
| Companies Covered | Toppan Photomasks, Photronics, HOYA Corporation, Dai Nippon Printing, SK-Electronics, KLA Corporation, Advance Reproductions Corporation, LG Innotek, Nippon Filcon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithographic Photomasks Market Trends and Innovations
Photomask technology is fragmenting into two performance tiers governed by wavelength economics. The divergence between EUV-grade and DUV-legacy requirements is redrawing vendor specialization boundaries and capital deployment strategies.
High-NA EUV mask architecture is bifurcating the supplier base into mirror-blank specialists and patterning houses. Taiwan Semiconductor Manufacturing and Samsung Foundry are qualifying 0.55 numerical aperture masks for 2027 production ramps. This wavelength compression is eliminating second-source options for critical layers, binding foundries to single qualified vendors per technology node.
Japan's METI semiconductor supply chain security directives are mandating domestic mask blank reserves and cross-border replication agreements. The policy is accelerating HOYA Corporation's capacity expansion in Miyagi Prefecture while pressuring foreign competitors to establish Japanese manufacturing entities. EUV substrate procurement is now subject to national security screening protocols previously reserved for raw silicon.
Long-term service contracts are displacing spot-market mask purchases among leading-edge foundries. TSMC and Intel are consolidating patterning procurement into five-year master agreements with volume guarantees and joint yield-improvement clauses. Taiwan and South Korea exhibit the tightest buyer concentration, with three customers accounting for the majority of EUV mask revenue commitments.
Lithographic Photomasks Market Segmentation
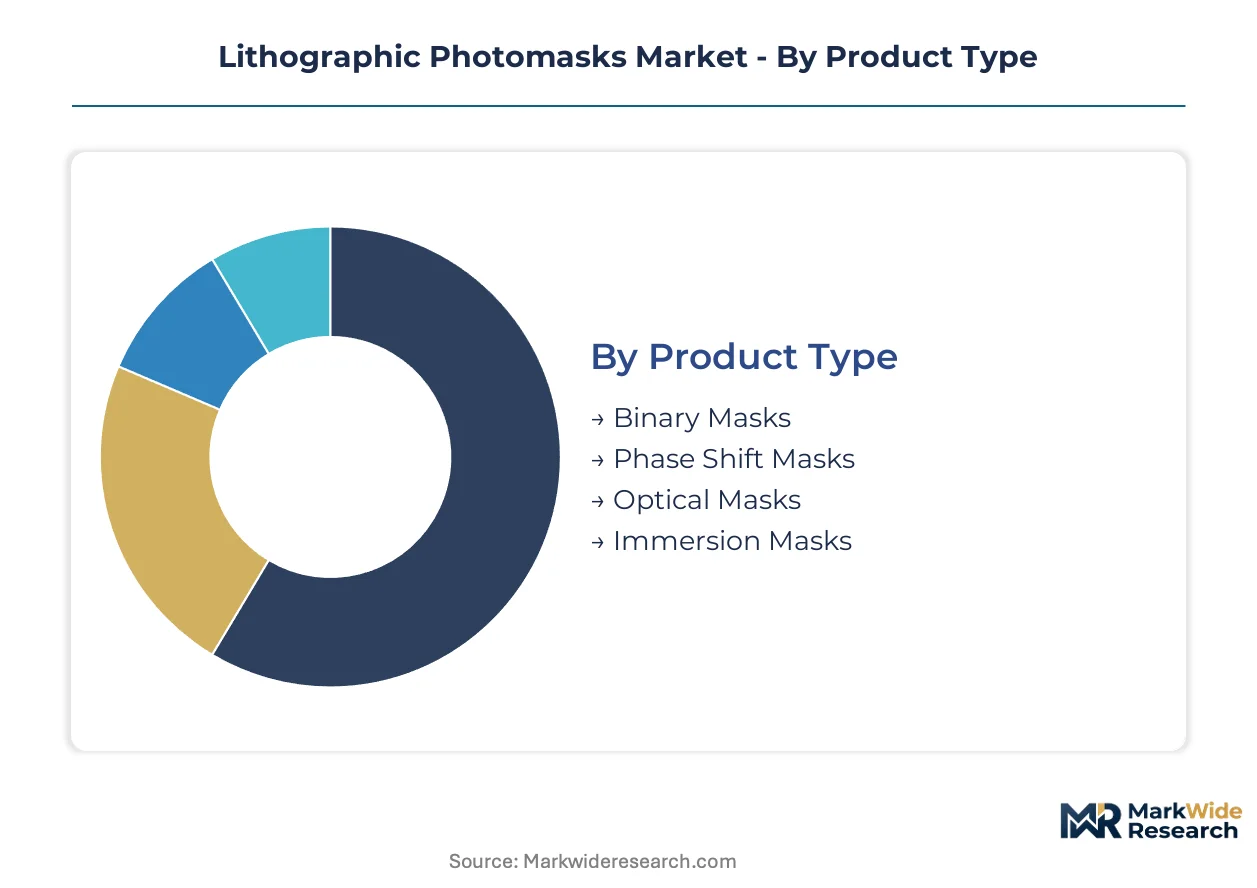
Photomask segmentation reveals distinct procurement patterns between captive foundry demand and merchant market supply. Technology node requirements fragment purchasing power across wavelength-specific tiers, while end-use concentration in Taiwan, South Korea, and Japan shapes geographic sourcing strategies.
Product Type:
Binary masks serve mature node production domestically in most consuming countries, while phase shift and EUV-grade variants flow through specialized export channels controlled by Japanese and German substrate suppliers.
- Binary Masks:Chrome-on-quartz patterns at 248nm and 193nm wavelengths dominate legacy logic and memory production. Semiconductor Manufacturers in Taiwan and South Korea maintain substantial captive binary mask libraries for nodes above 7nm, though procurement is shifting toward phase shift alternatives as foundries consolidate process platforms.
- Phase Shift Masks:Molybdenum silicide and attenuated phase shift films enable sub-40nm resolution without double patterning. Demand concentrates with Taiwan Semiconductor Manufacturing and Samsung Foundry as they push below 3nm transistor densities, tightening mask write times and elevating unit values through added pattern complexity.
- Optical Masks:Broad-spectrum transmission masks serve research institutions and prototyping lines with flexible specification tolerances.
- Immersion Masks:Water-immersion-compatible substrates support the 193nm extension nodes bridging DUV and EUV eras.
Binary masks command the established base. The steepest expansion runs through phase shift variants.
End User:
Customer concentration varies sharply by volume tier: foundry giants absorb premium EUV capacity while research and display segments compete for residual DUV throughput.
- Semiconductor Manufacturers:Leading-edge foundries and IDMs account for the dominant share of EUV mask procurement, with TSMC, Samsung, and Intel binding vendors into multi-year master agreements. Their qualification protocols, including SEMI P37 substrate mandates, effectively set industry standards that smaller consumers must follow.
- Research Institutions:Universities and national laboratories purchase low-volume, high-mix mask sets for process development and academic research, often accepting longer lead times in exchange for design flexibility.
- Display Manufacturers:OLED and micro-LED patterning is opening captive mask demand in South Korea, where Samsung Display and LG Display are qualifying DUV masks for augmented reality headset micro-patterning.
- Electronics Companies:Fabless design houses and system integrators procure masks indirectly through foundry services or engage merchant mask houses for prototyping runs.
Semiconductor Manufacturers anchor volume commitments. Display Manufacturers are climbing the fastest as OLED micro-patterning scales.
Technology:
Capital intensity stratifies supply tiers: EUV infrastructure demands billion-dollar deposition systems while electron beam and nanoimprint serve niche, lower-throughput applications.
- 193nm Lithography:Immersion and dry variants of ArF lithography continue serving mature node production and memory layers where EUV penetration remains incomplete. Mask houses in Japan and the United States maintain substantial 193nm patterning capacity for trailing-edge logic and specialty foundry customers.
- Extreme Ultraviolet Lithography:13.5nm wavelength masks require Mo/Si multilayer mirror blanks from HOYA Corporation and captive substrate specialists, creating supply bottlenecks that constrain foundry expansion timelines. High-NA EUV variants at 0.55 numerical aperture are qualifying for production ramps, further tightening vendor qualification requirements.
- Electron Beam Lithography:Maskless direct-write systems serve prototyping and low-volume production where photomask economics break down.
- Nanoimprint Lithography:Mechanical pattern replication targets specific layers in memory and photonics where resolution requirements outpace optical alternatives.
193nm Lithography retains the installed base. Extreme Ultraviolet Lithography is gaining share fastest as node transitions accelerate.
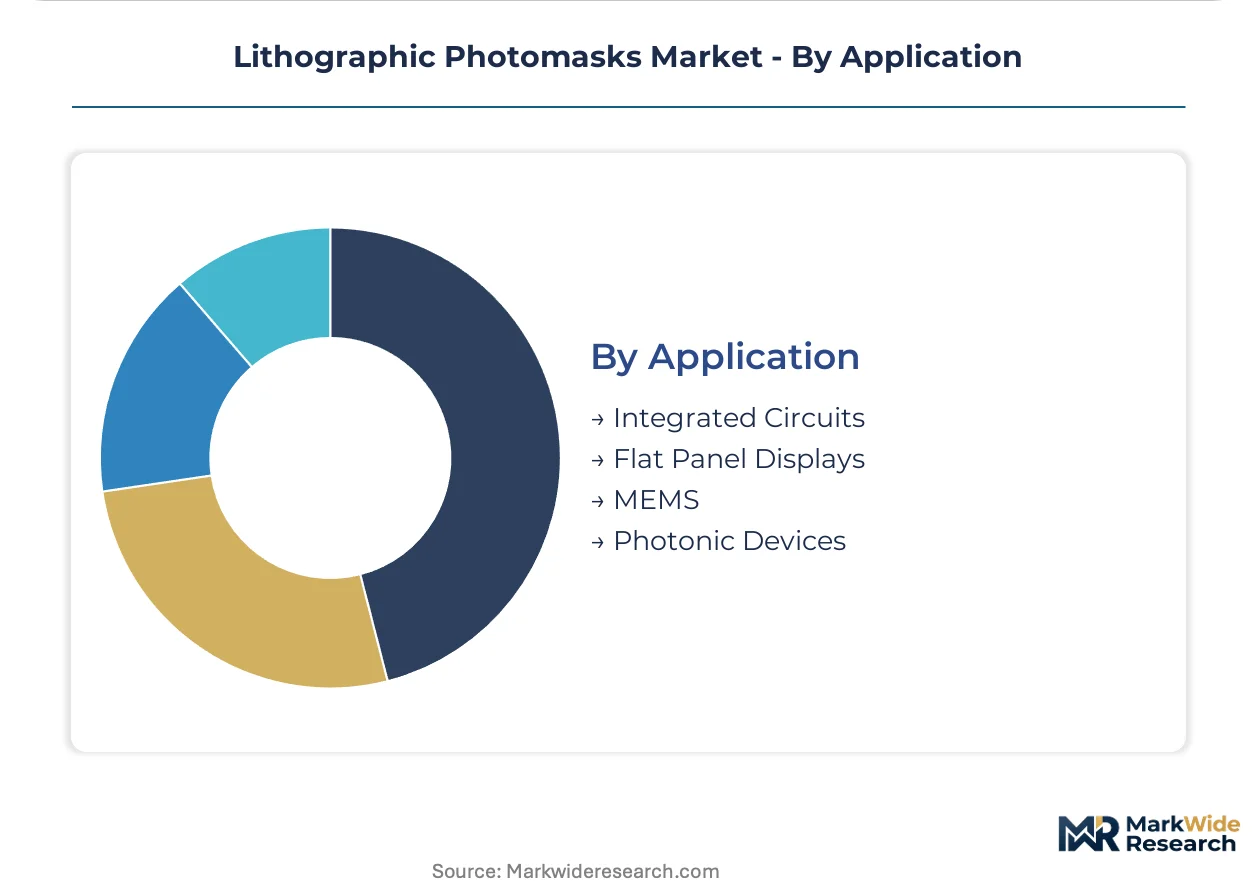
Application:
Application mix determines mask complexity tiers: integrated circuits demand the finest pattern fidelity while MEMS and photonics tolerate relaxed specifications at higher volumes.
- Integrated Circuits:Logic and memory device production consumes the most technically demanding mask sets, with leading-edge processors requiring 50-100 masks per design. Taiwan and South Korea foundries are pushing mask complexity through 3nm node ramps and gate-all-around transistor architectures.
- Flat Panel Displays:Large-area patterning for OLED and LCD backplanes uses 1:1 projection or stepper-scanner hybrids with distinct mask formats from semiconductor applications.
- MEMS:Micro-electromechanical systems for sensors and actuators employ thicker resist processes and relaxed critical dimension tolerances compared to CMOS logic.
- Photonic Devices:Silicon photonics interposers for AI accelerators are adopting DUV mask patterning at volumes previously reserved for leading-edge logic, creating demand spillover from traditional semiconductor channels.
Integrated Circuits command the established base. Photonic Devices are climbing the fastest as AI packaging scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports EUV-grade mask blanks to Taiwan and South Korea, where TSMC and Samsung Foundry convert substrates into patterned photomasks for leading-edge logic production. This trade corridor concentrates the highest-value photomask flows in the semiconductor supply chain.
Taiwan
TSMC's 3nm and 2nm node ramps are absorbing the majority of global EUV mask capacity, with Hsinchu Science Park hosting the densest cluster of mask patterning vendors outside Japan. Taiwan's National Development Council enforces SEMI P37 substrate mandates that accelerate blank certification timelines. Tainan and Taichung foundry campuses are pulling mask houses into co-development partnerships with equipment makers.
South Korea
Samsung Foundry and SK Hynix are expanding EUV mask procurement for gate-all-around transistor architectures, with Pyeongtaek and Yongin campuses driving demand concentration. South Korea's Ministry of Trade, Industry and Energy subsidizes domestic mask blank development under the K-Semiconductor Belt initiative. Seoul's Pangyo Techno Valley is emerging as a hub for mask design software and inspection tool development.
Japan
HOYA Corporation and Toppan Photomasks anchor the critical multilayer mirror blank and patterning layers that few rivals replicate, with Miyagi Prefecture expanding EUV substrate capacity. Japan's METI semiconductor supply chain security directives mandate domestic mask blank reserves and cross-border replication agreements. Tokyo-Osaka industrial corridors concentrate actinic inspection tool development and synthetic fused silica purification expertise.
United States
Intel's Arizona and Oregon fabs are qualifying high-NA EUV masks for 2027 production ramps, pulling patterning procurement into long-term master agreements. EPA hazardous substance rules constrain chrome etching chemistries and cleaning processes, forcing costly dry-etch retrofits. California's Silicon Valley maintains merchant mask houses serving fabless design houses and research institutions with prototyping capacity.
China
SMIC and Hua Hong Semiconductor are advancing domestic mask capabilities for mature nodes above 7nm, with Shanghai and Beijing clusters absorbing DUV patterning equipment. China's MIIT enforces GB standards for semiconductor materials that tighten mask qualification protocols. Wuxi and Hefei foundry campuses are developing captive mask libraries to reduce import dependence for trailing-edge logic.
Lithographic Photomasks Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology tiers, with publicly traded mask houses accessing project finance for billion-dollar deposition systems while private specialists retain flexibility in niche patterning segments. The vendor base stratifies into three tiers: mirror-blank specialists controlling EUV substrate supply, patterning houses converting blanks into qualified masks, and merchant vendors serving trailing-edge and research demand. Two dominant competitive moves are reshaping positioning: long-term service contracts displacing spot-market purchases among leading-edge foundries, and geographic expansion into India under PLI scheme incentives for domestic fab construction.
Within the mirror-blank specialist tier, HOYA Corporation and Toppan Photomasks exemplify the capital-intensive archetype that controls critical supply chain chokepoints. Among patterning houses, Photronics occupies a position spanning merchant and captive demand across multiple geographies. These three names represent the narrowing supplier base capable of certifying EUV-grade blanks and sustaining the qualification partnerships that bind foundries to single vendors per technology node.
| Leading Market Players |
|---|
| Toppan Photomasks |
| Photronics |
| HOYA Corporation |
| Dai Nippon Printing |
| SK-Electronics |
| KLA Corporation |
| Advance Reproductions Corporation |
| LG Innotek |
| Nippon Filcon |
| Others |
Pricing and Supply Chain Analysis
Ninety-day mask blank qualification cycles concentrate procurement power among three foundry clusters while inflating work-in-process inventory carrying costs. This lead-time band binds pricing power to substrate availability, compressing margins for patterning houses unable to secure EUV-grade mirror blanks from Japanese suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume guarantees across five-year master agreements. Price differentiation stems from SEMI P37 certification tier and multilayer deposition complexity, with high-NA EUV variants commanding substantial premiums over 193nm immersion alternatives. Cost compression in DUV-legacy tiers is intensifying because foundries are consolidating process platforms below 7nm, leaving merchant mask houses competing for residual trailing-edge demand. Research institutions exhibit the highest price sensitivity due to flexible specification tolerances and extended lead-time acceptance, while TSMC and Samsung demonstrate the lowest sensitivity given single-source vendor dependencies per technology node.
Supply Chain Analysis
Port congestion on transpacific routes from Yokohama to Kaohsiung elevates inbound logistics costs for synthetic fused silica substrates and Mo/Si deposition equipment. Supply concentrates in Japan, Taiwan, and Germany, with HOYA Corporation and Toppan Photomasks controlling critical mirror-blank output that feeds patterning houses in Hsinchu and Pyeongtaek. Raw material dependencies center on high-purity quartz from Shin-Etsu Chemical, chrome sputtering targets, and pellicle membrane polymers. Single-source vulnerability pervades EUV substrate procurement, as fewer than fifty technicians worldwide possess production-grade Mo/Si sputtering calibration experience. Distribution runs through captive foundry channels for leading-edge logic, with merchant vendors serving residual research and display demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mask lifecycle services—including defect inspection, pellicle replacement, and regeneration cycles—are expanding faster than hardware procurement as foundries extend asset utilization across node transitions. This service-attach dynamic reorients vendor economics toward recurring revenue streams.
For Market Incumbents: Secure long-term Mo/Si sputtering capacity reservations and cross-border replication agreements under Japan's METI directives to defend against emerging substrate specialists in South Korea. Deepen backward integration into synthetic fused silica purification to reduce exposure to Shin-Etsu Chemical rationing during capacity crunches. Prioritize certification investment for high-NA EUV blanks before 0.55 numerical aperture production ramps concentrate vendor selection. For New Entrants and Emerging Players: Rapid mask prototyping for silicon photonics interposers represents an underserved service layer where incumbent patterning houses prioritize leading-edge logic throughput. Target India's PLI scheme incentives for domestic fab construction, establishing local patterning service centers before captive mask libraries mature at Wuxi and Hefei. Pursue joint development partnerships with AR headset OEMs qualifying DUV masks for OLED micro-patterning. For Investors and Strategic Acquirers: Long-term, this sits as a chokepoint-control play because EUV substrate qualification binds foundries to single vendors per technology node, creating durable moats around mirror-blank specialists. Acquisition candidates should demonstrate atomic force microscopy infrastructure for sub-50 picometer flatness verification and existing SEMI P37 certification partnerships. Watch for actinic inspection tool availability as the inflection signal—scarcity here extends mask qualification cycles and inflates work-in-process inventory, favoring vertically integrated blank-to-pattern players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mirror-Blank Production | Captive Mo/Si deposition capacity insulates patterning houses from HOYA Corporation supply rationing during foundry expansion cycles. |
| High-NA EUV Certification Investment | Early qualification for 0.55 numerical aperture masks binds TSMC and Intel into exclusive vendor relationships per technology node. |
| India Patterning Service Center Establishment | PLI scheme incentives for domestic fab construction create first-mover advantage before captive mask libraries mature at local foundries. |
| Silicon Photonics Prototyping Partnership | AI accelerator packaging demand spills DUV mask volumes into merchant channels previously reserved for leading-edge logic procurement. |
| Pellicle Stress-Engineering Capability Buildout | Anamorphic optics convergence opens specialist niches for membrane architecture differentiation in next-generation EUV exposure systems. |
Research Methodology
Initial hypotheses were tested against primary input from mask patterning executives, foundry procurement directors, actinic inspection tool engineers, and multilayer deposition technicians and refined through secondary validation against SEMI P37 substrate specifications, METI supply chain security directives, EPA hazardous substance filings, and customs trade data for synthetic fused silica imports. Bottom-up triangulation across equipment utilization rates and top-down validation through foundry capex disclosures anchored volume estimates.
Variance decomposition across technology node transitions, wavelength-specific adoption curves, and geographic foundry expansion patterns structured the analytical framework. Segmentation dimensions modeled include mask type, end-user concentration, lithography wavelength, and application complexity tier. CAGRs were derived from node ramp schedules and equipment lead-time observations across the projection horizon. Forecast inputs incorporated actinic inspection tool availability constraints and technician pool limitations for Mo/Si sputtering calibration.
Forecasts assume regulatory continuity in EPA hazardous substance rules, ECHA REACH restrictions, and Japan's METI semiconductor supply chain directives; material policy shifts would require re-modeling chrome etching chemistry transitions and cross-border replication agreement enforceability. Practitioners should keep alternative scenarios live as high-NA EUV qualification timelines and India PLI scheme disbursement rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market