
 Global Tamping Machine Market | 2026-2036
Global Tamping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tamping Machine Market Analysis
The EU Green Deal's modal shift targets is realigning procurement priorities across European rail networks toward lower-emission maintenance equipment. Plasser & Theurer leverages its Austrian engineering heritage to dominate high-speed tamping system supply across Central Europe. Harsco Rail anchors North American aftermarket service capacity through its extensive rebuild and lease fleet network. CRCC competes aggressively on project bundling, integrating tamping services within turnkey rail construction contracts across Belt and Road corridors.
A tamping machine is a specialized rail maintenance vehicle that restores track geometry by compacting ballast beneath sleepers using synchronized vibrating tines, typically operating at frequencies between 35-50 Hz and pressures exceeding 200 bar to achieve specified longitudinal level and alignment tolerances. Automatic tamping machines lead value generation due to their GPS-guided leveling systems and continuous-action designs that minimize track possession windows. Hydraulic tamping technology occupies the largest installed base, though vibratory tamping is gaining share in urban infrastructure applications where noise restrictions constrain pneumatic alternatives. Railway track maintenance represents the most mature application segment, while railway track construction in emerging economies offers faster growth trajectories.
The European Union Agency for Railways enforces interoperability standards under the EU Rail Safety Directive, mandating specific tamping performance thresholds for cross-border corridor compatibility. China's National Railway Administration implements GB standards for track maintenance machinery that condition market access for imported equipment. India's Ministry of Railways prescribes indigenous content requirements through its PLI scheme for rail component manufacturing. Stakeholders must monitor evolving carbon-border adjustment mechanisms and localization mandates that will reshape supplier qualification criteria and aftermarket parts sourcing strategies.
Market Dynamics
Railway infrastructure managers face escalating pressure to reduce track possession windows while EU Green Deal modal shift mandates intensify fleet utilization rates across European networks.
Growth Catalysts
- EU Rail Safety Directive interoperability mandates:Cross-border corridor compatibility requirements compel network operators to upgrade tamping capabilities for standardized track geometry thresholds.
- China's dual carbon goals:Freight modal shift targets accelerate rail construction and maintenance machinery deployment across Belt and Road corridors.
- Urban noise restriction frameworks:Vibratory tamping technology gains preference in metropolitan rail systems where pneumatic alternatives face decibel limitations.
Market Restraints
- High-grade hydraulic component concentration:Precision servo valves and high-pressure pumps concentrate among German and Austrian suppliers, exposing procurement to single-source risk.
- Specialized technician scarcity:GPS-guided leveling system calibration requires certified operators whose training pipelines lag fleet expansion timelines.
- Ballast quality volatility:Regional quarry output variations force tamping parameter recalibration, extending machine setup cycles.
Strategic Opportunities
- India's PLI scheme for rail component manufacturing:Indigenous content requirements create localized assembly partnerships for foreign tamping system providers.
- Predictive maintenance convergence:Integration of vibration sensors with cloud analytics platforms enables condition-based tamping scheduling.
- High-speed rail expansion in Southeast Asia:Indonesia, Vietnam, and Thailand execute network modernization programs requiring precision track geometry restoration.
Industry Challenges
- Legacy fleet integration complexity:Older tamping units lack CAN bus compatibility with modern GPS guidance systems, forcing expensive control system retrofits.
- CE marking timeline compression:EU Machinery Directive conformity assessment durations extend delivery schedules for non-European manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tamping Machine Market |
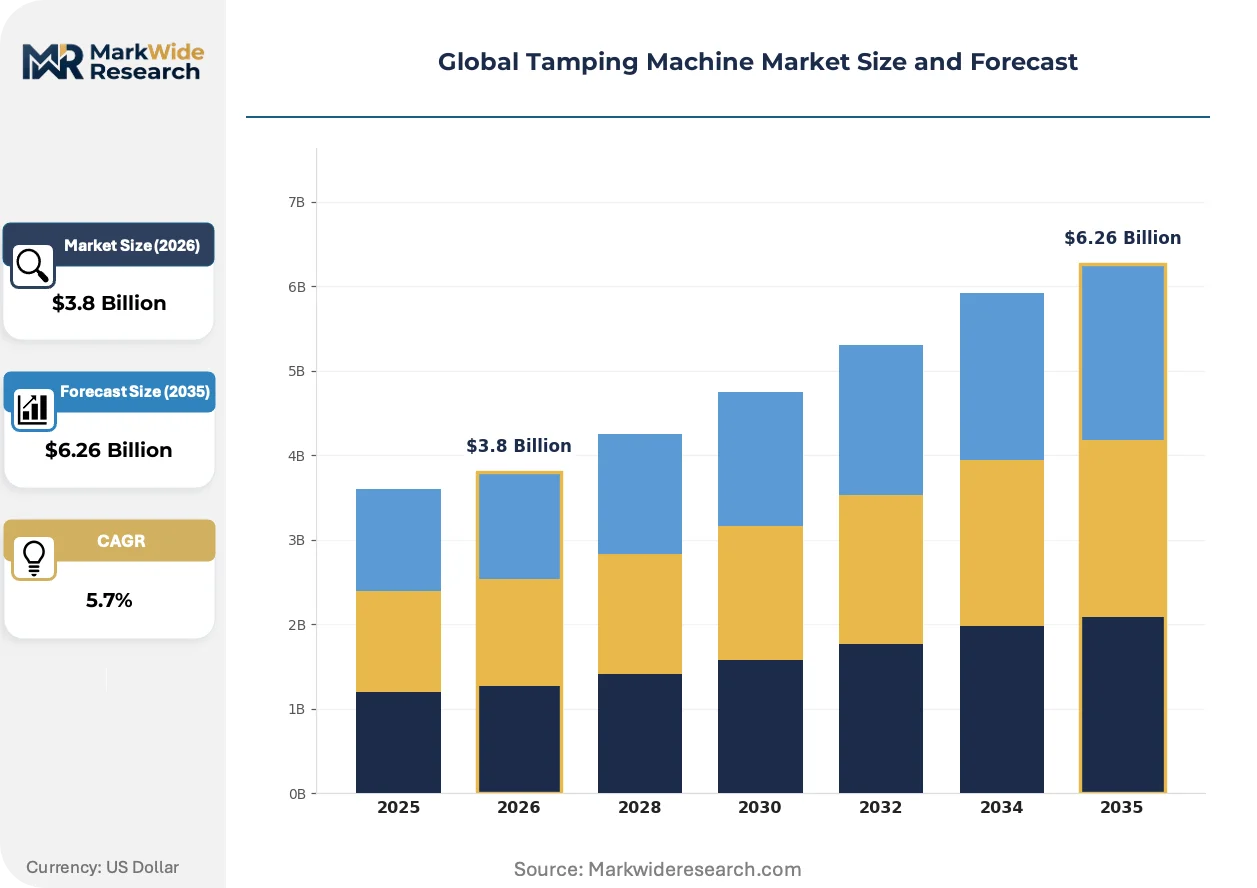
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Tamping Machines, Automatic Tamping Machines, Compact Tamping Machines, High-Speed Tamping Machines End User: Railway Contractors, Construction Firms, Government Agencies, Maintenance Providers Technology: Pneumatic Tamping, Hydraulic Tamping, Mechanical Tamping, Vibratory Tamping Application: Railway Track Construction, Railway Track Maintenance, Road Construction, Urban Infrastructure |
| Companies Covered | Plasser & Theurer, Harsco Rail, CRCC, MATISA, Robel, Gemac Engineering Machinery, Remputmash Group, Ammann Group, Wacker Neuson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tamping Machine Market Emerging Trajectories
Tamping system architecture is fragmenting into configurable subsystems as infrastructure managers demand site-specific performance without full platform replacement.
Electro-hydraulic tamping drive technology is modularizing across European maintenance fleets. Deutsche Bahn and SNCF deploy plug-and-play actuator packages that permit field replacement of individual tamping units rather than complete machine overhaul. This architecture compresses capital deployment cycles by allowing incremental capability upgrades aligned with track possession availability.
REACH chemical substance restrictions are reshaping hydraulic fluid specifications across EU rail networks. Biodegradable ester-based formulations displace mineral oil in tamping system circuits, compelling seal material redesigns and recalibrated pressure tolerances. German KBA type-approval processes now incorporate fluid compatibility testing, extending certification timelines for imported equipment.
Maintenance contracting is consolidating toward integrated track geometry management. British and French infrastructure managers bundle tamping, lining, and surveying services under multi-year performance agreements. This model displaces spot-hire machine availability, favoring fleet operators with captive technical labor and predictive analytics capabilities.
Global Tamping Machine Market Segmentation
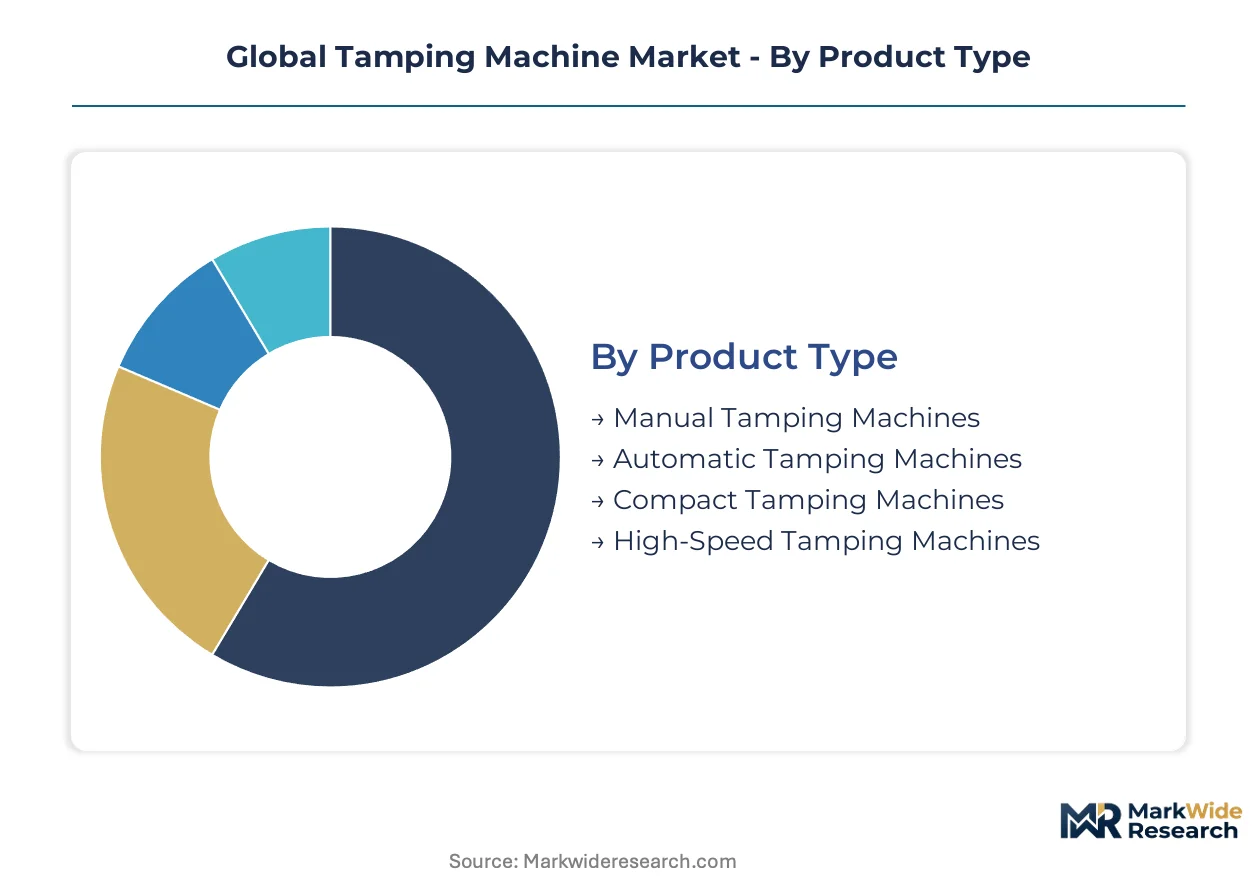
Tamping machine procurement diverges sharply across operational contexts, with track geometry tolerances, possession window constraints, and fleet integration requirements dictating technology selection. Infrastructure managers segment purchases by automation level, end-user contracting structure, and drive mechanism to align capital deployment with specific corridor maintenance strategies.
Product Type:
Supply concentration tilts toward automatic platforms as European and Asian infrastructure managers prioritize GPS-guided systems that compress track possession windows.
- Automatic Tamping Machines:GPS-guided leveling systems synchronize vibrating tine arrays with continuous-action chassis designs, achieving longitudinal level tolerances below 2mm. Deutsche Bahn and SNCF procurement specifications mandate these platforms for high-speed corridor maintenance, driven by EU Rail Safety Directive interoperability thresholds for cross-border routes.
- High-Speed Tamping Machines:Specialized units operate at track speeds exceeding 200 km/h maintenance windows, integrating dynamic track stabilization and laser alignment subsystems. China's National Railway Administration deploys these across Beijing-Shanghai and Beijing-Guangzhou corridors where freight modal shift targets intensify line utilization.
- Manual Tamping Machines:Portable units serve secondary line remediation and emergency response where mechanized access proves impractical.
- Compact Tamping Machines:Narrow-gauge configurations access urban tram networks and industrial sidings with restricted loading gauges.
Today's leader: Automatic Tamping Machines. Tomorrow's challenger: High-Speed Tamping Machines.
End User:
Contracting consolidation is reshaping customer concentration as performance-based agreements displace spot-hire machine availability.
- Maintenance Providers:Integrated track geometry management contracts bundle tamping, lining, and surveying services under multi-year agreements with British and French infrastructure managers. Harsco Rail anchors North American aftermarket capacity through captive technical labor and predictive analytics platforms.
- Railway Contractors:CRCC and European construction consortia procure tamping fleets for turnkey rail construction contracts across Belt and Road corridors and EU cohesion fund projects. Project bundling requirements favor suppliers offering embedded maintenance training and spare parts localization.
- Government Agencies:India's Ministry of Railways prescribes indigenous content thresholds through PLI scheme mandates for rail component manufacturing.
- Construction Firms:General infrastructure developers acquire compact units for greenfield rail alignment projects in Southeast Asian markets.
Procurement gravity centers on Maintenance Providers. Volume expansion concentrates with Railway Contractors.
Technology:
Drive mechanism selection hinges on hydraulic component availability and urban noise restriction frameworks that constrain pneumatic alternatives.
- Hydraulic Tamping:Precision servo valve arrays deliver tine pressures exceeding 200 bar with frequency modulation between 35-50 Hz. German and Austrian suppliers dominate high-grade hydraulic component manufacturing, exposing procurement to single-source risk for pressure pumps and control manifolds.
- Vibratory Tamping:Electromechanical oscillation systems reduce acoustic emissions below 75 dB, satisfying metropolitan rail system decibel limitations in Paris, London, and Tokyo urban networks. REACH chemical restrictions accelerate biodegradable ester-based hydraulic fluid adoption, compelling seal material redesigns.
- Pneumatic Tamping:Compressed air systems retain installed base share in quarry-adjacent operations where ballast quality volatility demands rapid parameter recalibration.
- Mechanical Tamping:Cam-driven tine actuation persists in legacy fleet refurbishment programs where CAN bus compatibility constraints limit control system upgrades.
Installed base dominance: Hydraulic Tamping. Regulatory tailwind beneficiary: Vibratory Tamping.
Application:
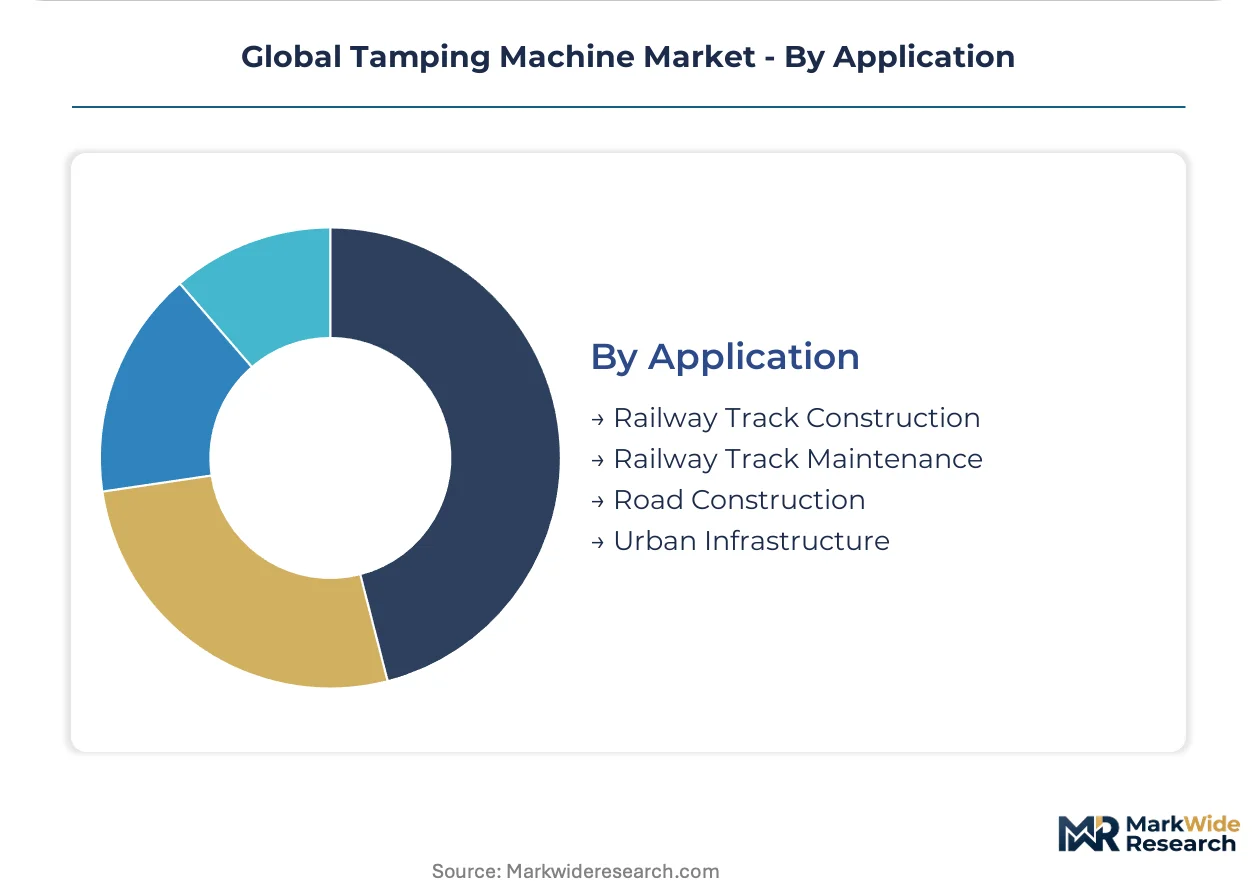
Revenue maturity separates track maintenance from construction applications, with emerging economy network buildouts offering steeper expansion trajectories.
- Railway Track Maintenance:Mature demand concentrates in Germany, China, and India as these countries execute large-scale network modernization programs. Automatic tamping platforms with predictive maintenance sensor integration command premium positioning within EU Green Deal modal shift procurement frameworks.
- Railway Track Construction:Indonesia, Vietnam, and Thailand high-speed rail expansions require precision track geometry restoration during greenfield alignment. Turnkey construction contracts integrate tamping services within civil works packages, favoring project bundling capabilities.
- Urban Infrastructure:Metro system extensions in São Paulo, Cairo, and Jakarta deploy compact vibratory units for tunnel and elevated guideway maintenance.
- Road Construction:Specialized tamping attachments serve ballasted roadbed preparation for heavy-haul mining corridors and port intermodal facilities.
Revenue anchor: Railway Track Maintenance. Climbing the fastest: Railway Track Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central European engineering traditions established the tamping machine industry during post-war railway reconstruction, with Austrian and German manufacturers scaling hydraulic precision systems for cross-border corridor maintenance. This heritage continues shaping procurement patterns across high-speed networks.
Germany
Deutsche Bahn's high-speed corridor maintenance drives automatic tamping platform demand with GPS-guided leveling specifications. KBA type-approval processes incorporate biodegradable hydraulic fluid compatibility testing, extending certification timelines for imported equipment. Bavaria's Munich-Augsburg industrial corridor hosts precision servo valve manufacturing clusters serving tamping system integrators.
China
Beijing-Shanghai and Beijing-Guangzhou high-speed freight corridors intensify line utilization under dual carbon modal shift targets. National Railway Administration GB standards condition market access for track maintenance machinery imports. Sichuan-Chongqing manufacturing bases produce integrated tamping units for Belt and Road construction contracts.
India
Ministry of Railways network modernization programs concentrate automatic tamping procurement for dedicated freight corridors. PLI scheme indigenous content requirements mandate localized assembly partnerships for foreign system providers. Maharashtra's Mumbai-Pune industrial belt hosts emerging rail component manufacturing clusters.
United States
Class I railroad precision scheduled railroading initiatives compress track possession windows, favoring continuous-action tamping systems. FRA track geometry standards enforce interoperability thresholds for cross-border Canadian and Mexican corridor compatibility. Chicago's rail equipment rebuild centers anchor North American aftermarket service capacity.
France
SNCF performance-based maintenance contracts bundle tamping with track geometry management under multi-year agreements. EU Rail Safety Directive interoperability mandates standardize cross-border corridor equipment specifications. Île-de-France's Paris metropolitan rail network deploys vibratory tamping units for urban noise restriction compliance.
Global Tamping Machine Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the tamping machine sector, with integrated manufacturers maintaining captive hydraulic component foundries while specialized assemblers source precision subsystems from Austrian and German suppliers. Market structure tilts toward consolidation among European heritage brands with decades of rail maintenance equipment lineage. Three archetypes dominate: vertically integrated platform builders with in-house hydraulic production, regional system integrators leveraging localized assembly partnerships, and aftermarket service specialists operating rebuild and lease fleet networks. Competitive positioning hinges on M&A-driven geographic expansion and strategic partnerships for indigenous content compliance in protected procurement markets.
Among European heritage manufacturers, Plasser & Theurer exemplifies the vertically integrated archetype with Austrian engineering lineage, while Harsco Rail occupies the aftermarket service tier through North American rebuild network positioning. CRCC represents the project-bundling model integrating tamping services within turnkey construction contracts. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without requiring uniform capability portfolios across hydraulic, vibratory, and pneumatic technology lines.
| Leading Market Players |
|---|
| Plasser & Theurer |
| Harsco Rail |
| CRCC |
| MATISA |
| Robel |
| Gemac Engineering Machinery |
| Remputmash Group |
| Ammann Group |
| Wacker Neuson |
| Others |
Supply Flow & Price Mechanics
Family-owned Austrian and German engineering specialists anchor precision hydraulic component manufacturing, translating captive production control into pricing discipline that resists commoditization pressure from Asian system integrators. Their ownership structure insulates long-term R&D cycles from quarterly margin compression, reinforcing premium positioning across EU Rail Safety Directive-mandated interoperability tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates GPS-guided automatic platforms from basic hydraulic units and refurbished legacy fleets. Price differentiation rests on CE marking certification grade and after-sales service bundling rather than raw performance specifications. Cost compression in the economy tier is intensifying because Indian PLI scheme localization mandates force foreign suppliers to absorb assembly partnership overhead. Railway contractors exhibit highest price sensitivity due to turnkey contract margin constraints, while Deutsche Bahn and SNCF maintenance divisions prioritize possession-window efficiency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for precision servo valves and high-pressure pumps are hardening as infrastructure managers mitigate single-source exposure to Bavarian and Upper Austrian component foundries. Geographic supply concentration draws from Germany, Austria, and China, with Sichuan-Chongqing manufacturing bases feeding Belt and Road construction demand. Raw material dependencies center on specialty steel forgings, biodegradable ester-based hydraulic fluids, and GPS guidance system chipsets. Tariff exposure on Chinese-assembled units threatens cost structures for European system integrators. Distribution runs through captive technical service networks rather than third-party equipment dealers, locking in aftermarket revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European heritage premium pricing and Asian project-bundling volume scale, with India's PLI localization requirements creating a middle-cost manufacturing corridor that captures regulatory preference without full Austrian production overhead.
For Market Incumbents: Cement hydraulic component foundry capacity in Bavaria and Upper Austria against Chinese system integrators acquiring precision manufacturing capabilities through Sichuan-Chongqing joint ventures. Deepen backward integration into biodegradable hydraulic fluid formulation to preempt REACH chemical restriction compliance costs that threaten seal material redesign cycles. Prioritize CAN bus compatibility retrofit programs for legacy fleet integration complexity that blocks aftermarket service penetration. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Southeast Asian high-speed rail construction contracts offers white-space entry below Plasser & Theurer positioning but above CRCC project-bundling commoditization. Target Indonesia, Vietnam, and Thailand network modernization programs where precision track geometry requirements outstrip local maintenance provider technical capacity. Pursue embedded maintenance training partnerships as the primary go-to-market angle, converting equipment sales into multi-year performance agreements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with localized assembly partnerships but without captive hydraulic component production. Long-term viability over a five-to-ten year horizon hinges on indigenous content compliance capabilities across EU, Indian, and Chinese procurement frameworks. Monitor CE marking timeline compression for non-European manufacturers as the inflection signal—extended conformity assessment durations that advantage heritage brands with established KBA type-approval relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Hydraulic Fluid Transition | REACH chemical restrictions force seal material redesigns and recalibrated pressure tolerances across EU networks. |
| Localized Assembly Partnership Formation | India's PLI scheme indigenous content requirements mandate foreign system providers establish Maharashtra-based manufacturing clusters. |
| Predictive Maintenance Platform Integration | Vibration sensor convergence with cloud analytics enables condition-based tamping scheduling for Deutsche Bahn performance contracts. |
| High-Speed Corridor Certification Investment | EU Rail Safety Directive interoperability mandates standardize cross-border equipment specifications for Beijing-Shanghai corridor suppliers. |
| Aftermarket Service Network Expansion | Harsco Rail's Chicago rebuild centers demonstrate captive technical labor anchoring North American spot-hire displacement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with railway infrastructure managers, maintenance provider fleet directors, OEM procurement teams, and aftermarket service heads with secondary validation against EU Agency for Railways interoperability filings, National Railway Administration GB standards documentation, and Indian Ministry of Railways PLI scheme notifications. Bottom-up tamping machine deployment tallies by corridor and top-down rail maintenance expenditure estimates triangulated market sizing across the projection horizon.
Segment-weighting approaches distributed value generation across automatic, high-speed, manual, and compact product types, with end-user contracting structure and drive mechanism technology layered as secondary dimensions. CAGRs were derived from corridor-specific fleet expansion timelines and modal shift target intensities. Forecast inputs incorporated EU Green Deal implementation velocity and China's dual carbon freight shift enforcement patterns.
The model assumes a particular technology adoption path; alternative pathways for electro-hydraulic modular tamping drive architectures would alter the outlook if Deutsche Bahn and SNCF accelerate plug-and-play actuator deployment beyond current field replacement cycles. Deviation in CE marking timeline compression for non-European manufacturers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Europe Chip Mounter Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Global Wafer Cleaning Equipment Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Chip Conveyors Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Semiconductor Laser Equipment Market